
 Potting Compound Market | 2026-2036
Potting Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Potting Compound Market Intelligence
Application-specific formulation services are repositioning the value proposition beyond bulk material sales. Henkel AG & Co. KGaA leverages its extensive portfolio to serve diverse end-markets from automotive to consumer electronics. Huntsman Corporation specializes in high-performance epoxy and polyurethane systems for demanding aerospace applications. Dow Inc. competes on manufacturing scale and global supply chain reach, particularly for silicone-based compounds.
Potting compounds are protective materials, typically liquid resins, used to encase electronic components in a solid, durable mass. These materials cure to provide electrical insulation, shock and vibration resistance, and protection from moisture and corrosive agents. Epoxy and silicone chemistries dominate the product landscape, offering different balances of thermal conductivity and flexibility. The electronics and automotive sectors represent the largest application areas, driven by the need to protect intricate circuitry.
Material formulations are constrained by environmental regulations like the European Union's RoHS and REACH directives, which limit hazardous substances. In the United States, standards from the EPA govern volatile organic compound (VOC) content, influencing solvent-based system development. Future material selection will hinge on balancing performance requirements with an expanding list of global environmental and safety mandates.
Market Dynamics
The central dynamic in the potting compound market is the dual requirement for enhanced thermal management and stringent dielectric insulation. This pressure stems directly from component densification in electric vehicle power electronics and the miniaturization of consumer mobile devices.
Growth Catalysts
- Regulatory Compliance Frameworks:Directives like the EU's RoHS, which restricts hazardous substances in electronics, compel manufacturers to use compliant potting compounds, ensuring component protection and market access for finished goods.
- Automotive Electrification:The expansion of electric vehicle production creates substantial demand for thermally conductive silicones and epoxies to encapsulate and protect battery management systems and on-board chargers from heat and vibration.
- Manufacturing Ecosystem Concentration:The dense clustering of electronics manufacturing services in specific zones within China and South Korea creates concentrated demand hubs, simplifying logistics and fostering close collaboration between material suppliers and end-users.
Market Restraints
- Raw Material Price Volatility:The costs of key precursors, such as epoxy resins and silicone polymers, are closely tied to fluctuating petrochemical and siloxane feedstock prices, creating margin pressure for formulators.
- Stringent Regulatory Hurdles:Compliance with chemical safety regulations like the EU's REACH framework involves extensive testing and registration costs, which can slow the commercialization of new and innovative formulations.
- Threat from Conformal Coatings:In less demanding applications, lower-cost conformal coatings provide a viable alternative for moisture and dust protection, posing a substitution threat where full, rigid encapsulation is not required.
Strategic Opportunities
- Bio-Based and Recyclable Formulations:Developing potting compounds derived from renewable sources or designed for easier end-of-life recovery presents a significant opportunity to align with corporate sustainability mandates and circular economy principles.
- Renewable Energy Systems:The growing installation of solar and wind energy infrastructure opens a new application frontier for potting compounds to protect inverters, control units, and power electronics from harsh outdoor environmental conditions.
- Emerging Manufacturing Geographies:The expansion of electronics assembly operations into Southeast Asian countries like Vietnam and Malaysia offers new growth markets for potting compound suppliers beyond traditional centers.
Industry Challenges
- Lengthy Qualification Cycles:Gaining approval for use in high-reliability sectors such as aerospace and medical devices requires extensive and costly testing protocols, creating long lead times and significant barriers to entry.
- Application Process Complexity:The need for specialized mixing, dispensing, and curing equipment represents a capital investment hurdle and requires skilled technicians, which can limit adoption by smaller manufacturers.
- Material Compatibility Assurance:Ensuring that a compound’s chemistry does not induce stress, corrosion, or degradation of sensitive microelectronic components over a device's lifespan remains a critical and complex technical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potting Compound Market |
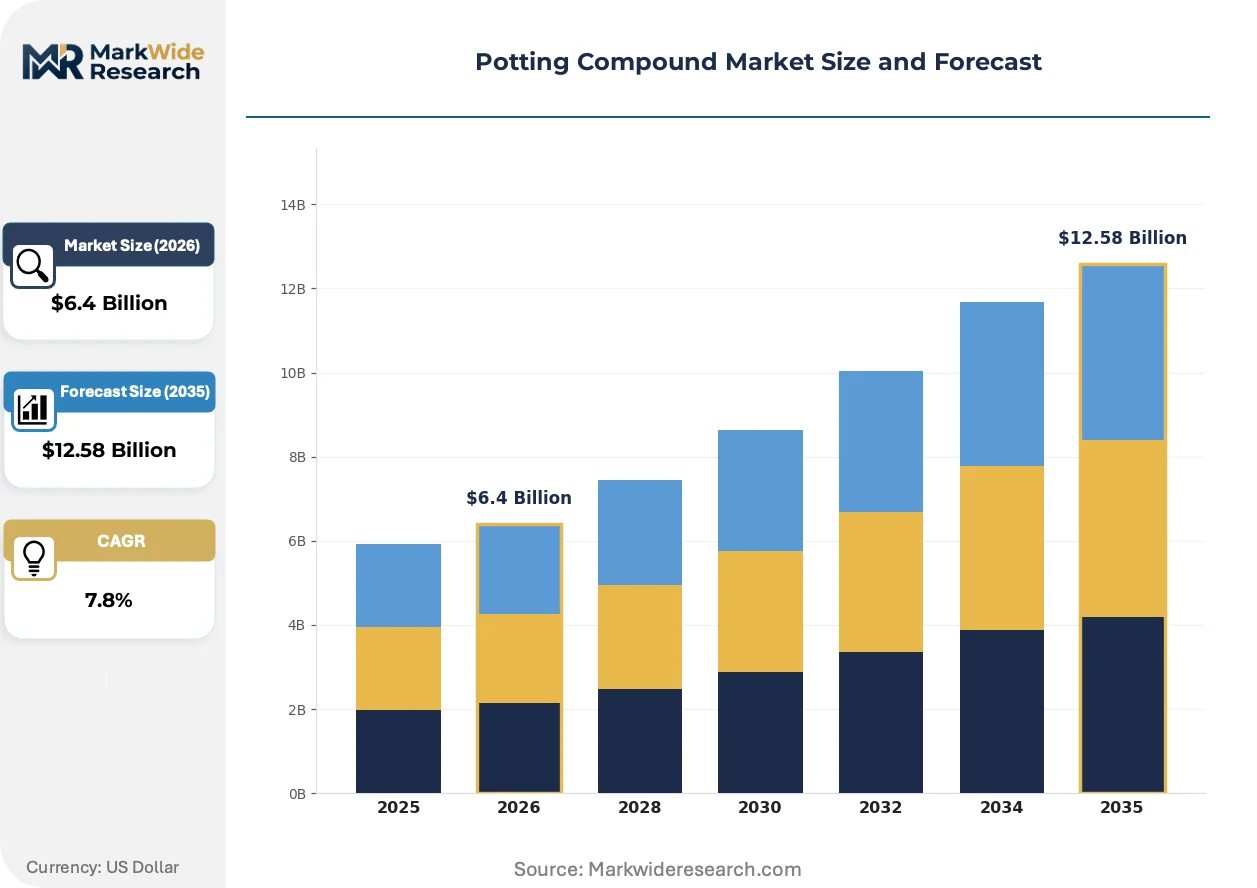
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $12.58 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Silicone, Polyurethane, Polymeric Application: Electronics, Automotive, Aerospace, Medical End User: Manufacturers, OEMs, Repair Shops, Distributors Distribution Channel: Online, Direct Sales, Retail, Wholesalers |
| Companies Covered | Huntsman Corporation, LORD Corporation, Henkel AG & Co. KGaA, ELANTAS Beck GmbH, Master Bond Inc., 3M Company, H.B. Fuller Company, MG Chemicals, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potting Compound Market Strategic Shifts & Innovations
Material innovation is pivoting toward multifunctional compounds that solve multiple engineering problems simultaneously. Formulations are increasingly expected to provide thermal dissipation, electrical insulation, and structural support while adhering to a growing list of global environmental safety standards.
Thermally conductive compounds, primarily based on silicone or epoxy chemistries, are engineered to dissipate heat from high-power-density electronics. The automotive sector is adopting these materials at a rapid pace for applications like EV inverters, DC-DC converters, and battery modules. This focus on heat management is electrifying the entire material science field, pushing R&D toward higher thermal conductivity without compromising dielectric strength.
The US Environmental Protection Agency (EPA) regulations on volatile organic compound (VOC) content are accelerating the market's shift from solvent-based systems to 100% solids formulations. This transition impacts material handling and processing for manufacturers of electronics and industrial controls. These sectors must now adapt production lines to manage the different viscosities and curing profiles inherent to low-VOC epoxy and polyurethane systems.
Buyer behavior is evolving from transactional bulk material orders toward collaborative, application-specific formulation development. Original equipment manufacturers in high-stakes industries are increasingly engaging directly with material scientists to co-develop compounds with tailored properties. This trend is most visible within the aerospace and medical device verticals, where unique performance criteria for each new product demand customized encapsulation solutions.
Potting Compound Market Segmentation
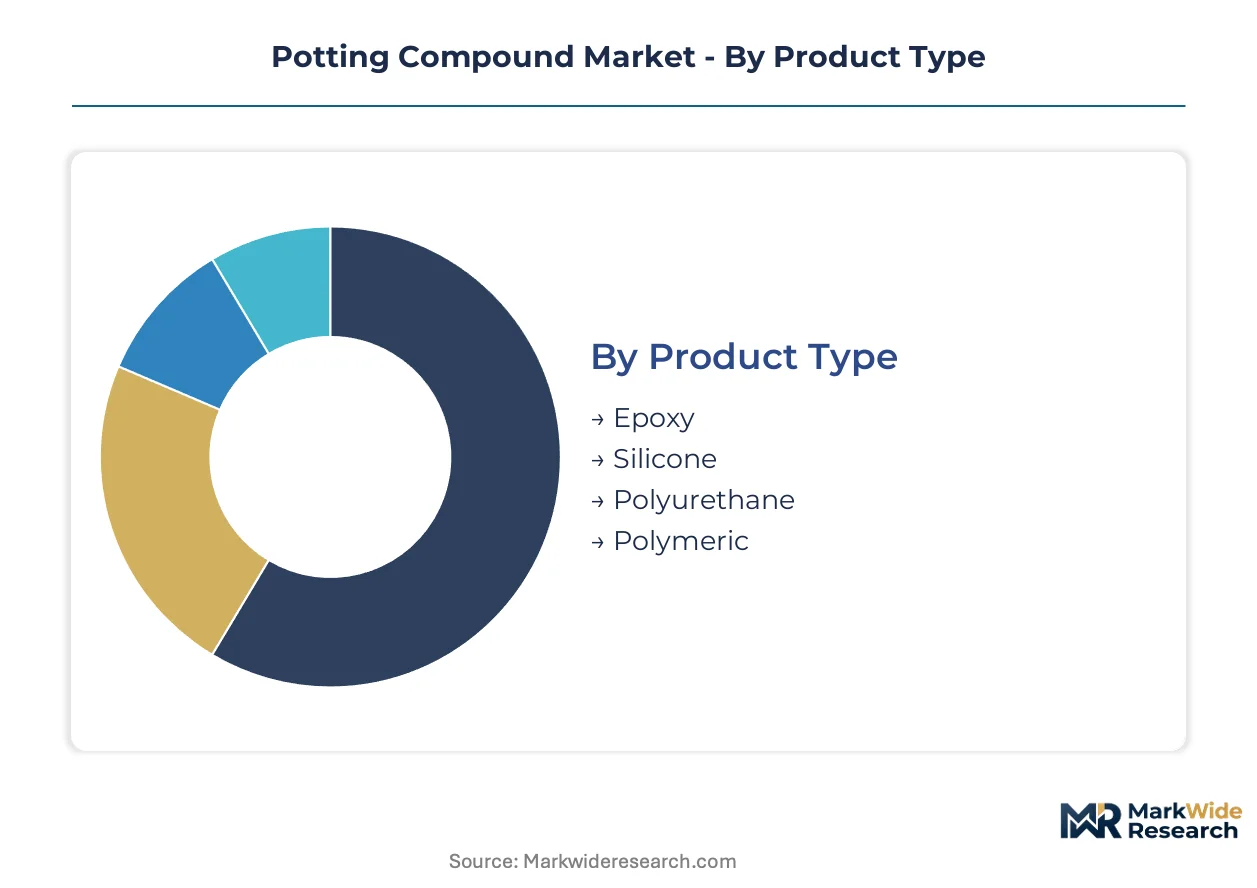
Market segmentation provides a granular understanding of the diverse requirements and purchasing behaviors driving the potting compound industry. Analyzing these distinct segments helps manufacturers tailor product offerings and strategic investments to specific end-use demands.
Product Type:
Manufacturers select potting compound product types based on specific performance requirements for thermal management, flexibility, and dielectric strength.
- Epoxy:These thermosetting polymers provide excellent adhesion, chemical resistance, and high mechanical strength for rugged electronic assemblies. Demand concentrates in industrial controls and automotive applications requiring robust protection against harsh operating conditions.
- Silicone:Known for superior flexibility, thermal stability, and moisture resistance, silicone compounds protect sensitive components from vibration and extreme temperatures. Electric vehicle battery management systems and power electronics are driving significant demand for these materials.
- Polyurethane:These compounds offer good flexibility, abrasion resistance, and strong adhesion, making them suitable for vibration damping and environmental sealing in various electronic enclosures.
- Polymeric:This broad category includes acrylics and other specialized polymers, chosen for specific properties such as UV resistance, rapid curing times, or cost-effectiveness in less demanding applications.
Epoxy leads on scale; Silicone leads on momentum.
Application:
Application-specific demands dictate the precise physical and chemical properties required from potting compounds.
- Electronics:This sector utilizes potting compounds to protect printed circuit boards, sensors, and power supplies from moisture, dust, and electrical short circuits. Consumer electronics and industrial control units represent significant volume for encapsulation materials.
- Automotive:Potting compounds are critical for protecting sensitive electronic control units, sensors, and battery components in electric vehicles from vibration, thermal cycling, and harsh fluids. The electrification trend drives a substantial increase in demand for these protective materials.
- Aerospace:High-performance potting compounds encapsulate critical avionics, navigation systems, and engine control components, ensuring reliability under extreme temperature fluctuations and mechanical stress.
- Medical:Biocompatible and sterilizable potting materials protect implantable devices, diagnostic equipment, and surgical tools from bodily fluids and maintain electrical integrity.
Electronics applications represent the largest volume, while Automotive shows the steepest expansion trajectory.
End User:
Procurement patterns for potting compounds vary significantly across different end-user types within the value chain.
- Manufacturers:These entities directly integrate potting compounds into their production lines for encapsulating electronic components during assembly. Their purchasing decisions prioritize material performance, processing efficiency, and cost-effectiveness for large-scale operations.
- OEMs:Original Equipment Manufacturers specify particular potting compounds for their product designs, often collaborating with material suppliers for custom formulations. They focus on long-term reliability, regulatory compliance, and seamless integration into their proprietary systems.
- Repair Shops:Smaller volumes of potting compounds are purchased by repair and maintenance facilities for component restoration or localized protection of electronic parts.
- Distributors:These intermediaries supply a diverse range of potting compounds to smaller manufacturers, prototyping labs, and repair shops, offering convenience and broader product access.
Manufacturers account for the bulk of direct consumption, with OEMs shaping product specifications.
Distribution Channel:
Supply chain efficiency and customer relationship management define the effectiveness of various distribution channels for potting compounds.
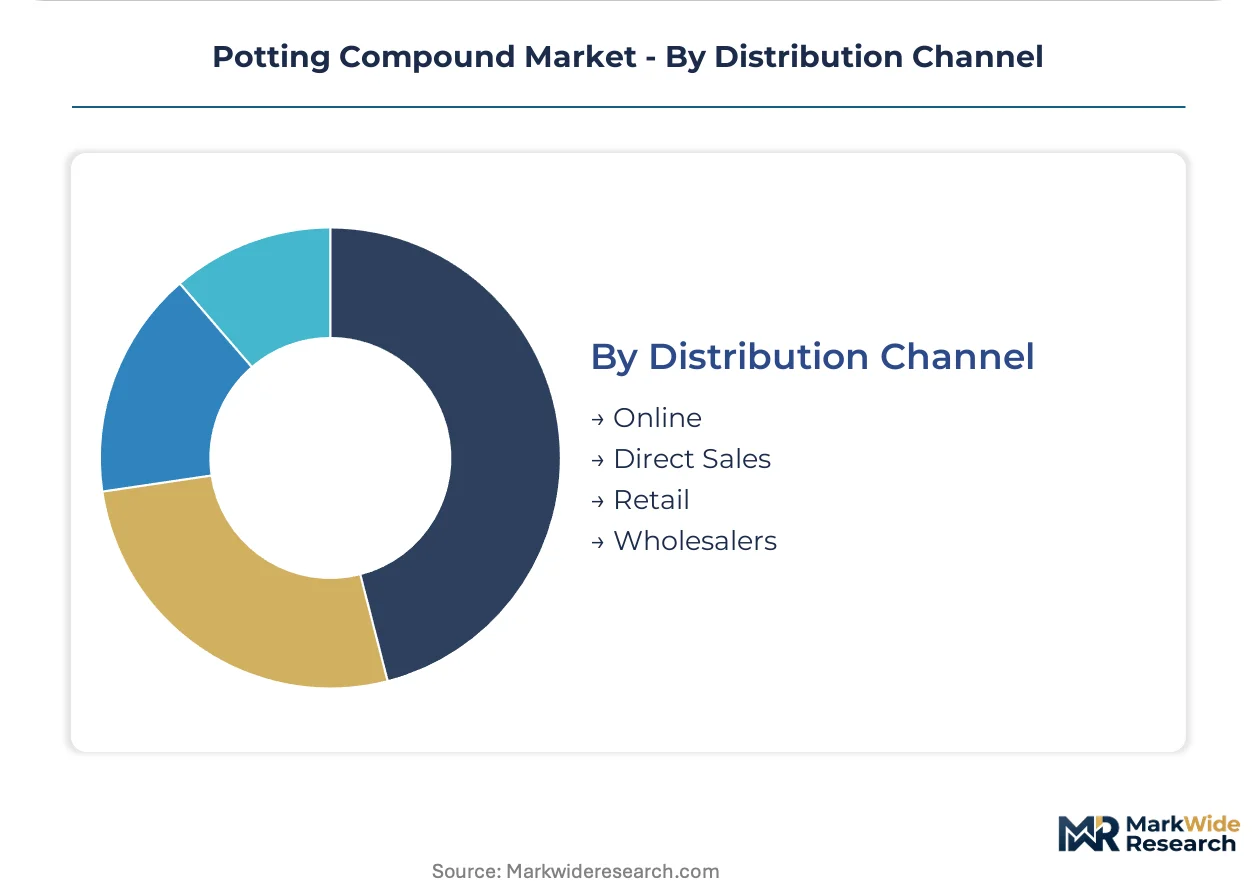
- Online:E-commerce platforms and specialized material marketplaces offer convenient access to a wide range of standard potting compounds for small to medium-sized enterprises and R&D labs. The digital channel streamlines ordering and product discovery for diverse applications.
- Direct Sales:Material suppliers engage directly with large industrial clients and OEMs, providing technical support, custom formulation services, and bulk quantities. This channel facilitates deep technical collaboration and long-term supply agreements.
- Retail:Specialized electronics stores or industrial supply outlets may offer smaller quantities of general-purpose potting compounds to hobbyists, repair technicians, or very small businesses.
- Wholesalers:These entities purchase potting compounds in bulk from manufacturers and then distribute them to a network of smaller distributors, retailers, or directly to end-users, often serving regional markets.
Direct sales channels handle the majority of high-volume transactions, while online platforms are gaining share most quickly for specialized requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage, driven by differing environmental standards and production costs, influences the global distribution of potting compound manufacturing. This dynamic shapes where electronics assembly, and thus demand for protective materials, concentrates. Manufacturers strategically locate production to optimize compliance and supply chain efficiency across various regions.
China
China's electronics manufacturing prowess and burgeoning electric vehicle market drive substantial demand for potting compounds. The country's GB standards for electronic product safety and hazardous substances guide material selection. Key industrial clusters in the Yangtze River Delta continue to expand their capacity for advanced electronics packaging.
German
German automotive sector's electrification initiatives create significant demand for high-performance potting materials, particularly in EV components. The EU's RoHS and REACH directives mandate strict compliance for all electronic components. Bavaria's automotive and industrial electronics cluster actively integrates advanced potting solutions into new designs.
United States
Demand for potting compounds in the United States stems from aerospace, medical device, and defense applications requiring extreme reliability. The EPA's regulations on volatile organic compound (VOC) content influence material formulation trends. Technology hubs like Silicon Valley and the Northeast corridor continue to innovate in microelectronics protection.
Within
Within South Korea, a major hub for consumer electronics, advanced display technologies, and electric vehicle battery systems, potting compound consumption is high. The MFDS oversees materials used in medical devices, while national environmental regulations guide industrial chemical use. The Seoul Capital Area hosts numerous electronics manufacturers requiring specialized encapsulation.
As
As an emerging electronics manufacturing hub, Vietnam attracts foreign investment and expands its demand for potting compounds. The government's investment incentives for high-tech manufacturing encourage local production capabilities. Industrial zones around Ho Chi Minh City and Hanoi are rapidly developing electronics assembly operations.
Potting Compound Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. Large chemical conglomerates and specialized formulators represent two key strategic archetypes. Competitive moves often involve strategic partnerships for application-specific development and targeted acquisitions to expand technology portfolios. Companies also focus on geographic expansion into emerging manufacturing hubs.
Large, diversified chemical conglomerates like Henkel AG & Co. KGaA and Dow Inc. anchor the market, leveraging extensive R&D and global supply chains to offer a wide array of potting solutions. These entities exemplify broad portfolio strategies, serving diverse end-markets from automotive to consumer electronics with advanced material science. Huntsman Corporation occupies a position as a specialized formulator, focusing on high-performance epoxy and polyurethane systems for demanding applications such as aerospace, representing a more niche-oriented approach. This strategic differentiation allows various players to capture value across the market's varied technical requirements.
| Leading Market Players |
|---|
| Huntsman Corporation |
| LORD Corporation |
| Henkel AG & Co. KGaA |
| ELANTAS Beck GmbH |
| Master Bond Inc. |
| 3M Company |
| H.B. Fuller Company |
| MG Chemicals |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
The European Union's REACH framework gates qualified supply and premium-tier pricing access for potting compounds, especially for formulations entering sensitive applications. This regulatory scrutiny ensures material safety, but also adds significant cost and complexity for suppliers.
Pricing Analysis
Capacity additions in Southeast Asian countries are reshaping price floors for standard-grade potting compounds. The dominant pricing model is contract-based long-term offtake for large manufacturers and OEMs. Price differentiation stems from certification levels, such as RoHS compliance, and the degree of custom formulation required. Pricing pressure stems from raw material price volatility, particularly for epoxy resins. Repair shops and smaller manufacturers exhibit higher price sensitivity compared to aerospace or medical device OEMs.
Supply Chain Analysis
Single-source vulnerability sits with specialized chemical suppliers for certain high-performance additives. Geographic supply concentration centers on China, South Korea, and Germany for base chemical production. Raw material dependencies include epoxy resins, silicone polymers, and petrochemical feedstocks. Regulatory restrictions, such as the EU's REACH framework, pose a structural supply chain risk by limiting material options. Distribution runs primarily through direct sales channels to large industrial clients and OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story, driven by a demand-shift toward premium specifications for electric vehicle electronics. Manufacturers are prioritizing enhanced thermal management and dielectric insulation.
For Market Incumbents: Anticipate continued margin pressure from lower-cost conformal coatings in less demanding applications. Defend core market share by investing in R&D for bio-based and recyclable formulations, aligning with corporate sustainability mandates. Deepen vertical integration into key raw material production to mitigate supply chain volatility. Focus on expanding application-specific formulation services for high-value end-markets like aerospace and medical devices.
For New Entrants and Emerging Players: Launch via online distribution platforms targeting smaller manufacturers and R&D labs requiring specialized compounds. The most penetrable segment is the emerging electronics assembly market in Southeast Asia, particularly Vietnam. Offer customized, low-volume solutions with rapid prototyping capabilities as a go-to-market angle. Emphasize compliance with local environmental regulations to gain market entry.
For Investors and Strategic Acquirers: Roll-up economics work for specialized formulators because of the fragmented nature of application-specific demand. Long-term viability rests on material innovation in thermal management and environmental compliance. Identify acquisition targets with strong intellectual property in bio-based chemistries or advanced silicone formulations. A signal to watch is increased M&A activity among companies specializing in renewable energy system protection.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Achieving carbon neutrality in production processes attracts sustainability-focused OEMs. |
| Long-term Supply Agreement | Securing stable access to critical raw materials mitigates price volatility for formulators. |
| Joint Venture for R&D | Accelerating development of multifunctional compounds addresses complex engineering challenges. |
| Geographic Expansion into Southeast Asia | Capturing demand from new electronics manufacturing hubs diversifies revenue streams. |
| Certification Investment (RoHS/REACH) | Ensuring regulatory compliance unlocks market access for finished electronic goods. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. The analysis combines in-depth primary interviews with industry stakeholders, including R&D directors, procurement leads at OEMs, plant managers, and regulatory compliance officers. Secondary validation draws from customs/trade data, corporate financial filings, environmental agency reports, and industry association publications. A robust bottom-up and top-down triangulation approach ensures data accuracy.
The forecast framework modeled market dimensions at a granular level, including product type, application, end-user, distribution channel, and specific chemistry types. Compound annual growth rates were derived from historical data analysis and projected demand drivers across the analysis window. Key industry-specific forecast inputs included electric vehicle production forecasts and electronics miniaturization trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme raw material price shocks or new environmental regulations. All forecasts reflect assumptions regarding technological advancements and market adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Lithium Compound Market
Specialty Compounds
Thionyl Chloride Market
Specialty Compounds
Polyurea Market
Specialty Compounds
Filler Masterbatch Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Lauramidopropyl Betaine Market
Specialty Compounds
Chromatography Silica Resins Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
India Sealants Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
High Performance Foam Market