
 Mexico Masterbatch Market | 2026-2036
Mexico Masterbatch Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Masterbatch Market Insights
Asset-light toll manufacturing and third-party compounding arrangements is fragmenting competitive dynamics among domestic masterbatch suppliers. Ampacet Corporation leverages its regional distribution infrastructure to serve multinational packaging converters operating near Mexico City. Avient Corporation sustains technical service capabilities that anchor relationships with Tier 1 automotive suppliers in Monterrey. Cabot Corporation specializes in carbon black-based formulations that dominate premium pricing tiers for exterior automotive applications requiring UV stability.
Masterbatch denotes concentrated mixtures of pigments, additives, or performance enhancers dispersed in a polymer carrier resin, typically containing 15-80% active loading by weight, designed for let-down ratios of 1-5% during final plastic processing. These formulations enable precise color consistency, flame retardancy, or UV protection across injection molding, extrusion, and blow molding operations. Black Masterbatch commands the largest volume share due to pervasive use in automotive underhood components and agricultural film, while Additive Masterbatch represents the fastest-expanding margin pool as processors seek multifunctional packages combining antioxidants with processing aids. Packaging applications absorb the greatest absolute tonnage, though Automotive Components generate superior per-kilogram value through specification-grade color matching and regulatory documentation requirements.
NOM-057-ECOL and PROFEPA enforcement protocols govern volatile organic compound emissions and heavy metal content in plastic colorants sold within Mexican territory, compelling reformulation of legacy lead-chromate pigment systems. BIS-equivalent conformity assessment procedures for imported masterbatches create documentation burdens that favor suppliers with established local testing partnerships. Stakeholders must monitor pending updates to Mexico's extended producer responsibility framework for plastic packaging, as these regulations will recolorant specification requirements and reshape supplier qualification criteria for brand-owner contracts.
Market Dynamics
Automotive component suppliers are consolidating masterbatch procurement around specification-grade black formulations for exterior UV-stable applications, compressing supplier qualification timelines and favoring compounders with captive carbon black sourcing.
Growth Catalysts
- Bajío Automotive Cluster Expansion:Tier 1 suppliers in Querétaro and Guanajuato are expanding injection molding capacity for bumper fascias and interior trim, pulling concentrated volumes of color-matched masterbatches with documented heavy metal compliance.
- NOM-057-ECOL Stringency:PROFEPA enforcement of volatile organic compound limits is phasing out solvent-based colorant systems, redirecting demand toward pelletized masterbatches with verified emission profiles.
- Agricultural Film Modernization:Sinaloa and Sonora growers are adopting UV-stabilized mulch films with carbon black loadings above 25%, creating dedicated demand for agricultural-grade black masterbatch formulations.
Market Restraints
- Carbon Black Import Concentration:Domestic masterbatch compounders depend on US Gulf Coast carbon black supply, exposing margin compression when freight rates spike or customs delays accumulate at Laredo crossings.
- Pigment Substitution Costs:Reformulation away from lead chromate and cadmium sulfide pigments for NOM compliance requires expensive organic alternatives that degrade processing windows in polypropylene carriers.
- Testing Infrastructure Gaps:BIS-equivalent conformity assessment for imported masterbatches lacks sufficient accredited laboratories in central Mexico, extending qualification cycles for new suppliers.
Strategic Opportunities
- Extended Producer Responsibility Preparedness:Pending updates to Mexico's packaging waste framework will mandate recycled content verification, creating first-mover advantage for masterbatch suppliers with traceable post-industrial feedstock partnerships.
- Appliance Manufacturing Densification:Monterrey's expanding washing machine and refrigerator production clusters represent underpenetrated demand for metallic-effect color masterbatches with fingerprint-resistant additive packages.
- Toll Manufacturing Partnerships:Asset-light processors in Toluca and Puebla seek third-party compounding arrangements for specialty additive combinations, opening service revenue streams beyond commodity black formulations.
Industry Challenges
- Color Matching Talent Scarcity:Specification-grade automotive approvals require spectrophotometric expertise that concentrates among aging technicians in Mexico City, constraining expansion of technical service teams in secondary manufacturing corridors.
- Multi-Site Certification Burden:Tier 1 automotive contracts require simultaneous IATF 16949 qualification across toll manufacturing partners, extending commercialization timelines for regional compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Masterbatch Market |
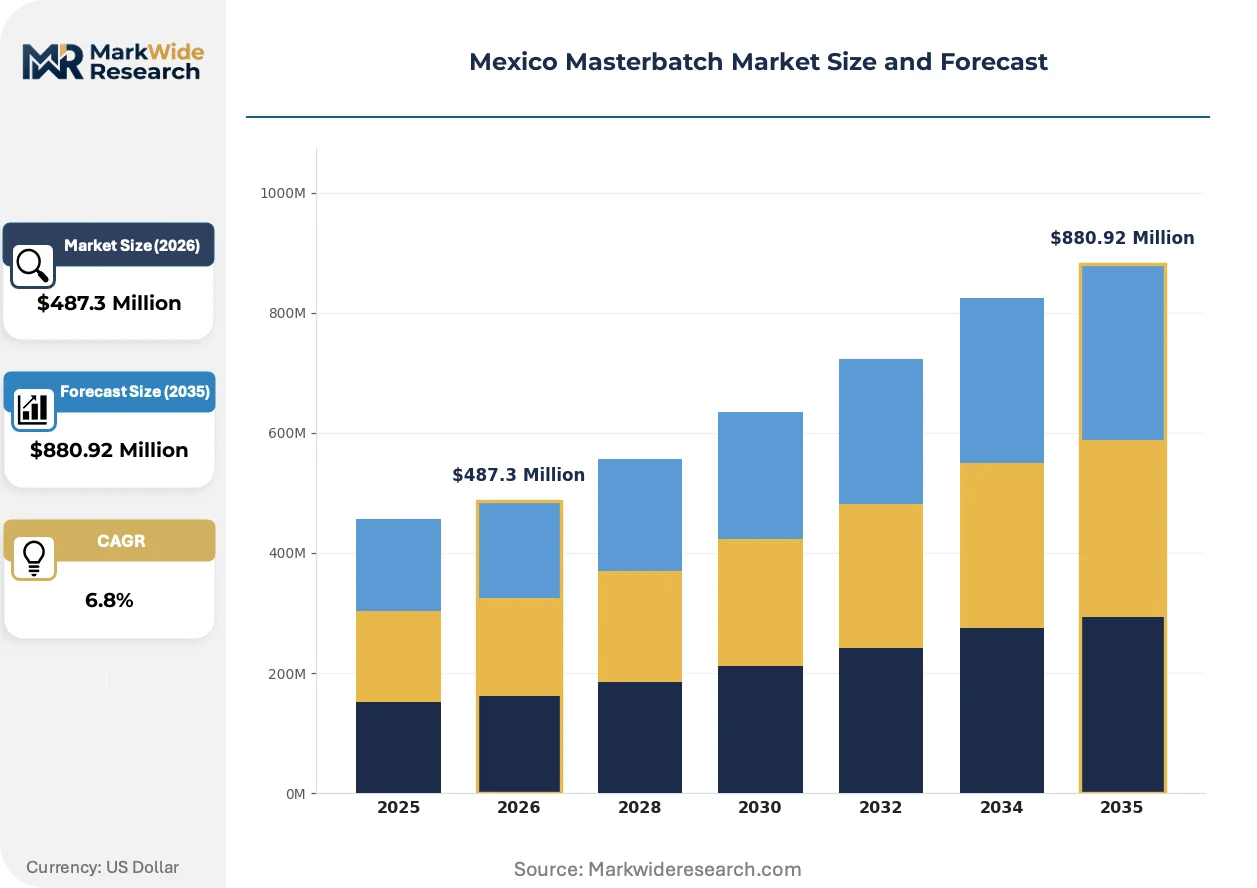
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Masterbatch, White Masterbatch, Color Masterbatch, Additive Masterbatch Application: Packaging, Consumer Goods, Automotive Components, Electrical Insulation Form: Granules, Pellets, Powders, Liquid End User: Plastics Manufacturers, Paints Producers, Textile Industry, Construction |
| Companies Covered | LyondellBasell Industries Holdings B.V., TOYO INK CO., LTD., Chroma Color Corporation, Sun Chemical, Ampacet Corporation, Avient Corporation, Cabot Corporation, BASF SE, Agama-Pigments & Masterbatch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Masterbatch Market Trends and Innovations
Digital color formulation tools and predictive let-down ratio software are compressing the traditional sample-and-approve cycle, while regulatory pressure on heavy metal content accelerates pigment system turnover across automotive and packaging applications.
Dispersion modeling software is virtualizing the traditional trial-and-error approach to color development in masterbatch production. Automotive suppliers in Aguascalientes now specify digital color recipes before physical sampling, cutting approval cycles from six weeks to ten days. This compression is virtualizing the role of regional technical service labs, centralizing formulation expertise while pushing quality verification toward automated in-line spectrophotometry.
PROFEPA's intensified NOM-057-ECOL enforcement is eliminating legacy lead-chromate pigment systems from imported masterbatch formulations. Compounders serving the Bajío corridor must now document heavy metal content through third-party testing at accredited Mexico City laboratories. Packaging converters with brand-owner contracts are most affected, accelerating reformulation investments ahead of scheduled 2027 compliance audits.
Buyers are consolidating masterbatch procurement around compounders with integrated color matching and regulatory documentation capabilities. Tier 2 automotive suppliers in Guanajuato now favor single-source arrangements covering black, color, and additive grades, displacing fragmented multi-supplier portfolios. This concentration is most visible in exterior automotive applications, where UV stability certification and lot-to-lot consistency outweigh marginal price advantages from spot purchasing.
Mexico Masterbatch Market Segmentation
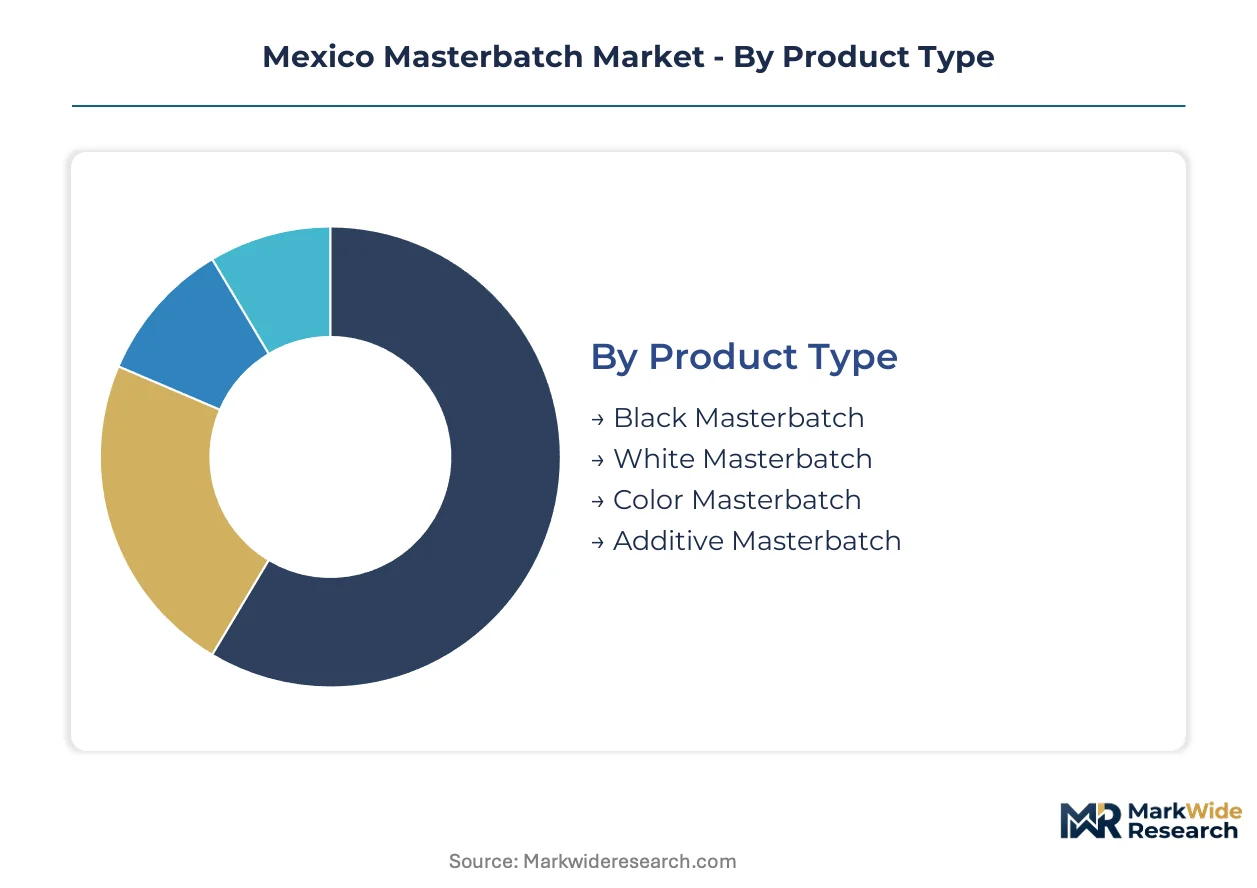
Masterbatch segmentation in Mexico reflects divergent technical requirements across automotive specification-grade applications and cost-sensitive packaging volumes. Procurement patterns fragment by performance tier, with UV-stable formulations commanding premium positioning against commodity black grades.
Product Type:
Formulations span the performance spectrum from basic carbon black loadings to multifunctional additive packages integrating flame retardancy and process stabilization.
- Black Masterbatch:Carbon black dispersions in polyethylene or polypropylene carriers, typically loaded at 25-50% by weight for agricultural film and automotive underhood components. Demand concentrates in Sinaloa's agricultural belt and the Bajío automotive corridor, where UV stabilization requirements above 3000 hours drive specification-grade procurement.
- Color Masterbatch:Organic and inorganic pigment systems dispersed for precise color matching in consumer-facing applications. Tier 1 automotive suppliers in Querétaro now require spectrophotometric documentation and heavy metal compliance certificates, compressing supplier qualification timelines.
- White Masterbatch:Titanium dioxide-based formulations serving appliance housings and packaging opacity requirements.
- Additive Masterbatch:Multifunctional packages combining antioxidants, UV stabilizers, and processing aids. Processors seek consolidated additive delivery to reduce dosing complexity.
Established volume favors black formulations; emerging adoption favors additive packages with regulatory documentation bundles.
Application:
End-use concentration varies by margin profile, with automotive specifications generating superior per-kilogram value against commodity packaging tonnage.
- Automotive Components:Specification-grade color matching for bumper fascias, interior trim, and underhood applications requiring thermal stability above 150°C. Exterior UV-stable formulations dominate procurement in Aguascalientes and Guanajuato, where IATF 16949 certification gates supplier entry.
- Packaging:The largest absolute tonnage segment, spanning flexible film, rigid containers, and closure systems. PROFEPA's NOM-057-ECOL enforcement is eliminating solvent-based colorants, redirecting demand toward pelletized formulations with verified emission profiles.
- Consumer Goods:Household products and personal care packaging requiring FDA-equivalent compliance for food contact.
- Electrical Insulation:Cable jacketing and connector housings demanding flame-retardant additive packages.
Packaging absorbs the greatest volume; automotive applications generate the steepest expansion trajectory in value terms.
Form:
Physical presentation shapes handling economics and dispersion efficiency across injection molding, extrusion, and blow molding operations.
- Pellets:Standardized cylindrical forms optimized for automated feeding systems and consistent let-down ratios. Automotive compounders in Monterrey prefer pelletized masterbatches for dust-free handling and precise dosing control.
- Granules:Irregular particulate forms offering lower production costs for agricultural film and construction applications with less stringent dispersion requirements.
- Powders:Fine-ground formulations for specialized coating and rotational molding applications.
- Liquid:Pumpable dispersions for continuous extrusion processes and color-on-demand systems.
Pellet dominance reflects automotive precision requirements; liquid forms are gaining share fastest in high-volume packaging extrusion.
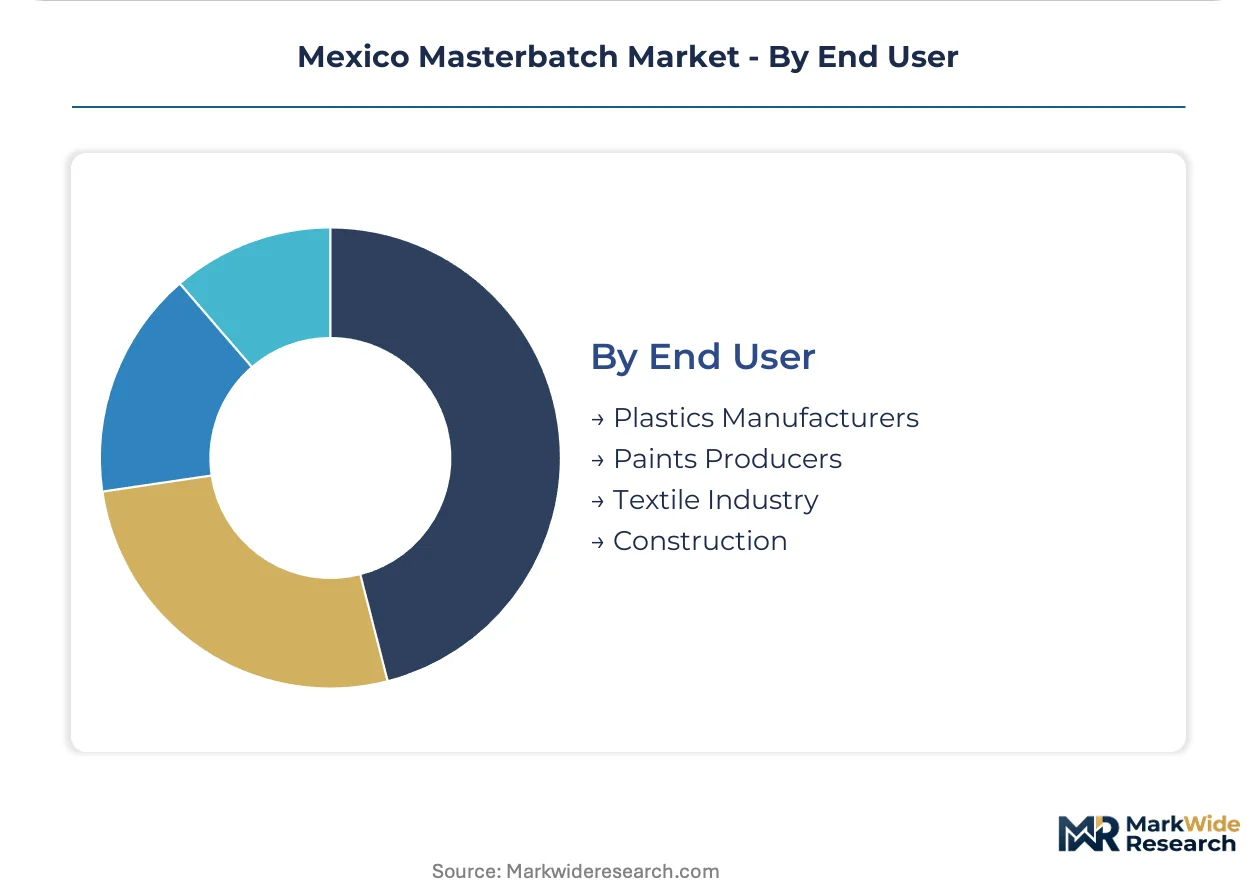
End User:
Customer sophistication varies dramatically, from multinational OEMs with captive technical specification teams to regional processors purchasing on spot price.
- Plastics Manufacturers:Injection molders, extruders, and blow molders serving as the primary demand channel. Tier 2 automotive suppliers in Guanajuato are consolidating procurement around single-source arrangements covering black, color, and additive grades.
- Construction:Piping, geomembrane, and insulation applications requiring weathering resistance and long-term color stability.
- Paints Producers:Specialty coatings and industrial finishes utilizing masterbatch dispersions for tinting systems.
- Textile Industry:Synthetic fiber coloration and nonwoven applications with unique carrier resin requirements.
Plastics manufacturers anchor volume demand; construction applications are expanding most quickly on infrastructure investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's masterbatch trade flows reflect a structural import dependence for carbon black feedstock and specialty pigments, with domestic compounding capacity concentrated near automotive assembly corridors to minimize finished goods logistics costs.
Mexico City Metro
Packaging converters in the metropolitan zone drive tonnage demand for white and color masterbatches serving food-contact applications. PROFEPA's NOM-057-ECOL enforcement has eliminated solvent-based colorant inventories across Ecatepec and Tlalnepantla processing parks. Multinational brand owners now require pelletized formulations with third-party emission verification from accredited laboratories in the capital district.
Nuevo León
Monterrey anchors northern demand through appliance manufacturing clusters producing washing machines and refrigerator housings. IATF 16949 certification requirements from Tier 1 automotive suppliers in Apodaca and Santa Catarina compress supplier qualification timelines. Metallic-effect color masterbatches with fingerprint-resistant additive packages penetrate this corridor as OEMs consolidate procurement around documented compliance bundles.
Bajío Region
Querétaro and Guanajuato concentrate specification-grade consumption for bumper fascias and interior trim applications. Tier 2 automotive suppliers in Silao and Irapuato are expanding injection molding capacity, pulling carbon black loadings above 25% for UV-stable exterior formulations. Heavy metal compliance documentation gates entry to this procurement channel.
Jalisco
Guadalajara's electronics packaging and medical device molding sectors generate demand for FDA-equivalent masterbatch grades. Testing infrastructure gaps extend qualification cycles for imported formulations lacking established local laboratory partnerships. Regional compounders seek toll manufacturing arrangements to access specialty additive combinations without captive compounding investment.
Northern Border States
Tijuana and Matamoros maquiladoras process masterbatches for re-export to US automotive and consumer goods markets. Customs delays at Laredo crossings expose margin compression when carbon black supply from US Gulf Coast faces freight rate volatility. Just-in-time delivery requirements favor compounders with bonded warehouse capacity near border crossings.
Mexico Masterbatch Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and dispersion technology. The Mexico masterbatch market structures around three tiers: multinational compounders with captive carbon black sourcing, regional formulators serving automotive specification channels, and toll processors filling specialty additive niches. Strategic moves concentrate on backward integration into carbon black supply and geographic densification near Bajío automotive clusters.
Among US-based chemical conglomerates, LyondellBasell Industries Holdings B.V. and Cabot Corporation occupy positions anchored by polymer carrier resin and carbon black feedstock control respectively. Japanese specialty chemical players including TOYO INK CO., LTD. represent the precision color matching archetype for consumer-facing packaging applications. These named entities exemplify competitive positioning strategies rather than definitive market share claims.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings B.V. |
| TOYO INK CO., LTD. |
| Chroma Color Corporation |
| Sun Chemical |
| Ampacet Corporation |
| Avient Corporation |
| Cabot Corporation |
| BASF SE |
| Agama-Pigments & Masterbatch |
| Others |
Pricing and Supply Chain Analysis
The US Gulf Coast carbon black supply corridor anchors Mexican masterbatch pricing power, with freight rate volatility at Laredo crossings transmitting directly to compounder margins and downstream contract renegotiations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Specification-grade automotive formulations with IATF 16949 certification and UV stability documentation command premium positioning, while agricultural-grade black masterbatches compete on volume scale. Cost compression in standard-tier color masterbatches is intensifying because organic pigment substitution for NOM-057-ECOL compliance degrades processing efficiency. Tier 2 automotive suppliers in Guanajuato exhibit lowest price sensitivity, prioritizing lot-to-lot consistency over spot purchasing advantages.
Supply Chain Analysis
Tariff exposure between the United States and Mexico dominates supply chain risk assessment for carbon black feedstock. Domestic compounders draw from US Gulf Coast carbon black production, South Korean specialty pigment manufacturing, and domestic polyethylene carrier resin supply. Single-source vulnerability concentrates in carbon black imports crossing at Laredo, where customs delays accumulate during peak agricultural film demand cycles. Distribution runs through bonded warehouse capacity near border crossings serving maquiladora re-export operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story, where PROFEPA enforcement of NOM-057-ECOL standards and IATF 16949 certification requirements create switching costs that cement incumbent positions.
For Market Incumbents: Build captive carbon black sourcing moats through long-term offtake agreements with US Gulf Coast producers, insulating margin structures from freight volatility. Expand technical service laboratories in Querétaro to compress automotive qualification timelines threatened by aging spectrophotometric talent concentration in Mexico City. Prioritize backward integration into post-industrial recycled feedstock partnerships ahead of extended producer responsibility mandate implementation. For New Entrants and Emerging Players: Build out toll manufacturing partnerships with asset-light processors in Toluca and Puebla, accessing specialty additive niches without captive compounding capital deployment. Target appliance manufacturing clusters in Monterrey for metallic-effect color masterbatches with fingerprint-resistant packages, the most penetrable segment lacking established supplier relationships. Lead with regulatory documentation bundles as the primary go-to-market angle, displacing fragmented multi-supplier portfolios. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with integrated color matching software and automated spectrophotometry capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. Acquisition targets should display established local laboratory partnerships for BIS-equivalent conformity assessment. Watch for inflection signals in PROFEPA enforcement intensity and extended producer responsibility framework finalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Black Supply | Captive sourcing from US Gulf Coast producers insulates margins from Laredo crossing volatility. |
| Technical Service Laboratory Expansion | Querétaro facilities address spectrophotometric talent scarcity constraining automotive qualification cycles. |
| Recycled Feedstock Partnership Development | Post-industrial traceability capabilities create first-mover positioning for extended producer responsibility compliance. |
| Digital Color Formulation Platform Deployment | Predictive let-down software compresses sample-and-approve cycles from six weeks to ten days. |
| Toll Manufacturing Network Partnership | Asset-light arrangements in Toluca and Puebla access specialty additive combinations without capital intensity. |
Research Methodology
Desk research of customs trade databases, SEC chemical company filings, and automotive production records preceded structured interviews with masterbatch plant managers, Tier 1 supplier procurement leads, and PROFEPA regulatory compliance officers. Primary fieldwork with distribution channel partners and technical R&D directors validated secondary findings. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down market sizing from import-export flow analysis.
Base-case assumptions held NOM-057-ECOL enforcement intensity and Bajío automotive cluster expansion rates constant across the analysis window, with sensitivity scenarios testing alternative regulatory trajectories. Segmentation modeling spanned product type, application tier, and regional production hub dimensions. CAGRs were derived from regression analysis against automotive production forecasts and agricultural film adoption curves, incorporating carbon black pricing indices and freight rate volatility bands as exogenous inputs.
Stress conditions across carbon black supply disruption severity, PROFEPA audit frequency, and pigment substitution cost trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions regarding regulatory enforcement and industrial cluster development. Macroeconomic contraction, unilateral tariff escalation, or breakthrough bio-based pigment technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Acrylic Pad Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Lentein Market
Specialty Compounds
India Sealants Market
Specialty Compounds
Acetyl Tyrosine Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Furniture Foam Market
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Film Dressing Market