
 Chemical Hardener Compounds Market | 2026-2036
Chemical Hardener Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Hardener Compounds Market Outlook
The capital-intensity divergence between integrated resin producers and specialty formulators is bifurcating competitive dynamics in chemical hardeners. Sika Limited leverages its global construction chemicals platform to sustain backward integration into epoxy hardener supply. Euclid Chemical Company anchors its position through specialized distribution to concrete contractors across North America. RCR Group competes on regional manufacturing scale in European construction applications.
Chemical hardener compounds are reactive substances that cross-link with base resins through polyaddition or condensation reactions, typically requiring precise stoichiometric ratios and controlled cure temperatures between 15°C and 60°C to achieve specified Shore D hardness and compressive strength. These compounds serve primarily to transform liquid or semi-liquid resin systems into solid, dimensionally stable materials for protective coatings, structural adhesives, and flooring systems. Epoxy hardeners command the largest value share due to their dominance in construction flooring and corrosion protection, while polyurethane variants represent the fastest-expanding category driven by automotive lightweighting and flexible electronics encapsulation. Powder-form hardeners capture premium positioning in automated manufacturing lines where solvent-free processing aligns with tightening workplace exposure limits.
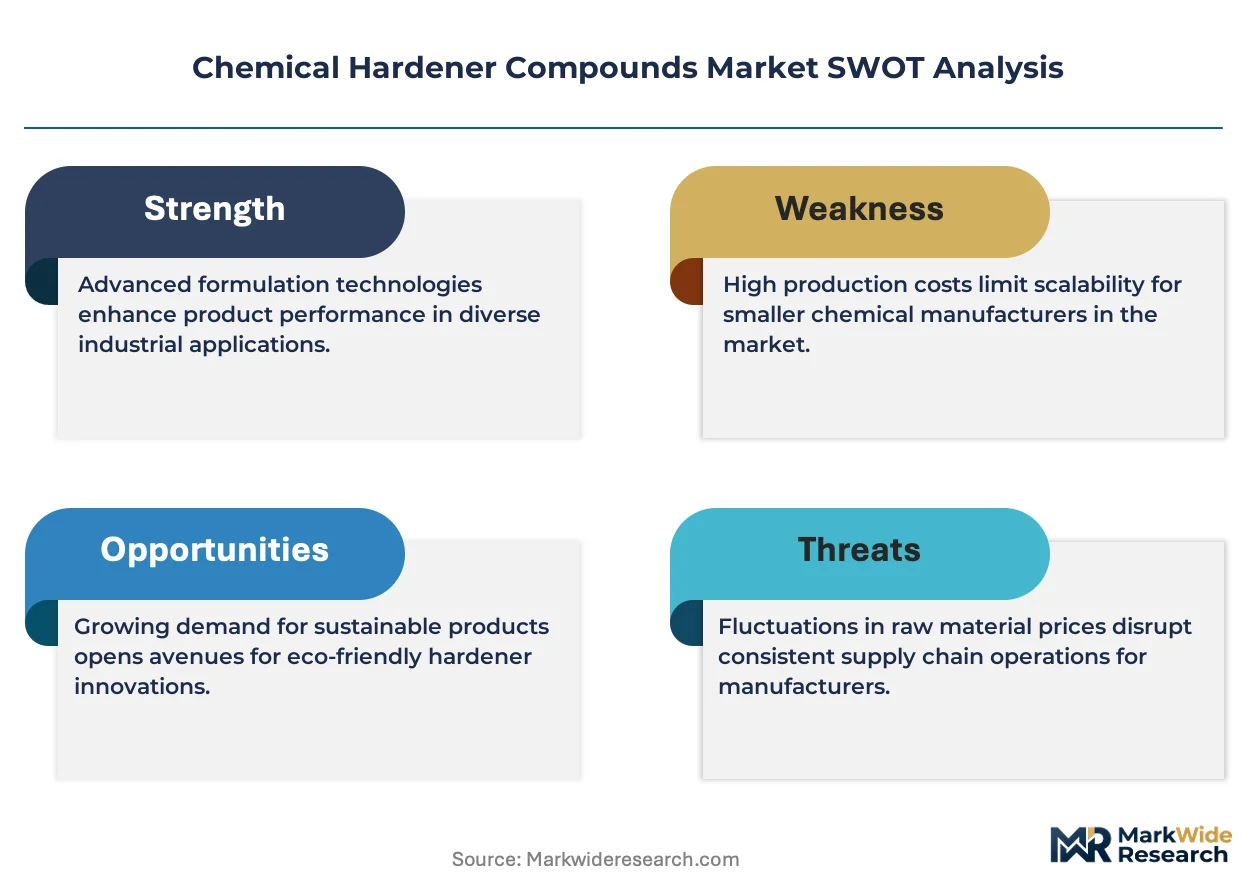
REACH registration requirements in Europe and EPA TSCA Section 5 premanufacture notifications in the United States impose substantial compliance burdens on novel amine and anhydride hardener introductions, effectively filtering market access to well-capitalized suppliers with dedicated regulatory affairs functions. OSHA permissible exposure limits for aromatic amines and Germany's TRGS 615 technical rules for hazardous substances further constrain formulation flexibility in industrial coating applications. Stakeholders must monitor evolving PFAS restrictions and bio-based feedstock certification schemes, as these frameworks will increasingly determine which hardener chemistries retain commercial viability across construction and automotive end uses.
Market Dynamics
REACH compliance deadlines and tightening EPA VOC rules are forcing simultaneous reformulation of amine and anhydride hardener portfolios across construction and automotive supply chains. Manufacturers face compressed timelines to certify low-emission alternatives while maintaining cure performance.
Growth Catalysts
- Construction flooring specifications:Industrial facility upgrades in China specify high-performance epoxy systems for concrete surface treatments. Infrastructure investment absorbs substantial hardener volumes.
- REACH registration completion:European suppliers with approved substance dossiers gain preferential access to industrial coating contracts. Regulatory clarity accelerates procurement decisions.
- Polyurethane automotive applications:Lightweighting mandates drive flexible encapsulation demand for electronics. Polyurethane hardener formulations penetrate vehicle assembly lines.
Market Restraints
- Petrochemical feedstock volatility:Benzene and propylene derivative costs swing hardener production economics. Margins compress during upstream price spikes.
- Amine supply concentration:Aromatic amine production clusters in coastal China and the US Gulf Coast. Geopolitical friction threatens just-in-time delivery.
- Cure temperature limitations:Ambient-cure systems below 15°C suffer extended set times. Cold-climate construction seasons constrain application windows.
Strategic Opportunities
- Bio-based certification schemes:EU Green Deal procurement rules favor hardeners with renewable carbon content. Early certifiers capture public infrastructure tenders.
- Wind blade manufacturing:Epoxy hardener systems for composite laminates expand with offshore turbine installations. Specialized anhydride formulations penetrate this vertical.
- Automated powder coating lines:Powder-form hardeners eliminate solvent handling in high-throughput facilities. Workplace exposure limit compliance drives conversion.
Industry Challenges
- Formulation chemist scarcity:Stoichiometric ratio optimization for novel low-VOC systems requires specialized expertise. Talent competition intensifies between resin integrators and specialty formulators.
- Dual certification timelines:EPA TSCA Section 5 premanufacture notifications and ECHA REACH updates run on parallel tracks. Sequential approval delays commercial launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Hardener Compounds Market |
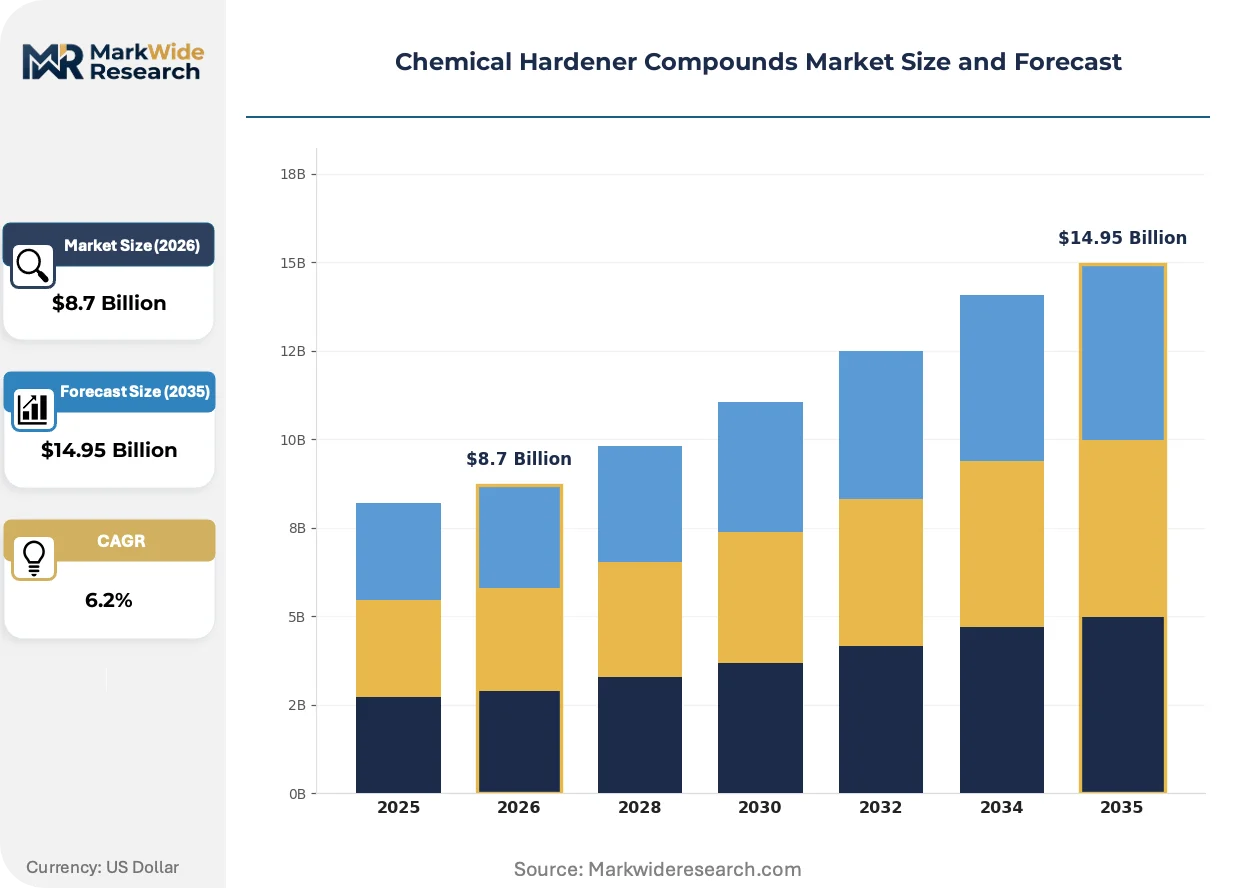
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Polyester, Acrylic Application: Construction, Automotive, Electronics, Aerospace End User: Manufacturers, Contractors, OEMs, Distributors Form: Liquid, Powder, Paste, Granule |
| Companies Covered | Sika Limited, Euclid Chemical Company, RCR Group, Flowcrete Group Ltd., Laticrete International Inc, W. R. Meadows Inc, Boyer Industries Corporation (Prosoco), Convergent Concrete Technologies LLC, Fescon Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Hardener Compounds Market Strategic Shifts
Reactive chemistry platforms are diverging as integrated producers pursue captive hardener supply while specialty formulators develop application-specific modifiers. This bifurcation reshapes R&D investment patterns and partnership structures.
Waterborne epoxy hardener technology is fragmenting the solvent-borne dominance in industrial maintenance coatings. Marine and protective coating contractors adopt these systems to meet OSHA permissible exposure limits for aromatic amines. The shift compresses margins for conventional solvent-based suppliers while opening formulation partnerships with regional distributors.
EPA TSCA Section 5 notification requirements are extending review timelines for novel anhydride hardeners entering US manufacturing. Industrial coating formulators stockpile approved substances to hedge against approval delays. Construction flooring applications face the tightest substitution constraints as specified systems await regulatory clearance.
Specification authority is migrating from general contractors to certified concrete specialists in North American commercial flooring. Euclid Chemical and similar distributors build direct technical relationships with applicator crews. This channel compression rewards suppliers with localized technical service capabilities over pure manufacturing scale.
Chemical Hardener Compounds Market Segmentation
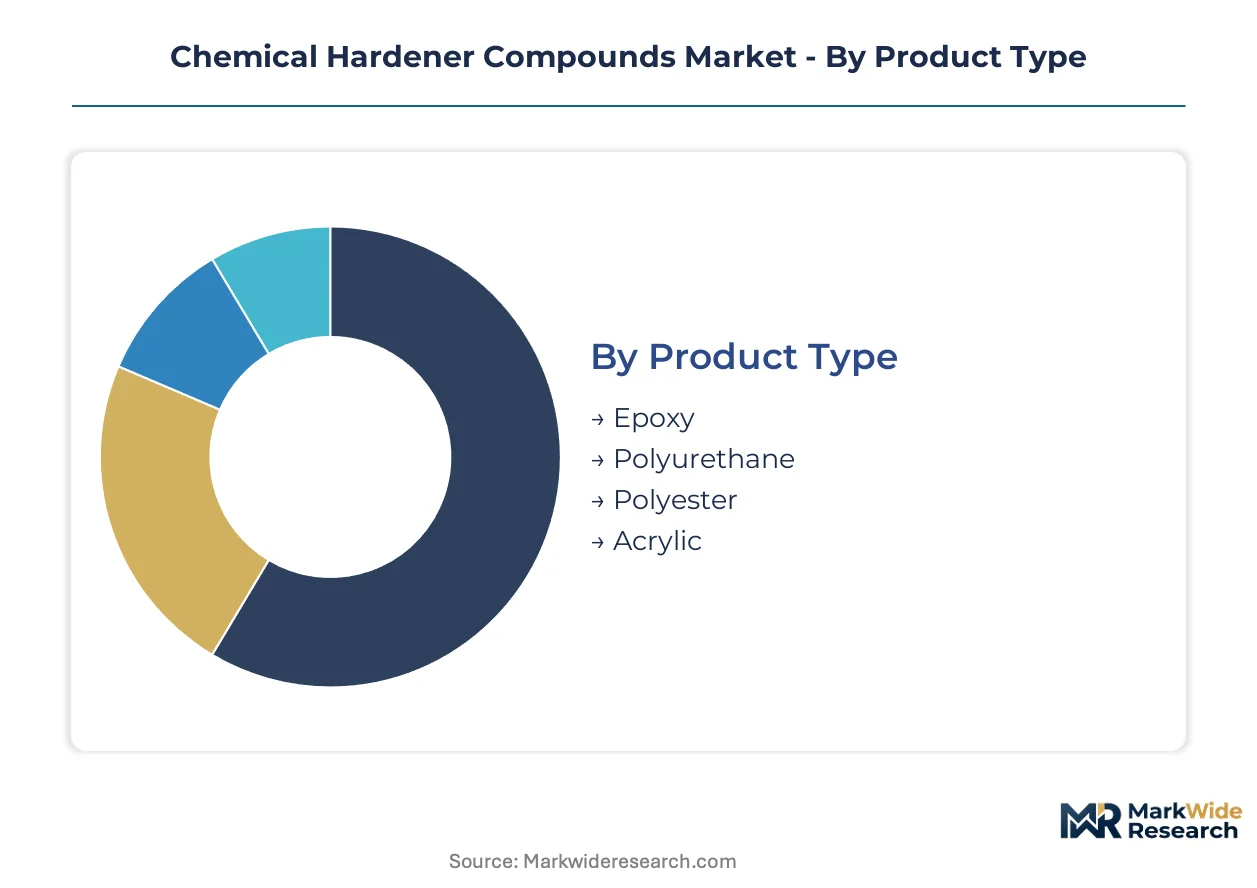
Segmentation in chemical hardener compounds reveals how formulation chemistry, physical state, and customer procurement patterns create distinct commercial battlegrounds. Suppliers must align R&D investment and distribution architecture to the specific technical and regulatory requirements of each slice.
Product Type:
Domestic production dominates epoxy and polyester hardener supply chains in China and the United States, while polyurethane variants flow through more export-intensive networks serving European automotive assembly plants.
- Epoxy:These amine and anhydride-based cross-linking agents cure through polyaddition reactions with diglycidyl ether resins. Construction flooring specifications in China absorb substantial volumes as industrial facility upgrades specify high-performance concrete surface treatments. REACH registration dossiers for novel aliphatic amines face extended ECHA review timelines, compressing formulation flexibility.
- Polyurethane:Isocyanate-terminated prepolymers react with polyol hardeners to form elastomeric or rigid thermosets. German and Japanese automotive lightweighting programs drive flexible encapsulation demand for electronics assemblies. EPA TSCA Section 5 premanufacture notifications for modified isocyanates extend approval cycles to 180 days.
- Polyester:Peroxide and cobalt-based promoters accelerate unsaturated polyester cross-linking in composite manufacturing. Marine and corrosion protection applications in South Korea and Taiwan concentrate procurement.
- Acrylic:UV-curable acrylate hardeners enable rapid processing in automated coating lines. Mexican and Brazilian industrial finishing operations represent emerging demand pockets.
Epoxy holds the largest share; momentum sits with polyurethane as vehicle electrification expands electronics encapsulation requirements.
Application:
Cost tier stratification separates specification-grade systems for infrastructure from commodity formulations in consumer goods manufacturing.
- Construction:High-build epoxy flooring systems for warehouse and logistics facilities require precise stoichiometric control to achieve specified Shore D hardness. Chinese provincial infrastructure tenders increasingly mandate low-VOC compliance with MEE emission standards.
- Automotive:Underhood component encapsulation and structural adhesives demand thermal stability above 150°C. German KBA type-approval processes for adhesive bonding in crash-critical structures impose validation burdens on hardener suppliers.
- Electronics:Potting compounds for power modules and circuit board protection favor low-ion-content anhydride formulations. Japanese METI energy efficiency regulations for industrial drives expand high-voltage insulation demand.
- Aerospace:Out-of-autoclave prepregs for composite primary structures require extended pot-life hardener systems. FAA certification timelines for new adhesive formulations stretch to 24 months.
Construction generates the highest absolute volume; aerospace commands the steepest premium per kilogram applied.
End User:
Customer type determines whether procurement flows through specification authority held by formulators or direct technical relationships with applicator crews.
- Manufacturers:Captive hardener production at integrated resin producers like Sika Limited secures supply chain control. In-house formulation teams optimize cure profiles for specific substrate conditions.
- Contractors:North American concrete specialists specify systems directly, bypassing general contractor intermediaries. Euclid Chemical builds technical service relationships with applicator crews to anchor loyalty.
- OEMs:Automotive and electronics original equipment manufacturers audit hardener suppliers for IATF 16949 and ISO 14001 compliance. Dual-source requirements prevent single-supplier concentration.
- Distributors:Regional chemical distributors stock approved substances to hedge against EPA TSCA notification delays. Inventory carrying costs pressure margins during feedstock price volatility.
Manufacturers retain the largest procurement volume; contractors are gaining specification authority fastest in commercial flooring.
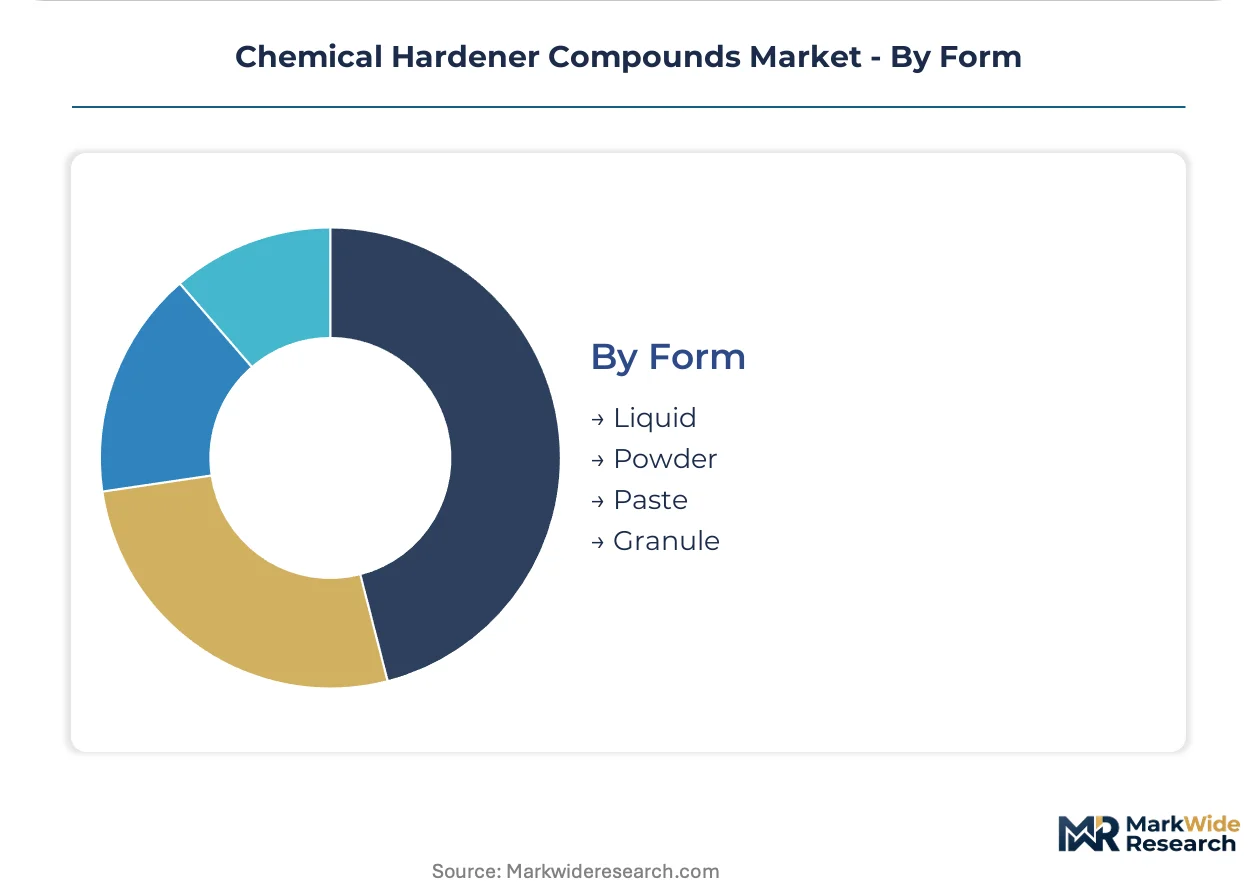
Form:
Supply concentration diverges between solvent-intensive liquid production on the US Gulf Coast and powder processing in automated European manufacturing corridors.
- Liquid:Solvent-borne amine adducts dominate industrial maintenance coatings. OSHA permissible exposure limits for aromatic amines push contractors toward lower-emission alternatives.
- Powder:Solid anhydride and phenolic hardeners enable solvent-free processing in automated powder coating lines. Germany's TRGS 615 technical rules for hazardous substances reward workplace exposure elimination.
- Paste:Thixotropic formulations for vertical surface application and trowel-grade flooring systems. Bridge deck waterproofing in Canada absorbs specialized paste hardener volumes.
- Granule:Free-flowing solid hardeners for bulk handling in wind blade manufacturing. Offshore turbine installations in Denmark and the Netherlands drive specialized anhydride granule demand.
Liquid maintains dominant volume share; powder is climbing the fastest as workplace exposure regulations tighten across industrialized economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Chinese infrastructure contractors specify high-build epoxy systems for industrial flooring, while German automotive engineers prioritize low-emission polyurethane formulations for electronics encapsulation.
China
Provincial infrastructure tenders in Jiangsu and Guangdong absorb substantial epoxy hardener volumes for warehouse flooring systems. MEE emission standards mandate low-VOC compliance in industrial coating applications. The Yangtze River Delta cluster hosts concentrated manufacturing of amine adducts serving domestic construction demand.
Germany
Automotive lightweighting programs in Stuttgart and Munich drive flexible encapsulation demand for power electronics. TRGS 615 technical rules for hazardous substances accelerate powder-form hardener adoption in automated coating lines. The North Rhine-Westphalia corridor anchors European production of specialty anhydride formulations.
United States
Concrete surface treatment specifications from Texas to California sustain epoxy hardener procurement for commercial flooring. EPA TSCA Section 5 premanufacture notifications extend review timelines for novel anhydride introductions. Gulf Coast petrochemical infrastructure feeds benzene derivative supply to regional formulators.
Japan
METI energy efficiency regulations for industrial drives expand high-voltage insulation demand using low-ion-content anhydride systems. Electronics potting compound specifications from Osaka-based OEMs favor precision-cure formulations. The Kanto region concentrates polyurethane hardener R&D for flexible encapsulation applications.
India
Infrastructure investment in Maharashtra and Gujarat generates construction flooring demand for epoxy systems. BIS certification requirements for imported chemical hardeners filter market access to compliant suppliers. The Delhi-Mumbai Industrial Corridor absorbs substantial volumes for logistics facility upgrades.
Chemical Hardener Compounds Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier. Backward integration into epoxy hardener supply distinguishes capital-intensive resin producers from application-focused formulators. Two strategic archetypes dominate: construction chemicals platforms with captive manufacturing and regional distributors with localized technical service. Competitive moves center on regulatory dossier completion and specification authority capture through direct contractor relationships.
Within the integrated tier, Sika Limited exemplifies global construction chemicals platforms with upstream control over hardener supply. Euclid Chemical Company and RCR Group occupy positions as regional specialists—Euclid anchoring North American concrete contractor channels, RCR leveraging European manufacturing scale. These three represent the bifurcation between scale-driven integration and service-intensive distribution.
| Leading Market Players |
|---|
| Sika Limited |
| Euclid Chemical Company |
| RCR Group |
| Flowcrete Group Ltd. |
| Laticrete International Inc |
| W. R. Meadows Inc |
| Boyer Industries Corporation (Prosoco) |
| Convergent Concrete Technologies LLC |
| Fescon Oy |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory buffers at epoxy hardener distributors in the US Gulf Coast and Yangtze River Delta signal how supply concentration translates directly into pricing leverage for integrated resin producers. These stockpile levels compress margins for regional formulators while rewarding backward-integrated platforms with captive amine supply.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated producers and large construction flooring contractors, insulating volume commitments from benzene derivative spot volatility. Three-tier pricing structure across specification-grade, standard industrial, and economy formulations separates REACH-registered suppliers from uncertified competitors. Cost compression in economy-grade amine adducts is intensifying because Chinese domestic production scales. General contractors in commercial flooring remain most price-sensitive; aerospace OEMs with FAA certification requirements show least sensitivity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for polyurethane hardener shipments to German automotive assembly plants. Manufacturing concentrates in China, the United States, and Germany. Feedstock supply draws from benzene derivatives, propylene oxide, and aliphatic amine precursors. Single-source vulnerability clusters around coastal Chinese aromatic amine production. Distribution runs through regional construction chemical distributors with localized technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance deadlines and EPA TSCA Section 5 notification backlogs are compressing formulation timelines, creating high-growth disruption for suppliers with approved regulatory dossiers.
For Market Incumbents: Consolidate backward integration into amine hardener supply to defend against specialty formulator encroachment in specification-grade flooring systems. Lock in long-term offtake agreements with provincial infrastructure contractors in China before MEE emission standards tighten further. Prioritize REACH registration completion for novel aliphatic amines to capture European industrial coating contracts.
For New Entrants and Emerging Players: Anchor in bio-based certification schemes to penetrate EU Green Deal procurement channels for public infrastructure tenders. Target powder-form hardener production for automated coating lines in Germany where TRGS 615 workplace exposure rules accelerate solvent-free conversion. Partner with regional distributors lacking captive technical service capabilities.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because hardener suppliers with completed REACH dossiers and EPA premanufacture approvals command persistent procurement preference. Acquisition targets should combine regional manufacturing scale with localized specification authority through direct contractor relationships. Watch ECHA substance evaluation timelines as the signal for which chemistries retain commercial viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Supply | Sika Limited secures captive feedstock for epoxy hardener production, insulating margins from benzene volatility. |
| REACH Registration Completion | European suppliers with approved dossiers gain preferential access to industrial coating contracts under ECHA deadlines. |
| Bio-based Certification Investment | Early certifiers capture EU Green Deal public infrastructure tenders with renewable carbon content mandates. |
| Powder-form Hardener Capacity Expansion | Solvent-free processing aligns with Germany's TRGS 615 technical rules for hazardous substances elimination. |
| Direct Contractor Technical Service | Euclid Chemical builds specification authority with North American concrete specialists, bypassing general contractor intermediaries. |
Study Parameters
Initial hypotheses were tested against primary input from plant managers at hardener manufacturing facilities, procurement leads at downstream construction contractors, distribution channel partners, and technical R&D directors at specialty formulators, and refined through secondary validation against customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance registration databases. Bottom-up volume estimates triangulated with top-down market sizing across product chemistry, physical form, end-use industry, and regional production hub.
Variance decomposition across the projection horizon isolates volume, price, and mix effects for each segmentation dimension modeled: epoxy versus polyurethane versus polyester chemistry, liquid versus powder versus paste physical state, construction versus automotive versus electronics end-use, and captive versus merchant supply mode. CAGRs derive from regression-based trend extrapolation calibrated to named regulatory inflection points including REACH compliance deadlines and MEE emission standard implementations. Industry-specific inputs include benzene derivative feedstock cost indices and provincial infrastructure tender volumes in China.
Material uncertainties — petrochemical feedstock price spikes, geopolitical friction affecting aromatic amine supply corridors, and extended EPA TSCA notification delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and substitution elasticity in cold-climate construction applications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Global Zinc Phosphate Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Saudi Arabia Collagen Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market