
 North America Lithium Compound Market | 2026-2036
North America Lithium Compound Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lithium Compound Market Intelligence
The US Inflation Reduction Act's domestic content bonus credit structure is hardening demand for North American-sourced lithium compounds. Albemarle Corporation leverages its Silver Peak brine operations in Nevada to sustain the region's largest integrated lithium production footprint. Livent Corporation anchors its competitive position through specialized lithium hydroxide output tailored to high-nickel cathode chemistries. Arcadium Lithium competes by extending its asset base across both US and Argentine salares with differentiated direct shipping ore capabilities.
North America lithium compounds encompass chemically processed lithium derivatives including carbonate, hydroxide, metal, and specialty salts, typically refined to battery-grade specifications exceeding 99.5 percent purity through acid leaching, electrochemical purification, or solar evaporation sequences. These compounds serve primarily as cathode precursors in lithium-ion electrochemical cells and as fluxing agents in industrial glass and lubricating grease formulations. Lithium hydroxide claims the fastest-expanding product position as automakers and cell manufacturers pivot toward nickel-rich NMC and nickel-cobalt-aluminum architectures requiring lower-temperature sintering profiles. Battery production dominates the application hierarchy by margin contribution, while automotive end users command the most intensive offtake negotiations and longest-term supply agreements.
The US Environmental Protection Agency and Mine Safety and Health Administration jointly shape extraction permitting timelines and operational compliance burdens for domestic lithium projects. Canada's Investment Canada Act and provincial environmental assessment processes in Quebec and Ontario govern foreign participation in critical mineral development. Stakeholders must monitor how evolving US Federal Energy Regulatory Commission grid interconnection rules and state-level renewable portfolio standards will synchronize battery storage deployment with lithium compound procurement cycles.
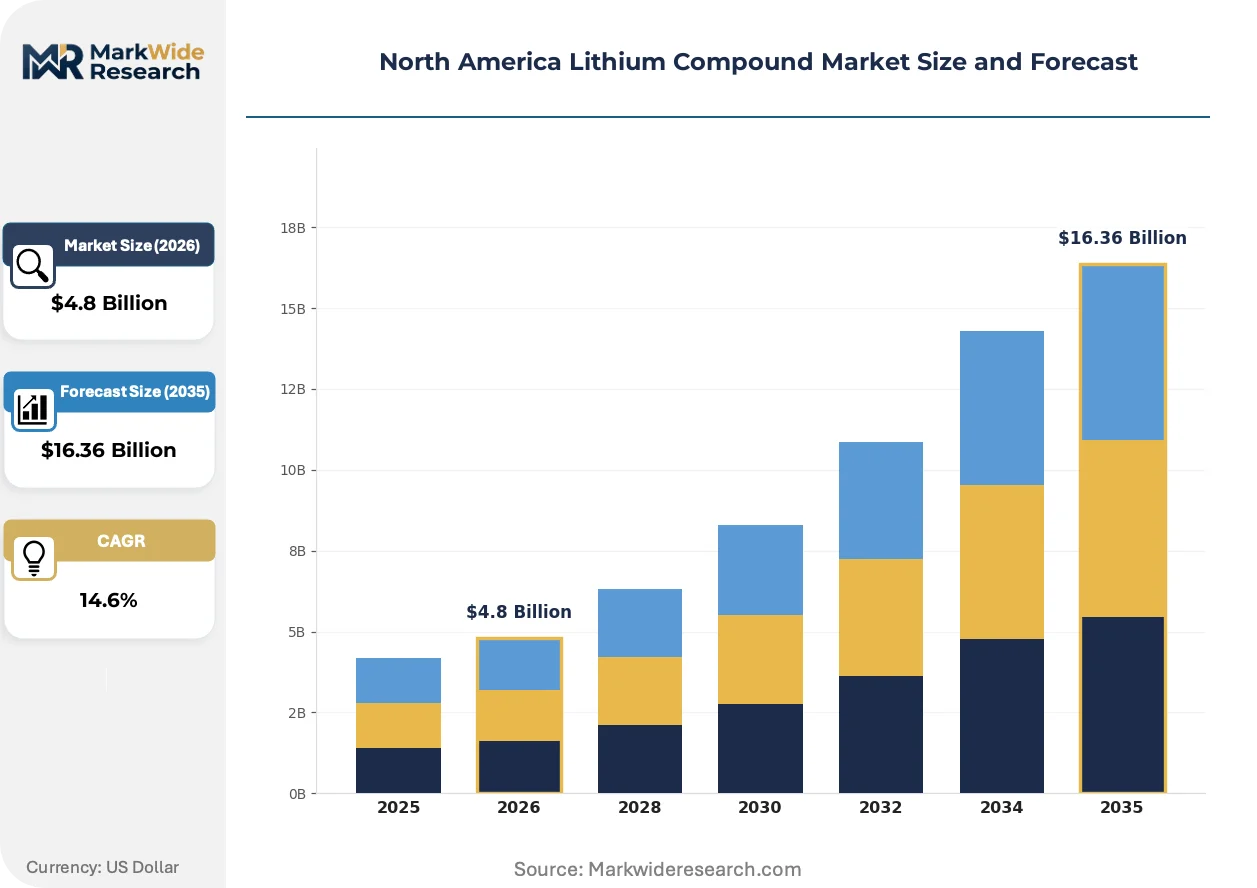
Market Dynamics
The US Inflation Reduction Act's domestic content bonus credit structure is hardening demand for North American-sourced lithium compounds. This policy mechanism redirects supply chain investments toward domestic extraction and refining capacity.
Growth Catalysts
- Electric vehicle battery procurement:Detroit automakers are hardening demand across the Great Lakes manufacturing corridor. Cell manufacturers are securing long-term offtake agreements for battery-grade lithium hydroxide.
- US Inflation Reduction Act:The domestic content bonus credit structure mandates North American sourcing thresholds. Automakers must qualify for the full credit through regional supply chain compliance.
- Nevada brine district concentration:Clayton Valley's lithium-rich brine formations support scalable solar evaporation operations. This geographic cluster enables integrated production from extraction to battery-grade refining.
Market Restraints
- Permitting timeline volatility:The US Environmental Protection Agency and Mine Safety and Health Administration jointly shape extraction permitting timelines. Project developers face multi-year environmental review cycles.
- Spodumene concentrate dependency:North American refiners rely partially on imported hard rock feedstock. Quebec's James Bay belt offers limited near-term expansion relative to conversion capacity.
- Water intensity constraints:Brine extraction in arid western states competes with agricultural and municipal water allocations. Solar evaporation sequences require substantial surface water rights.
Strategic Opportunities
- Direct extraction technology convergence:Selective absorption and electrochemical separation methods are converging with traditional brine operations. These technologies enable faster lithium recovery from lower-concentration sources.
- Quebec hydroelectric-powered refining:The province's renewable grid supports low-carbon lithium hydroxide production. Carbon intensity metrics are becoming a procurement differentiator for European automakers.
- Battery recycling feedstock integration:Black mass processing facilities are emerging as secondary lithium sources. Recycled content qualifies under IRA domestic content calculations.
Industry Challenges
- Electrochemical purification skill scarcity:Battery-grade lithium production requires specialized chemical engineering expertise. Training pipelines lag behind capacity expansion timelines.
- Grid interconnection synchronization:The US Federal Energy Regulatory Commission rules govern renewable energy pairing with refining operations. Developers must coordinate power purchase agreements with production ramp schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lithium Compound Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithiated Carbonate, Lithium Hydroxide, Lithium Metal, Lithium Salts Application: Battery Production, Glass Manufacturing, Grease Production, Pharmaceuticals End User: Automotive, Electronics, Aerospace, Renewable Energy Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Albemarle Corporation, Livent Corporation, FMC Corporation, Lithium Americas Corp, Sociedad Química y Minera de Chile, Arcadium Lithium, American Lithium Corp, Piedmont Lithium, Neometals Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lithium Compound Market Strategic Shifts & Innovations
Direct lithium extraction technologies are automating separation workflows and compressing production timelines. These advances are reshaping competitive positioning between brine and hard rock sourcing strategies.
Continuous ion exchange systems are automating selective lithium recovery from complex brine matrices. Developers in Nevada's Clayton Valley are piloting these units to reduce evaporation pond footprints. The technology is automating impurity rejection and enabling year-round production regardless of seasonal evaporation rates.
The US Inflation Reduction Act's domestic content bonus credit is restructuring supplier qualification protocols. Automakers now require documented North American provenance for cathode precursor materials. High-nickel NMC chemistries are most affected, as these formulations demand battery-grade lithium hydroxide with stringent impurity specifications.
Long-term offtake contracting is displacing spot market procurement for battery-grade compounds. Cell manufacturers are securing five-to-ten-year supply agreements directly with refiners. This pattern is most visible in negotiations between Detroit automakers and Quebec-based spodumene converters, where volume commitments lock in capacity years ahead of production startup.
North America Lithium Compound Market Segmentation
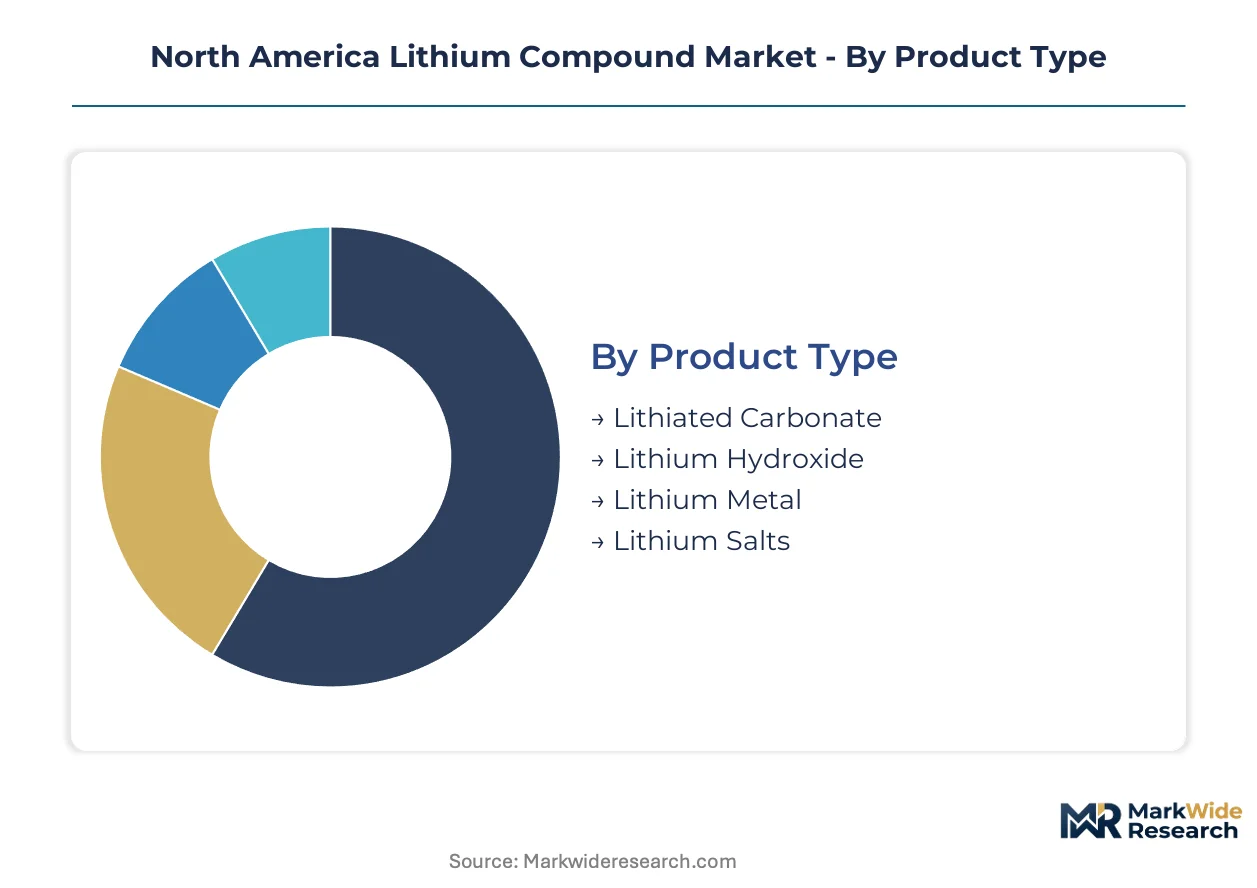
Lithium compound procurement patterns diverge sharply across product specifications, end-use purity requirements, and customer scale. Understanding these segment boundaries clarifies where capital deployment concentrates and which channels capture margin.
Product Type:
Capital intensity varies dramatically across these four product categories, with electrochemical purification infrastructure demanding the heaviest upfront investment.
- Lithium Hydroxide:Battery-grade material exceeding 99.5% purity serves high-nickel NMC and NCA cathode architectures requiring lower-temperature sintering profiles. Detroit automakers are locking in five-to-ten-year offtake agreements for this specification through Quebec-based converters and Nevada brine refiners, driven by IRA domestic content bonus credit thresholds.
- Lithiated Carbonate:Traditional lithium-ion precursor with established supply chains from South American brine operations. LFP battery chemistries and industrial glass applications sustain steady demand, though automakers are shifting procurement toward hydroxide for energy density targets.
- Lithium Metal:Ultra-high purity metal for solid-state battery anodes and specialized aerospace alloys. Thin-film deposition and molten salt electrolysis require specialized production infrastructure.
- Lithium Salts:Specialty derivatives including chloride, bromide, and lubricating grease formulations. Industrial applications in air conditioning and chemical synthesis sustain niche demand.
Most installed capacity flows through Lithiated Carbonate. Expansion is steepest in Lithium Hydroxide.
Application:
Volume concentration and margin capture diverge across these four application clusters, with battery production commanding the most intensive contract negotiations.
- Battery Production:Cathode precursor demand from cell manufacturers and integrated automakers dominates value capture. Long-term supply agreements now span five-to-ten-year horizons with stringent impurity specifications and documented North American provenance requirements.
- Glass Manufacturing:Fluxing agent applications in ceramic and glass formulations provide steady industrial offtake. Lower purity tolerances reduce processing costs compared to battery-grade specifications.
- Grease Production:Lithium-based lubricants for high-temperature industrial and automotive applications. Formulators blend lithium hydroxide with fatty acids for multi-purpose grease products.
- Pharmaceuticals:High-purity lithium carbonate and citrate for mood disorder therapeutics. FDA compliance and batch certification requirements sustain premium pricing tiers.
Battery Production captures the dominant revenue share. Glass Manufacturing maintains the most stable demand baseline.
End User:
Customer scale and technical specification intensity shape procurement patterns across these four end-user categories.
- Automotive:OEMs and their cell manufacturing joint ventures drive the most aggressive capacity expansion timelines. Detroit's Great Lakes manufacturing corridor anchors North American demand concentration with IRA compliance requirements hardening sourcing mandates.
- Electronics:Consumer device and power tool manufacturers procure smaller volumes with shorter contract cycles. Cylindrical and pouch cell formats for portable applications sustain diversified demand.
- Renewable Energy:Grid-scale battery storage developers are emerging as volume customers with distinct procurement rhythms. FERC interconnection rule synchronization affects deployment timelines and compound ordering patterns.
- Aerospace:Specialized alloys and thermal management applications require ultra-high purity specifications. Long qualification cycles limit supplier switching.
Automotive commands the largest contract volumes. Renewable Energy is climbing the fastest as grid storage deployment accelerates.
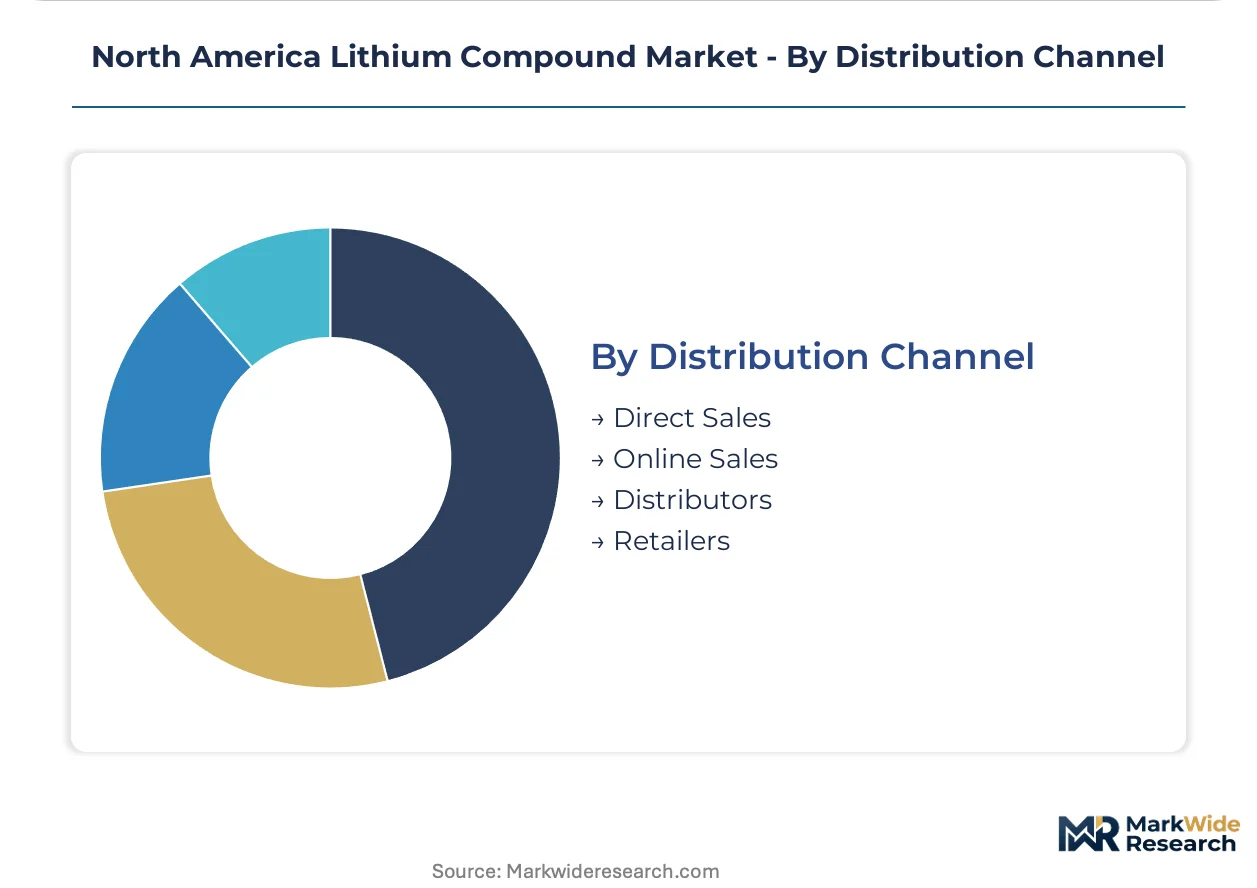
Distribution Channel:
Channel selection correlates with customer scale, technical service requirements, and IRA documentation needs.
- Direct Sales:Integrated producers contract directly with automakers and cell manufacturers for battery-grade compounds. Provenance documentation and long-term volume commitments flow through these relationships.
- Distributors:Industrial chemical distributors serve smaller-volume customers in glass, grease, and pharmaceutical applications with blended inventory and technical support services.
- Online Sales:E-commerce platforms capture research-grade and small-batch laboratory demand with rapid fulfillment and certificate-of-analysis transparency.
- Retailers:Limited presence for specialty lubricant and consumer product formulations through industrial supply chains.
Direct Sales channels handle the majority of battery-grade volume. Distributors retain the broadest customer coverage across industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The lithium compound industry traces its North American scaling to 1966, when Foote Mineral Company established the first commercial brine operations in Nevada's Clayton Valley. This Nevada brine corridor remains the continent's production anchor six decades later.
United States
Nevada's Clayton Valley brine district supplies the majority of domestic lithium extraction, with solar evaporation sequences feeding integrated refining complexes. The EPA and Mine Safety and Health Administration jointly govern extraction permitting timelines, extending environmental review cycles to multi-year horizons. Michigan's Great Lakes manufacturing corridor hosts Detroit automaker cell manufacturing joint ventures that are locking in five-to-ten-year offtake agreements for battery-grade lithium hydroxide.
Canada
Quebec's James Bay spodumene belt anchors hard rock lithium development, with hydroelectric-powered refining emerging as a carbon intensity differentiator for European automaker procurement. The Investment Canada Act governs foreign participation thresholds in critical mineral projects, while provincial environmental assessment processes in Quebec and Ontario shape development timelines. Ontario's automotive manufacturing corridor is integrating cathode precursor production with existing vehicle assembly infrastructure.
Mexico
Sonora's clay-hosted lithium deposits represent emerging extraction frontiers, though project development timelines lag established brine and hard rock operations. The country's national mining regulator shapes concession frameworks and environmental compliance protocols for foreign developers. Baja California's proximity to US battery manufacturing clusters positions the state for potential downstream refining investment.
North America Lithium Compound Market Key Industry Players
Capital-heavy integrated producers compete with asset-light conversion specialists for margin capture in North American lithium compounds. The market structure concentrates around three to five vertically integrated operators controlling extraction-through-refining value chains, with a fragmented tier of project developers seeking offtake partnerships. Strategic archetypes include brine-based integrated producers, spodumene converters with hydroelectric power access, and direct extraction technology developers. Dominant competitive moves encompass long-term automaker offtake contracting and backward integration into captive feedstock supply.
Within the integrated producer tier, Albemarle Corporation and Arcadium Lithium exemplify capital-heavy operators with established extraction footprints. Livent Corporation occupies a specialized position in lithium hydroxide output tailored to high-nickel cathode requirements. These three entities represent distinct strategic postures: brine-based Nevada operations, trans-Andean salare diversification, and hydroxide-focused refining specialization.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Livent Corporation |
| FMC Corporation |
| Lithium Americas Corp |
| Sociedad Química y Minera de Chile |
| Arcadium Lithium |
| American Lithium Corp |
| Piedmont Lithium |
| Neometals Ltd |
| Others |
Cost & Logistics Intelligence
Backward integration into captive brine feedstock anchors pricing power for Nevada-based refiners serving IRA-compliant automaker contracts. This upstream control over Clayton Valley extraction rights enables margin defense against imported spodumene price volatility while securing long-term offtake premiums.
Pricing Analysis
Long-term contract-based offtake agreements dominate battery-grade lithium hydroxide procurement, with pricing stratifying across battery-grade certification tiers, volume scale commitments, and carbon intensity documentation. Price differentiation hinges on IRA domestic content qualification thresholds and automaker-specific impurity specifications. Cost compression in standard-grade carbonate runs through South American brine import competition. Spot market buyers in industrial glass applications exhibit the highest price sensitivity, while Detroit OEMs locking in five-to-ten-year hydroxide supply show the least.
Supply Chain Analysis
Battery-grade qualification gates from the US EPA and state environmental regulators constrain supplier entry and fragment the qualified refiner base. Geographic supply concentrates in the United States, Canada, and Argentina, with Nevada brine and Quebec spodumene feeding North American conversion capacity. Raw material dependencies span sulfuric acid for leaching, reagents for electrochemical purification, and natural gas or hydroelectric power for thermal processing. Tariff exposure on imported spodumene concentrate from Australia and Brazil creates supply chain risk. Distribution runs through direct sales channels for automaker offtake, with distributors serving residual industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Battery-grade lithium hydroxide specifications are hardening as nickel-rich cathode chemistries displace lower-performance alternatives.
For Market Incumbents: To counter direct extraction technology disruption, Albemarle and Arcadium Lithium should deepen captive brine reserve positions in Nevada while accelerating selective absorption pilot deployments. Securing EPA pre-permitted expansion footprints ahead of competitor environmental review cycles provides defensive moat extension.
For New Entrants and Emerging Players: Automaker joint venture partners represent the most penetrable channel for unqualified refiners seeking first offtake validation. Quebec hydroelectric-powered conversion offers white-space entry with carbon intensity differentiation for European OEM procurement. Target grid-scale battery storage developers as secondary demand anchor with shorter qualification cycles than automotive.
For Investors and Strategic Acquirers: Roll-up economics work for spodumene conversion specialists because the James Bay development pipeline fragments ownership across junior miners lacking standalone refining capital. Five-to-ten-year viability hinges on IRA domestic content rule persistence. Acquisition target archetype: Quebec-based converters with hydroelectric power purchase agreements and pending automaker qualification. Watch FERC interconnection rule synchronization with battery storage deployment as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Assets | Captive Nevada feedstock secures IRA compliance premiums for Detroit automaker contracts. |
| Direct Extraction Technology Deployment | Selective absorption pilots in Clayton Valley compress production timelines versus solar evaporation. |
| Quebec Hydroelectric Refining Expansion | Low-carbon lithium hydroxide output captures European automaker procurement differentiation. |
| Long-term Offtake Contracting | Five-to-ten-year agreements with cell manufacturers lock in capacity ahead of competitor startup. |
| Battery Recycling Feedstock Integration | Black mass processing qualifies under IRA domestic content calculations for secondary lithium supply. |
Research Approach
Coverage spans the United States, Canada, and Argentina, with primary inputs from each lithium production jurisdiction. The approach combines executive interviews with refinery operations directors, automaker cell procurement leads, and Quebec provincial mining regulators with secondary validation from EPA permitting databases, SEC 10-K extraction disclosures, and FERC interconnection filings. Bottom-up capacity modeling and top-down demand triangulation from electric vehicle production forecasts cross-validate volume estimates.
Granularity-level modeling disaggregates the analysis window by product type, application purity tier, and end-user procurement scale. Segmentation dimensions include lithium hydroxide versus carbonate grade splits, battery production versus industrial application revenue allocation, and automotive OEM versus grid storage developer demand patterns. CAGRs derive from compound annual trajectory fitting across the projection horizon. Forecast inputs incorporate IRA domestic content bonus credit qualification thresholds and EPA permitting timeline distributions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to direct extraction technology maturation and Quebec spodumene mine development delays. Model assumptions reflect automaker platform electrification commitments and provincial environmental assessment process durations. A model refresh is warranted upon material change in IRA domestic content rule interpretation or FERC storage interconnection queue processing rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Silicone Potting Compounds Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Compounding Systems Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Thionyl Chloride Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Solketal Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market