
 Radiant Barriers and Reflective Insulation Market | 2026-2036
Radiant Barriers and Reflective Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Radiant Barriers and Reflective Insulation Market Analytics
Multi-layer metallized film lamination is narrowing the performance gap between commodity reflective insulation and advanced aerogel composites. Reflectix Inc. leverages captive extrusion capacity to control substrate quality across North American distribution. Innovative Insulation Inc. anchors its position through specialized contractor training programs that lock in specification loyalty. Fi-Foil Company Inc. differentiates via proprietary perforated vapor-venting designs that extend product applicability into humid climate zones.
Radiant barriers and reflective insulation comprise low-emissivity surface materials—typically aluminum foil or metallized polymer films bonded to kraft paper, polyethylene bubbles, or oriented strand board—that block radiant heat transfer by reflecting thermal radiation rather than absorbing it. These systems achieve emissivity ratings below 0.05 and primarily reduce summer heat gain in attic assemblies, cutting air-conditioning loads. Foil insulation dominates existing-home retrofit channels where lightweight, roll-form installation minimizes labor. Residential applications represent the deepest demand pool, though commercial warehousing is expanding fastest as logistics operators pursue warehouse roof thermal management. Aluminum-based materials command the largest volume share, while polyethylene bubble laminates capture margin pools in DIY retail.
US builders face IECC and ASHRAE 90.1 envelope performance mandates that effectively require radiant barrier compliance in climate zones 1-3. EPA ENERGY STAR certification programs and DOE Building America research partnerships further validate product performance claims for consumer acceptance. Stakeholders must monitor evolving state-level stretch codes in California and Washington that may mandate lower emissivity thresholds or require whole-building energy modeling rather than prescriptive compliance paths.
Market Dynamics
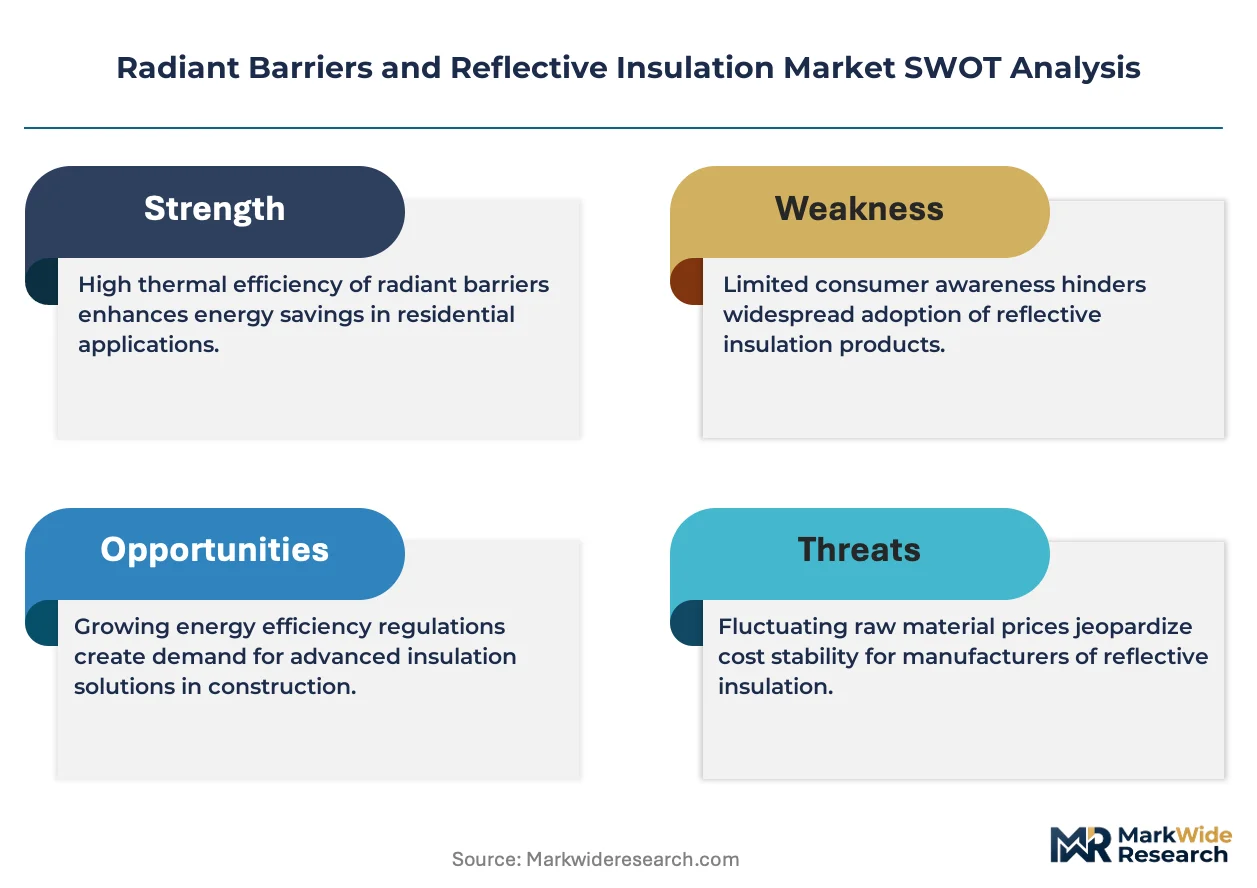
Residential builders in cooling-dominated climates face mounting pressure to meet IECC thermal envelope mandates without ballooning material costs, forcing specification shifts toward aluminum-foil radiant barrier systems that deliver compliance at lower installed expense than foam-based alternatives.
Growth Catalysts
- IECC Climate Zone 1-3 Mandates:ASHRAE 90.1 envelope performance requirements in the southern United States effectively compel radiant barrier installation in new residential construction, creating pull-through demand for foil-faced attic assemblies.
- Polyethylene Bubble Laminates:Lightweight roll-form products are capturing retrofit channel volume in existing-home markets where labor minimization drives contractor preference.
- Texas-Florida-Arizona Concentration:Cooling-dominated electricity load profiles in these states maximize payback periods for reflective attic systems, accelerating builder specification.
Market Restraints
- Aluminum Input Volatility:Primary aluminum price swings transmitted through foil laminators compress margin stability for composite manufacturers serving price-sensitive residential segments.
- Humid Climate Performance Limits:Unperforated radiant barrier designs face condensation risk in Gulf Coast moisture regimes, restricting addressable market without vapor-venting engineering.
- Fiberglass Batt Substitution:Conventional insulation retains code compliance pathways in climate zones 4-8, limiting radiant barrier penetration in heating-dominated northern states.
Strategic Opportunities
- Commercial Warehousing Expansion:Logistics operators pursuing roof thermal management in fulfillment centers represent an underpenetrated vertical with faster specification cycles than residential construction.
- California Stretch Code Trajectory:State-level energy codes may mandate lower emissivity thresholds, creating premium tier demand for advanced metallized film laminates.
- DIY Retail Channel Development:Big-box home improvement chains offer margin capture potential for bubble-film products targeting homeowner self-installation in retrofit markets.
Industry Challenges
- Contractor Training Requirements:Proper installation of perforated vapor-venting designs demands specialized knowledge that remains unevenly distributed across regional installer bases.
- Emissivity Certification Timelines:Third-party validation of sub-0.05 emissivity claims for new laminate formulations extends product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiant Barriers and Reflective Insulation Market |
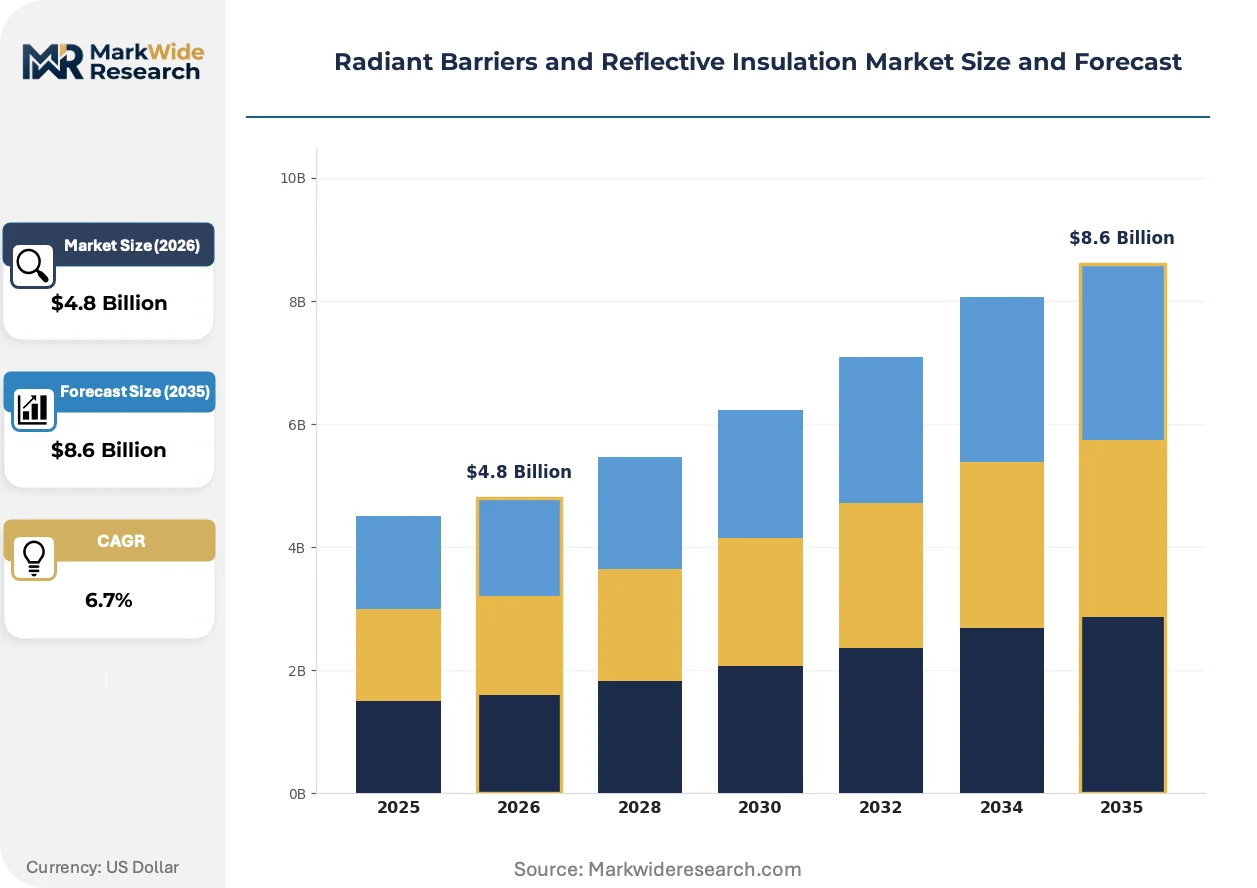
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foil Insulation, Radiant Barriers, Reflective Foils, Insulating Sheathing Application: Residential, Commercial, Industrial, Warehousing Material: Aluminum, Polyethylene, Fiberglass, Foam Board Installation Type: Attic, Walls, Roofs, Under Floors |
| Companies Covered | Reflectix Inc., Innovative Insulation Inc., Fi-Foil Company Inc., Dunmore Corporation, Patidar Corporation, Covertech Flexible Packaging, Spunchem International, Advanced Technical Laminates Manufacturing, RadiantGUARD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiant Barriers and Reflective Insulation Market Evolving Landscape
Multi-layer metallization techniques are compressing the performance hierarchy between commodity reflective insulation and advanced thermal barriers, while regulatory pressure on building envelope efficiency intensifies specification scrutiny across southern US construction markets.
Metallized polymer films with nano-scale aluminum deposition are collapsing the cost-performance tradeoff that previously separated basic radiant barriers from aerogel-composite systems. Residential builders in Texas and Florida are specifying these laminates at accelerating rates for attic ridge and rafter applications. The technology is collapsing installed cost premiums for high-performance thermal envelopes, enabling code compliance without foam insulation price exposure.
EPA ENERGY STAR certification programs and DOE Building America research partnerships are tightening performance validation requirements for reflective insulation products entering the residential channel. Manufacturers must now submit third-party emissivity testing and long-term durability data to maintain program eligibility. Southern US builders dependent on ENERGY STAR compliance for mortgage eligibility are screening supplier portfolios against these tightened standards.
Specification decisions are consolidating around whole-building energy modeling rather than prescriptive component compliance, shifting buyer power toward general contractors with in-house simulation capability. Regional production builders in Arizona are internalizing energy modeling functions that previously outsourced to specialized consultants. This capability concentration is visible most acutely in Phoenix and Tucson metropolitan construction markets where utility rebate programs reward modeled performance over material prescriptions.
Radiant Barriers and Reflective Insulation Market Segmentation
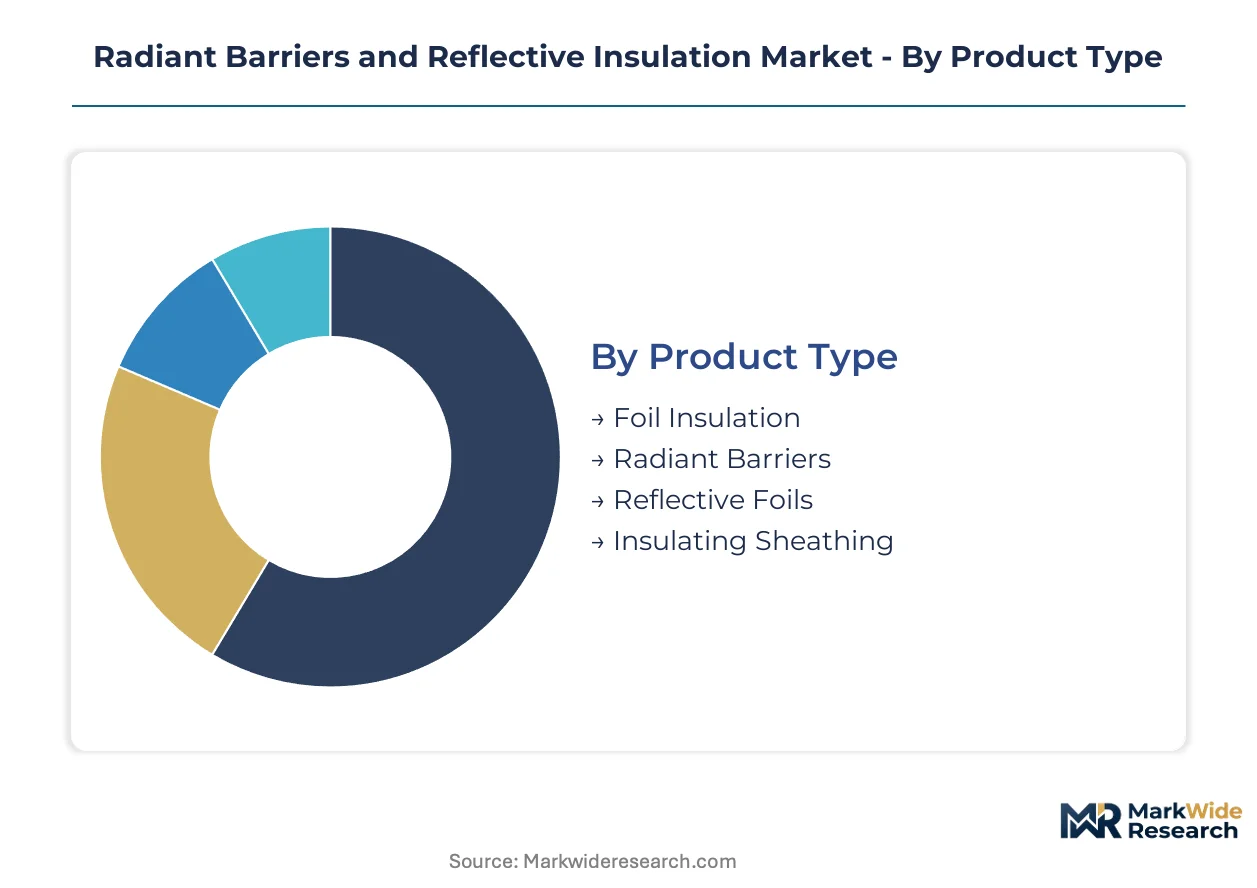
Radiant barrier specification cycles vary dramatically by product format and installation channel, with roll-form retrofit products turning inventory faster than engineered sheathing systems. Understanding these velocity differentials helps manufacturers allocate extrusion capacity and distributor incentives across divergent demand rhythms.
Product Type:
Foil insulation and radiant barriers move through distribution on fundamentally different replenishment cycles, with commodity roll goods restocking monthly while laminated sheathing ties up working capital across quarterly project timelines.
- Foil Insulation:Aluminum-foil composites bonded to kraft paper or polymer substrates deliver sub-0.05 emissivity ratings in lightweight roll formats. Texas and Florida residential retrofits drive the highest velocity through HVAC contractor channels where summer cooling loads accelerate replacement decisions.
- Radiant Barriers:Perforated and unperforated attic-grade laminates engineered for rafter and ridge applications dominate new construction specifications. Arizona production builders specify these systems at accelerating rates to meet IECC climate zone 2-3 envelope mandates without foam insulation cost exposure.
- Reflective Foils:Metallized polymer films with nano-scale aluminum deposition narrow the performance gap against aerogel composites at commodity price points.
- Insulating Sheathing:Rigid foil-faced panels integrated with OSB or gypsum substrates carry the longest specification cycles due to structural engineering review requirements.
Foil insulation dominates installed base. Radiant barriers are where expansion concentrates.
Application:
Cost tier stratification separates residential retrofit demand from commercial warehousing procurement, with homeowner self-installation at big-box price points sitting far below engineered logistics facility specifications.
- Residential:Single-family attic retrofits and new construction specifications represent the deepest demand pool, with cooling-dominated southern states maximizing energy payback calculations for reflective systems.
- Commercial:Office and retail envelope upgrades follow longer capital planning cycles tied to lease rollover schedules and utility rebate program windows.
- Industrial:Manufacturing facility roof retrofits prioritize durability over emissivity performance, favoring heavier-gauge aluminum laminates.
- Warehousing:Fulfillment center operators pursue roof thermal management at accelerating rates, with faster specification cycles than residential construction as logistics real estate competes on operating cost metrics.
Residential applications anchor volume. Warehousing is climbing the fastest.
Material:
Supply concentration around aluminum smelter networks in the southern United States shapes regional manufacturing footprints more than polyethylene extrusion capacity.
- Aluminum:Primary and secondary foil rolling capacity concentrates near Tennessee and Kentucky smelter corridors, with laminators co-locating to minimize coil freight.
- Polyethylene:Bubble-film extrusion for DIY retail channels runs on commodity resin contracts with less geographic lock-in than metallized film production.
- Fiberglass:Hybrid systems combining reflective surfaces with batt substrates compete on thermal bridging performance rather than pure emissivity.
- Foam Board:Foil-faced rigid insulation carries the highest material cost per R-value but integrates structural sheathing functions.
Aluminum commands volume leadership. Polyethylene captures margin in retail.
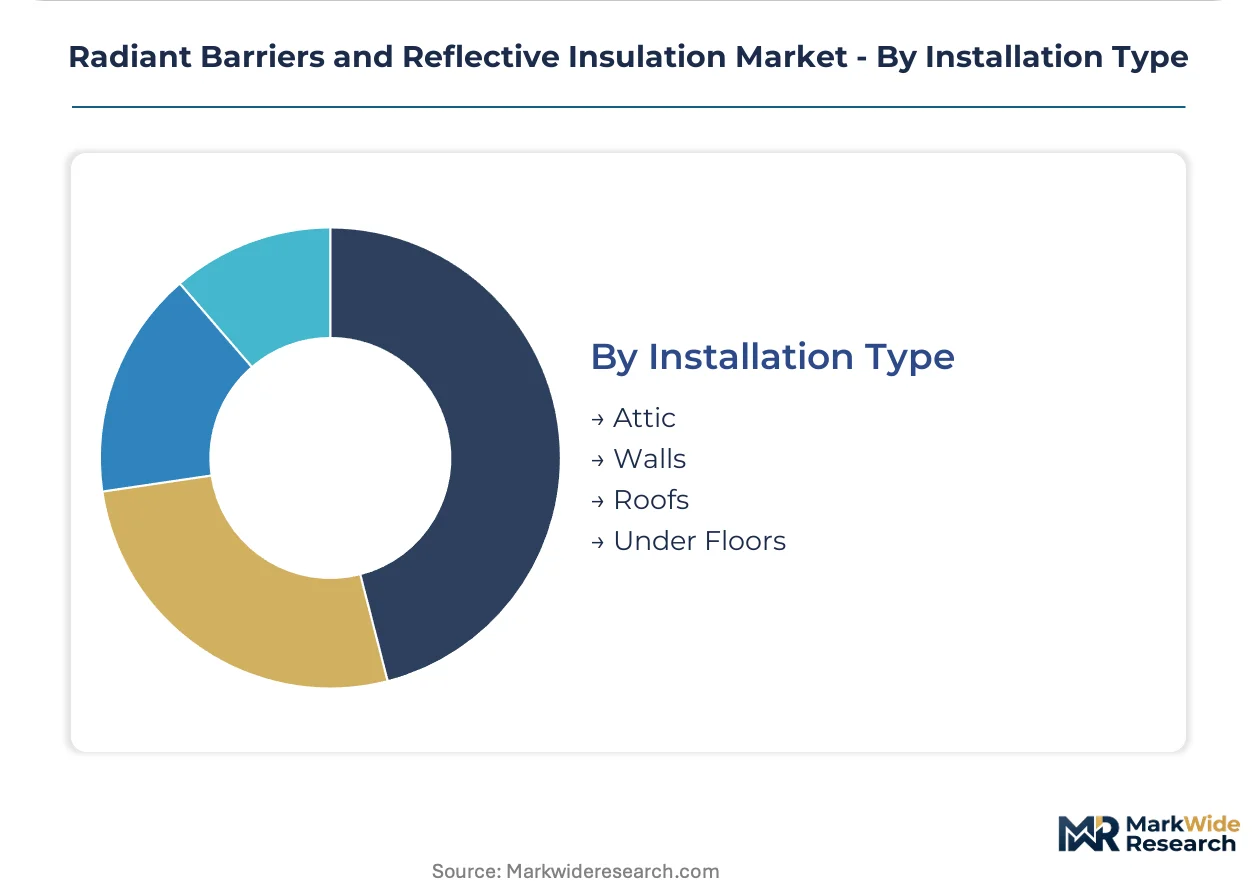
Installation Type:
Application geometry determines labor content and contractor skill requirements, with attic installations completing in hours while under-floor systems demand crawl-space access protocols.
- Attic:Ridge and rafter applications dominate specification, with perforated vapor-venting designs extending addressable market into Gulf Coast humidity regimes.
- Walls:Exterior sheathing integration competes against conventional insulation on thermal bridging metrics rather than radiant heat transfer alone.
- Roofs:Deck-applied systems below roofing membranes require coordination with roofing contractors, extending project timelines.
- Under Floors:Crawl-space applications in humid climates face condensation risk without adequate ground vapor barriers.
Attic systems dominate current deployment. Wall integration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese metallized film producers export roll-stock laminates to Southeast Asian fabricators serving Australian and Middle Eastern construction markets. This trade corridor channels commodity-grade reflective insulation toward cooling-dominated climates where IECC-equivalent thermal mandates are emerging.
United States
Southern residential builders in Texas and Florida specify perforated radiant barriers for attic ridge applications to satisfy IECC climate zone 1-3 envelope requirements. EPA ENERGY STAR certification programs validate sub-0.05 emissivity claims for consumer-facing products. Phoenix and Tucson production builders internalize whole-building energy modeling to capture utility rebate incentives.
Australia
Queensland and Western Australia warehouse operators pursue roof thermal management systems as fulfillment center operating costs drive specification. The country's national building code regulator mandates minimum R-value performance for commercial envelope assemblies. Perth metropolitan construction markets concentrate demand for lightweight retrofit roll-form products.
China
Guangdong and Zhejiang province laminators supply metallized polymer films to Southeast Asian fabricators serving tropical climate construction. MIIT industrial standards govern aluminum deposition thickness for thermal performance claims. The Yangtze River Delta hosts extrusion capacity co-located with foil rolling corridors.
Saudi Arabia
NEOM and Riyadh gigaproject developers specify reflective roof systems to reduce cooling loads in extreme desert climates. The national building code regulator mandates thermal envelope performance for commercial and residential structures. Eastern Province petrochemical complexes supply polyethylene resin for bubble-film laminates.
Germany
Baden-Württemberg industrial facility operators retrofit warehouse roofs with foil-faced systems to meet EU Green Deal energy efficiency trajectories. REACH chemical regulations govern adhesive formulations in composite manufacturing. Stuttgart-area technical laminators develop multi-layer metallization for premium-tier building envelope applications.
Radiant Barriers and Reflective Insulation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price bands. The vendor base fragments between captive-extrusion manufacturers and toll-lamination service providers. Three archetypes dominate: vertically integrated film producers, specialized contractor-training outfits, and toll-coating operators serving private-label brands. Capacity expansion and proprietary perforated-design engineering constitute the dominant competitive moves.
Among North American specialists, Reflectix Inc. and Fi-Foil Company Inc. occupy positions within the channel-controlling tier, while Innovative Insulation Inc. exemplifies the contractor-loyalty archetype through training-program investment. These three entities represent distinct strategic postures without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| Reflectix Inc. |
| Innovative Insulation Inc. |
| Fi-Foil Company Inc. |
| Dunmore Corporation |
| Patidar Corporation |
| Covertech Flexible Packaging |
| Spunchem International |
| Advanced Technical Laminates Manufacturing |
| RadiantGUARD |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta metallized film cluster anchors global reflective insulation substrate supply, with Guangdong and Zhejiang province laminators translating raw aluminum coil availability into downstream pricing leverage for North American distributors.
Pricing Analysis
Multi-layer nano-deposition laminates command premium positioning against commodity single-layer foil composites, while bubble-film polyethylene products occupy economy tiers in DIY retail channels. Pricing stratifies across premium, standard, and economy tiers based on emissivity certification grade and volume procurement scale. Cost compression in standard-grade attic barriers is intensifying because primary aluminum volatility transmits directly through toll-lamination contracts. Residential retrofit contractors exhibit highest price sensitivity, while commercial warehousing procurement teams prioritize thermal performance metrics over unit cost.
Supply Chain Analysis
Extended payment terms from Southeast Asian fabricators to Australian and Middle Eastern distributors have become standard working capital practice across the metallized film trade corridor. Raw material supply concentrates in China, the United States, and Saudi Arabia, drawing from primary aluminum smelting, polyethylene resin production, and kraft paper pulping respectively. The supply chain rests on aluminum coil rolling capacity co-located with Tennessee and Kentucky smelter corridors. Single-source vulnerability around Chinese metallized film exports creates structural exposure to tariff escalation. Distribution runs through HVAC contractor channels in residential retrofit markets and direct specification relationships with production builders in new construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against spray-foam insulation and advanced aerogel composites, with incumbent laminators vulnerable to building envelope technology shifts that bypass radiant heat transfer physics entirely.
For Market Incumbents: Pre-empt spray-foam substitution by accelerating perforated vapor-venting product lines that extend addressable market into Gulf Coast humidity regimes. Lock in specification loyalty through expanded contractor certification programs that create switching costs for production builders. Backward integration into captive aluminum foil rolling capacity insulates margin stability from London Metal Exchange volatility.
For New Entrants and Emerging Players: Build out commercial warehousing fulfillment center specialization, where logistics operators pursue roof thermal management at faster specification cycles than residential construction channels. Target underpenetrated industrial facility retrofit markets in EU Green Deal compliance corridors where foil-faced systems meet energy efficiency trajectories. Anchor go-to-market strategy around whole-building energy modeling partnerships that align with Arizona and California builder procurement evolution.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because IECC climate zone mandates and ASHRAE 90.1 envelope requirements create structural demand pull-through regardless of commodity aluminum cycles. Acquisition targets should display captive extrusion capacity and EPA ENERGY STAR certification maintenance. The signal to watch is California stretch code trajectory toward lower emissivity thresholds, which would compress margin pools for commodity laminators while expanding premium-tier addressable market.
| Strategic Initiative | Industry Significance |
|---|---|
| Perforated Vapor-Venting Product Line Expansion | Extends Fi-Foil's Gulf Coast specification reach beyond condensation-limited unperforated designs. |
| Captive Aluminum Foil Rolling Capacity Addition | Reflectix's Tennessee corridor integration insulates margin stability from LME price transmission. |
| Contractor Certification Program Scaling | Innovative Insulation's training investment locks production builder loyalty through installation expertise scarcity. |
| Commercial Warehousing Direct Sales Force Buildout | Captures logistics real estate procurement cycles faster than residential construction channel development. |
| Multi-Layer Nano-Deposition R&D Partnership | Collapses cost-performance gap against aerogel composites for California stretch code premium tier. |
Research Methodology
A standing panel of production builder procurement directors, HVAC contractor business owners, metallized film plant managers, and EPA ENERGY STAR program administrators provided ongoing calibration across the primary research phase. Secondary validation drew from IECC code development records, ASHRAE 90.1 compliance documentation, DOE Building America research publications, and aluminum industry trade association shipment data. Bottom-up volume modeling triangulated against top-down construction spending allocation to ensure segment-level consistency.
Scenario-bracketing framed low, baseline, and high cases around regulatory adoption speed for stretch codes and aluminum price volatility bands. Segmentation modeling spanned product format, installation channel, application vertical, and climate zone regulatory cluster across the projection horizon. CAGRs derived from installation volume trajectories indexed to residential construction permit data and commercial square footage completion rates. Forecast inputs included utility rebate program expansion schedules and metallized film capacity commissioning timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese export-oriented laminators would shift outcomes toward price erosion scenarios. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Basalt Rock Market
Building Materials
Qatar Cement Market
Building Materials
Poland Architectural Coatings Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
North America Architectural Coatings Market
Building Materials
South Africa White Cement Market
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
Cladding Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
Aluminum Door and Window Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Brick Adhesive Market
Building Materials
Global Facade Market
Building Materials
Foam Concrete Market