
 North America Residential Ductwork Design Software Market | 2026-2036
North America Residential Ductwork Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Residential Ductwork Design Software Market Analytics
The United States is reshaping capacity for residential construction software tooling, with engineering-technology clusters in Texas and California expanding developer workforces for building-performance applications. Autodesk, Inc. leverages its Revit platform ecosystem to anchor BIM-compatible ductwork workflows across North American architectural practices. Trimble Inc. competes through field-to-office connectivity that sustains contractor loyalty in fragmented HVAC installation markets. Dassault Systèmes SE differentiates via simulation-depth that extends into airflow dynamics and thermal-load validation for high-performance homes.
North America residential ductwork design software comprises digital engineering applications that calculate pressure drops, size distribution networks, and generate fabrication-ready layouts using algorithms compliant with ACCA Manual D and ASHRAE fundamentals. These tools integrate duct geometry with heating and cooling load outputs to prevent energy losses from improper airflow distribution in single-family and multifamily buildings. Cloud-based applications are capturing the fastest expansion as small contractors abandon perpetual-license burdens for subscription flexibility, while BIM compatibility segments command premium positioning where architects and engineers coordinate mechanical systems with structural and electrical disciplines. Standalone software retains a mature installed base among specialized HVAC technicians who prioritize calculation speed over interdisciplinary collaboration.
ASHRAE standards, ACCA Manual D guidelines, and U.S. Department of Energy efficiency regulations collectively mandate documented airflow performance in residential mechanical designs, creating compliance-driven demand for validated calculation engines. The U.S. Environmental Protection Agency's ENERGY STAR certification requirements and Canada's National Energy Code for Buildings further tighten duct-sealing and fan-efficiency thresholds that software must model accurately. Stakeholders must monitor how municipal electrification ordinances in California, Washington, and British Columbia reshape load-calculation assumptions as heat pumps displace fossil-fuel furnaces.
Market Dynamics
The U.S. Department of Energy's escalating efficiency mandates for residential mechanical systems are forcing HVAC contractors to abandon spreadsheet-based duct calculations in favor of automated pressure-loss modeling and ACCA Manual D-compliant algorithms.
Growth Catalysts
- ASHRAE Standard 62.2 ventilation requirements:The U.S. Department of Energy incorporates these air-exchange rates into federal efficiency compliance, mandating documented airflow calculations that manual methods cannot reliably produce.
- Heat pump electrification mandates:Municipal ordinances in California, Washington, and British Columbia are reshaping load-calculation assumptions as fossil-fuel furnace replacements accelerate software procurement for duct resizing.
- Sun Belt construction volume:Texas, Florida, and Arizona residential building permits are concentrating demand for cooling-load complexity tools among regional HVAC contractors.
Market Restraints
- Perpetual-license stranded costs:Established contractors face write-downs on depreciated desktop software assets when migrating to cloud-based subscription models with recurring fee structures.
- Interoperability fragmentation:Proprietary file formats between BIM platforms, load-calculation engines, and fabrication CAM systems force redundant data entry and error-prone manual translation.
- Skilled technician scarcity:The HVAC trade's aging workforce limits absorption of computational design methods among field-installation crews who retain authority over final duct routing decisions.
Strategic Opportunities
- Canadian National Energy Code adoption:Provincial implementation timelines in Ontario and British Columbia create compliance-driven procurement windows for duct-sealing and fan-efficiency modeling tools.
- Multifamily mid-rise electrification:Vertical distribution system complexity in four-to-six-story buildings exceeds rule-of-thumb sizing methods, opening specialized module opportunities.
- API-first platform architecture:Embedded calculation engines that integrate with contractor ERP and dispatch systems are capturing loyalty in fragmented installation markets.
Industry Challenges
- Manual-to-digital workflow conversion:Veteran HVAC designers resist abandoning accumulated judgment-based heuristics for algorithmic outputs they cannot intuitively verify.
- Fabrication-to-field tolerance management:Sheet metal shop output precision conflicts with jobsite modification practices, requiring software to model as-built deviation ranges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Residential Ductwork Design Software Market |
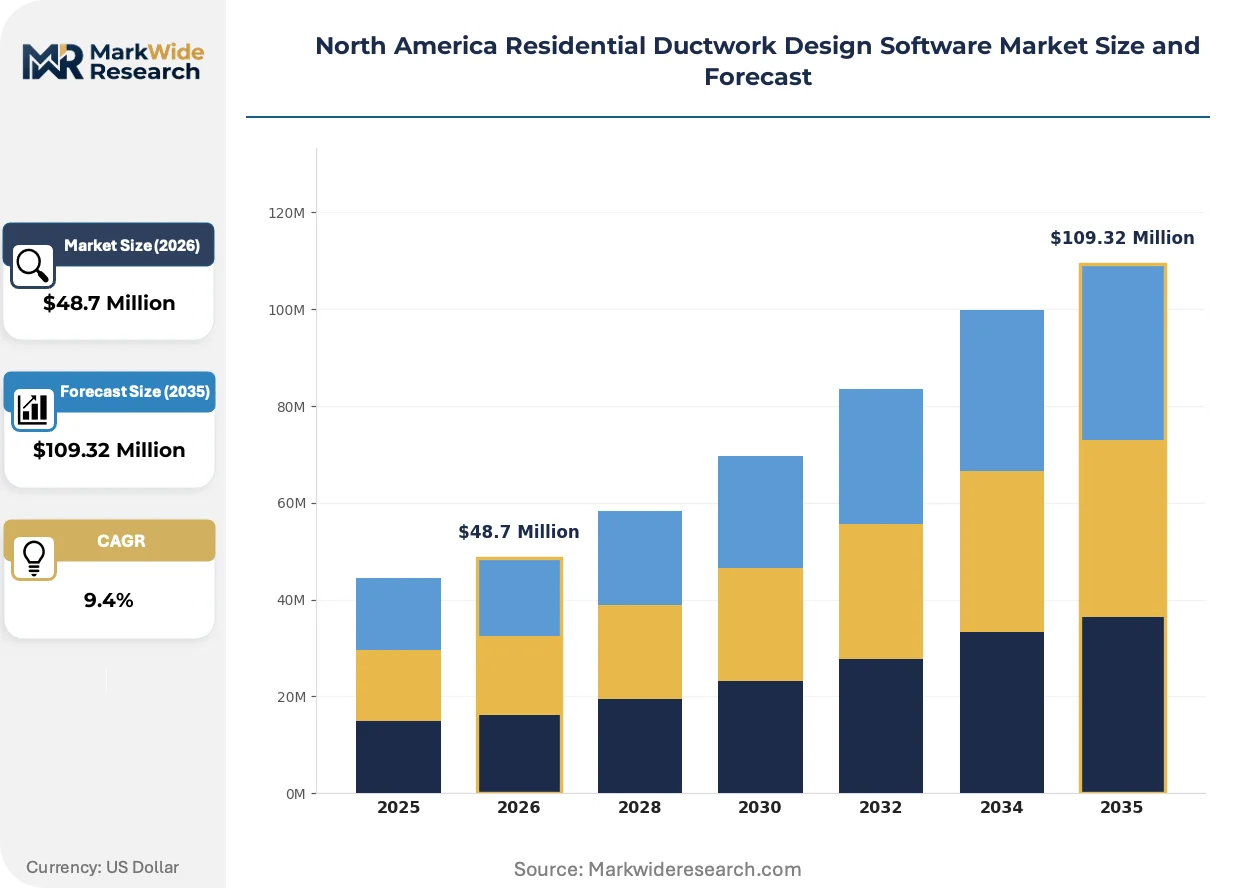
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $109.32 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Integrated Solutions, Cloud-Based Applications, Mobile Applications End User: Architects, Engineers, Contractors, HVAC Technicians Technology: 3D Modeling, Simulation Tools, BIM Compatibility, CAD Software Deployment: On-Premises, SaaS, Cloud Hosting, Hybrid Solutions |
| Companies Covered | Autodesk, Inc., Trimble Inc., Dassault Systèmes SE, Graphisoft SE, Design Master Software, Inc., Bentley Systems, MagiCAD Group, Trane Technologies, CAD International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Residential Ductwork Design Software Market Evolving Landscape
Computational fluid dynamics and generative design algorithms are penetrating residential-scale applications, compressing the expertise gap between specialized engineers and field-practicing contractors.
Parametric duct-layout generators are hybridizing rule-based ACCA Manual D compliance with topology-optimization algorithms that minimize pressure loss across branch configurations. Mid-sized HVAC contractors in Texas and Florida are adopting these tools fastest where cooling-load density justifies subscription costs. The technology is hybridizing traditional fabrication-drawing production with automated spool-sheet generation for plasma-cutting equipment.
The U.S. Environmental Protection Agency's ENERGY STAR Version 3.1 certification requirements are tightening duct-leakage modeling thresholds that software must validate against blower-door test correlations. Manufacturers must now document whole-system airflow distribution accuracy to maintain certification eligibility. High-performance home builders in California and Washington are demanding simulation-depth that extends beyond prescriptive sizing into thermal-load validation.
Subscription-based procurement is displacing perpetual-license ownership among contractor fleets with under twenty technicians. Small installation firms in fragmented Sun Belt markets are abandoning capital-intensive software purchases for monthly SaaS arrangements that bundle automatic code-update downloads. California and Arizona show the steepest adoption curves where municipal permit departments require digital submission of duct-design documentation.
North America Residential Ductwork Design Software Market Segmentation
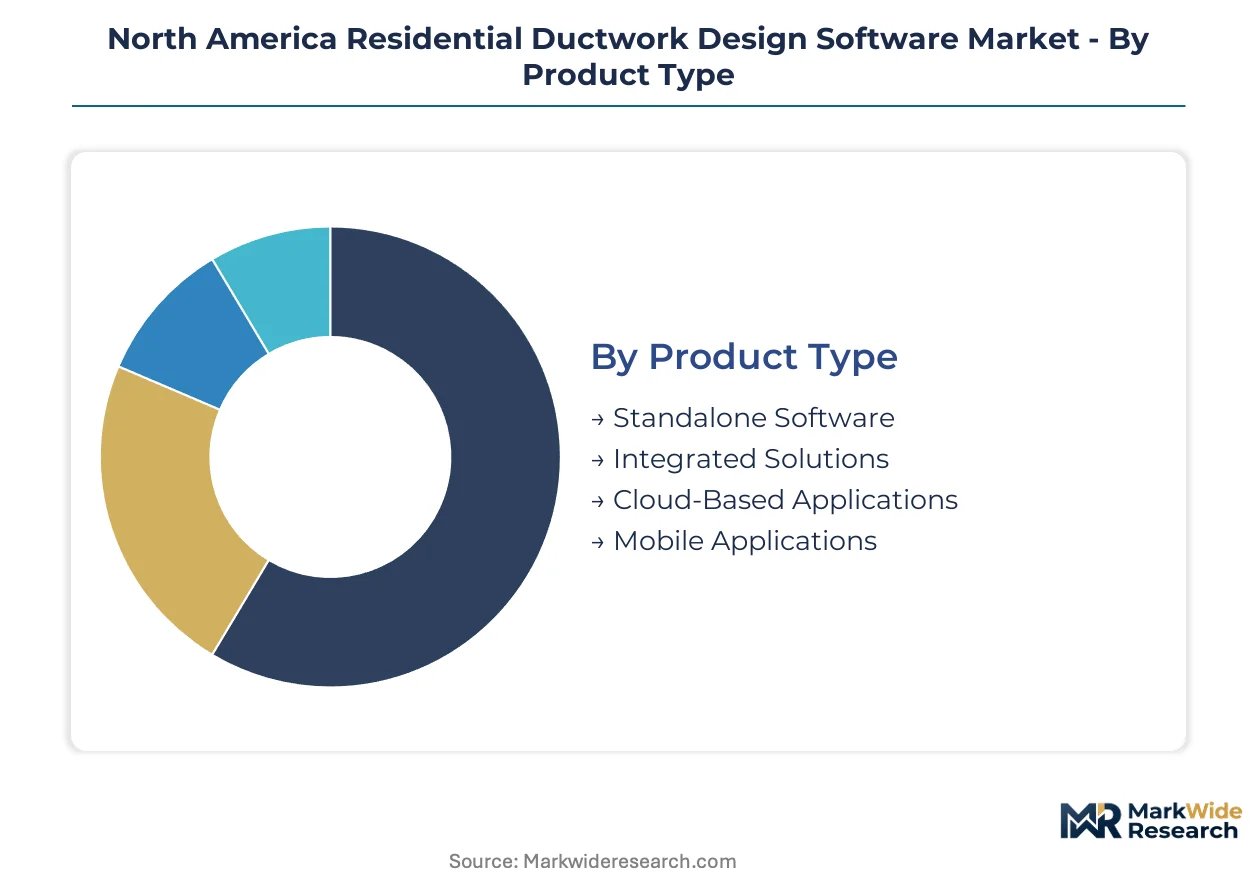
Segmentation in residential ductwork design software reveals how procurement cycles, technical requirements, and compliance pressures fragment demand across distinct user workflows. Understanding these divisions exposes where vendors must differentiate calculation engines versus interoperability features.
Product Type:
Cloud-based applications turn over fastest as contractors abandon depreciated desktop licenses, while standalone software retains the slowest replacement cycles among veteran technicians.
- Standalone Software:Perpetual-license desktop applications prioritize calculation speed for ACCA Manual D compliance without network dependencies. HVAC technicians in Texas and Florida maintain these tools where field connectivity remains unreliable, though municipal permit departments in California and Arizona increasingly reject non-cloud documentation submissions.
- Integrated Solutions:Multi-module platforms combine load calculation, duct sizing, and equipment selection within unified workflows. Engineering-technology clusters in California anchor demand as high-performance home builders require thermal-load validation extending beyond prescriptive methods.
- Cloud-Based Applications:Subscription-hosted tools with automatic code-update delivery.
- Mobile Applications:Tablet-optimized field tools for real-time duct routing adjustments.
Standalone software anchors the volume base while cloud-based applications gain share at the steepest rate.
End User:
Cost tiers separate specification authority from installation execution, with architects and engineers commanding premium positioning against price-sensitive contractor fleets.
- Contractors:Installation firms with under twenty technicians drive SaaS procurement in fragmented Sun Belt markets. Texas and Florida residential building permits concentrate demand where cooling-load complexity justifies monthly subscription costs over capital-intensive perpetual licenses.
- HVAC Technicians:Field-practicing crews retain final authority over duct routing decisions despite software-generated layouts. The aging trade workforce limits absorption of computational methods, creating friction with algorithmic outputs technicians cannot intuitively verify.
- Architects:Design-phase coordinators requiring BIM-compatible mechanical system integration.
- Engineers:Technical specifiers demanding simulation-depth for high-performance home validation.
Contractors dominate procurement volume while HVAC technicians represent the steepest expansion trajectory for training-intensive adoption programs.
Technology:
Application maturity separates established CAD workflows from emerging generative-design capabilities reshaping residential-scale engineering.
- BIM Compatibility:Building information modeling integration enables mechanical system coordination with structural and electrical disciplines. Architectural practices in California and Texas leverage these capabilities where multidisciplinary collaboration prevents field conflicts in complex residential projects.
- Simulation Tools:Computational fluid dynamics and airflow dynamics modeling extend beyond prescriptive sizing. Washington and British Columbia high-performance home builders require these capabilities for ENERGY STAR certification and heat pump electrification compliance.
- 3D Modeling:Spatial visualization for duct geometry and spatial conflict detection.
- CAD Software:Traditional fabrication-drawing production for sheet metal shop output.
CAD software retains the largest installed base while BIM compatibility climbs fastest among architect-engineer coordination requirements.
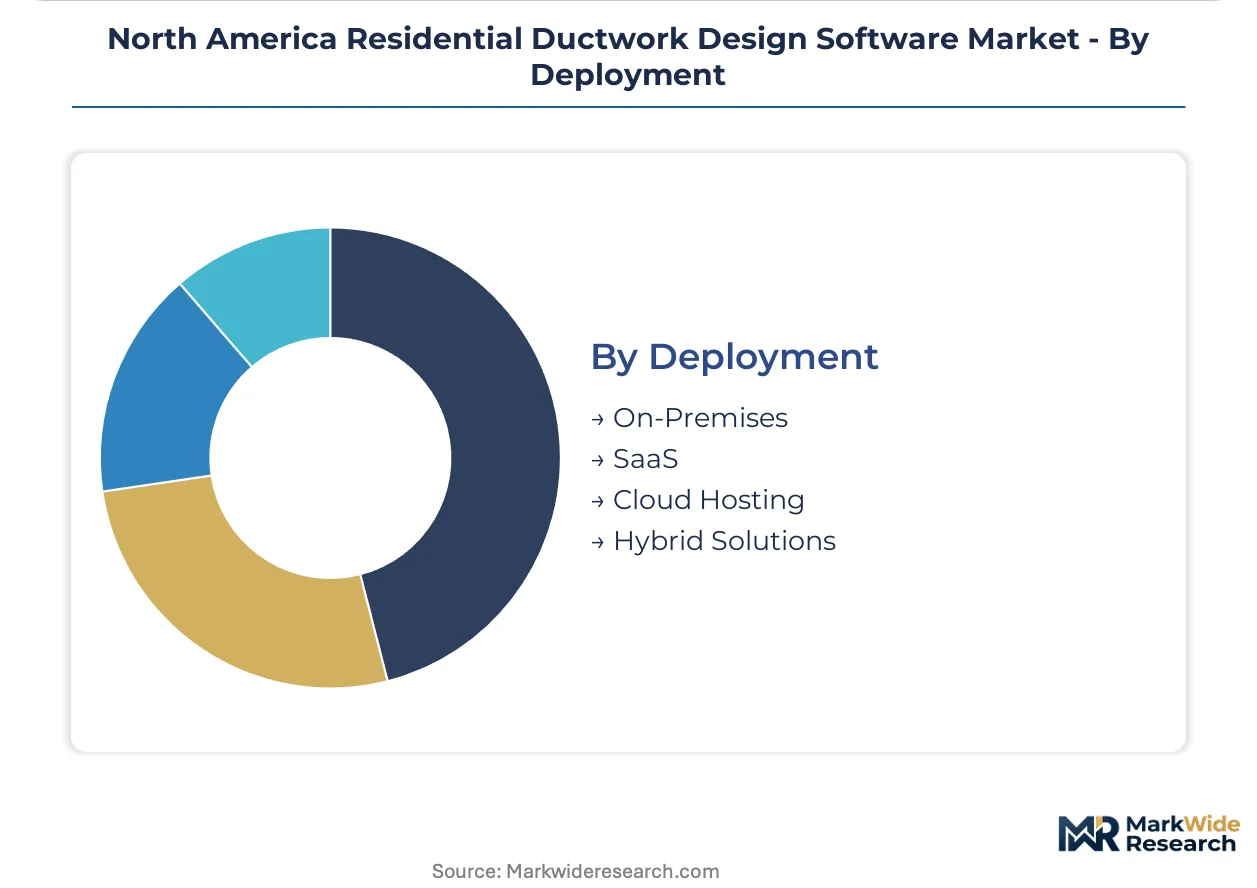
Deployment:
Customer type and geography together determine infrastructure preferences, with municipal digitization mandates accelerating cloud transitions.
- SaaS:Pure subscription models with recurring fee structures and automatic updates. Small contractors in Arizona and California abandon perpetual-license stranded costs fastest where permit departments require digital submission formats.
- Hybrid Solutions:Mixed on-premises calculation with cloud-based collaboration and backup. Mid-sized firms in Texas adopt these configurations to balance field-crew offline functionality with office-based coordination requirements.
- On-Premises:Locally installed software with capital purchase and depreciation schedules.
- Cloud Hosting:Third-party infrastructure for legacy application remote access.
On-premises deployment anchors remaining legacy volume while SaaS expands most quickly across compliance-driven procurement windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-35 corridor freight rail network and cross-border natural gas pipelines anchor North America's residential construction software distribution, with digital design tools flowing through Texas logistics hubs into Sun Belt building markets.
United States
Texas and Florida concentrate cooling-load complexity demand where residential building permits exceed national averages. The U.S. Department of Energy's escalating efficiency mandates for residential mechanical systems pressure contractors toward automated duct sizing. Engineering-technology clusters in Austin and Houston expand developer workforces for building-performance applications serving multifamily mid-rise electrification projects.
Canada
Ontario and British Columbia drive compliance-driven procurement as provincial National Energy Code implementation tightens duct-sealing thresholds. Health Canada's building efficiency coordination with provincial regulators accelerates software validation requirements for ENERGY STAR-equivalent certification. Vancouver's high-performance home builder community demands simulation-depth extending into thermal-load validation for heat pump retrofits.
California
Municipal electrification ordinances in Los Angeles, San Francisco, and San Diego reshape load-calculation assumptions as heat pumps displace fossil-fuel furnaces. The California Energy Commission's Title 24 building standards mandate documented airflow performance that manual methods cannot reliably produce. Silicon Valley engineering-technology clusters anchor BIM-compatible mechanical system development for architect-engineer coordination.
Texas
Houston and Dallas-Fort Worth residential construction volume concentrates demand for cooling-load complexity tools among regional HVAC contractors. ERCOT grid interconnection standards for distributed energy resources influence residential mechanical system design software requirements. Austin's technology corridor hosts expanding developer workforces for cloud-based subscription platforms with automatic code-update delivery.
Florida
Miami-Dade and Orange County building departments increasingly require digital submission of duct-design documentation for permit approval. The Florida Building Commission's adoption of ASHRAE ventilation standards mandates documented airflow calculations. Tampa and Orlando contractor fleets show steep adoption curves for SaaS arrangements that bundle compliance updates.
North America Residential Ductwork Design Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with calculation engines that embed into contractor workflows. The vendor base stratifies across three tiers: multinational CAD-BIM conglomerates with cross-disciplinary coordination capabilities, HVAC-focused software houses with ACCA Manual D compliance depth, and emerging cloud-native entrants attacking subscription price points. Dominant competitive moves include API-first architecture development for ERP integration and strategic partnerships with sheet metal fabrication equipment manufacturers.
Among platform-scale conglomerates, Autodesk, Inc. and Trimble Inc. occupy positions that exemplify the BIM-to-field connectivity archetype, while Dassault Systèmes SE represents the simulation-depth specialization tier with airflow dynamics modeling capabilities. These three entities anchor the competitive structure through divergent technical positioning rather than overlapping functional coverage.
| Leading Market Players |
|---|
| Autodesk, Inc. |
| Trimble Inc. |
| Dassault Systèmes SE |
| Graphisoft SE |
| Design Master Software, Inc. |
| Bentley Systems |
| MagiCAD Group |
| Trane Technologies |
| CAD International |
| Others |
Value Network & Pricing Analysis
Austin's engineering-technology corridor anchors cloud-platform development capacity that feeds downstream pricing power toward SaaS vendors serving fragmented HVAC contractor markets across Texas and Florida.
Pricing Analysis
ASHRAE Standard 62.2 and ACCA Manual D compliance mandates dictate the pricing tier structure across deployment models. Three-tier pricing structure across premium BIM-integrated, standard calculation-engine, and economy mobile-field levels separates architect-engineer coordination tools from technician-grade standalone licenses. Price differentiation rests on certification depth and ERP integration capability. Cost compression in the standalone tier intensifies as municipal permit departments reject non-cloud documentation formats. Small contractors with under twenty technicians exhibit highest price sensitivity, while high-performance home builders in California show lowest sensitivity to simulation-depth premiums.
Supply Chain Analysis
Tariff exposure between the United States and China dominates semiconductor component sourcing for calculation-engine hardware dependencies. Software development capacity concentrates in the United States, Canada, and India, with cloud infrastructure provisioning drawing from hyperscaler data center networks across Virginia, Oregon, and Quebec. Raw material dependencies center on silicon for server hardware, rare earth elements for magnetic storage systems, and copper for data center thermal management. Single-source vulnerability in specialized HVAC engineering talent pools creates recruitment bottlenecks. Distribution runs through direct vendor-to-contractor digital channels and regional HVAC equipment distributors bundling software with mechanical system procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential ductwork design software sits in early-cycle expansion as municipal electrification ordinances in California, Washington, and British Columbia force algorithmic compliance adoption ahead of installed-base replacement curves.
For Market Incumbents: Pre-empt cloud-native entrants by embedding ACCA Manual D calculation engines directly into contractor ERP and dispatch systems through API-first architecture. Consolidate position through strategic partnerships with sheet metal fabrication equipment manufacturers to lock in automated spool-sheet generation workflows. Defend against interoperability fragmentation by supporting open file format standards that reduce redundant data entry friction.
For New Entrants and Emerging Players: Mid-market multifamily mid-rise electrification projects in Ontario and British Columbia represent the most penetrable entry point, as vertical distribution complexity exceeds rule-of-thumb sizing methods and incumbent platforms lack specialized modules. Target small contractor fleets in Arizona and Florida through mobile-first SaaS arrangements that bundle automatic code-update delivery with municipal permit submission compliance. Attack through subscription price points below perpetual-license depreciation recovery thresholds.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-utility play because ASHRAE and DOE efficiency mandates create non-discretionary procurement demand with automatic update revenue visibility. Acquisition target archetype: HVAC-focused software houses with deep ACCA Manual D compliance engines and established technician training programs. Signal to watch: provincial National Energy Code implementation timelines in Canada creating compliance-driven procurement windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architecture embedding calculation engines into contractor ERP systems captures fragmented market loyalty. |
| Strategic Partnership | Fabrication equipment manufacturer alliances lock in automated spool-sheet generation for plasma-cutting workflows. |
| Product Launch | Specialized multifamily mid-rise modules address vertical distribution complexity beyond prescriptive sizing methods. |
| Acquisition of Specialist Firm | HVAC-focused software houses with ACCA Manual D depth fill gaps in simulation-compliance capabilities. |
| Geographic Expansion | Provincial Canadian Energy Code implementation creates compliance-driven procurement windows in Ontario and British Columbia. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with HVAC contractors, mechanical engineers, software platform developers, municipal permit officials, and sheet metal fabrication shop managers. Secondary validation drew from ASHRAE technical standards documentation, ACCA Manual D guidelines, U.S. Department of Energy efficiency regulation filings, Canada National Energy Code provincial implementation schedules, and ENERGY STAR certification requirements. Bottom-up contractor procurement surveys triangulated against top-down platform vendor capacity assessments.
Calibration against historical adoption curves in adjacent construction software categories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, end-user type, technology tier, and regional regulatory cluster. CAGRs were derived from installed-base replacement cycles and new-construction permit volume correlations. Forecast inputs incorporated heat pump electrification mandate timelines and municipal digitization requirements for permit documentation submission.
Macroeconomic conditions sit as an overlay; deviation in residential construction permit volumes, HVAC technician workforce availability, or cloud infrastructure cost trajectories would shift the trajectory. Forecasts reflect documented assumptions about compliance mandate enforcement intensity and software interoperability standard adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Roof Insulation Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
HVAC Blower and Fan Systems Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
Aeration System Market
HVAC Systems
Corrugated Air Duct Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Spray Booth Ventilation System Market