
 Compaction Equipment Market | 2026-2036
Compaction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Compaction Equipment Market Analysis
Intelligent compaction grade with integrated GPS density mapping and accelerometer feedback is reorganizing procurement priorities across municipal and contractor fleets. BOMAG GmbH leverages its OEM telematics platform to sustain aftermarket service attachment rates in European road building. Caterpillar anchors North American rental channel dominance through its Cat Command remote operation architecture. Sany Heavy Industry Co. Ltd competes on manufacturing scale in vibratory roller exports across Asia-Pacific and African markets.
Compaction equipment comprises mechanical systems designed to increase material density through applied force, vibration, or impact, with drum widths typically spanning 500 mm to 2,500 mm and centrifugal forces reaching 400 kN in heavy tandem configurations. These machines serve critical functions in achieving specified proctor densities for subgrade stability, asphalt mat uniformity, and landfill cell integrity. Rollers command the largest installed base among product types due to their versatility across soil and asphalt applications, while trench rollers represent the fastest-expanding category as utility corridor work intensifies in congested urban corridors. Among technology segments, vibratory systems retain the deepest margin pools where aftermarket drum refurbishment and variable frequency controls create recurring revenue streams.
EPA Tier 4 Final emissions standards and EU Stage V regulations from ECHA are forcing engine retrofit cycles and accelerating electric powertrain pilot programs in compactors below 9 metric tons. OSHA noise exposure limits and ISO 2631 whole-body vibration standards shape operator cabin design specifications and ergonomic feature premiums. Stakeholders must monitor battery-electric runtime benchmarks against diesel equivalent compaction output as charging infrastructure deployment determines fleet electrification feasibility.
Market Dynamics
Intelligent compaction systems with real-time density monitoring are compressing traditional equipment replacement cycles as infrastructure resilience mandates from the EU Green Deal and EPA force contractors toward telematics-enabled fleet management.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V emissions frameworks:Regulatory pressure is accelerating engine retrofit demand and pilot deployments of electric powertrains in compactors below 9 metric tons, expanding addressable fleet renewal.
- Urban utility corridor densification:Trench roller demand is accelerating in congested metropolitan infrastructure projects where space constraints favor compact, maneuverable compaction equipment.
- Accelerometer-based density feedback loops:Intelligent compaction grade adoption is reorganizing municipal procurement specifications toward integrated GPS mapping and real-time quality assurance.
Market Restraints
- Diesel engine input cost volatility:Emissions-compliant powertrain components and aftertreatment systems inflate manufacturing costs and compress margin pools on mid-tier equipment.
- Supply concentration in precision sensor manufacturing:GPS density mapping hardware and telematics control modules face concentrated sourcing from specialized electronics suppliers.
- Battery-electric runtime limitations:Current lithium-ion energy density constraints restrict continuous compaction output equivalence to diesel benchmarks in heavy tandem configurations.
Strategic Opportunities
- Landfill cell integrity applications:Waste management operators are expanding compaction equipment specifications for geomembrane protection and leachate control in engineered containment systems.
- EU Green Deal infrastructure resilience funding:Dedicated capital allocation for climate-adaptive road networks is creating procurement preference for intelligent compaction systems with documented density verification.
- Rental channel telematics integration:Equipment rental fleets are unbundling compaction-as-a-service models where usage-based billing replaces outright ownership.
Industry Challenges
- ISO 2631 whole-body vibration certification complexity:Operator cabin redesign timelines extend product development cycles as ergonomic compliance intersects with emissions hardware packaging constraints.
- Legacy fleet telematics retrofit integration:Municipal contractors face capital allocation friction when upgrading installed bases with intelligent compaction sensors and connectivity modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compaction Equipment Market |
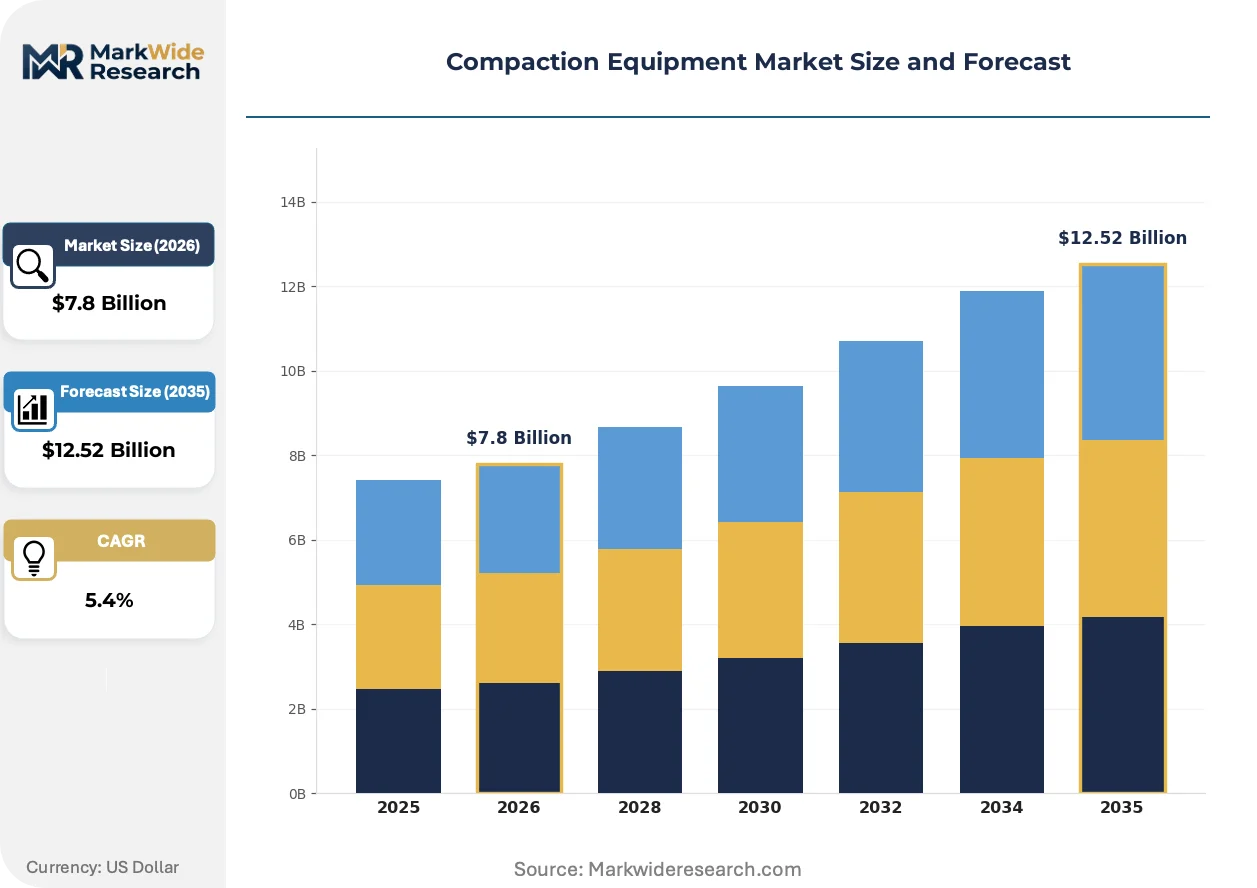
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plate Compactors, Rollers, Rammers, Trench Rollers Technology: Vibratory, Static, Pneumatic, Combination End User: Construction, Road Building, Landscaping, Mining Application: Soil Compaction, Asphalt Compaction, Concrete Compaction, Waste Management |
| Companies Covered | Wacker Neuson SE, Atlas Copco, Caterpillar, XCMG Co. Ltd, Terex Corporation, BOMAG GmbH, Volvo Construction Equipment, Sany Heavy Industry Co. Ltd, Wirtgen Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compaction Equipment Market Emerging Trajectories
Compaction equipment architecture is splitting between premium intelligent-grade systems and cost-optimized mechanical configurations as buyer sophistication polarizes and regulatory documentation requirements tighten.
Variable frequency vibratory control technology is bifurcating the aftermarket service landscape. Drum refurbishment specialists now compete with OEM-authorized service networks for variable amplitude system maintenance. Large contractor fleets in Germany and the United States are adopting predictive drum wear analytics. This technology is compressing third-party parts margins while deepening OEM software lock-in through proprietary accelerometer calibration protocols.
REACH chemical substance restrictions and EU F-Gas Regulation phase-down schedules are reshaping hydraulic fluid formulations and refrigerant selections in operator climate control systems. Equipment manufacturers face reformulation costs across European-bound product lines. Tandem vibratory roller configurations for asphalt mat finishing are most affected, with suppliers accelerating biodegradable hydraulic fluid certification timelines.
Rental fleet operators are consolidating compaction equipment procurement around telematics-enabled utilization tracking. Independent rental houses in the United States are losing share to national platforms with integrated Cat Command or equivalent remote operation architectures. Municipal contractors in Texas and Florida now specify minimum telematics reporting intervals in bid documents, privileging connected equipment suppliers.
Compaction Equipment Market Segmentation
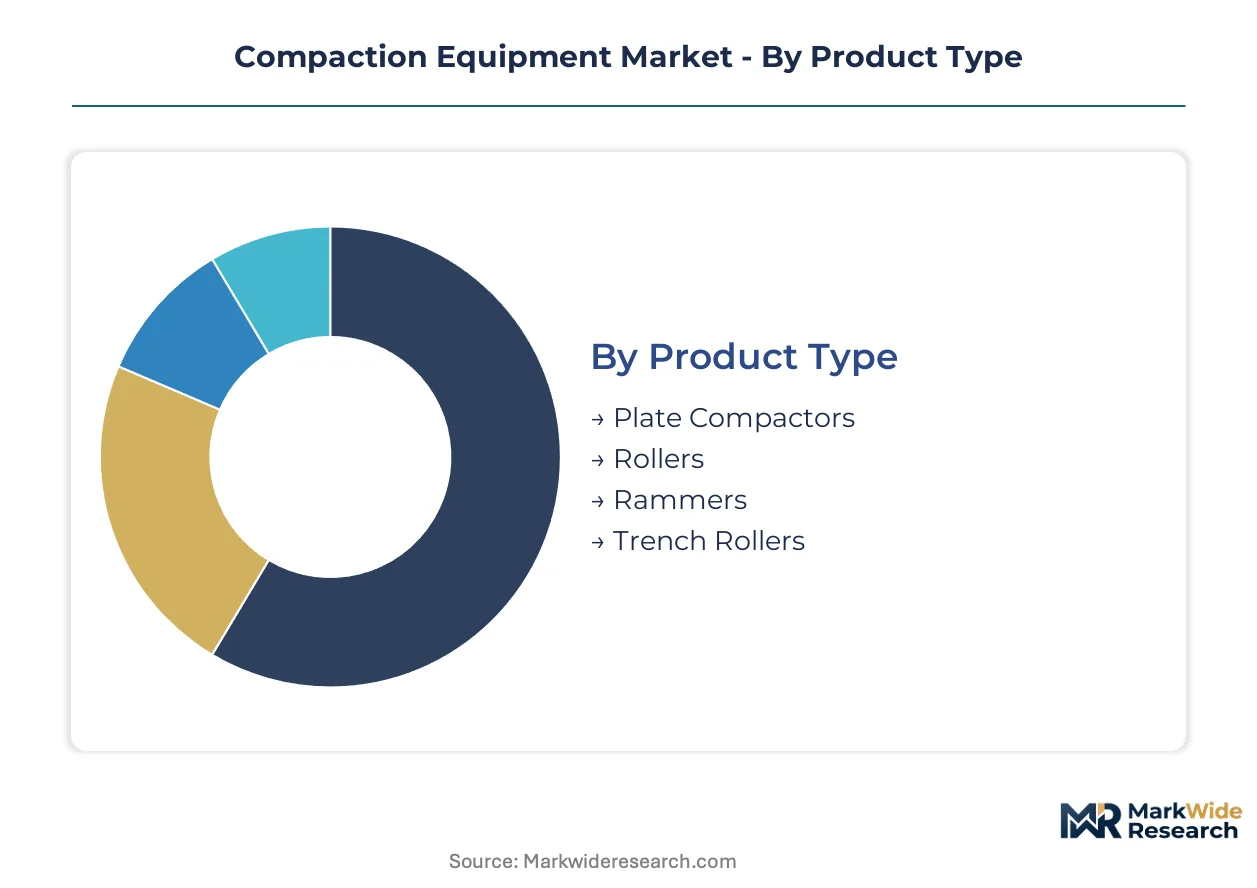
Compaction equipment segmentation reveals distinct procurement patterns across municipal, contractor, and rental fleet channels. Specification requirements diverge sharply between heavy infrastructure projects demanding intelligent-grade systems and utility contractors prioritizing maneuverability in confined corridors.
Product Type:
Rollers dominate domestic fleet renewal cycles in Germany, the United States, and China, while plate compactors and rammers sustain export-led manufacturing from Asia-Pacific assembly hubs.
- Rollers:Tandem and single-drum configurations generate the deepest aftermarket revenue pools through drum refurbishment and variable frequency control maintenance. Demand concentrates in federal highway programs across the United States and EU Green Deal-funded road resilience projects in Germany, where intelligent compaction grade with GPS density mapping is becoming standard specification.
- Trench Rollers:Remote-controlled and walk-behind units are expanding fastest as metropolitan utility corridor work intensifies in congested urban cores. Japanese and South Korean contractors are driving specification upgrades for zero-tail-swing designs in fiber-optic and district heating installations.
- Plate Compactors:Forward and reversible plate designs serve landscaping and small-scale soil compaction across residential construction clusters in Texas, Florida, and Australia's eastern seaboard.
- Rammers:Jumping jack configurations maintain steady replacement demand in trench backfill and foundation perimeter work where vertical compaction depth requirements exceed plate compactor capability.
Rollers hold the largest share; momentum sits with trench rollers.
Technology:
Cost tier differentiation separates premium vibratory systems with accelerometer feedback from static and pneumatic alternatives serving price-sensitive rental channels.
- Vibratory:Variable amplitude and frequency controls enable real-time density optimization through accelerometer-based feedback loops. EPA Tier 4 Final and EU Stage V compliance costs are accelerating electric powertrain pilots in compactors below 9 metric tons, with German manufacturers leading field testing.
- Static:Dead-weight drum configurations persist in landfill cell compaction and specialized geomembrane protection applications where vibration risks membrane integrity. Waste management operators in the United States specify static drum finishes for leachate collection layer protection.
- Pneumatic:Multi-tire configurations deliver kneading action for asphalt mat sealing in airport runway and highway surface course applications.
- Combination:Vibratory-pneumatic hybrid systems command specification premiums in high-profile infrastructure projects requiring documented density verification for warranty compliance.
Vibratory systems capture the dominant revenue position; electric variants are climbing the fastest.
End User:
Application maturity varies sharply, with road building demanding the most sophisticated intelligent compaction documentation while landscaping maintains mechanical-grade preferences.
- Road Building:Federal and state transportation departments in the United States, Germany, and China mandate real-time density monitoring for quality assurance documentation. EU Green Deal resilience funding is accelerating fleet replacement toward telematics-enabled systems.
- Construction:General building foundations and subgrade preparation sustain steady demand across commercial and residential development cycles in Australia, Canada, and the United Kingdom.
- Mining:Haul road maintenance and tailings dam compaction require heavy tandem configurations with 400 kN centrifugal force ratings in Australian iron ore and Chilean copper operations.
- Landscaping:Small-scale plate compactors and rammers serve residential hardscaping and golf course construction where equipment mobility outweighs precision documentation requirements.
Road building commands the largest installed base; mining applications are gaining share fastest.
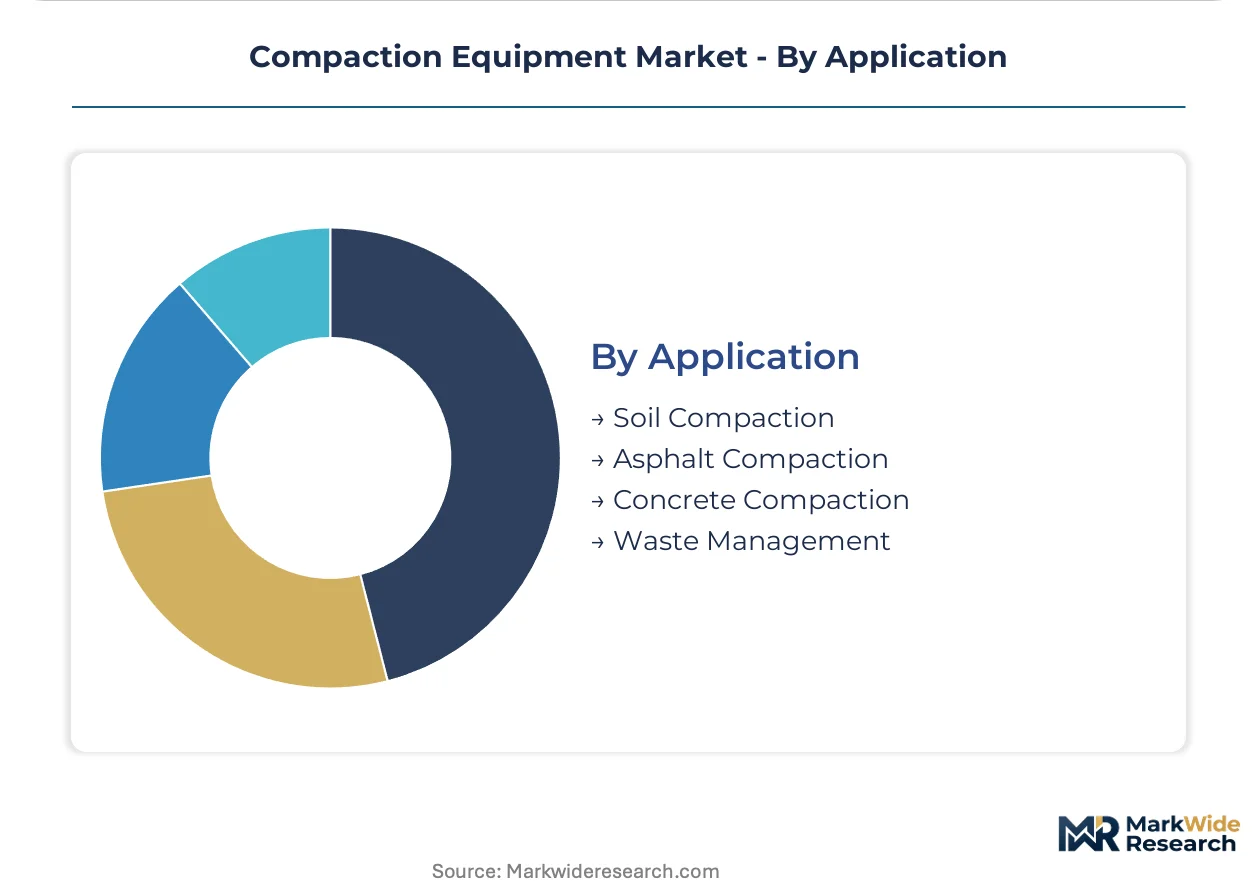
Application:
Volume concentration in soil and asphalt compaction contrasts with emerging specification intensity in engineered waste containment systems.
- Soil Compaction:Subgrade stabilization for building foundations and embankment construction sustains the broadest equipment utilization across geotechnical specification tiers. Proctor density achievement requirements drive vibratory roller specification in German and Japanese civil engineering standards.
- Waste Management:Landfill cell integrity applications are expanding equipment specifications for geomembrane protection, leachate control, and daily cover compaction density. EPA subtitle D regulations in the United States and EU landfill directives are tightening operational documentation requirements.
- Asphalt Compaction:Mat density uniformity and surface finish quality drive tandem vibratory roller deployment in highway and airport runway construction.
- Concrete Compaction:External vibrators and surface finishing equipment serve precast manufacturing and slab-on-grade applications with distinct equipment configurations from soil and asphalt systems.
Soil compaction retains the largest share; waste management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export intelligent compaction systems to North American highway contractors, while Chinese assembly hubs supply vibratory rollers across Southeast Asian and African infrastructure markets.
United States
Federal highway budgets and state transportation department fleet renewals sustain demand for tandem vibratory rollers with GPS density mapping. EPA Tier 4 Final emissions standards accelerate electric powertrain pilots in compactors below 9 metric tons. Municipal contractors in Texas and Florida now specify minimum telematics reporting intervals in bid documents.
Germany
EU Green Deal infrastructure resilience funding creates procurement preference for intelligent compaction systems with documented density verification. ECHA Stage V regulations force engine retrofit cycles and deepen OEM telematics platform adoption. Road building clusters in Bavaria and North Rhine-Westphalia anchor European demand for premium vibratory equipment.
China
Urban densification projects and federal highway expansion sustain vibratory roller fleet renewal at manufacturing scale. MIIT industrial equipment standards and dual carbon goals accelerate battery-electric compaction trials in metropolitan construction zones. Xuzhou-based manufacturing anchors export supply chains for Asia-Pacific and African markets.
Japan
Metropolitan utility corridor work intensifies demand for zero-tail-swing trench rollers in fiber-optic and district heating installations. METI energy efficiency mandates shape procurement specifications for compact equipment below 9 metric tons. Osaka and Nagoya construction clusters drive specification upgrades for remote-controlled compaction systems.
Australia
Haul road maintenance and tailings dam compaction in Western Australian iron ore operations require heavy tandem configurations with 400 kN centrifugal force ratings. ISO 2631 whole-body vibration standards shape operator cabin design specifications for mining contractors. Queensland infrastructure projects sustain demand for soil compaction equipment in embankment construction.
Compaction Equipment Market Vendor Landscape
Listed leaders compete with private specialists across technology tiering and geographic reach, producing a bifurcated structure where premium intelligent-grade systems separate from cost-optimized mechanical configurations. Three archetypes dominate: integrated construction equipment conglomerates with telematics platforms, specialized compaction OEMs with drum refurbishment service networks, and scale-driven fabricants competing on manufacturing throughput. M&A activity concentrates on telematics capability acquisition, while strategic partnerships address battery-electric powertrain development.
Within the premium intelligent-grade tier, BOMAG GmbH and Caterpillar exemplify telematics-anchored competitive positioning. Wacker Neuson SE occupies a specialist position in compact equipment below 9 metric tons. Sany Heavy Industry Co. Ltd anchors the scale-driven export archetype for vibratory roller manufacturing. These three represent distinct strategic postures: European precision-engineering heritage, North American rental channel integration, and Chinese manufacturing scale.
| Leading Market Players |
|---|
| Wacker Neuson SE |
| Atlas Copco |
| Caterpillar |
| XCMG Co. Ltd |
| Terex Corporation |
| BOMAG GmbH |
| Volvo Construction Equipment |
| Sany Heavy Industry Co. Ltd |
| Wirtgen Group |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final and EU Stage V emissions frameworks gate both supplier qualification and price differentiation simultaneously, forcing OEMs to absorb aftertreatment system costs while tiering offerings around telematics capability. Certification compliance separates premium intelligent-grade systems from cost-optimized mechanical configurations, with procurement specifications in Germany and the United States now mandating documented density verification as a price threshold condition.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade and after-sales service bundling, with intelligent compaction systems commanding premiums for GPS density mapping and accelerometer calibration protocols. Cost compression in mid-tier equipment is intensifying because emissions-compliant powertrain components inflate manufacturing inputs. Municipal contractors in Texas and Florida exhibit highest price sensitivity due to budget-constrained fleet renewals, while mining operators in Western Australia show lowest sensitivity given productivity documentation requirements.
Supply Chain Analysis
Strategic stockpiling of precision sensor inventory dominates over just-in-time preferences as GPS density mapping hardware and telematics control modules face concentrated sourcing. Manufacturing draws from Germany, China, and Japan for vibratory drum assemblies, precision electronics, and hydraulic systems respectively. Raw material dependencies include high-strength steel plate, rare-earth magnet components for electric powertrains, and specialized hydraulic fluids. Single-source vulnerability in accelerometer sensor manufacturing poses structural risk. Distribution runs through OEM-authorized dealer networks and national rental platforms with integrated telematics architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compaction equipment market sits in cyclical recovery as federal highway budgets and EU Green Deal infrastructure resilience funding drive fleet replacement waves. Municipal and contractor procurement cycles correlate with transportation appropriations and climate-adaptive road network capital allocation.
For Market Incumbents: Shield installed base relationships through proprietary telematics platform lock-in and accelerated drum refurbishment service network expansion. Battery-electric runtime limitations threaten margin pools in heavy tandem configurations; deepen vertical integration into precision sensor calibration protocols to defend aftermarket revenue streams against third-party parts competitors.
For New Entrants and Emerging Players: Lead with landfill cell integrity applications where EPA subtitle D regulations and EU landfill directives tighten operational documentation requirements and specification intensity outpaces incumbent focus. Waste management operators in the United States represent the most penetrable segment given geomembrane protection and leachate control equipment upgrades. Pursue compaction-as-a-service rental channel partnerships to bypass capital-intensive fleet ownership barriers.
For Investors and Strategic Acquirers: EU Stage V and EPA Tier 4 Final implementation timelines reshape the acquisition landscape toward electric powertrain capability and telematics platform assets. Long-term viability centers on OEMs with demonstrated battery-electric field testing and software-defined compaction system architectures. Acquisition target archetype: specialized compaction OEMs with drum refurbishment service networks and variable frequency control maintenance expertise. Signal to watch: municipal bid document telematics specification thresholds crossing from optional to mandatory.
| Strategic Initiative | Industry Significance |
|---|---|
| Intelligent Compaction System Integration | GPS density mapping and accelerometer feedback satisfy EU Green Deal documentation mandates in German road building. |
| Electric Powertrain Pilot Expansion | Battery-electric compactors below 9 metric tons address EPA Tier 4 Final compliance costs in United States municipal fleets. |
| Aftermarket Drum Refurbishment Network | Variable frequency control maintenance deepens OEM software lock-in against third-party parts competitors. |
| Rental Channel Telematics Partnership | Compaction-as-a-service models unbundle utilization-based billing from outright ownership in Texas and Florida markets. |
| Landfill Cell Integrity Specification Development | Geomembrane protection and leachate control applications expand addressable equipment demand under EPA subtitle D regulations. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal fleet managers, highway contractor procurement leads, OEM aftermarket service heads, and rental channel operations directors. Secondary validation drew from EPA regulatory filings, EU Green Deal implementation documents, SEC equipment manufacturer disclosures, and federal highway budget appropriations records. Bottom-up equipment shipment triangulation against top-down infrastructure spending analysis anchored volume estimates.
Across the analysis window, projections segment by product type, technology grade, end-use application, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle modeling against infrastructure resilience funding trajectories. Key inputs include municipal telematics specification adoption curves, battery-electric runtime benchmark improvements, and landfill cell integrity equipment specification expansion rates.
The analysis sits within stated boundaries; outcomes outside sustained federal highway budget commitment and EU Green Deal capital allocation continuity would require recalibration. Forecasts reflect assumptions regarding emissions regulation implementation timelines and charging infrastructure deployment density. Revision becomes warranted when battery-electric compaction output equivalence to diesel benchmarks crosses commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Compact Electric Construction Equipment Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
Crane Buffer Market
Construction Equipment
Shield Machines Market
Construction Equipment
Cold Planers Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Trailer Winch Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Felling Heads Market
Construction Equipment
Spray Washer Market
Construction Equipment
Backhoe Bucket Market