
 Geotechnical Engineering Market | 2026-2036
Geotechnical Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
Geotechnical Engineering Market Analysis
ISO 14688 soil classification certification is bifurcating the competitive landscape between accredited laboratories and unqualified regional operators. Arup leverages its integrated design-consulting model across major infrastructure corridors. WSP Global Inc. anchors its position through specialized geohazard assessment capabilities in seismically active zones. Jacobs Engineering Group competes by sustaining long-term relationships with government transportation agencies for tunnel feasibility studies.
Geotechnical engineering encompasses the mechanical analysis of soil, rock, and subsurface fluid behavior to assess bearing capacity, settlement rates, and lateral earth pressures for structural support systems. The discipline employs in-situ testing methods such as standard penetration tests and cone penetration tests to characterize ground conditions before foundation design. Foundation engineering currently occupies the largest application share due to relentless commercial and residential high-rise development in dense urban cores. Slope stability is gaining structural prominence as climate-intensified rainfall events trigger more frequent landslide risks across mountainous terrain. Remote sensing technology is displacing traditional manual survey methods, with satellite-based interferometric synthetic aperture radar enabling millimeter-scale ground deformation monitoring at regional scales.
FERC guidelines govern dam safety assessments and levee integrity evaluations that mandate periodic geotechnical instrumentation reviews across United States watersheds. The EPA's brownfield remediation standards require comprehensive site characterization before property redevelopment, directly expanding demand for contaminated land investigation services. ASTM D1586 and D3441 test protocols shape product specifications for drilling equipment and sampling tools sold into North American markets. Stakeholders must monitor how building code adoptions of performance-based foundation design will alter procurement criteria for ground improvement contractors.
Market Dynamics
ISO 14688 soil classification certification is bifurcating the competitive landscape between accredited laboratories and unqualified regional operators, forcing procurement officers to rewrite vendor qualification criteria for site investigation contracts.
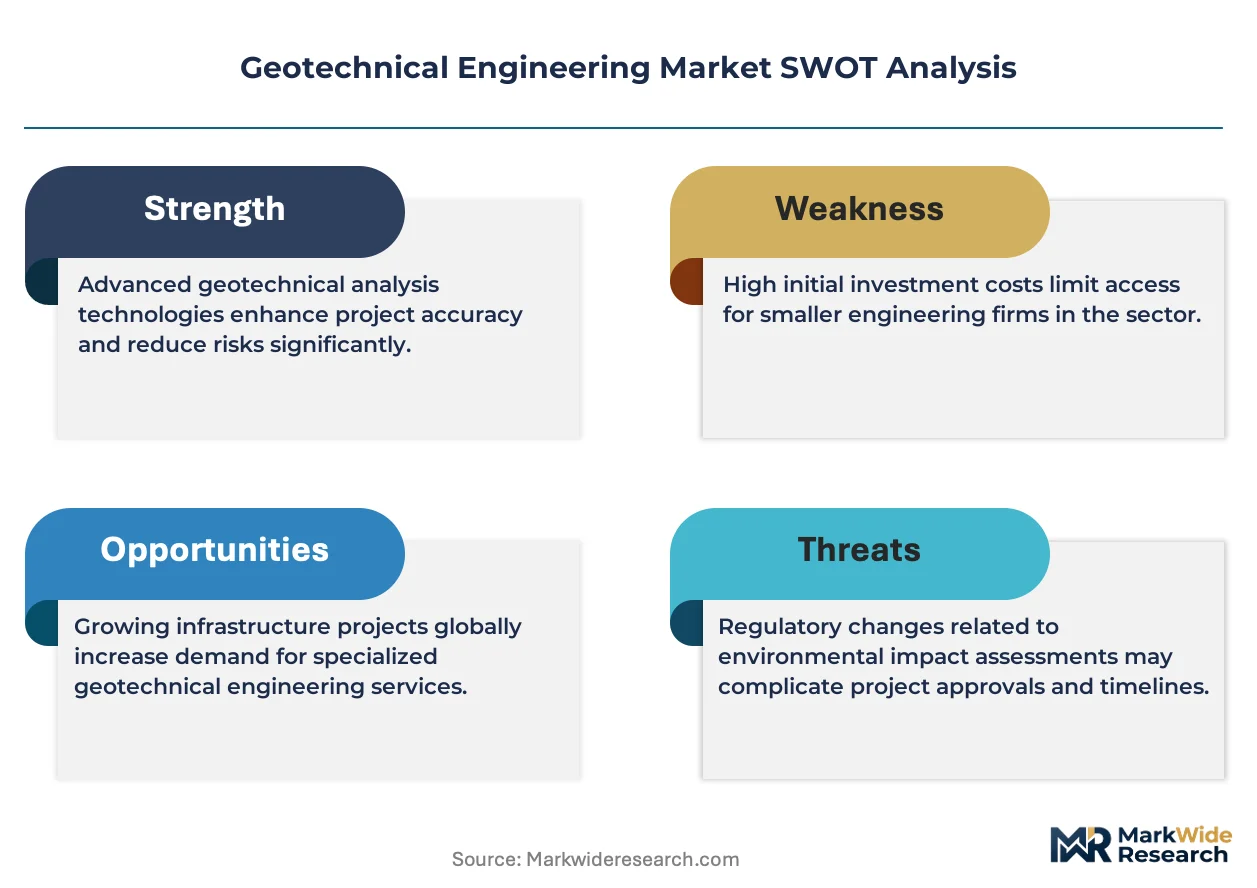
Growth Catalysts
- EU Green Deal soil protection directives:Stricter site investigation mandates across brownfield redevelopment corridors in Germany's Rhine-Ruhr region are expanding mandatory testing volumes for contaminated land assessment.
- Metro rail underground construction:India's accelerating urban transit expansion is driving demand for tunnel boring machine support and ground improvement verification across dense metropolitan cores.
- Interferometric synthetic aperture radar:Satellite-based millimeter-scale deformation monitoring is displacing manual survey crews for regional landslide risk management across mountainous terrain.
Market Restraints
- Specialized drilling equipment import dependency:Cone penetration test rigs and undisturbed sampling tools concentrate manufacturing in Germany and Japan, exposing project timelines to shipping bottlenecks and currency volatility.
- ASTM D1586/D3441 compliance friction:North American test protocol adoption outside the United States remains uneven, fragmenting equipment specification standards and inflating cross-border project engineering costs.
- Geotechnical instrumentation technician scarcity:Certified piezometer installation and inclinometer monitoring specialists are concentrated in legacy infrastructure markets, constraining expansion into emerging construction corridors.
Strategic Opportunities
- Performance-based foundation design codes:Building code adoptions in seismically active zones are opening procurement pathways for ground improvement contractors who can warranty settlement performance rather than prescribe methods.
- Drone-mounted LiDAR convergence with photogrammetry:Rapid site reconnaissance platforms are reducing mobilization costs for preliminary geohazard screening in remote terrain previously deemed uneconomical.
- FERC dam safety instrumentation mandates:Periodic levee integrity evaluation requirements across United States watersheds are institutionalizing recurring revenue streams for automated monitoring system providers.
Industry Challenges
- ISO 14688 accreditation timeline compression:Laboratory certification backlog is delaying project commencement for mid-tier site investigation firms competing against established accredited networks.
- Legacy borehole data integration:Digitization of decades-old paper-based geotechnical logs for machine learning training sets requires specialized geoscience data engineering capacity that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geotechnical Engineering Market |
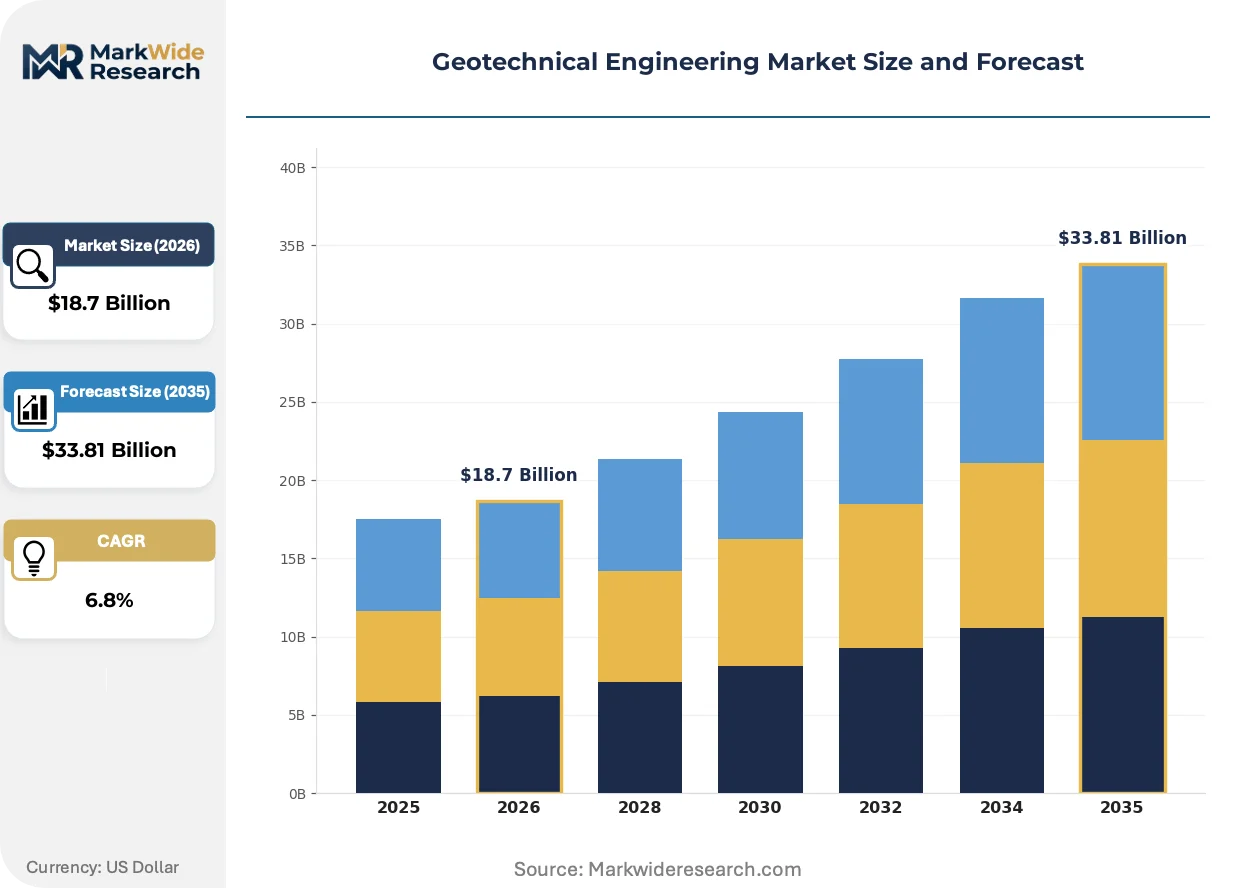
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soil Stabilization, Piling Equipment, Testing Instruments, Geosynthetic Materials Application: Foundation Engineering, Slope Stability, Earth Retention, Mining Operations End User: Construction Companies, Mining Organizations, Government Agencies, Environmental Consultants Technology: 3D Imaging, Soil Analysis Software, Remote Sensing, Geophysical Techniques |
| Companies Covered | Arup, AECOM, Golder Associates, Ramboll, Jacobs Engineering Group, WSP Global Inc., Geosyntec Consultants, Bechtel Corporation, Tetra Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geotechnical Engineering Market Emerging Trajectories
Digital subsurface characterization tools are compressing project timelines while elevating precision expectations. Three interconnected developments are restructuring how ground conditions are assessed and reported.
Automated cone penetration test rigs equipped with real-time pore pressure transducers and seismic velocity modules are displacing traditional split-spoon sampling for deep foundation design in urban high-rise corridors. Transportation agencies in Japan and South Korea now specify continuous profiling methods for expressway embankment verification. The shift is compressing field investigation duration from weeks to days while expanding data density by an order of magnitude.
REACH chemical restriction expansions are phasing out diesel-based drilling fluids in European Union site investigations. Synthetic polymer alternatives are reformulating mud rotary specifications for contaminated land characterization projects. Contractors serving Netherlands and Belgium markets are retooling fluid systems ahead of enforcement deadlines to avoid project suspension.
Subscription-based deformation monitoring services are unbundling capital-intensive instrumentation ownership from operational delivery. Mining operators in Chile and Australia are piloting satellite-InSAR telemetry for tailings dam surveillance without maintaining dedicated geodetic survey departments. The model is penetrating where in-house monitoring capacity was previously uneconomical at single-asset scale.
Geotechnical Engineering Market Segmentation
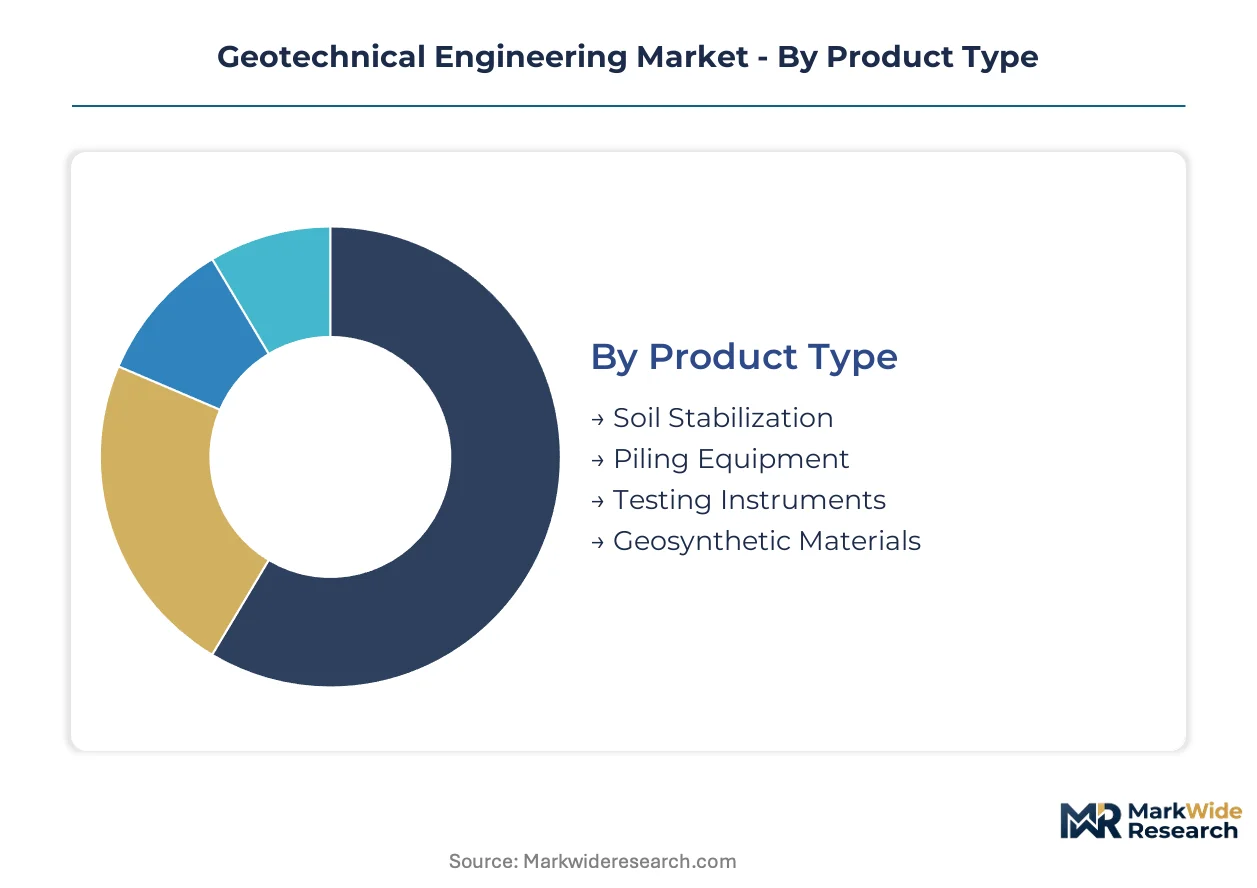
Geotechnical engineering services and equipment fragment across multiple dimensions that determine procurement patterns and project economics. Product specifications vary sharply between domestic infrastructure markets and export-oriented mining corridors. Technology adoption curves diverge based on regulatory maturity and capital availability.
Product Type:
Domestic infrastructure markets in Germany and Japan drive premium piling equipment demand, while export-led soil stabilization products concentrate manufacturing in China and India for Southeast Asian construction corridors.
- Piling Equipment:Hydraulic impact hammers and continuous flight auger rigs handle deep foundation installation for urban high-rise clusters. Japanese metropolitan transit authorities specify automated rig positioning systems for vibration-sensitive tunneling adjacent to existing structures.
- Testing Instruments:Piezometers, inclinometers, and settlement plates monitor ground deformation during and after construction. FERC-mandated dam safety instrumentation across United States watersheds sustains replacement demand for automated data logging systems.
- Soil Stabilization:Cement deep mixing equipment and jet grouting systems strengthen soft ground for highway embankments in the Netherlands.
- Geosynthetic Materials:Geogrids and geomembranes reinforce earth structures and contain contaminants at brownfield sites in Belgium.
Piling equipment commands the established base. The steepest expansion runs through testing instruments as regulatory instrumentation mandates proliferate.
Application:
Cost tier stratification separates foundation engineering as the volume leader from slope stability as the premium-margin specialist application requiring continuous monitoring capabilities.
- Foundation Engineering:Bearing capacity analysis and settlement prediction support structural loads for commercial high-rises and industrial facilities. India's metro rail expansion across Delhi, Mumbai, and Bangalore corridors consumes specialized deep foundation design services for underground station boxes.
- Slope Stability:Landslide risk assessment and stabilization design protect transportation corridors and residential developments in mountainous terrain. Climate-intensified rainfall patterns in the Alps and Himalayas are expanding mandatory geohazard screening for road and rail alignments.
- Earth Retention:Soldier pile walls and soil nail systems enable vertical excavation in dense urban cores with limited right-of-way.
- Mining Operations:Tailings dam surveillance and pit slope monitoring ensure geotechnical integrity at open-cut and underground extraction sites in Chile and Australia.
Foundation engineering captures the volume base. Slope stability is climbing the fastest as climate adaptation spending redirects infrastructure budgets.
End User:
Customer type determines contract structure, with government agencies favoring long-term framework agreements while mining organizations prefer outcome-based performance contracts.
- Construction Companies:General contractors and specialty foundation subcontractors procure geotechnical investigation and ground improvement as bundled design-build packages. Germany's Rhine-Ruhr brownfield redevelopment corridor concentrates demand for contaminated land characterization among mid-tier construction firms.
- Government Agencies:Transportation departments and water resource authorities mandate standardized investigation protocols for public infrastructure procurement. Japan's Ministry of Land, Infrastructure, Transport and Tourism specifies continuous cone penetration profiling for expressway embankment verification.
- Mining Organizations:Copper and iron ore operators commission tailings storage facility surveillance and pit wall stability assessment.
- Environmental Consultants:Site remediation specialists coordinate phased investigation and risk assessment for property transactions and regulatory compliance.
Construction companies anchor the demand base. Government agencies are gaining share fastest as infrastructure stimulus programs expand public procurement volumes.
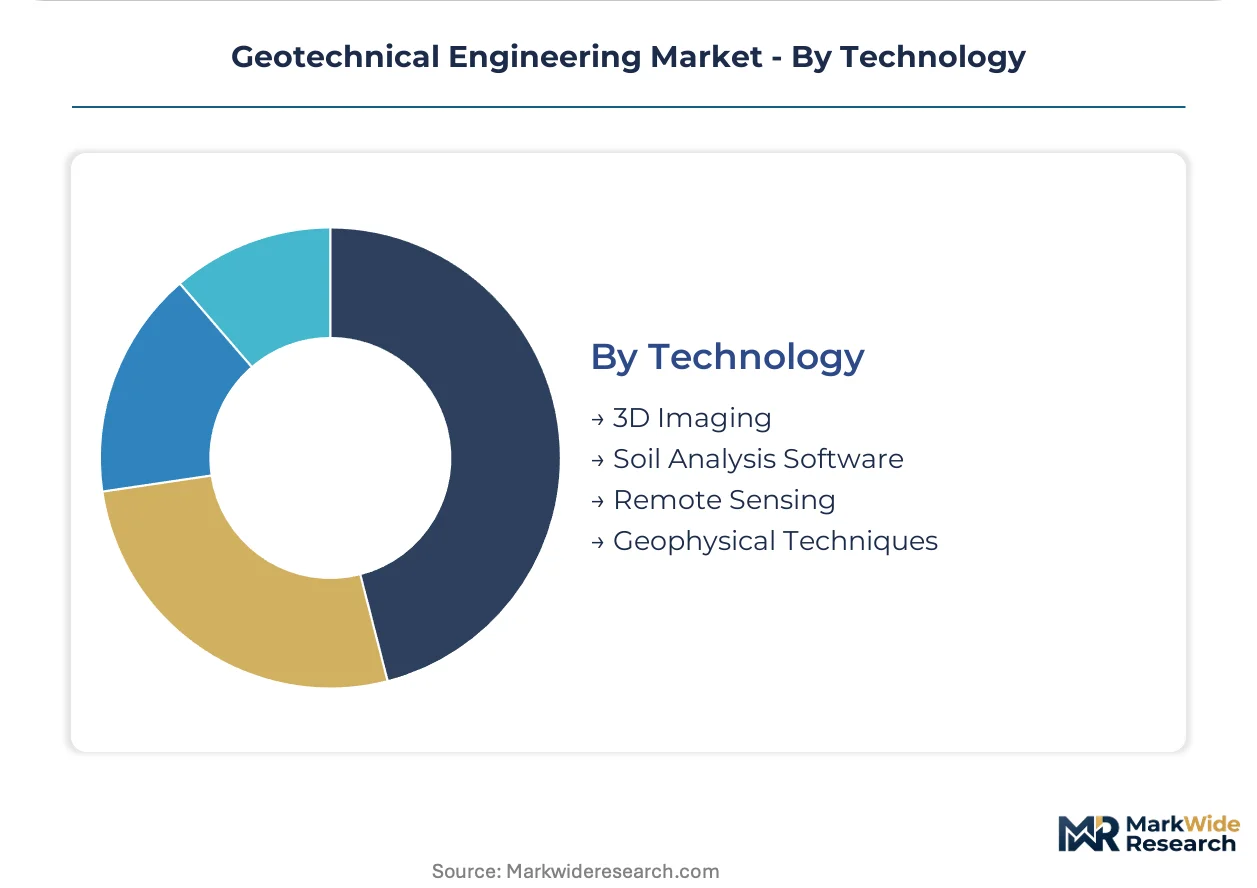
Technology:
Supply concentration in software development clusters shapes geographic adoption patterns, with North American and European firms leading 3D imaging platforms while Asian specialists dominate remote sensing hardware.
- Remote Sensing:Satellite-based interferometric synthetic aperture radar and drone-mounted LiDAR enable millimeter-scale deformation monitoring without ground crew mobilization. Australian mining operators pilot subscription-based InSAR telemetry for tailings dam surveillance without maintaining dedicated geodetic departments.
- 3D Imaging:Electrical resistivity tomography and seismic refraction surveys generate subsurface volumetric models for complex geology interpretation. South Korean transportation agencies now specify 3D geophysical coverage for tunnel route selection through fault zones.
- Soil Analysis Software:Digital platforms automate bearing capacity calculation and settlement prediction from field investigation data.
- Geophysical Techniques:Ground-penetrating radar and magnetometry map buried utilities and geological anomalies prior to excavation.
Remote sensing commands the technology investment base. 3D imaging is expanding most quickly as visualization requirements tighten in seismically active design codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai Metro Line 3 underground corridor anchors India's accelerating geotechnical engineering demand. Germany's Rhine-Ruhr brownfield redevelopment corridor drives soil protection compliance spending. Japan's seismic retrofit programs for expressway infrastructure sustain precision instrumentation procurement.
United States
FERC-mandated dam safety instrumentation across the Mississippi River watershed sustains recurring contracts for automated monitoring system providers. The EPA's brownfield remediation standards require comprehensive site characterization before property redevelopment. California's Sacramento-San Joaquin Delta levee system upgrades concentrate demand for geotechnical investigation firms serving water resource authorities.
Germany
EU Green Deal soil protection directives are expanding mandatory testing volumes for contaminated land assessment in industrial corridors. REACH chemical restrictions are phasing out diesel-based drilling fluids ahead of enforcement deadlines. The Rhine-Ruhr metropolitan region concentrates brownfield redevelopment projects requiring advanced ground improvement and site investigation services.
India
Metro rail underground construction across Delhi, Mumbai, and Bangalore corridors consumes specialized deep foundation design services for station boxes and tunnel boring machine support. The Ministry of Housing and Urban Affairs infrastructure stimulus programs expand public procurement volumes for geotechnical contractors. The Mumbai-Ahmedabad high-speed rail corridor generates sustained demand for ground improvement verification in dense metropolitan cores.
Japan
MLIT specifications for continuous cone penetration profiling on expressway embankment verification elevate data density requirements for transportation infrastructure. Seismic design code revisions for performance-based foundation assessment open procurement pathways for ground improvement contractors. The Osaka-Kobe metropolitan corridor concentrates urban transit expansion requiring vibration-sensitive tunneling adjacent to existing structures.
Australia
Mining operators in Western Australia pilot subscription-based InSAR telemetry for tailings dam surveillance without maintaining dedicated geodetic survey departments. The country's national mining regulator mandates periodic pit wall stability assessment for open-cut extraction sites. The Pilbara iron ore region concentrates demand for automated deformation monitoring systems at remote single-asset operations.
Geotechnical Engineering Market Vendor Landscape
Listed leaders compete with private specialists across engineering-consulting service delivery, creating a tiered structure where scale-driven multinationals anchor framework contracts with government agencies while boutique firms capture premium-margin specialist assessments. The competitive landscape fragments across integrated design-build operators, standalone geohazard assessment specialists, and equipment-anchored field service providers. Two dominant competitive moves are reshaping positioning: strategic partnerships between instrumentation manufacturers and regional service networks, and portfolio diversification into subscription-based remote monitoring telemetry.
Among integrated engineering consultancies, Arup and Jacobs Engineering Group exemplify the design-consulting archetype that anchors long-term relationships with government transportation agencies. WSP Global Inc. occupies a position within the geohazard specialist tier, serving seismically active zones through dedicated assessment capabilities. These three entities represent contrasting strategic postures—integrated service breadth, public-sector relationship depth, and technical specialization—without any single model commanding uniform preference across procurement contexts.
| Leading Market Players |
|---|
| Arup |
| AECOM |
| Golder Associates |
| Ramboll |
| Jacobs Engineering Group |
| WSP Global Inc. |
| Geosyntec Consultants |
| Bechtel Corporation |
| Tetra Tech |
| Others |
Supply Flow & Price Mechanics
ISO 14688 soil classification certification gates both supplier qualification and price differentiation simultaneously, forcing procurement officers to rewrite vendor criteria while accredited laboratories command premium positioning over unqualified regional operators.
Pricing Analysis
Volume-discount tiering structures separate framework contract pricing for government transportation agencies from spot-market rates for mining operators and environmental consultants. Price differentiation rests on certification grade and geographic delivery cost, with FERC-mandated instrumentation specialists capturing margin premiums. Cost compression in standard site investigation services is intensifying because unaccredited regional operators compete on mobilization speed. Construction companies show highest price sensitivity, while mining organizations prioritize outcome-based performance warranties over unit costs.
Supply Chain Analysis
Extended lead times for cone penetration test rigs and undisturbed sampling tools concentrate manufacturing in Germany and Japan, exposing project timelines to shipping bottlenecks. Raw material dependencies include high-strength steel alloys, precision sensors, and synthetic polymer drilling fluids. Single-source vulnerability runs through specialized piezometer and inclinometer component suppliers. Distribution feeds from manufacturer-direct sales for large infrastructure frameworks through regional equipment rental networks serving mid-tier contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs through subscription-based remote monitoring telemetry, as climate adaptation spending and regulatory instrumentation mandates create specialist niches beyond integrated consultancies.
For Market Incumbents: Shield accredited laboratory networks from price erosion by accelerating ISO 14688 certification investments before backlog delays erode competitive position. Deepen relationships with government transportation agencies through long-term framework contracts for FERC-mandated dam safety instrumentation. Counter drone-mounted LiDAR specialists by bundling automated monitoring systems with legacy geohazard assessment expertise.
For New Entrants and Emerging Players: Subscription-based deformation monitoring services present the most penetrable white-space, where Australian mining operators pilot satellite-InSAR telemetry without dedicated geodetic departments. Target slope stability assessment in climate-intensified rainfall corridors across the Alps and Himalayas, where mandatory geohazard screening expands faster than specialist capacity. Enter through pilot performance contracts with single-asset mining operators, then scale through equipment-anchored service partnerships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across remote sensing telemetry platforms, as subscription models unbundle instrumentation ownership from operational delivery. Long-term viability favors automated monitoring system providers with recurring revenue streams over project-based field service contractors. Signal to watch: building code adoptions of performance-based foundation design in seismically active zones, which will accelerate procurement pathway shifts toward settlement-warranty contractors.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14688 Accreditation Investment | Accredited laboratories capture premium positioning as certification bifurcates competitive landscape. |
| Subscription-Based Telemetry Launch | Mining operators in Chile and Australia pilot InSAR surveillance without dedicated geodetic departments. |
| Drone-Mounted LiDAR Integration | Rapid site reconnaissance reduces mobilization costs for preliminary geohazard screening in remote terrain. |
| Performance-Based Foundation Contracting | Seismic design code revisions in Japan open procurement for settlement-warranty ground improvement. |
| Regional Equipment Rental Expansion | Germany's Rhine-Ruhr brownfield corridor concentrates demand for contaminated land investigation services. |
Methodological Framework
The analysis maps foundation engineering, slope stability, earth retention, and mining operations segments, each validated through project directors at engineering consultancies, procurement officers at transportation agencies, instrumentation technicians, and mining geotechnical managers. Primary interviews combined with secondary validation from FERC dam safety filings, EPA brownfield remediation records, MLIT expressway specifications, and ASTM test protocol documentation. Bottom-up project pipeline assessment triangulated against top-down infrastructure stimulus allocation tracking.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include application type, end-user contract structure, technology adoption tier, and regional regulatory maturity. CAGRs derived from infrastructure investment flow analysis, with industry-specific inputs capturing metro rail underground construction timelines and EU Green Deal soil protection directive implementation pacing.
Underlying assumptions cover sustained infrastructure stimulus program continuity and REACH chemical restriction enforcement timelines, with deviation risk concentrated in specialized drilling equipment import bottlenecks and geotechnical instrumentation technician scarcity constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
UK Facade Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
India Structural Steel Fabrication Market
Structural Engineering
Civil Engineering Market
Structural Engineering
North America Facade Market
Structural Engineering
Structural Steel Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Fabricated Structural Steel Market