
 Global Pile Driving Equipment Market | 2026-2036
Global Pile Driving Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pile Driving Equipment Market Analysis
The EU Green Deal is recalibrating procurement standards for marine and infrastructure contractors across European ports. Bauer AG anchors its position through integrated manufacturing of crawler carriers and drilling rigs for deep foundation work. Dieseko Group B.V. specializes in vibratory and impact hammers for offshore wind monopile installation. Soilmec S.p.A. competes with a focused portfolio of hydraulic piling rigs tailored to urban foundation constraints.
Pile driving equipment comprises heavy machinery designed to install structural piles into soil or seabed substrates using impact, vibratory, hydraulic, or static force, typically operating at stroke energies from 30 kJ to over 1,500 kJ depending on substrate density and pile diameter. Its primary purpose is to transfer structural loads from buildings, bridges, offshore platforms, or wind turbines to stable bearing strata. Hydraulic hammer systems currently lead product type demand due to precision control and reduced noise emissions relative to diesel alternatives. Vibratory technology dominates offshore installation where soil liquefaction enables rapid pile penetration without repeated impact stress. Static and continuous flight auger methods occupy growing niches in urban environments where vibration limits restrict conventional hammer operations.
The EPA enforces noise and emissions standards for construction equipment operating in US coastal zones, while the EU F-Gas Regulation constrains hydraulic fluid formulations used in European machinery. China's MEE implements dual carbon goals that tighten manufacturing emissions benchmarks for heavy equipment producers. Japan's METI drives adoption of quieter, electrically assisted pile drivers through urban construction codes around Osaka and Tokyo. Stakeholders must monitor how evolving carbon border mechanisms and local content requirements reshape equipment sourcing decisions across major project markets.
Market Dynamics
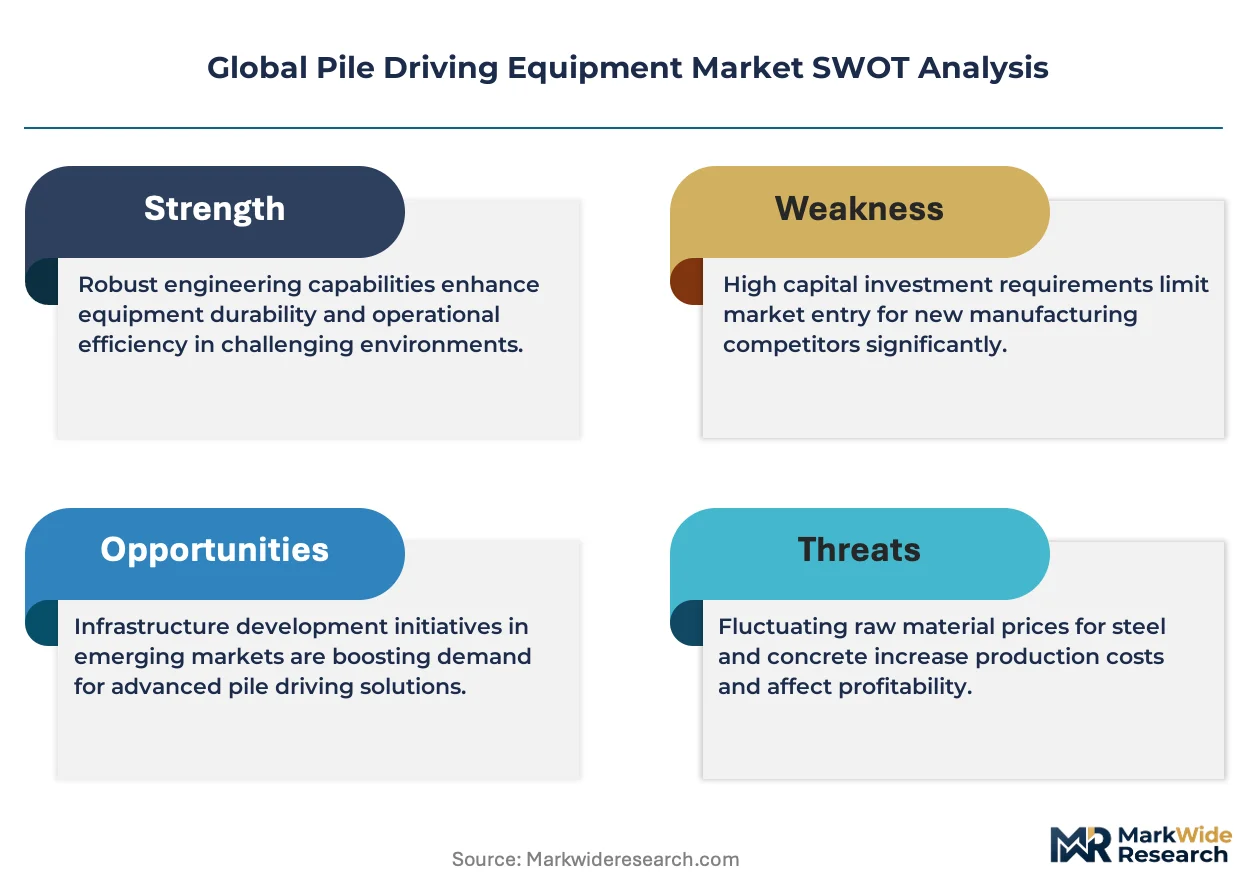
Foundation depth requirements for offshore wind monopiles in the North Sea have crossed 50 meters, forcing contractors to retire legacy diesel hammers in favor of high-capacity hydraulic and vibratory systems with precision energy control.
Growth Catalysts
- EU Green Deal infrastructure mandates:The European Commission's decarbonization targets require marine contractors to achieve measurable emissions reductions, redirecting capital toward electrified pile driving fleets.
- Offshore wind foundation scale-up:Turbine capacities exceeding 15 MW demand monopile diameters above 10 meters, creating sustained demand for vibratory hammers with soil liquefaction capabilities.
- China's port modernization wave:Dual carbon goals under MEE oversight are accelerating replacement of aging port infrastructure, concentrating equipment procurement in Shanghai and Tianjin corridors.
Market Restraints
- Specialized steel alloy supply:Hammer anvil and drive cap production depends on high-grade manganese steel from concentrated European and Japanese foundries.
- EPA coastal zone noise limits:Impact hammer operations in US waters face seasonal restrictions that compress project windows and elevate standby costs.
- Skilled operator scarcity:Vibratory and hydraulic systems require certified technicians with substrate-specific calibration expertise that training pipelines have failed to replenish.
Strategic Opportunities
- US offshore wind lease expansion:Bureau of Ocean Energy Management auctions off California and Gulf Coast sites where floating foundation pilots will test hybrid installation methods.
- Electric assist retrofits:Convergence of battery powertrains with conventional hydraulic systems enables partial electrification without full fleet replacement.
- Japan urban construction codes:METI-mandated noise restrictions around Osaka and Tokyo are creating first-mover advantage for manufacturers with ultra-quiet static press systems.
Industry Challenges
- Substrate variability modeling:Geotechnical uncertainty in seabed conditions forces contractors to maintain redundant hammer configurations, inflating mobilization costs.
- EU F-Gas hydraulic fluid compliance:Reformulation timelines for biodegradable alternatives lag behind equipment certification cycles, creating inventory management complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pile Driving Equipment Market |
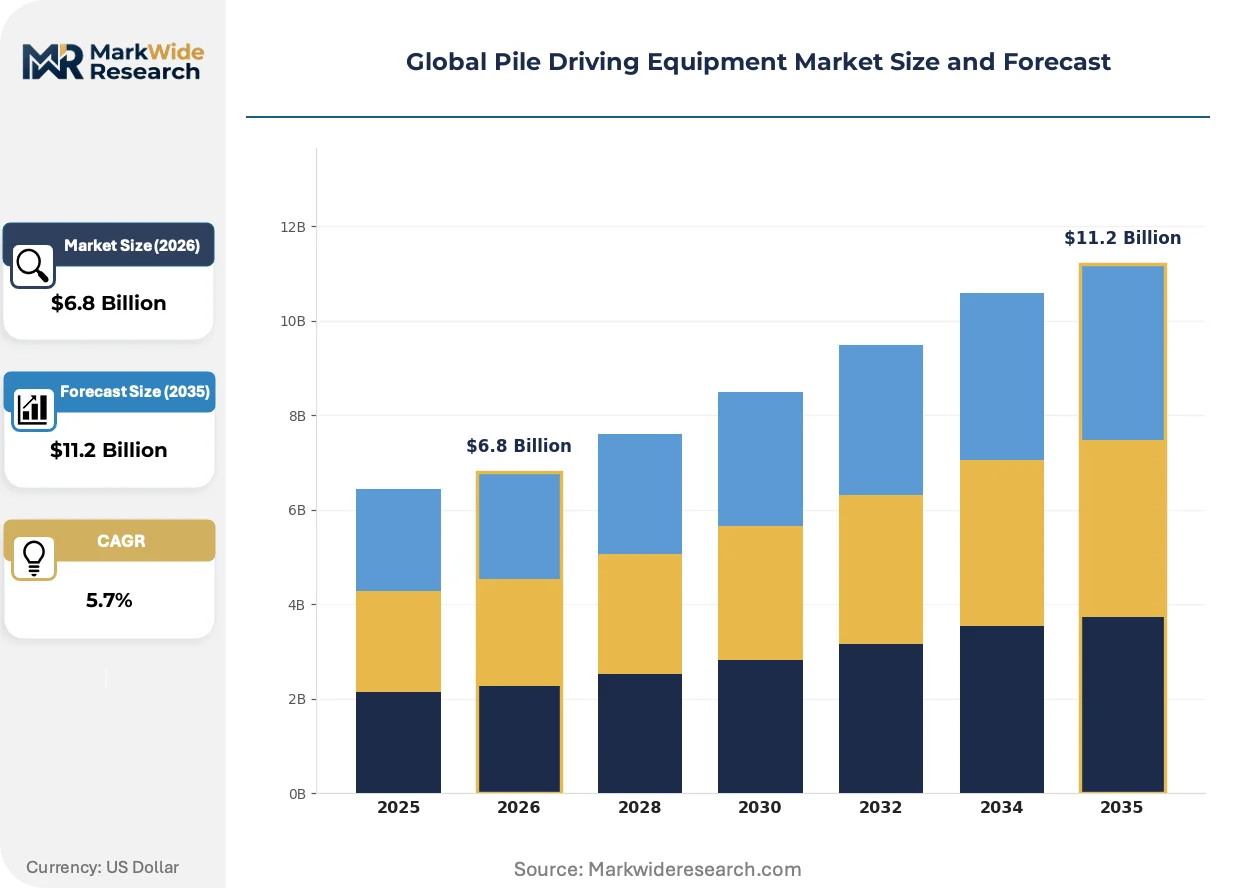
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impact Hammer, Diesel Hammer, Electric Pile Driver, Hydraulic Hammer End User: Construction Companies, Marine Contractors, Infrastructure Developers, Utilities Installation Type: Onshore, Offshore, In-Water, Ground Technology: Vibratory, Static, Continuous, Auger |
| Companies Covered | Soilmec S.p.A., Dieseko Group B.V., Bauer AG, Vermeer Corporation, Junttan Oy, Liebherr Group, Casagrande S.p.A., Sunward Intelligent Equipment, American Piledriving Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pile Driving Equipment Market Emerging Trajectories
Equipment intelligence and energy delivery systems are converging to reshape competitive advantage, with digital feedback loops and alternative powertrains displacing operator-dependent calibration methods.
Variable frequency drive vibratory hammers are overtaking fixed-frequency units in offshore wind applications. These systems adjust eccentric moment in real-time based on pile penetration resistance, reducing installation time by enabling continuous optimization. Orsted and Equinor contractors in Danish and German waters have standardized on this technology, compressing foundation installation windows and reducing vessel day rates.
The EU F-Gas Regulation is constraining hydraulic fluid formulations across European machinery fleets. Equipment manufacturers must reformulate seal materials and pump architectures to accommodate biodegradable alternatives with different viscosity profiles. German and Dutch contractors face the steepest compliance curves as their installed bases contain the highest concentration of legacy fluid systems.
Service unbundling is fragmenting traditional equipment procurement relationships. Contractors in the North Sea are separating hammer rental from vessel provision and installation engineering, creating direct procurement channels with specialized equipment lessors. This pattern is most visible in German offshore wind clusters where project sponsors now specify hammer performance standards independently of EPC contractor preferences.
Global Pile Driving Equipment Market Segmentation
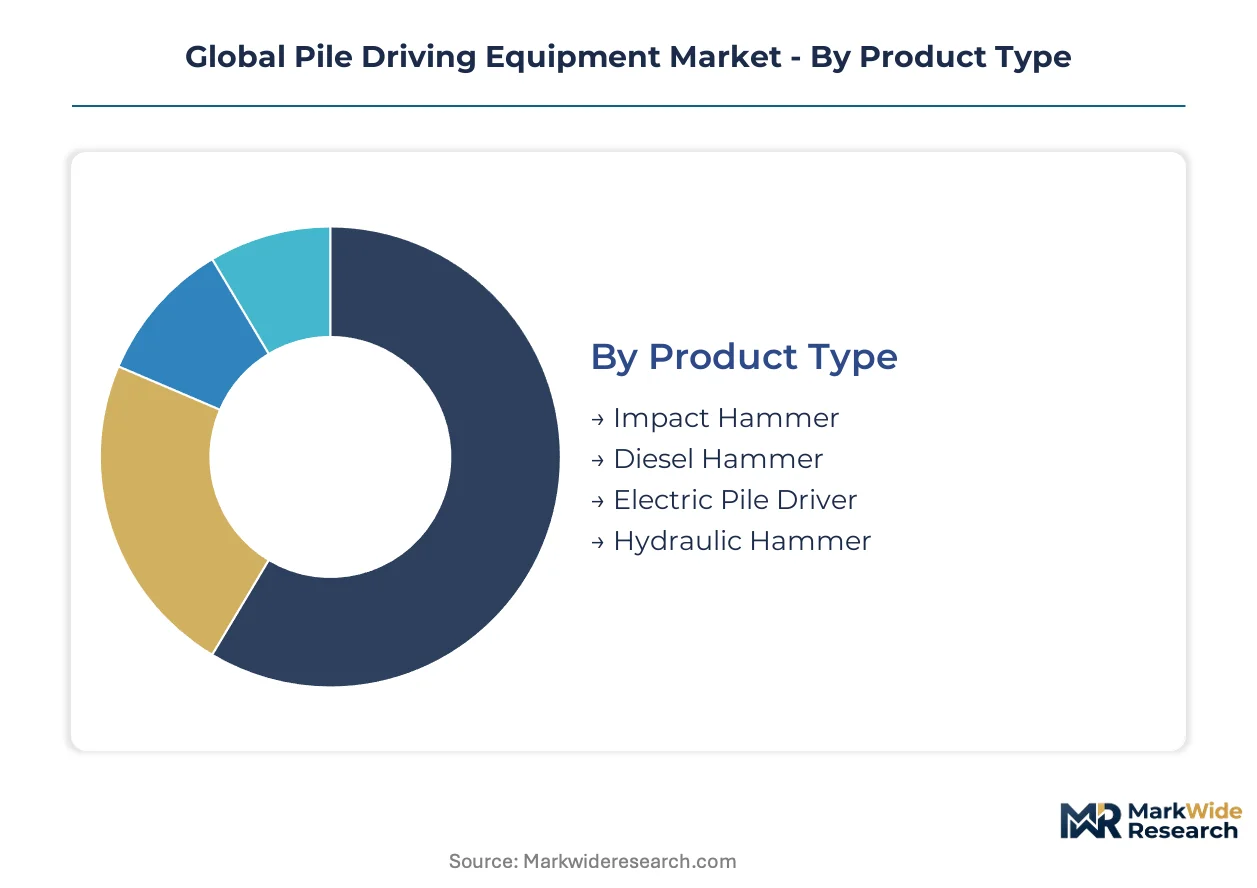
Pile driving equipment procurement varies sharply across project environments, substrate conditions, and regulatory constraints. Contractors select systems based on noise limits, foundation depth, and vessel compatibility rather than unit cost alone.
Product Type:
Buyers differentiate primarily by stroke energy precision and emissions profile, with coastal regulations and urban noise codes dictating acceptable technology.
- Impact Hammer:Traditional percussive systems deliver concentrated energy through repeated blows, suited for dense soils and hard rock penetration. Demand concentrates in US Gulf Coast marine construction where EPA seasonal restrictions compress project windows, forcing contractors to maximize daily pile count.
- Hydraulic Hammer:Closed-loop hydraulic systems enable programmable stroke energy and reduced noise signatures compared to diesel alternatives. German and Dutch offshore wind developers specify these systems for North Sea monopile installation where foundation depths exceed 50 meters and precision energy control prevents pile fatigue.
- Diesel Hammer:Combustion-powered units remain deployed in remote onshore sites lacking electrical infrastructure.
- Electric Pile Driver:Grid-tied or battery-electric systems serve Japanese urban corridors under METI noise mandates.
Hydraulic hammer leads volumes today; electric pile driver is gaining share fastest.
End User:
Capital deployment scale and project duration separate these buyer categories, with marine contractors commanding the highest equipment utilization rates.
- Marine Contractors:Specialized offshore installation firms operate heavy-lift vessels with permanently mounted vibratory and hydraulic systems. Northern European developers in Danish and German waters drive specification standards, unbundling hammer procurement from EPC contracts to control performance metrics directly.
- Construction Companies:General contractors deploy rented or owned equipment across building foundation, bridge, and civil works portfolios. Chinese port modernization in Shanghai and Tianjin corridors concentrates procurement, with MEE dual carbon goals accelerating fleet replacement.
- Infrastructure Developers:State-backed entities finance long-horizon transportation and energy projects with captive equipment pools.
- Utilities:Power grid and renewable energy operators specify foundation systems for transmission towers and offshore wind arrays.
Marine contractors lead volumes today; utilities are gaining share fastest.
Installation Type:
Environmental exposure and substrate access determine equipment configuration, with offshore and in-water applications requiring vessel integration.
- Offshore:Open-water foundation installation demands vibratory hammers with soil liquefaction capabilities and dynamic positioning vessel compatibility. North Sea wind farm developers standardize on variable frequency drive systems that adjust eccentric moment in real-time based on penetration resistance.
- Onshore:Land-based construction spans building foundations, bridge piers, and industrial facilities across varied soil conditions. German urban codes and Japanese METI restrictions around Osaka and Tokyo favor static press methods where vibration limits prohibit impact hammers.
- In-Water:Coastal and estuarine projects in tidal zones require corrosion-resistant systems and floating platform deployment.
- Ground:Terrestrial applications without water table complications use conventional crawler-mounted rigs.
Onshore leads volumes today; offshore is gaining share fastest.
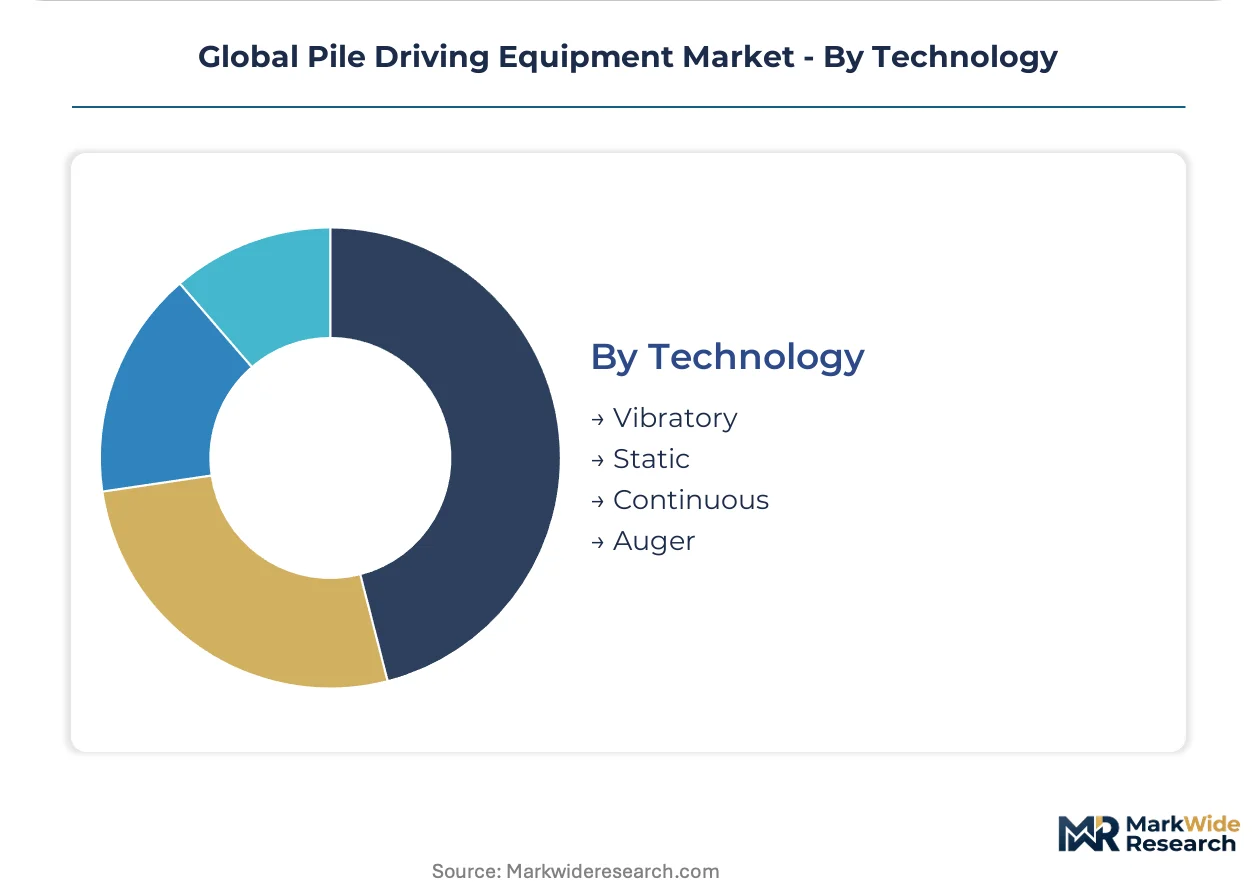
Technology:
Energy transmission mechanism and soil interaction physics define competitive positioning, with vibratory systems displacing impact methods in sensitive environments.
- Vibratory:Eccentric mass rotation generates horizontal oscillations that liquefy granular soils, enabling rapid pile penetration without repeated impact stress. Orsted and Equinor contractors in Danish waters have standardized this technology, compressing installation windows and reducing vessel day rates for monopile diameters above 10 meters.
- Static:Hydraulic press systems apply continuous downward force, eliminating vibration and noise entirely. Japanese urban construction codes around Tokyo create first-mover advantage for manufacturers with ultra-quiet systems capable of operating adjacent to sensitive structures.
- Continuous:Flight auger methods drill and concrete-fill in single passes for urban foundation constraints.
- Auger:Rotary drilling with displacement piles serves cohesive soils where vibration must be minimized.
Vibratory leads volumes today; static is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled marine equipment operators and certified hydraulic technicians concentrate in Northern European ports and Chinese manufacturing corridors, anchoring regional competitive positions.
Germany
Offshore wind developers in the North Sea drive specification standards for high-capacity hydraulic systems. The EU Green Deal mandates emissions reductions that redirect capital toward electrified fleets. Installation contractors in Cuxhaven and Bremerhaven unbundle hammer procurement from EPC contracts to control performance metrics directly.
China
Port modernization in Shanghai and Tianjin corridors concentrates equipment procurement for dual carbon infrastructure replacement. The MEE tightens manufacturing emissions benchmarks for heavy equipment producers. State-backed developers finance long-horizon transportation projects with captive equipment pools in the Yangtze River Delta.
United States
Bureau of Ocean Energy Management auctions off California and Gulf Coast sites where floating foundation pilots test hybrid installation methods. The EPA enforces seasonal noise restrictions that compress project windows and elevate standby costs. Marine contractors in the Gulf Coast maintain redundant hammer configurations to manage geotechnical uncertainty.
Japan
METI-mandated noise restrictions around Osaka and Tokyo create first-mover advantage for manufacturers with ultra-quiet static press systems. Urban construction codes favor methods where vibration limits prohibit impact hammers. Specialized technicians with substrate-specific calibration expertise concentrate in the Kanto and Kansai industrial belts.
Netherlands
Rotterdam port expansion and North Sea wind farm installation sustain demand for variable frequency drive vibratory hammers. The EU F-Gas Regulation constrains hydraulic fluid formulations used in European machinery. Contractors in Dutch waters standardize on soil liquefaction technology that adjusts eccentric moment in real-time based on penetration resistance.
Global Pile Driving Equipment Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered vendor base where integrated manufacturers anchor premium positioning while specialized lessors capture service unbundling opportunities. The market structure concentrates around German, Italian, and Dutch engineering clusters with deep foundation expertise. Strategic archetypes include vertically integrated rig manufacturers, vibratory hammer specialists, and regional equipment lessors. Dominant competitive moves encompass electric assist retrofits and direct procurement channel development with North Sea project sponsors.
Among European integrated manufacturers, Bauer AG represents the capital-intensive archetype with captive production of crawler carriers and drilling rigs, while Dieseko Group B.V. exemplifies the specialized technology tier focused on vibratory and impact hammer systems. Soilmec S.p.A. occupies a position within the urban foundation segment, tailoring hydraulic piling rigs to constrained construction environments. These three entities anchor distinct competitive vectors without overlapping core specializations.
| Leading Market Players |
|---|
| Soilmec S.p.A. |
| Dieseko Group B.V. |
| Bauer AG |
| Vermeer Corporation |
| Junttan Oy |
| Liebherr Group |
| Casagrande S.p.A. |
| Sunward Intelligent Equipment |
| American Piledriving Equipment |
| Others |
Supply Flow & Price Mechanics
Performance-tier divergence between precision-controlled hydraulic systems and legacy diesel alternatives manifests in both capital expenditure spreads and supplier consolidation patterns. Buyers unbundling hammer procurement from EPC contracts in Northern Europe command pricing leverage through direct specification of energy delivery metrics, while remote onshore contractors absorb diesel hammer premiums driven by infrastructure scarcity and logistics premiums.
Pricing Analysis
Bundled service contracts—combining equipment rental with vessel provision and installation engineering—are fragmenting into unbundled direct procurement channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service intensity, with marine contractors in German waters least price-sensitive due to vessel day-rate dominance in total project economics. Cost compression in standard-tier diesel hammers is intensifying because Chinese port modernization concentrates volume procurement in state-backed tender processes.
Supply Chain Analysis
High-grade manganese steel for hammer anvils and drive caps rests on concentrated European and Japanese foundry capacity, with German, Italian, and Dutch engineering clusters anchoring finished equipment assembly. Critical inputs span specialty hydraulic seals reformulated for EU F-Gas biodegradable fluid compliance, precision-machined eccentric masses for variable frequency vibratory systems, and corrosion-resistant coatings for offshore saltwater exposure. Single-source vulnerability in Japanese specialty steel alloys exposes lead times to METI industrial allocation protocols. Distribution runs through regional equipment lessors with captive maintenance networks and direct manufacturer channels for unbundled North Sea procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by offshore wind foundation depth requirements crossing 50 meters and the resulting specification shift toward precision energy control systems that prevent pile fatigue.
For Market Incumbents: Extend aftermarket service capabilities into predictive maintenance platforms using penetration resistance telemetry from variable frequency vibratory systems. Backward integration into high-grade manganese steel sourcing mitigates Japanese foundry concentration risk. Certification investment in EU F-Gas fluid compatibility creates switching costs against emerging electric assist retrofits threatening hydraulic system incumbency. For New Entrants and Emerging Players: Battery-electric assist retrofits for conventional hydraulic systems offer a technology-first wedge into Japanese urban construction corridors where METI noise mandates prohibit impact hammer deployment. White-space concentration sits in California and Gulf Coast floating foundation pilots testing hybrid installation methods. Direct procurement relationships with Bureau of Ocean Energy Management leaseholders bypass established EPC contractor gatekeeping. For Investors and Strategic Acquirers: Consolidation pressure builds where service unbundling fragments traditional equipment procurement relationships and specialized lessors capture margin pools previously retained by integrated manufacturers. Long-term viability favors asset-light designers with electric powertrain intellectual property over capital-heavy rig manufacturers exposed to cyclical vessel utilization. The signal to watch is variable frequency drive standardization by Orsted and Equinor contractors as procurement specification precedent.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Assist Retrofit Development | Battery-hybrid powertrains enable partial fleet electrification without full replacement capex. |
| Direct Procurement Channel Establishment | Unbundled hammer sales to North Sea project sponsors bypass EPC margin extraction. |
| Biodegradable Hydraulic Fluid Certification | EU F-Gas Regulation compliance opens German and Dutch contractor installed base conversion. |
| Predictive Maintenance Platform Launch | Real-time penetration resistance telemetry reduces vessel standby costs for marine contractors. |
| Specialized Steel Alloy Supply Agreement | Long-term manganese steel offtake secures anvil production against Japanese foundry allocation risk. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from marine equipment operators, foundation installation engineers, EPC contractor procurement directors, and aftermarket service technicians. Secondary validation drew from customs trade data for pile driving equipment imports, SEC filings of publicly traded heavy equipment manufacturers, EU ETS emissions disclosure databases, and offshore wind project development registries. Bottom-up equipment unit economics and top-down infrastructure investment forecasts were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon to observed foundation depth escalation patterns and regulatory compliance cost curves. Segmentation modeling spanned product type, installation environment, end-user category, and technology mechanism. CAGRs were derived from installed base replacement cycles, vessel day-rate sensitivity analysis, and regional infrastructure pipeline assessments. Key inputs included geotechnical uncertainty coefficients affecting hammer configuration redundancy and electrification subsidy trajectories under EU Green Deal implementation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to floating foundation technology maturation and carbon border mechanism expansion affecting equipment sourcing decisions. Forecasts reflect documented assumptions regarding substrate variability modeling accuracy and skilled technician training pipeline replenishment. Material deviation in Japanese urban noise code enforcement or EPA seasonal restriction expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Snow Pushers Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Ground Engaging Tools (GET) Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Asia-Pacific Road Marking Machine Market