
 Hydroforming Press Market | 2026-2036
Hydroforming Press Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroforming Press Market Insights
Equipment leasing and project finance for large-capacity presses is reconfiguring competitive entry barriers across the hydroforming sector. Schuler AG leverages its German engineering base to sustain premium positioning in multi-station systems for automotive OEMs. Fagor Arrasate anchors its presence through specialized tubular hydroforming lines serving European commercial vehicle manufacturers. Quintus Technologies differentiates via high-pressure pump technology leadership in aerospace-grade forming applications.
A hydroforming press applies fluid pressure, typically between 100 and 400 MPa, to shape metal sheets or tubes against a die cavity without conventional stamping force, producing complex geometries with reduced wall thinning and superior structural integrity for lightweight components. Tubular hydroforming dominates current installed capacity across automotive exhaust and chassis programs, while sheet hydroforming captures expanding margin pools in aerospace skin panel fabrication where AS9100 certification requirements elevate supplier qualification barriers. Electromechanical system technology represents the fastest-growing segment as servo-driven presses displace conventional hydraulic architectures in Tier-1 supplier facilities seeking energy efficiency and process repeatability.
EPA fuel-economy regulations and EU F-Gas restrictions on hydraulic fluid emissions are reshaping equipment specifications and replacement demand across North American and European manufacturing bases. China's GB standards for industrial machinery safety and Japan's METI energy-efficiency directives impose additional compliance layers on press imports and local production. OEM procurement teams and fabrication workshop operators must monitor evolving carbon-border adjustment mechanisms and servo-hydraulic hybrid architectures to align capital deployment with tightening regulatory trajectories.
Market Dynamics
Electromechanical servo architectures are compressing replacement cycles as Tier-1 suppliers abandon hydraulic systems under combined pressure from EPA fuel-economy mandates and EU F-Gas restrictions on fluid emissions.
Growth Catalysts
- EPA Fuel-Economy Standards:Tightened Corporate Average Fuel Economy requirements force automotive OEMs to adopt lightweight structural components, directly expanding sheet hydroforming capacity across US manufacturing corridors.
- EU CO2 Fleet Mandates:Binding emission reduction targets for passenger vehicle fleets accelerate press replacement investments among German and Italian automotive suppliers seeking compliant chassis geometries.
- Tubular Hydroforming:Exhaust system and chassis programs in China's Yangtze River Delta automotive cluster sustain dominant installed capacity utilization, anchoring equipment demand for commercial vehicle manufacturers.
Market Restraints
- High-Pressure Pump Costs:Aerospace-grade forming applications require precision pump systems with extended lead times, constraining capital deployment timelines for tier-2 fabrication workshops.
- AS9100 Certification Barriers:Supplier qualification requirements for aerospace skin panel fabrication elevate entry thresholds, limiting accessible margin pools to incumbent certified operators.
- Hydraulic Fluid Substitution:Electromechanical servo systems threaten conventional hydraulic press installed bases, stranding capital in legacy equipment across North American metal forming facilities.
Strategic Opportunities
- India Commercial Vehicle Expansion:Domestic chassis and exhaust program growth creates underpenetrated demand for tubular hydroforming lines as OEMs localize production under PLI scheme incentives.
- Servo-Hydraulic Convergence:Hybrid architectures combining electromechanical precision with hydraulic force capacity open retrofit markets for mid-capacity press operators seeking energy efficiency without full replacement.
- Carbon Border Adjustment Mechanisms:Emerging EU carbon pricing on imported industrial machinery creates competitive advantage for European-engineered presses with documented lifecycle emission profiles.
Industry Challenges
- Servo Drive Expertise Scarcity:Electromechanical system maintenance and programming require specialized skill sets unavailable in traditional hydraulic press technician labor pools, compressing operational readiness timelines.
- AS9100 Compliance Duration:Aerospace certification cycles spanning 18-24 months delay revenue recognition for suppliers targeting skin panel fabrication contracts with prime contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroforming Press Market |
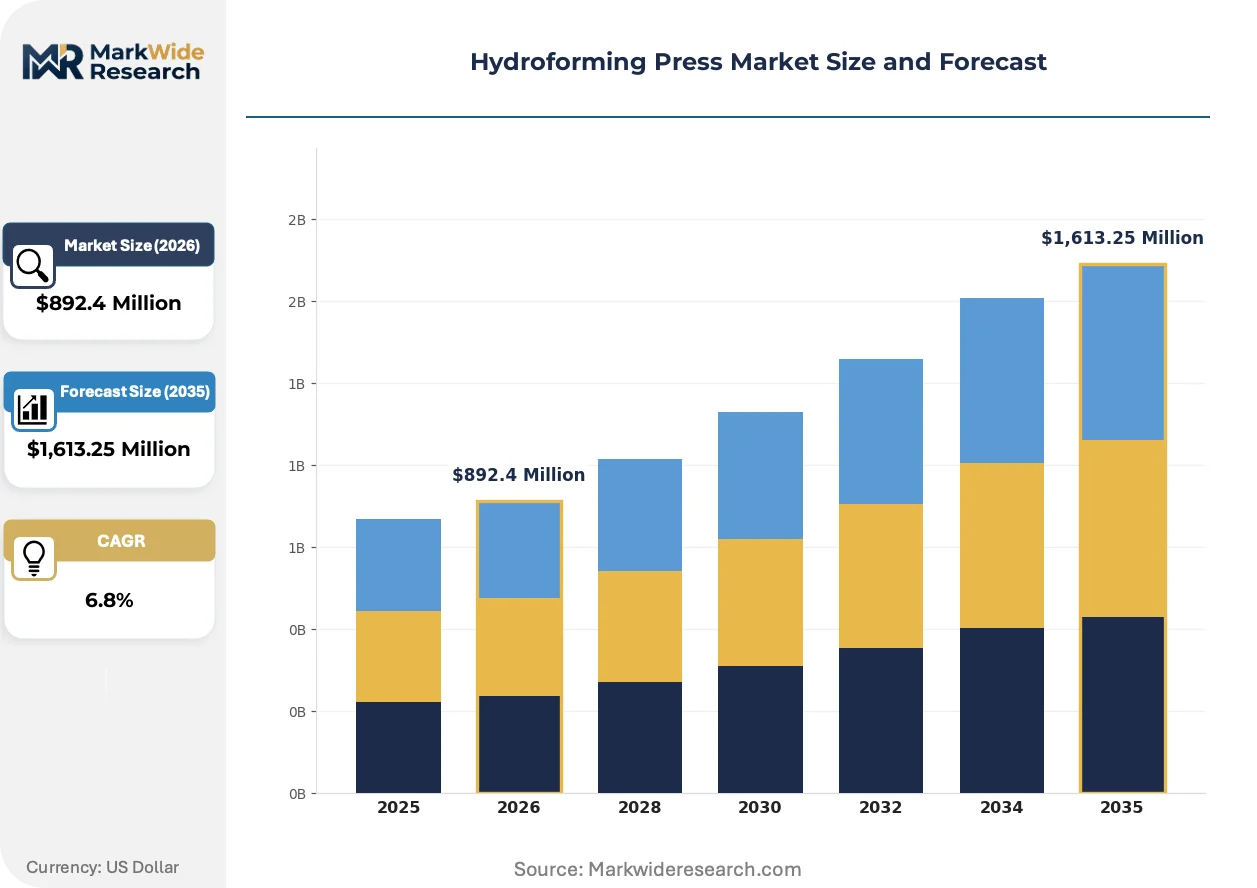
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Press Type: Sheet Hydroforming, Tubular Hydroforming, Multi-Station Hydroforming, Deep Draw Hydroforming Technology: High-Pressure Pump, Servo Valve, Hydraulic Intensifier, Electromechanical System Application: Commercial Vehicle Manufacturing, Aerospace Component Fabrication, Appliance Shell Production, Agricultural Equipment Fabrication End User: OEM Manufacturers, Tier-1 Suppliers, Fabrication Workshops, Industrial Equipment Makers |
| Companies Covered | Schuler AG, Fagor Arrasate, Quintus Technologies, Kobe Steel Ltd., Siempelkamp Maschinen- und Anlagenbau GmbH, ANDRITZ Schuler, American Hydroformers Inc., Aerospace Metal Forming Technologies LLC, FluidForming Americas LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroforming Press Market Trends and Innovations
Servo-driven press architectures are actively restructuring equipment specifications as energy efficiency mandates and process repeatability requirements converge across automotive and aerospace manufacturing bases.
Servo-hydraulic hybrid press technology is hybridizing conventional forming system categories. These systems combine electromechanical precision positioning with hydraulic force generation, enabling variable pressure profiles across complex die geometries. Tier-1 automotive suppliers in Germany and Japan are piloting these configurations for lightweight structural component production. The technology is hybridizing equipment procurement decisions by collapsing the historical trade-off between energy efficiency and forming force capacity.
EU F-Gas Regulation restrictions on fluorinated greenhouse gas emissions in hydraulic systems are forcing fluid formulation changes and sealed system redesigns across European press installations. Industrial consequence includes accelerated obsolescence of open-loop hydraulic architectures unable to meet leakage containment requirements. Italian and Spanish metal forming facilities are responding with preemptive electromechanical conversion investments ahead of enforcement phase-in.
Equipment leasing and project finance structures are displacing traditional capital purchase models for large-capacity presses. Automotive OEM procurement teams are unbundling ownership from operational control, transferring residual value risk to specialized industrial asset financiers. This shift is most visible in China's Yangtze River Delta corridor, where state-backed leasing vehicles support capacity expansion without direct balance sheet loading for private component suppliers.
Hydroforming Press Market Segmentation
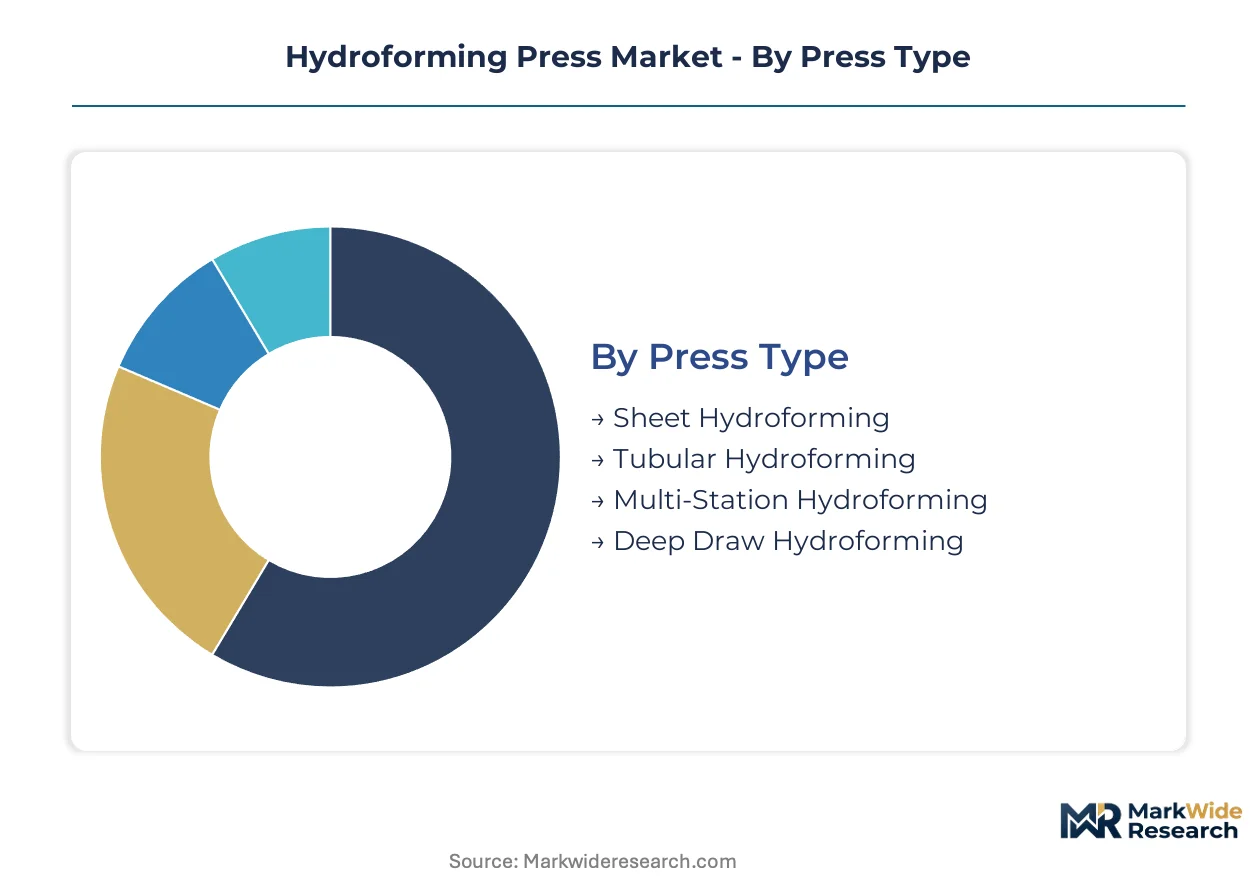
Hydroforming press segmentation reveals distinct technology-adoption curves across automotive, aerospace, and industrial equipment verticals. Each category maps equipment specifications to buyer sophistication tiers and regulatory compliance requirements.
Press Type:
Mature tubular configurations dominate installed bases while emerging multi-station architectures capture premium replacement cycles.
- Tubular Hydroforming:Shapes hollow metal tubes using internal fluid pressure against die cavities, producing exhaust manifolds and chassis rails with uniform wall thickness. China's Yangtze River Delta automotive corridor sustains dominant capacity utilization for commercial vehicle programs under domestic OEM localization mandates.
- Sheet Hydroforming:Applies fluid pressure to flat metal blanks for complex skin panels and structural components without stamping force concentration. German and Japanese automotive OEMs are expanding this capacity to meet EPA fuel-economy standards and EU CO2 fleet mandates through lightweight structural geometries.
- Multi-Station Hydroforming:Integrates sequential forming, trimming, and piercing operations in single press configurations for high-volume production lines.
- Deep Draw Hydroforming:Combines hydroforming pressure with deep drawing mechanics for extended wall-height components in appliance and agricultural equipment applications.
Tubular Hydroforming retains volume leadership; Sheet Hydroforming holds the steepest expansion curve.
Technology:
Cost tiers separate legacy hydraulic architectures from premium electromechanical and hybrid servo systems.
- Electromechanical System:Servo-driven presses deliver precision positioning with energy recovery and process repeatability for Tier-1 supplier facilities. EU F-Gas Regulation restrictions on hydraulic fluid emissions are accelerating displacement of conventional architectures across Italian and Spanish metal forming facilities.
- High-Pressure Pump:Generates forming pressures between 100 and 400 MPa through precision pump systems for aerospace-grade applications. Extended lead times for aerospace-qualified pump assemblies constrain capital deployment timelines for tier-2 fabrication workshops seeking AS9100 certification.
- Servo Valve:Enables variable pressure profiling and rapid response in hybrid hydraulic architectures.
- Hydraulic Intensifier:Multiplies available hydraulic pressure for specialized deep-draw and thick-wall forming operations.
Electromechanical System commands premium pricing tiers; High-Pressure Pump faces supply-constrained expansion.
Application:
Application mix tracks divergent margin structures between automotive volume production and aerospace qualification barriers.
- Commercial Vehicle Manufacturing:Exhaust system and chassis programs in China's Yangtze River Delta cluster anchor tubular hydroforming demand. India's PLI scheme incentives for domestic commercial vehicle production are creating underpenetrated demand for localized chassis fabrication capacity.
- Aerospace Component Fabrication:Skin panel and structural component production requires AS9100 certification with 18-24 month qualification cycles. AS9100 certification barriers limit accessible margin pools to incumbent certified operators with established prime contractor relationships.
- Appliance Shell Production:High-volume forming of refrigerator, washing machine, and HVAC enclosures using deep-draw and sheet configurations.
- Agricultural Equipment Fabrication:Structural component production for tractors and harvesters with lower precision requirements than automotive applications.
Commercial Vehicle Manufacturing retains volume leadership; Aerospace Component Fabrication holds the steepest expansion curve.
End User:
Customer type determines procurement sophistication from integrated OEM specifications to workshop retrofit economics.
- Tier-1 Suppliers:Automotive component manufacturers operate captive forming facilities with direct OEM engineering collaboration. Equipment leasing and project finance structures are displacing capital purchase models across German and Japanese Tier-1 facilities seeking balance sheet efficiency.
- OEM Manufacturers:Integrated automotive and aerospace producers specify multi-station and electromechanical systems for proprietary component production. OEM procurement teams are unbundling ownership from operational control, transferring residual value risk to specialized industrial asset financiers.
- Fabrication Workshops:Independent metal forming operations serving fragmented industrial demand with mid-capacity hydraulic presses.
- Industrial Equipment Makers:Captive forming operations for internal machinery and component production with lower utilization requirements.
Tier-1 Suppliers retain volume leadership; OEM Manufacturers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in hydroforming press equipment tilt toward surplus production in Germany and Japan against concentrated import demand across China's automotive manufacturing belt. Equipment trade patterns reflect specialized engineering capabilities clustering in mature industrial economies while emerging manufacturing bases absorb capacity expansion.
China
Domestic OEM localization mandates drive tubular hydroforming line installations for commercial vehicle exhaust and chassis fabrication. GB standards for industrial machinery safety impose compliance layers on imported press architectures and local production alike. The Yangtze River Delta automotive corridor anchors dominant capacity utilization, with state-backed leasing vehicles supporting private supplier expansion without direct balance sheet loading.
Germany
Automotive OEM engineering collaboration sustains premium multi-station system demand for lightweight structural component production. EU F-Gas Regulation restrictions on fluorinated greenhouse gas emissions in hydraulic systems accelerate electromechanical conversion investments across metal forming facilities. Bavaria and Baden-Württemberg host concentrated Tier-1 supplier engineering centers specifying servo-driven press architectures.
United States
EPA Corporate Average Fuel Economy requirements force automotive OEMs toward sheet hydroforming capacity for compliant chassis geometries. Tightened fuel-economy standards compress replacement cycles as Tier-1 suppliers abandon conventional hydraulic systems. Manufacturing corridors in Michigan and Ohio see active equipment leasing structures displacing traditional capital purchase models for large-capacity presses.
Japan
METI energy-efficiency directives shape equipment specifications for domestic automotive and aerospace fabrication bases. Japanese automotive OEMs expand sheet hydroforming capacity alongside German counterparts for lightweight structural programs. The Nagoya-Tokyo industrial belt sustains captive forming facility investments with direct OEM engineering integration.
India
PLI scheme incentives for domestic commercial vehicle production create underpenetrated demand for localized chassis fabrication capacity. Central government production-linked incentive structures reduce import dependence for tubular hydroforming line deployment. Maharashtra and Tamil Nadu automotive clusters attract preliminary equipment inquiries as OEMs localize exhaust and chassis programs.
Hydroforming Press Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in pump and valve supply chains. The vendor base organizes around three strategic archetypes: German-engineered multi-station system houses, Japanese precision equipment fabricators, and specialized high-pressure component suppliers. Competitive moves concentrate on servo-hydraulic hybrid architecture development and equipment leasing partnership structures that unbundle ownership from operational control.
Among Germany-based system integrators, Schuler AG and Siempelkamp Maschinen- und Anlagenbau GmbH occupy positions anchoring premium-tier automotive OEM specifications. Fagor Arrasate exemplifies the specialized tubular hydroforming line archetype serving European commercial vehicle manufacturers. These named entities represent distinct competitive positioning vectors without exhaustive market coverage.
| Leading Market Players |
|---|
| Schuler AG |
| Fagor Arrasate |
| Quintus Technologies |
| Kobe Steel Ltd. |
| Siempelkamp Maschinen- und Anlagenbau GmbH |
| ANDRITZ Schuler |
| American Hydroformers Inc. |
| Aerospace Metal Forming Technologies LLC |
| FluidForming Americas LLC |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor cost dynamics compress margins for European-engineered electromechanical press imports while amplifying price differentiation between servo-hydraulic hybrid architectures and legacy hydraulic systems across Tier-1 supplier procurement portfolios.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with electromechanical servo systems commanding premium positioning against conventional hydraulic alternatives. Price differentiation rests on AS9100 certification tier and after-sales service bundling, particularly for aerospace-grade pump assemblies. Cost compression in mid-capacity hydraulic tiers is intensifying because electromechanical conversion investments accelerate under EU F-Gas enforcement timelines. Tier-2 fabrication workshops exhibit highest price sensitivity, while aerospace OEM procurement teams prioritize certification compliance over unit cost.
Supply Chain Analysis
German and Japanese precision equipment fabricators hold dominant contract-manufacturing capacity for high-pressure pump systems and servo drive assemblies. Component sourcing draws from South Korea for precision electronics, Germany for engineered steel frames, and China for auxiliary hydraulic intensifiers. Single-source vulnerability concentrates in aerospace-qualified pump assemblies with extended qualification cycles. Distribution runs through specialized industrial asset financiers and state-backed leasing vehicles in China's automotive manufacturing belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical servo architectures threaten conventional hydraulic press installed bases, forcing incumbents to defend substitution-driven replacement cycles while capturing hybrid retrofit economics.
For Market Incumbents: Build certification moats around AS9100-qualified aerospace fabrication capacity to lock out tier-2 competitors from prime contractor relationships. Deepen backward integration into high-pressure pump manufacturing to reduce lead time exposure and capture margin from supply-constrained aerospace tiers. Electromechanical conversion investments in Italian and Spanish facilities preempt EU F-Gas obsolescence risk. For New Entrants and Emerging Players: Pursue India's PLI scheme commercial vehicle corridor as the most penetrable demand pocket for tubular hydroforming line localization. Target servo-hydraulic hybrid retrofit contracts among North American mid-cap fabrication workshops seeking energy efficiency without full electromechanical replacement. Go-to-market leverage rests on equipment leasing partnerships that transfer residual value risk from capital-constrained operators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized hydroforming press divisions lacking AS9100 certification or servo drive expertise. Long-term viability favors suppliers with documented lifecycle emission profiles aligned with emerging carbon border adjustment mechanisms. Monitor quarterly order intake from China's Yangtze River Delta state-backed leasing vehicles as inflection signal for capacity expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Hydraulic Hybrid Development | Combines electromechanical precision with hydraulic force capacity for German automotive OEM lightweight programs. |
| AS9100 Certification Investment | Opens aerospace skin panel fabrication margin pools with 18-24 month qualification barriers protecting incumbent returns. |
| Equipment Leasing Partnership | Transfers residual value risk to industrial asset financiers across China's Yangtze River Delta supplier base. |
| Backward Integration into Pumps | Reduces lead time exposure for aerospace-qualified high-pressure assemblies constraining tier-2 deployment. |
| India Manufacturing Localization | Captures PLI scheme incentives for commercial vehicle chassis and exhaust program expansion. |
Research Methodology
Desk research of customs trade data, SEC equipment manufacturer filings, and automotive production databases preceded structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors across Germany, Japan, China, and the United States. Primary fieldwork with Tier-1 supplier engineering centers and aerospace fabrication facilities validated secondary estimates through bottom-up capacity assessment and top-down market sizing triangulation.
Assumptions held fixed include EPA fuel-economy standard stringency, EU F-Gas Regulation enforcement timelines, and METI energy-efficiency directive compliance requirements across the analysis window. Segmentation modeling incorporated press type, technology architecture, application vertical, and end-user sophistication tier. CAGRs derived from equipment replacement cycle analysis, capacity utilization surveys, and localized OEM procurement pipeline tracking across automotive and aerospace manufacturing corridors.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, commercial vehicle demand cycles, or aerospace capital expenditure trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement cadence and technology substitution elasticities. Quarterly review of OEM platform engineering disclosures, state-backed leasing vehicle origination volumes, and AS9100 certification pipeline data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
United States Crane Market
Construction Equipment
Ground Engaging Tools (GET) Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Trenchers Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Europe Crane Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Hand Push Trencher Market
Construction Equipment
Global Hydraulic Hammer Market