
 Dynamic Compactor Market | 2026-2036
Dynamic Compactor Market Size, Share, and Industry Trends Forecast 2026-2036
Dynamic Compactor Market Analytics
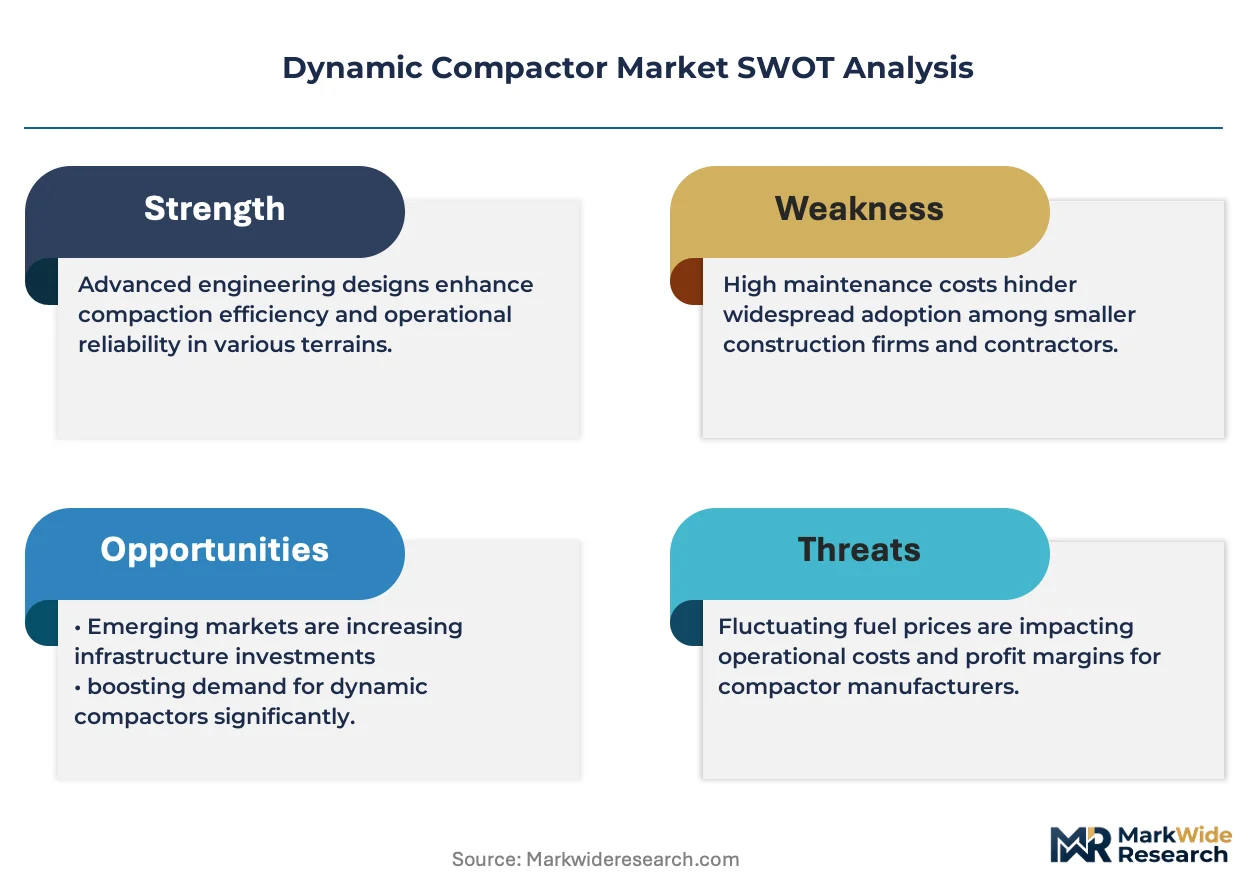
The gap between hydraulic and electric powertrain architectures is narrowing as battery energy density improves and thermal management systems mature. BOMAG leverages its German engineering heritage to sustain premium positioning in precision compaction for asphalt layers. XCMG anchors volume leadership through manufacturing scale and domestic supply chain integration across China. Caterpillar differentiates via global dealer networks and aftermarket parts ecosystems that lock in fleet operators.
A dynamic compactor is a mechanized soil and asphalt compaction machine that applies vibratory or impact force through a rotating eccentric mass or reciprocating ram to achieve specified Proctor density or Marshall stability values. These machines range from walk-behind plate compactors delivering 15-30 kN centrifugal force to ride-on double-drum units exceeding 200 kN, serving civil engineering applications where substrate bearing capacity determines structural longevity. Single drum variants dominate rough terrain and sub-base work where traction and penetration matter, while double drum configurations command premium pricing in finish paving due to surface smoothness requirements. Electric technology represents the fastest-growing segment as municipal contractors face zero-emission mandates in urban cores, though diesel hydraulic systems still occupy the majority of heavy-duty roadworks fleets.
EPA Tier 4 Final and EU Stage V emissions frameworks force engine redesigns and after-treatment add-ons that inflate base machine costs and push smaller rental houses toward equipment leasing. ISO Compaction Standards and national road agency specifications dictate vibration frequency, amplitude, and pass coverage metrics that manufacturers must certify before highway eligibility. Stakeholders must weigh powertrain transition timing against residual value risk in diesel-dominated secondary markets.
Market Dynamics
The transition from hydraulic to electric powertrains in heavy compaction equipment is compressing development cycles and forcing simultaneous investment in battery thermal management and vibration isolation engineering.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V:These emissions frameworks mandate after-treatment systems that accelerate fleet turnover toward cleaner powertrains. Municipal contractors in urban cores face zero-emission mandates that pull electric compactors into specification sheets.
- State-led infrastructure stimulus:China's sustained investment in highway and rail corridors sustains equipment replacement cycles. Provincial procurement programs prioritize domestic manufacturers with integrated supply chains.
- Battery energy density improvements:Lithium-ion cell chemistry advances enable 8-hour operational ranges in double-drum configurations. This technical threshold unlocks electric viability for finish paving where surface smoothness requirements demand continuous operation.
Market Restraints
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems add base machine costs that strain rental house margins. Smaller equipment lessors defer purchases or shift toward operating leases.
- Residual value risk in secondary markets:Diesel-dominated used equipment channels in India and Southeast Asia resist electric assets. Fleet operators face stranded asset exposure if powertrain transition timing misaligns with regional resale liquidity.
- ISO Compaction Standards certification timelines:Vibration frequency and amplitude validation protocols extend product launch schedules. Manufacturers must certify pass coverage metrics before highway eligibility, compressing competitive response windows.
Strategic Opportunities
- Zero-emission urban construction zones:London's Ultra Low Emission Zone and Paris's circulation restrictions create captive demand for electric compactors. Municipal contractors face operational bans on diesel equipment in city cores.
- Telematics-enabled predictive maintenance:Integration of vibration sensor data with cloud analytics platforms enables outcome-based service contracts. Fleet operators shift from time-based to condition-based maintenance scheduling.
- India's Bharatmala highway program:This road infrastructure initiative generates sub-base compaction demand for single-drum units. Domestic manufacturing incentives under the PLI scheme attract component localization investments.
Industry Challenges
- Electrification engineering talent scarcity:Competency in high-voltage system design and battery thermal management concentrates in automotive and consumer electronics sectors. Heavy equipment manufacturers compete for power electronics specialists.
- Dual powertrain platform development:Maintaining parallel hydraulic and electric product architectures strains R&D budgets. Engineering teams must sustain diesel refinement while accelerating electric product maturity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dynamic Compactor Market |
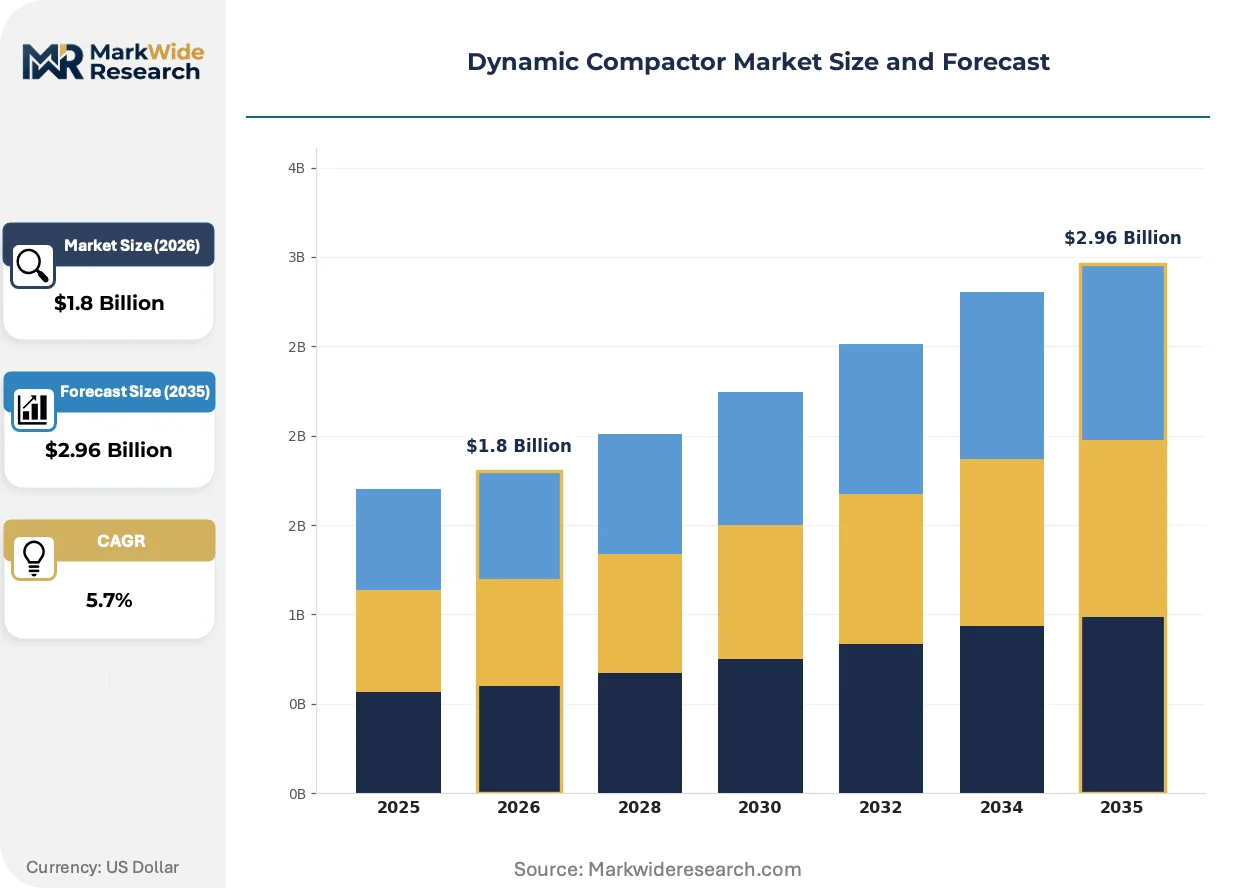
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Drum, Double Drum, Plate Compactors, Tamping Rammers Application: Construction, Roadworks, Landscaping, Utility Installation End User: Contractors, Construction Companies, Municipalities, Excavation Firms Technology: Hydraulic, Electric, Diesel, Pneumatic |
| Companies Covered | Ammann, XCMG, BOMAG, Dynapac, SANY, Caterpillar, Sakai Heavy Industries, Volvo Construction Equipment, Wirtgen Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dynamic Compactor Market Evolving Landscape
Digital twin technology and real-time compaction monitoring are virtualizing quality assurance workflows. Equipment manufacturers embed sensors that validate density specifications during the pass rather than through post-process testing.
Compaction control systems equipped with accelerometer arrays and GPS positioning are virtualizing the role of manual core sampling. Asphalt contractors in Germany and Japan adopt continuous compaction control to eliminate destructive testing delays. This technology is virtualizing quality verification from a laboratory function to an in-cab real-time display, compressing project timelines and reducing material waste.
EU Stage V and EPA Tier 4 Final regulations force engine downsizing and after-treatment integration that alter machine weight distribution. Manufacturers redesign drum frames to accommodate exhaust treatment hardware without compromising vibration isolation. Double-drum finish pavers in European markets absorb the highest compliance cost burden, prompting accelerated electric platform investment.
Rental channel consolidation is altering equipment access patterns. National rental chains in the United States and United Kingdom aggregate fleet purchasing power and standardize on telematics-enabled units. Independent rental houses lose specification influence as procurement centralizes under procurement departments optimizing total cost of ownership metrics across multi-site operations.
Dynamic Compactor Market Segmentation

Equipment specification in the dynamic compactor market follows substrate requirements and operational constraints. Segmentation reveals how powertrain choices, drum configurations, and end-user scale determine procurement patterns and service lifecycle economics.
Product Type:
Mature configurations dominate heavy roadworks while emerging formats penetrate specialized niches.
- Single Drum:These units employ a single oscillating drum with rear pneumatic tires to deliver high tractive force on unbound aggregates and cohesive soils. Highway contractors in China deploy single-drum machines for sub-base preparation on state-funded corridor projects where penetration depth exceeds surface finish priority.
- Double Drum:Tandem drum arrangements apply uniform compaction across asphalt layers with oscillating front and vibrating rear drums achieving surface regularity specifications. German road agencies mandate continuous compaction control systems on double-drum units for federal highway contracts, accelerating specification upgrades among municipal fleets.
- Plate Compactors:Walk-behind units with vibrating base plates service trench backfill and confined utility work where maneuverability constraints exclude ride-on equipment.
- Tamping Rammers:Vertical impact machines deliver high-amplitude blows for cohesive soil compaction in foundation pits and narrow excavations.
Single Drum retains volume leadership; Double Drum holds the steepest expansion curve.
Application:
Cost tier separation emerges between capital-intensive infrastructure and discretionary groundworks.
- Construction:Building foundation and structural pad preparation demands variable frequency control for cohesive and granular soil transitions. Japanese general contractors specify compaction meters with GPS logging to validate bearing capacity documentation for seismic code compliance.
- Roadworks:Highway and arterial paving operations require continuous operation capability across 8-hour shifts with surface smoothness validation. Battery-electric double-drum units are gaining specification in Paris and London urban cores where diesel bans now cover construction equipment.
- Landscaping:Residential and commercial ground finishing employs lighter plate compactors with lower centrifugal force ratings.
- Utility Installation:Trench reinstatement and pipeline bedding compaction prioritizes narrow-width machines for confined linear work.
Roadworks commands the premium equipment tier; Construction provides the broadest volume base.
End User:
Customer type determines procurement modality and service attachment rates.
- Contractors:Independent civil works operators balance fleet utilization across project portfolios with seasonal demand fluctuation. Rental channel dependence runs highest among this segment due to working capital constraints.
- Construction Companies:Integrated builders with multi-year project backlogs favor owned fleets with telematics integration for cross-site deployment optimization.
- Municipalities:City and county maintenance departments face zero-emission procurement mandates in EU jurisdictions, pulling electric compactors into formal tender specifications.
- Excavation Firms:Specialty earthmoving operators require single-drum units with high drawbar pull for cut-and-fill operations on uneven terrain.
Construction Companies dominate capital expenditure; Municipalities are expanding most quickly through green procurement mandates.
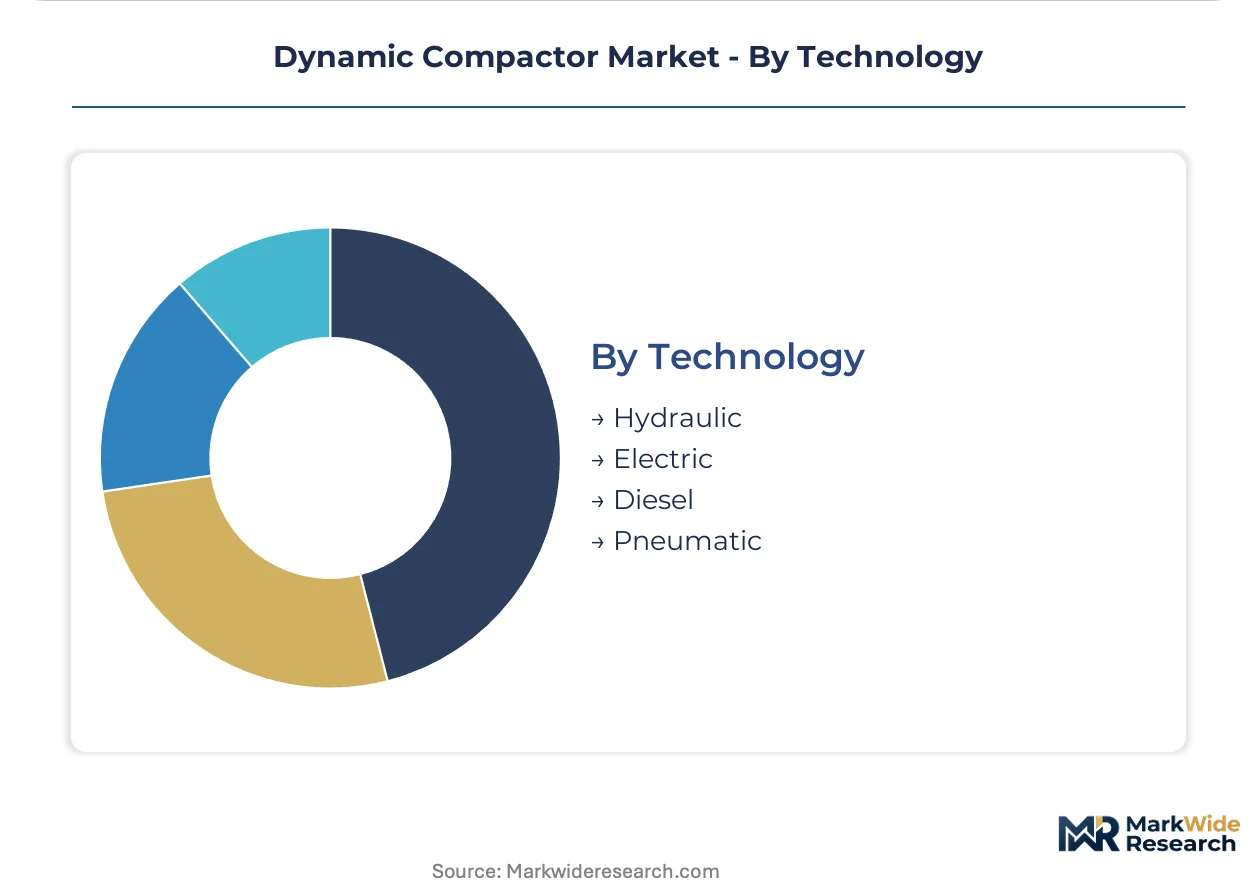
Technology:
Supply concentration in powertrain engineering creates divergent platform development paths.
- Hydraulic:Closed-loop hydrostatic transmissions deliver precise speed control and vibration modulation through variable displacement pumps. Legacy fleet dominance and technician familiarity sustain hydraulic specification among independent rental houses in secondary markets.
- Electric:Battery-electric architectures eliminate exhaust after-treatment while enabling regenerative braking from drum deceleration. Thermal management systems and high-voltage safety certification concentrate development resources in automotive supplier ecosystems.
- Diesel:Compression-ignition engines with DOC-DPF-SCR after-treatment chains remain standard for heavy-duty single-drum applications where refueling infrastructure and runtime duration outweigh emission compliance costs.
- Pneumatic:Compressed air power serves explosion-risk environments in petrochemical and mining sectors where spark ignition hazards prohibit internal combustion.
Diesel retains installed base dominance; Electric is climbing the fastest through urban emission zone expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision compaction systems to municipal contractors across Northern Europe. Chinese fabricators supply volume-oriented single-drum units throughout Southeast Asia and Africa. This trade-flow structure concentrates premium technology development in Western Europe while production scale advantages cluster in East Asia.
United States
Federal highway rehabilitation programs sustain fleet procurement among interstate contractors. EPA Tier 4 Final compliance deadlines force rental houses toward equipment leasing models. Texas and Florida DOT specifications increasingly reference telematics integration for density validation.
Germany
Continuous compaction control mandates on federal Autobahn contracts pull sensor-equipped double-drum units into specification. EU Stage V enforcement accelerates electric platform investment among municipal fleets. Baden-Württemberg engineering clusters concentrate vibration isolation and thermal management R&D.
China
Provincial infrastructure stimulus sustains equipment replacement cycles across highway and rail corridors. MIIT domestic content requirements favor integrated supply chain manufacturers. Xuzhou and Changzhou industrial bases anchor volume production for Belt and Road export markets.
India
Bharatmala highway corridor development generates sub-base compaction demand for high-drawbar single-drum units. PLI scheme incentives attract component localization investments. Gujarat and Maharashtra manufacturing zones concentrate fabrication capacity for domestic roadworks procurement.
Japan
Seismic code compliance drives precision compaction specification for foundation bearing capacity documentation. METI carbon neutrality roadmaps pull battery-electric units into urban construction tenders. Kanto and Kansai metropolitan contractors face diesel equipment restrictions in central business districts.
Dynamic Compactor Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement modalities. Consolidated rental chains aggregate fleet purchasing power and standardize on telematics-enabled units, while independent contractors rely on dealer networks for aftermarket service attachment. Three archetypes dominate: integrated construction equipment conglomerates with global distribution infrastructure, regional specialists with domestic supply chain integration, and precision engineering houses with premium positioning in finish paving applications. Competitive moves center on dual powertrain platform development and telematics-enabled service contract expansion.
Among German engineering houses, BOMAG GmbH and Wirtgen Group occupy positions within the precision-tier segment, exemplifying heritage-driven positioning in continuous compaction control specification. XCMG anchors the scale-driven archetype among Chinese manufacturers with integrated domestic supply chain control. Caterpillar Inc. represents the global-channel archetype through aftermarket parts ecosystem depth that locks in fleet operator loyalty across North American highway contractors.
| Leading Market Players |
|---|
| Ammann |
| XCMG |
| BOMAG |
| Dynapac |
| SANY |
| Caterpillar |
| Sakai Heavy Industries |
| Volvo Construction Equipment |
| Wirtgen Group |
| Others |
Value Network & Pricing Analysis
Xuzhou and Changzhou industrial clusters anchor global volume production for dynamic compactors, concentrating casting capacity and hydraulic component fabrication that grants integrated Chinese manufacturers asymmetric pricing leverage in export markets.
Pricing Analysis
Cost-plus contracts with steel and rare-earth indexation dominate procurement between OEMs and tier-one suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO compaction certification grade and telematics integration depth. Price erosion runs through standard-tier single-drum units as domestic Chinese capacity expansion floods Southeast Asian resale channels. Independent rental houses exhibit highest price sensitivity due to working capital constraints, while municipal fleets with green procurement mandates accept premium positioning for battery-electric configurations.
Supply Chain Analysis
High-grade steel plate and lithium-ion battery cells feed from China, Germany, and South Korea into compactor final assembly. Vibration isolation bearings and hydrostatic pump components draw from specialized automotive supplier ecosystems in Baden-Württemberg and Detroit. Single-source vulnerability concentrates in high-voltage power electronics and thermal management subsystems. Distribution runs through manufacturer-owned dealer networks for premium brands and consolidated rental chains for volume-tier equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final and EU Stage V emissions mandates are compressing powertrain transition timelines, creating asymmetric disruption windows where electric platform readiness determines competitive survival.
For Market Incumbents: Build aftermarket service moats through telematics-enabled predictive maintenance contracts that lock in fleet operator loyalty. Invest in battery thermal management R&D to defend against automotive supplier encroachment. Accelerate certification of dual powertrain architectures to hedge residual value risk in diesel-dominated secondary markets. For New Entrants and Emerging Players: India's Bharatmala highway corridors represent underpenetrated demand for high-drawbar single-drum units where domestic PLI incentives lower component localization barriers. Target municipal contractors in Paris and London urban cores facing diesel equipment bans. Pursue telematics-native positioning to bypass legacy dealer network dependencies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision-tier manufacturers with continuous compaction control certification and multi-year municipal service contracts. Long-term viability favors engineering houses with captive battery thermal management competency and integrated software stacks. Monitor EU Stage V enforcement acceleration and zero-emission zone expansion as inflection indicators for electric platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Powertrain Platform Development | Simultaneous diesel refinement and electric maturation hedges regulatory transition risk across EPA and EU jurisdictions. |
| Telematics-Enabled Service Contracts | Condition-based maintenance scheduling transforms equipment vendors into outcome-based fleet optimization partners. |
| Battery Thermal Management Investment | Automotive supplier ecosystem partnerships secure high-voltage engineering talent scarce in heavy equipment sectors. |
| Continuous Compaction Control Certification | German Autobahn mandates and Japanese seismic codes create specification barriers that premium-tier manufacturers exploit. |
| Component Localization Under PLI Schemes | India's production-linked incentives attract fabrication capacity for Bharatmala corridor procurement compliance. |
Research Methodology
Operator-level perspectives from fleet maintenance directors, municipal procurement officers, rental channel managers, and OEM aftermarket service heads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC equipment manufacturer filings, and national road agency specification databases. Bottom-up unit demand modeling triangulated against top-down infrastructure spending projections.
Scenario-bracketing around emissions enforcement timing and battery cost curves bounded the analytical framework across the projection horizon. Segmentation dimensions modeled include drum configuration, powertrain architecture, end-user scale, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and infrastructure stimulus flow-through rates incorporated vibration frequency specification upgrades and telematics penetration assumptions.
Practitioners should monitor EPA Tier 4 Final waiver extensions and EU zero-emission zone expansion calendars for early signals of powertrain transition acceleration. Forecasts reflect assumptions on battery energy density improvement trajectories and secondary market liquidity for diesel assets. Cross-checking against national highway agency procurement bid databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Push-Back Racking System Market
Material Handling Equipment
Hook Lifts and Skip Loaders Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Overhead Conveyor Systems Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Industrial Lift Ladder Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Hoist Market