
 Soil Compaction Equipment Market | 2026-2036
Soil Compaction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Compaction Equipment Market Analysis
Telematics-enabled fleet management is recalibrating what contractors purchase, shifting capital allocation from standalone machines to monitored uptime contracts. Caterpillar Inc. leverages its Cat Connect platform to anchor recurring service revenue alongside hardware sales. BOMAG GmbH specializes in oscillation drum technology, differentiating its rollers for sensitive urban compaction where vibration restrictions apply. Dynapac competes through manufacturing scale in Europe, sustaining cost positions across the roller segment.
Soil compaction equipment encompasses machines that apply static or dynamic force to densify soil, aggregate, or asphalt layers, with drum widths ranging from 500 mm on pedestrian plates to over 2,100 mm on tandem rollers, achieving densities specified by Proctor or modified Proctor test standards for structural fill and subgrade applications. The equipment serves primarily to eliminate voids, reduce settlement, and achieve load-bearing capacity in earthworks, roadbeds, and building foundations. Rollers dominate value capture given their centrality to highway and airfield projects, while electric technology represents the fastest-expanding category as battery energy density improvements enable cord-free operation in emission-restricted zones. Plate compactors remain a mature, margin-compressed segment where Chinese manufacturers occupy volume positions.
Federal EPA Tier 4 Final standards and corresponding CARB regulations in California constrain diesel engine configurations, pushing OEMs toward electric drivetrain development. ISO 13350 vibration emission standards and CE marking requirements under EU machinery directives shape product design for European market access. Stakeholders must monitor battery-swapping infrastructure buildout and local grid capacity constraints, as these determine where electric compaction fleets prove economically viable against conventional hydraulic alternatives.
Market Dynamics
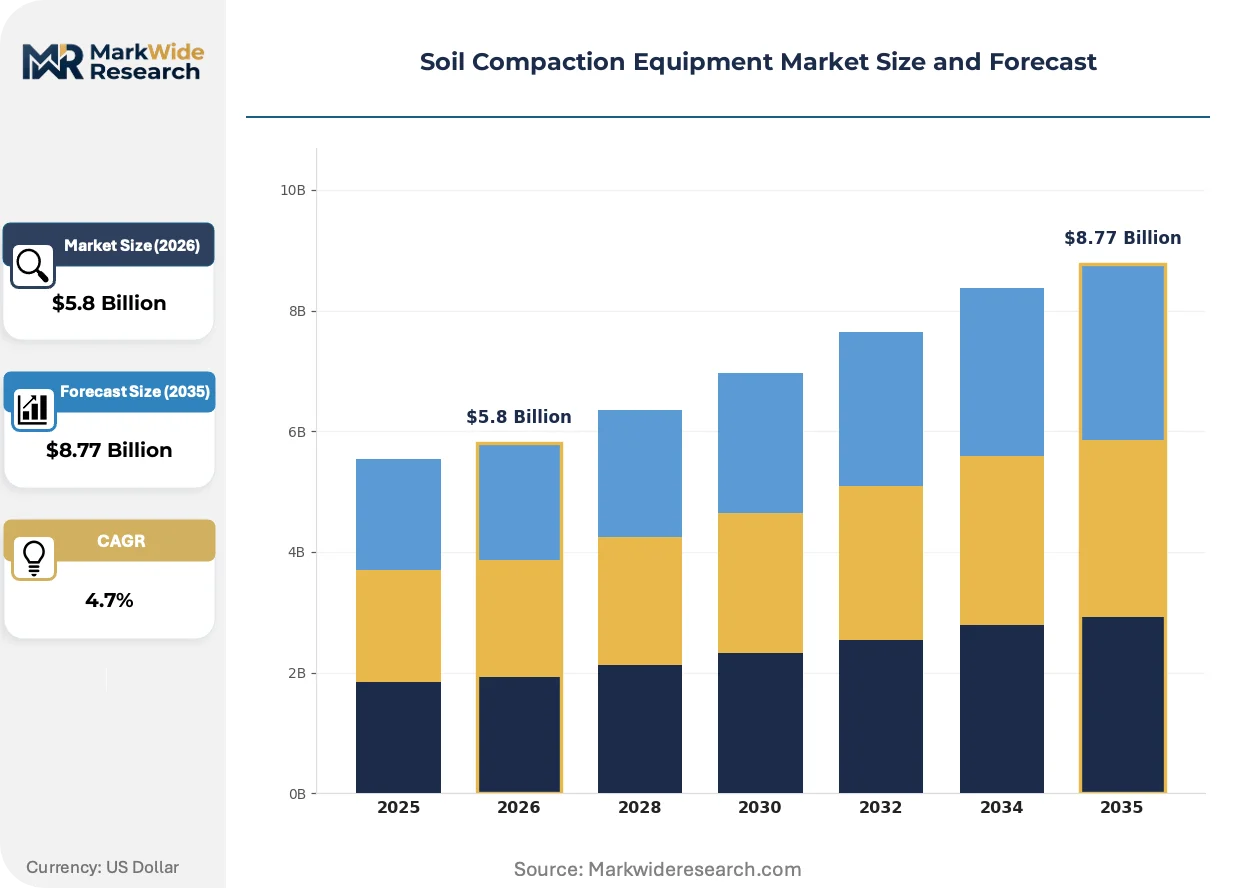
Electric drivetrain conversion is restructuring capital allocation across the soil compaction equipment sector, as battery-swapping architectures and grid-dependent operating economics displace conventional hydraulic powertrains in emission-restricted construction zones.
Growth Catalysts
- EPA Tier 4 Final:United States emission mandates are compelling fleet operators to retire older diesel rollers and adopt electric or hybrid alternatives for federal highway contracts.
- High-speed rail construction:China's ongoing rail expansion sustains concentrated demand for large-diameter tandem rollers capable of achieving specified subgrade densities across varied soil conditions.
- Oscillation drum technology:Urban compaction near sensitive infrastructure—hospitals, historic masonry, vibration-monitored utilities—creates specification pull for low-vibration compaction methods.
Market Restraints
- Battery cell cost volatility:Lithium-ion cathode material price swings compress electric roller margins and extend OEM payback periods for electrification R&D.
- Foundry capacity concentration:Cast iron drum manufacturing clusters in select industrial regions create single-source vulnerability for roller shell supply.
- Grid infrastructure gaps:Rural construction sites in India and Southeast Asia lack sufficient electrical capacity to support battery-charging or swapping operations.
Strategic Opportunities
- EU Green Deal construction incentives:Carbon-neutral public works procurement criteria in Germany and France favor electric compaction fleets with verified lifecycle emissions data.
- Telematics-anchored service contracts:Predictive maintenance platforms enable OEMs to capture recurring revenue through uptime-guarantee arrangements rather than discrete equipment sales.
- Modular battery architecture:Standardized swappable packs across roller classes reduce fleet downtime and allow contractors to scale energy capacity to project duration.
Industry Challenges
- Certification timeline compression:CE marking under EU machinery directives and concurrent EPA verification for US market entry strain engineering resources at mid-scale OEMs.
- Electrification skill gaps:Field service technician shortages for high-voltage battery systems and power electronics delay repair turnaround times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Compaction Equipment Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plate Compactors, Rollers, Rammers, Tamping Equipment End User: Construction Companies, Landscaping Firms, Road Maintenance, Earthwork Contractors Technology: Hydraulic, Mechanical, Pneumatic, Electric Application: Paving, Trenching, Backfilling, Foundation Work |
| Companies Covered | Wacker Neuson SE, Dynapac, Caterpillar Inc., J.C. Bamford Excavators Limited, Hamm AG, BOMAG GmbH, Ammann Group Holding AG, Terex Corporation, Volvo Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Compaction Equipment Market Emerging Trajectories
Battery-electric propulsion architectures are recalibrating equipment design priorities, shifting engineering focus from engine thermal management to thermal runaway prevention and charge-cycle optimization in variable terrain applications.
Intelligent compaction systems integrating accelerometer-based density measurement with GPS mapping is overtaking traditional spot-test verification methods. European highway agencies now specify continuous compaction control for asphalt layers, forcing contractors to spec rollers with onboard documentation capability. This shift compresses demand for standalone nuclear density gauges and redirects rental revenue toward integrated machine-intelligence packages.
EPA Tier 4 Final and corresponding CARB regulations in California are eliminating non-road diesel engine configurations below 56 kW from new equipment sales. OEM engineering resources have pivoted toward electric motor integration and battery thermal management, with compliance deadlines compressing development cycles. The tandem roller segment faces the steepest redesign burden given power demands and weight constraints.
Contractor procurement preferences are fragmenting between ownership and managed fleet services, with large infrastructure developers favoring full-service leases bundling equipment, telematics, and maintenance. Germany's construction sector shows the most pronounced shift, where municipal clients now require documented equipment utilization rates as contract performance metrics. This pressures traditional distributors to build service capabilities or cede share to OEM-direct fleet management programs.
Soil Compaction Equipment Market Segmentation
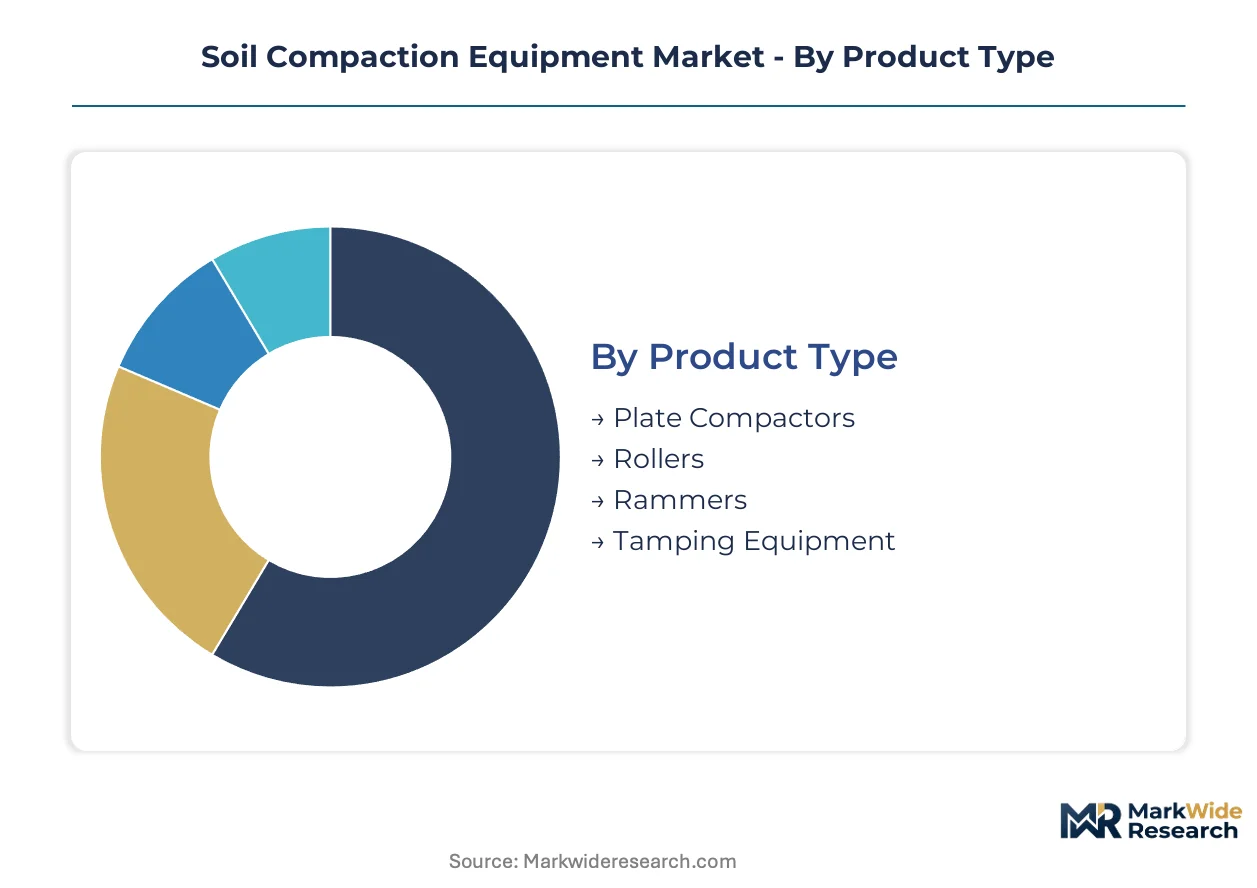
Segmentation in soil compaction equipment determines capital allocation, service bundling, and fleet replacement cycles. Contractors select machine classes based on project scale, emission zone restrictions, and density verification requirements. OEMs structure product portfolios around these divides to capture recurring revenue through differentiated service attachments.
Product Type:
Rollers command the highest capital intensity, requiring foundry investment for drum shells and precision machining for vibration systems. Plate compactors and rammers occupy lower equipment cost tiers with faster depreciation schedules.
- Rollers:Tandem and single-drum configurations achieve specified Proctor densities across highway subgrades and airfield runways. Demand concentrates in China's high-speed rail corridors where large-diameter drums prove essential for clay-heavy soils under time-bound contracts.
- Plate Compactors:Pedestrian-operated units with centrifugal force ratings from 10-30 kN handle trench backfill and landscaping finish work. Landscaping firms in Germany's municipal greening programs specify low-emission electric plates to meet EU Green Deal procurement criteria.
- Rammers:Vertical-impact machines deliver high compaction energy in confined utility trenches. Earthwork contractors deploy rammers where drum access is restricted by adjacent structures or underground utilities.
- Tamping Equipment:Manual and ride-on variants serve remote sites lacking grid infrastructure for electric alternatives. Road maintenance crews in rural India rely on tamping equipment where battery-charging capacity remains unavailable.
Most installed capacity flows through rollers. Expansion is steepest in electric plate compactors.
End User:
Application scale and fleet ownership models differentiate end user economics. Large developers favor full-service leases while specialty contractors prioritize equipment mobility across dispersed sites.
- Construction Companies:General contractors operating across commercial and residential verticals maintain diversified compaction fleets. Telematics-anchored service contracts from Caterpillar's Cat Connect platform reshape their procurement toward uptime guarantees rather than discrete purchases.
- Road Maintenance:Federal and state agencies in the United States face EPA Tier 4 Final mandates accelerating diesel fleet retirement. These public entities specify electric rollers for federal highway contracts with documented lifecycle emissions.
- Earthwork Contractors:Specialists in structural fill and foundation preparation require density verification systems. Continuous compaction control specifications from European highway agencies force these contractors toward intelligent roller investments.
- Landscaping Firms:Smaller operators prioritize maneuverability and noise restrictions near residential zones. Oscillation drum technology from BOMAG GmbH addresses their vibration-sensitive urban applications.
Construction companies deploy the broadest equipment mixes. Road maintenance agencies show the fastest procurement acceleration.
Technology:
Powertrain selection determines regulatory compliance, operating cost structure, and field service requirements. Electric architectures demand new technician competencies and charging infrastructure.
- Electric:Battery-powered drivetrains eliminate exhaust emissions and reduce noise signatures in urban construction zones. Grid capacity constraints in rural India and Southeast Asia limit viable deployment to electrified corridors.
- Hydraulic:Conventional fluid-power systems dominate current installed base with established service networks. EPA Tier 4 Final standards in the United States and CARB regulations in California constrain new diesel hydraulic sales below 56 kW.
- Mechanical:Direct-drive systems persist in low-cost plate compactors and tamping equipment. Chinese manufacturers occupy volume positions in this margin-compressed segment.
- Pneumatic:Compressed-air systems serve specialized applications requiring spark-free operation. Refinery and chemical plant construction in the United States specifies pneumatic compaction for hazardous area compliance.
Hydraulic systems retain the largest installed base. Electric drivetrains are climbing the fastest.
Application:
Soil conditions, layer thickness, and verification standards shape equipment specification for each application type. Density testing protocols determine whether continuous monitoring or spot validation suffices.
- Paving:Asphalt compaction requires uniform temperature maintenance and specified air void elimination. European highway agencies now mandate continuous compaction control documentation, displacing standalone nuclear density gauges.
- Foundation Work:Structural fill beneath buildings demands Proctor-standard density across variable soil profiles. Accelerometer-based measurement systems integrate with GPS mapping for quality assurance.
- Trenching:Narrow excavations for utilities restrict equipment width and turning radius. Rammers and small plates dominate where roller drum geometry prevents access.
- Backfilling:Pipeline and cable trenches require layered compaction to prevent settlement. Dynapac's European manufacturing scale supports cost-competitive roller supply for utility contractors.
Paving applications absorb the most roller capacity. Foundation work is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's high-speed rail corridors absorb more large-diameter tandem rollers than Germany's federal highway maintenance programs, yet both markets now specify emission-compliant drivetrains under tightening environmental mandates.
United States
Federal highway contracts drive fleet procurement across state transportation departments. EPA Tier 4 Final standards compel diesel roller retirement below 56 kW, accelerating electric and hybrid adoption. Equipment distributors in Texas and California anchor aftermarket service networks for telematics-integrated compaction fleets.
Germany
Municipal construction clients mandate documented equipment utilization rates as contract performance metrics. EU Green Deal procurement criteria favor electric compaction fleets with verified lifecycle emissions data. Manufacturing clusters in North Rhine-Westphalia sustain precision machining capabilities for oscillation drum systems.
China
High-speed rail expansion across clay-heavy subgrades sustains concentrated demand for large-diameter tandem rollers. MIIT industrial standards shape domestic equipment specifications for infrastructure resilience. Yangtze River Delta construction equipment manufacturers scale battery-electric roller production for urban emission zones.
India
Rural road construction under the Pradhan Mantri Gram Sadak Yojana sustains demand for cost-optimized compaction equipment. Grid infrastructure gaps in Maharashtra and Gujarat limit electric roller deployment to electrified highway corridors. Domestic fabricators in Tamil Nadu occupy volume positions in the plate compactor segment.
United Arab Emirates
NEOM and Red Sea Project developments specify intelligent compaction systems with GPS-mapped density verification. MOHAP construction safety regulations align with ISO vibration emission standards for worker protection. Equipment leasing operations in Dubai anchor full-service fleet management contracts for mega-project developers.
Soil Compaction Equipment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs capturing premium roller positions while regional fabricators dominate plate compactor volumes. Market structure tilts toward consolidation in large-diameter tandem rollers where foundry investment and precision machining create entry barriers. Three archetypes define competitive positioning: telematics-anchored service platforms, oscillation drum technology specialists, and scale-driven European manufacturers. Dominant competitive moves include strategic partnerships for battery-swapping infrastructure and portfolio diversification into electric drivetrain architectures.
Within the telematics-integrated tier, Caterpillar Inc. and Volvo Construction Equipment represent platform-anchored service models, while BOMAG GmbH exemplifies specialization in low-vibration compaction technologies. Dynapac occupies a position among scale-driven European manufacturers sustaining cost positions through manufacturing concentration. These three anchors illustrate how competitive positioning fragments between recurring revenue platforms, technical differentiation, and production scale.
| Leading Market Players |
|---|
| Wacker Neuson SE |
| Dynapac |
| Caterpillar Inc. |
| J.C. Bamford Excavators Limited |
| Hamm AG |
| BOMAG GmbH |
| Ammann Group Holding AG |
| Terex Corporation |
| Volvo Construction Equipment |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final emission mandates gate qualified supply access and premium-tier pricing power, restricting diesel hydraulic configurations below 56 kW while elevating electric drivetrain equipment to premium positioning. Contractors seeking federal highway contracts must absorb higher capital costs for compliant fleets, compressing margin structures for mid-tier hydraulic alternatives.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for battery-electric rollers, intensifying cost competition against European precision-machined alternatives. Pricing stratifies across premium intelligent compaction systems with GPS-mapped density verification, standard EPA-compliant electric rollers, and economy mechanical plate compactors where Chinese fabricators dominate. Cost compression in the mechanical tier stems from lithium-ion cathode material volatility and foundry capacity bottlenecks for drum shells. Small landscaping firms and rural Indian contractors exhibit highest price sensitivity, while German municipal clients prioritize lifecycle emissions documentation over acquisition cost.
Supply Chain Analysis
Precision machining workforce availability in Germany's North Rhine-Westphalia and foundry labor pools in China's Jiangsu province anchor roller drum manufacturing concentration. Supply chains draw from cast iron feedstock in select industrial regions, high-grade steel for vibration systems, and lithium-ion battery cells from East Asian chemical suppliers. Single-source vulnerability for roller shell foundries creates procurement risk during demand surges. Distribution runs through OEM-direct fleet management programs in Germany and independent equipment distributors in Texas and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between emission-mandated premium pricing in Germany and cost-optimized mechanical equipment demand in rural India, with regulatory divergence creating divergent margin structures across identical product categories.
For Market Incumbents: Extend telematics-anchored service contracts to capture recurring revenue from infrastructure developers favoring uptime guarantees over discrete purchases. Counter battery cell cost volatility through backward integration into modular battery architecture standardization. Certification investment in CE marking and EPA Tier 4 Final verification creates defensive moats against mid-scale OEM engineering resource constraints. For New Entrants and Emerging Players: Equipment-as-a-service digital platforms offer white-space entry into municipal fleet management contracts where documented utilization rates determine vendor selection. Target electric plate compactor segments for landscaping firms under EU Green Deal procurement criteria. Pursue direct channel partnerships with high-speed rail contractors in China's clay-heavy subgrade corridors. For Investors and Strategic Acquirers: Roll-up economics work for regional telematics-integrated service platforms because contractor procurement fragmentation between ownership and managed fleet services creates consolidation opportunities. Five-to-ten year viability hinges on battery-swapping infrastructure buildout pace. Monitor grid capacity expansion in Maharashtra and Gujarat as inflection indicator for electric roller deployment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Architecture Development | Standardized swappable packs reduce fleet downtime across roller classes in emission-restricted zones. |
| Telematics Platform Integration | Cat Connect-style uptime contracts displace discrete sales with recurring service revenue streams. |
| Oscillation Drum Technology Licensing | Low-vibration compaction methods access urban hospital and historic masonry adjacency specifications. |
| Foundry Capacity Expansion | Precision-machined drum shell supply security addresses single-source vulnerability in roller manufacturing. |
| Intelligent Compaction System Deployment | GPS-mapped density verification meets European highway agency continuous compaction control mandates. |
Methodological Framework
Direct dialogue with fleet procurement managers at state transportation departments, aftermarket service heads at equipment distributors, plant engineers at foundry operations, and telematics platform engineers grounded qualitative insights. Secondary validation drew from EPA certification filings, MIIT industrial standard disclosures, EU machinery directive documentation, and customs records of compaction equipment trade flows. Bottom-up equipment shipment analysis and top-down infrastructure investment allocation models were triangulated.
Bottom-up modeling segmented volume and value across product type, powertrain technology, application, and end-user archetype throughout the forecast period. CAGRs were derived from equipment replacement cycle analysis, emission mandate compliance deadlines, and infrastructure resilience spending trajectories. Intelligent compaction system penetration rates and battery energy density improvement curves served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for battery-electric propulsion in grid-constrained rural markets would alter the outlook. Forecasts reflect assumptions regarding lithium-ion cost trajectories, foundry capacity expansion, and highway agency specification evolution. Material deviation in battery cell pricing volatility or grid infrastructure buildout pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mini Excavators Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Turkey Construction Equipment Market
Construction Equipment
Bale Openers Market
Construction Equipment
BRICS Aerial Work Platforms Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Compressed Earth Block Machine Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Europe Air Compressor Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Industrial Grout Pumps Market