
 Mexico Flexible Concrete Vibrator Market | 2026-2036
Mexico Flexible Concrete Vibrator Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Flexible Concrete Vibrator Market Insights
Infrastructure development across Mexico is rebalancing demand toward highway, bridge, and water-treatment projects that require extended vibration cycles and remote-site portability. Wacker Neuson SE leverages its established rental-service network to anchor supply in major metropolitan zones. Enar Group competes through specialized electric-vibrator designs optimized for residential slab work. Multiquip Inc. extends its position via distributor partnerships that reach mid-sized contractors in Guadalajara and Monterrey.
A flexible concrete vibrator is a portable, shaft-driven compaction device that transmits oscillatory energy through a flexible rubber or steel-reinforced hose to a vibrating head, typically operating at frequencies between 10,000 and 15,000 vibrations per minute to eliminate voids in poured concrete. Its primary industrial purpose is to ensure structural integrity and surface finish quality in columns, beams, slabs, and precast elements. Electric vibrators dominate the product-type landscape due to reliable grid access on urban job sites, while battery-powered vibrators represent the fastest-expanding segment as contractors seek cord-free operation on sprawling infrastructure footprints. Within applications, construction commands the largest volume pool, though infrastructure development is capturing disproportionate margin growth through specification-grade procurement tied to federal project standards.
CONAPO workforce-safety directives and NOM-004-STPS-1999 vibration-exposure limits shape equipment design and operator-training requirements across Mexican job sites. The Secretaría de Comunicaciones y Transportes imposes material-quality benchmarks on federally financed infrastructure that cascade into contractor equipment-selection criteria. Stakeholders must monitor forthcoming amendments to Mexico's national building code and energy-efficiency labeling rules that could redirect procurement toward battery-powered and low-emission pneumatic systems.
Market Dynamics
Federally funded infrastructure corridors across Mexico's northern border states are compressing contractor equipment replacement cycles toward battery-powered and pneumatic vibrators that satisfy emission protocols and remote-site deployment requirements.
Growth Catalysts
- NOM-004-STPS-1999 vibration-exposure limits:Mandatory operator-safety thresholds are accelerating fleet turnover toward low-vibration electric and battery-powered units that reduce workplace liability exposure.
- Highway and bridge construction:SCT-financed transportation corridors demand extended vibration cycles and portable equipment configurations suited to remote concrete pours.
- Battery chemistry advances:Lithium-ion power density improvements are enabling cord-free operation on sprawling infrastructure footprints previously dependent on generator-tethered pneumatic systems.
Market Restraints
- Steel-reinforced hose input costs:Volatility in rubber and steel commodity pricing compresses manufacturer margins on mid-tier equipment lines.
- Import dependency for electronic controllers:Concentrated sourcing of variable-frequency drive components from Asian suppliers creates lead-time vulnerability for domestic assemblers.
- Pneumatic infrastructure limitation:Compressed-air system availability constraints on scattered rural job sites restrict pneumatic vibrator deployment outside established industrial zones.
Strategic Opportunities
- Baja California and Sonora water-treatment facilities:Federal CONAGUA investment programs are creating specification-grade procurement pools for corrosion-resistant vibrator designs.
- Rental-service channel expansion:Equipment-as-access models are penetrating mid-sized contractor segments in Guadalajara and Monterrey metropolitan zones.
- CONAPO workforce-certification mandates:Mandatory operator-training requirements are creating aftermarket service and recertification revenue streams for distributor networks.
Industry Challenges
- Certification timeline compression:NOM energy-efficiency labeling amendments are forcing manufacturers to accelerate product requalification cycles ahead of enforcement deadlines.
- Integration complexity with legacy formwork systems:New battery-powered vibrator head geometries require adaptation of existing concrete-placement workflows on established contractor sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Flexible Concrete Vibrator Market |
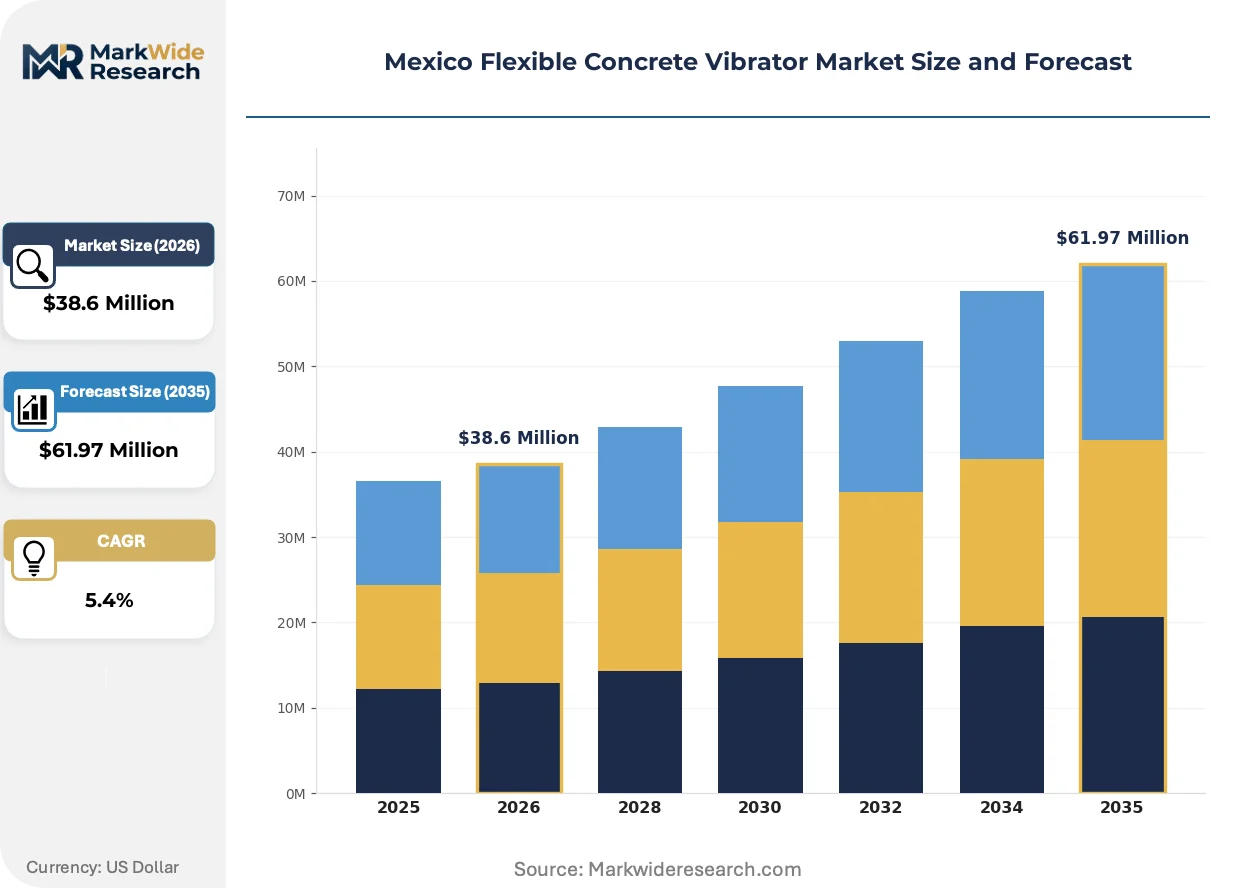
| Market Size in 2026 | $38.6 Million |
| Market Size in 2035 | $61.97 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Vibrators, Pneumatic Vibrators, Battery-Powered Vibrators, Hydraulic Vibrators Application: Construction, Infrastructure Development, Residential Projects, Industrial Applications End User: Contractors, Builders, Construction Companies, DIY Enthusiasts Distribution Channel: Online Retail, Direct Sales, Distributors, Hardware Stores |
| Companies Covered | Enar Group, Vibco Inc., Wacker Neuson SE, Badger Meter, Inc., WAMGROUP, Atlas Copco AB, Exen Group, Oztec Industries, Multiquip Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Flexible Concrete Vibrator Market Trends and Innovations
Equipment intelligence and power-system electrification are converging to redefine jobsite productivity metrics and maintenance protocols across Mexican concrete placement operations.
Brushless DC motor technology is integrating variable-frequency control into portable vibrator heads, enabling real-time amplitude adjustment based on concrete slump conditions. Highway contractors on SCT projects are adopting these units to standardize consolidation quality across pour sequences. The technology is integrating predictive maintenance algorithms that flag bearing-wear patterns before field failure, compressing unplanned downtime on critical-path infrastructure schedules.
Secretaría de Comunicaciones y Transportes material-quality benchmarks are cascading into contractor equipment-selection criteria that privilege traceable vibration-performance documentation. Federally financed bridge and water-treatment projects now require equipment calibration certificates that pneumatic legacy fleets cannot readily supply. Battery-powered and electric vibrator lines with integrated data-logging capability are capturing disproportionate specification-grade procurement volume in northern border state corridors.
Equipment procurement is consolidating through distributor rental-service agreements that unbundle capital expenditure from project cash-flow cycles. Mid-sized contractors in Monterrey and Guadalajara metropolitan zones are shifting from ownership to access-based models that include preventive maintenance and operator certification. This behavioral pivot is most visible in infrastructure verticals where project duration uncertainty makes fleet ownership risk-prohibitive.
Mexico Flexible Concrete Vibrator Market Segmentation
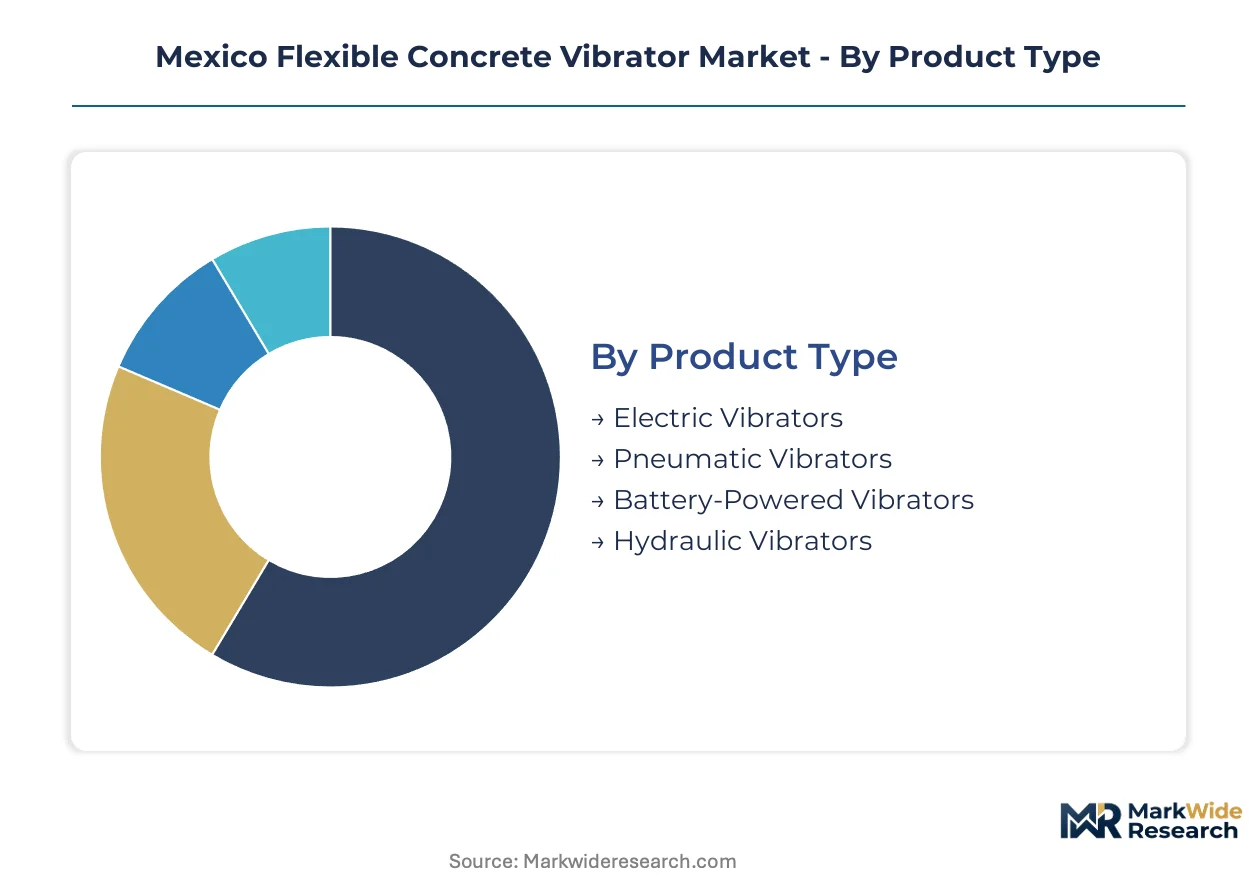
Equipment specification in the Mexican concrete vibration market diverges sharply between high-volume urban construction and margin-rich federal infrastructure projects. Procurement patterns across product types, applications, and distribution channels reflect this bifurcation, with contractors optimizing for either capital efficiency or specification compliance.
Product Type:
Electric vibrators anchor volume procurement through established grid infrastructure on metropolitan job sites, while battery-powered units command premium positioning in remote federal corridors.
- Electric Vibrators:Mains-powered units operating at 10,000-15,000 VPM dominate urban construction through reliable performance and lower capital outlay. Demand concentrates in Mexico City and Guadalajara metropolitan zones where grid access eliminates generator dependency.
- Battery-Powered Vibrators:Lithium-ion systems deliver cord-free operation critical to SCT-financed highway and bridge projects across Chihuahua and Sonora. CONAPO vibration-exposure compliance and emission protocols in northern border states are accelerating fleet replacement toward these units.
- Pneumatic Vibrators:Compressed-air systems maintain position in precast yard operations with existing compressor infrastructure.
- Hydraulic Vibrators:Heavy-duty units serve specialized dam and tunnel applications requiring sustained high-amplitude vibration cycles.
Mature deployment sits with Electric Vibrators. Newer deployment is concentrated in Battery-Powered Vibrators.
Application:
Construction absorbs the highest equipment volume through repetitive slab and column work, yet infrastructure development extracts disproportionate margin through specification-grade procurement tied to federal standards.
- Construction:Commercial and institutional building projects drive baseline demand for portable vibration equipment across Mexico's urban centers. NOM-004-STPS-1999 compliance requirements are filtering equipment selection toward low-vibration electric and battery-powered configurations on federally adjacent sites.
- Infrastructure Development:SCT-financed transportation corridors and CONAGUA water-treatment facilities require extended vibration cycles and documented performance calibration. Bridge deck consolidation and remote concrete pours in Baja California and Sonora favor battery-powered portability.
- Residential Projects:Single-family and low-rise development sustains demand for cost-optimized electric vibrators through distributor rental channels.
- Industrial Applications:Manufacturing floor slabs and heavy equipment foundations specify high-frequency units with integrated data-logging capability.
Volume leadership rests with Construction. Steepest expansion trajectory belongs to Infrastructure Development.
End User:
Mid-sized contractors in Monterrey and Guadalajara are shifting from equipment ownership to rental-service models that bundle maintenance and operator certification.
- Contractors:Project-based operators dominate procurement volume through distributor partnerships and rental-service agreements. CONAPO workforce-certification mandates are creating aftermarket revenue streams for training and recertification services.
- Construction Companies:Large integrated firms maintain owned fleets with preventive maintenance protocols and specification-grade documentation for federal project bidding.
- Builders:Residential-focused operators favor cost-efficient electric vibrators through hardware store and online retail channels.
- DIY Enthusiasts:Limited segment concentrated in small-scale residential renovation with entry-level equipment specifications.
Established procurement patterns sit with Construction Companies. Behavioral shift toward access-based models is concentrated in Contractors.
Distribution Channel:
Capital constraints on mid-sized operators are compressing direct sales volume toward rental-service and distributor arrangements that unbundle ownership from project cash flows.
- Distributors:Regional networks in Guadalajara, Monterrey, and Mexico City metropolitan zones anchor equipment access for mid-tier contractors. Wacker Neuson SE and Multiquip Inc. leverage these partnerships to reach specification-grade procurement pools.
- Direct Sales:Large construction companies and federal project contractors source calibrated equipment with traceable performance documentation directly from manufacturers.
- Online Retail:E-commerce penetration remains limited to entry-level electric vibrators for residential builders and small contractors.
- Hardware Stores:Local supply outlets serve emergency replacement and small-project demand with limited technical support capability.
Traditional volume sits with Distributors. Channel experimentation is concentrated in Direct Sales with integrated service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of flexible concrete vibrators concentrates in industrial manufacturing corridors, while consumption patterns diverge sharply between metropolitan construction zones and federally funded infrastructure corridors across Mexico's sub-regions.
Mexico City Metro
Urban densification and commercial high-rise construction drive electric vibrator procurement through established grid infrastructure. CONAPO workforce-safety directives enforce NOM-004-STPS-1999 compliance on major job sites. The metropolitan zone anchors distributor networks for Wacker Neuson SE and Multiquip Inc., serving mid-tier contractors through rental-service agreements.
Nuevo León
Monterrey's industrial expansion and cross-border manufacturing facilities sustain demand for specification-grade equipment with traceable calibration documentation. SCT-financed transportation corridors linking to Texas border crossings require battery-powered portability for remote concrete pours. The state represents the strongest penetration of equipment-as-access models among mid-sized contractors.
Jalisco
Guadalajara metropolitan growth and technology park construction favor low-vibration electric units compliant with updated NOM construction standards. Federal infrastructure adjacent to the city drives procurement toward documented performance equipment. Distributor partnerships in this zone reach residential builders shifting from ownership to rental channels.
Northern Border States
Chihuahua, Sonora, and Baja California host CONAGUA water-treatment investments and SCT highway corridors demanding extended vibration cycles. Emission protocols and remote-site requirements accelerate fleet turnover toward battery-powered and pneumatic systems. Corrosion-resistant vibrator designs capture specification-grade procurement in these federally prioritized zones.
Bajío Region
Querétaro and Guanajuato automotive supplier parks and logistics hubs generate industrial floor slab demand with integrated data-logging requirements. Manufacturing foreign direct investment brings stringent equipment documentation standards. The region shows emerging adoption of predictive maintenance-enabled vibrator systems for critical-path project schedules.
Mexico Flexible Concrete Vibrator Market Competitive Landscape
Top-tier vendors anchor specification-grade procurement on federally funded infrastructure, while mid-market distributors and rental-service networks capture volume construction demand. The competitive structure stratifies across three archetypes: integrated multinational equipment manufacturers with calibration-certification capabilities, specialized vibrator designers optimized for residential and light commercial work, and regional distributor partnerships bundling maintenance with operator training. Capacity expansion through rental-fleet growth and strategic partnerships for aftermarket service coverage represent the dominant competitive moves.
Among the established multinational tier, Wacker Neuson SE anchors supply through its rental-service network penetration in major metropolitan zones. Enar Group occupies a position exemplifying specialized electric-vibrator design focused on residential slab applications. Multiquip Inc. represents the distributor-partnership archetype, extending market reach through arrangements targeting mid-sized contractors in Guadalajara and Monterrey. These three entities collectively illustrate the competitive segmentation between premium specification-grade positioning and volume-oriented access models.
| Leading Market Players |
|---|
| Enar Group |
| Vibco Inc. |
| Wacker Neuson SE |
| Badger Meter, Inc. |
| WAMGROUP |
| Atlas Copco AB |
| Exen Group |
| Oztec Industries |
| Multiquip Inc. |
| Others |
Pricing and Supply Chain Analysis
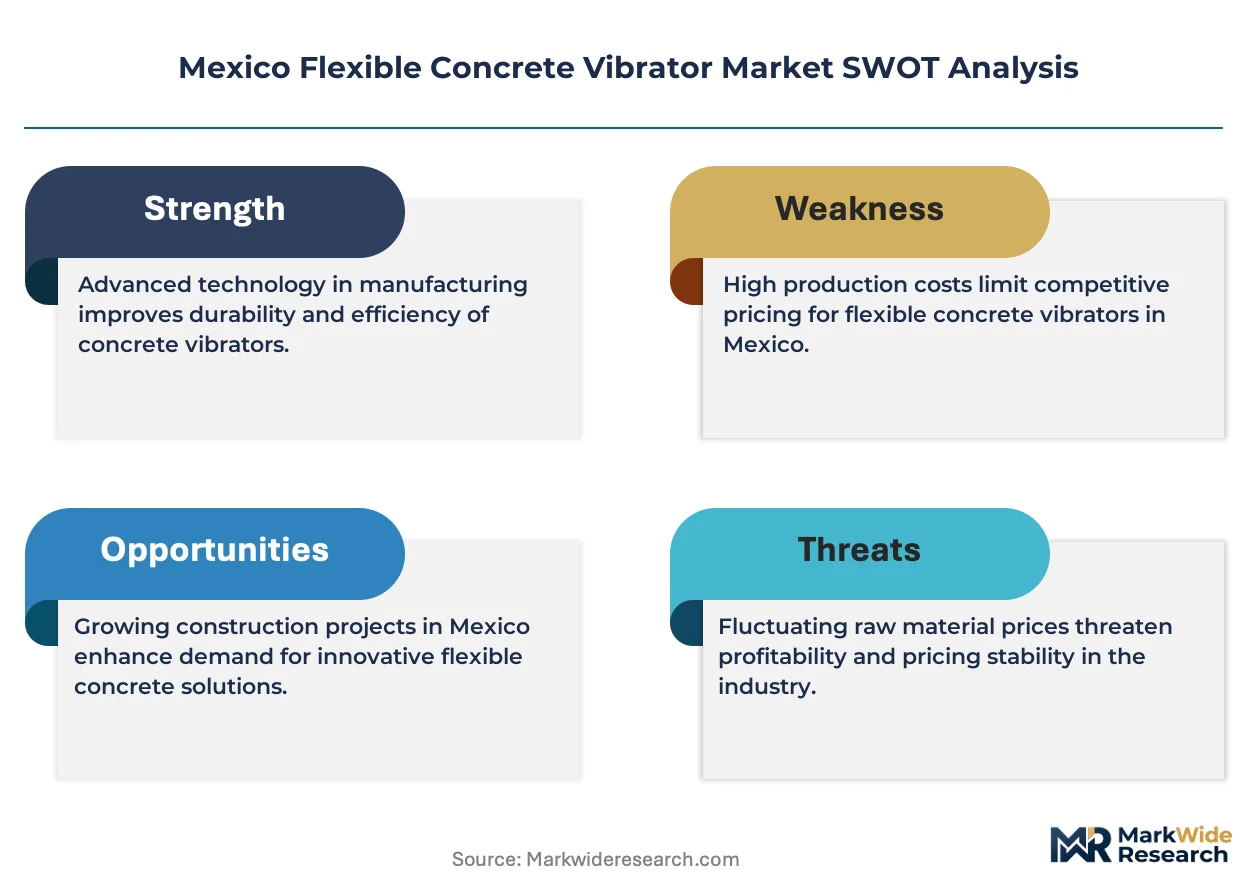
NOM-004-STPS-1999 vibration-exposure limits gate qualified supply access and premium-tier pricing power, as compliance-certified manufacturers command specification-grade procurement on federally funded infrastructure while uncertified competitors retreat to commoditized residential segments.
Pricing Analysis
Margin tightening in mid-tier equipment lines reflects steel-reinforced hose input cost volatility and rubber commodity pricing swings. Three-tier pricing structure across specification-grade, standard-certified, and economy-residential levels separates SCT-compliant battery-powered units with traceable calibration from basic electric vibrators sold through hardware channels. Price differentiation hinges on CONAPO certification documentation and integrated data-logging capability. Residential builders exhibit highest price sensitivity, while federal infrastructure contractors prioritize specification compliance over unit economics.
Supply Chain Analysis
Variable-frequency drive components and lithium-ion battery cells rest on concentrated Asian specialty electronics producers, with brushless DC motor controllers sourced from established industrial automation corridors. Steel-reinforced rubber hose assemblies draw from domestic compounding facilities and imported steel wire suppliers. Single-source vulnerability in electronic controller sourcing creates lead-time exposure for Mexican domestic assemblers. Distribution runs through regional distributor networks in Guadalajara, Monterrey, and Mexico City metropolitan zones, with rental-service agreements penetrating mid-sized contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NOM-004-STPS-1999 compliance creates a durable barrier-to-entry moat, elevating certified manufacturers above price-commoditized competitors while forcing capital-constrained entrants to absorb recertification costs or exit specification-grade procurement pools.
For Market Incumbents: Extend calibration-certification service capabilities to capture aftermarket revenue streams from CONAPO workforce mandates, while deepening backward integration into brushless DC motor production to offset electronic controller import dependency and defend margin position against Asian component pricing volatility. For New Entrants and Emerging Players: Begin with battery-powered vibrator rental-fleet deployment in Baja California and Sonora infrastructure corridors, where emission protocols and remote-site requirements outpace incumbent service coverage, leveraging equipment-as-access models to bypass capital-intensive ownership competition. For Investors and Strategic Acquirers: NOM energy-efficiency labeling amendment enforcement timelines are the leading indicator that specification-grade procurement consolidation will accelerate, favoring long-term positions in distributors with integrated certification service capabilities and traceable performance documentation infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Service Expansion | CONAPO workforce mandates create recurring aftermarket revenue from operator training and recertification. |
| Backward Integration into Motor Production | Brushless DC controller captive supply reduces Asian import dependency and compresses lead times. |
| Rental-Fleet Geographic Expansion | Equipment-as-access models penetrate mid-sized contractor segments in Monterrey and Guadalajara zones. |
| Corrosion-Resistant Design Development | CONAGUA water-treatment investments in northern border states demand specialized vibrator specifications. |
| Predictive Maintenance Platform Integration | Data-logging capability captures SCT-financed bridge and highway project procurement requirements. |
Research Methodology
Multi-period observation of SCT project award patterns, CONAGUA investment disbursements, and NOM compliance enforcement timelines anchored the trend analysis, supplemented by interviews with equipment maintenance directors at federal infrastructure contractors, distributor network managers in Guadalajara and Monterrey, aftermarket service heads, and procurement leads at precast yard operations. Secondary validation drew from Secretaría de Comunicaciones y Transportes material-quality benchmarks, CONAPO workforce directives, customs import records for electronic controllers, and SEC filings of listed equipment manufacturers. Bottom-up demand aggregation across product types and applications triangulated against top-down infrastructure spending projections.
Segment-weighting approaches modeled electric, battery-powered, pneumatic, and hydraulic product categories alongside construction, infrastructure development, residential, and industrial application verticals, with end-user archetypes and distribution channel dynamics as cross-cutting dimensions. CAGRs were derived from fitted growth curves applied to infrastructure spending trajectories and equipment replacement cycle compression patterns across the analysis window. Battery chemistry advancement curves and NOM amendment implementation schedules served as industry-specific forecast inputs.
Regulatory enforcement delays, commodity price spikes in rubber and steel inputs, and lithium-ion cell supply disruptions are the dominant revision risks to modeled equipment demand. Forecasts reflect documented assumptions regarding federal infrastructure commitment continuity and contractor fleet turnover velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Portable Welding Generators Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
Fogging Machine Market
Construction Equipment
Bucket Elevator Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Dozer Blade Market
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
Global Industrial Parts Washer Market
Construction Equipment
Log Splitters Rental Market