
 Asphalt Testing Equipment Market | 2026-2036
Asphalt Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asphalt Testing Equipment Market Analysis
Digital sensor integration is fragmenting traditional asphalt testing workflows into modular, software-driven platforms. Humboldt Manufacturing leverages its North American distribution network to anchor field testing equipment sales across state DOT channels. Controls Group competes through European laboratory automation systems that sustain premium positioning in research institution procurement. PULUODY Group extends its presence in microwave testing technology for rapid binder content analysis.
Asphalt testing equipment comprises mechanical, thermal, and electronic instruments designed to measure binder viscosity, aggregate gradation, mixture stability, and pavement performance under simulated load conditions, primarily ensuring compliance with engineered specifications for road durability. Performance test equipment leads segment value due to its role in accelerated pavement testing protocols required for long-life highway design. Automated testing technology is displacing manual Marshall stability procedures in quality control laboratories, while field testing equipment occupies a narrower but defensible niche in construction-site verification workflows.
The U.S. Federal Highway Administration shapes demand through AASHTO and ASTM specification mandates that govern state-level procurement standards. Germany's KBA and federal transport ministry enforce DIN EN standards for asphalt quality certification, while China's MIIT administers GB standards for highway material testing that condition market access for imported equipment. Stakeholders must monitor how carbon-footprint disclosure requirements under the EU Green Deal are beginning to influence laboratory equipment procurement criteria in European infrastructure programs.
Market Dynamics
Digital sensor integration is fragmenting traditional asphalt testing workflows into modular, software-driven platforms that compress validation timelines and reduce laboratory labor intensity. State DOTs and federal highway agencies now demand real-time data interoperability between field and laboratory systems, forcing equipment vendors to rearchitect hardware-software bundles around open API standards rather than proprietary closed systems.
Growth Catalysts
- Superpave Mix Design Mandates:The U.S. Federal Highway Administration's MAP-21 performance management requirements are tightening material certification protocols and expanding laboratory capacity needs among state DOTs.
- Autobahn Rehabilitation Cycles:Federal transport investment in Germany is accelerating equipment procurement timelines for DIN EN-compliant asphalt quality certification systems.
- Microwave Binder Analysis:Rapid testing technology for binder content verification is reducing quality control turnaround from hours to minutes in high-throughput laboratories.
Market Restraints
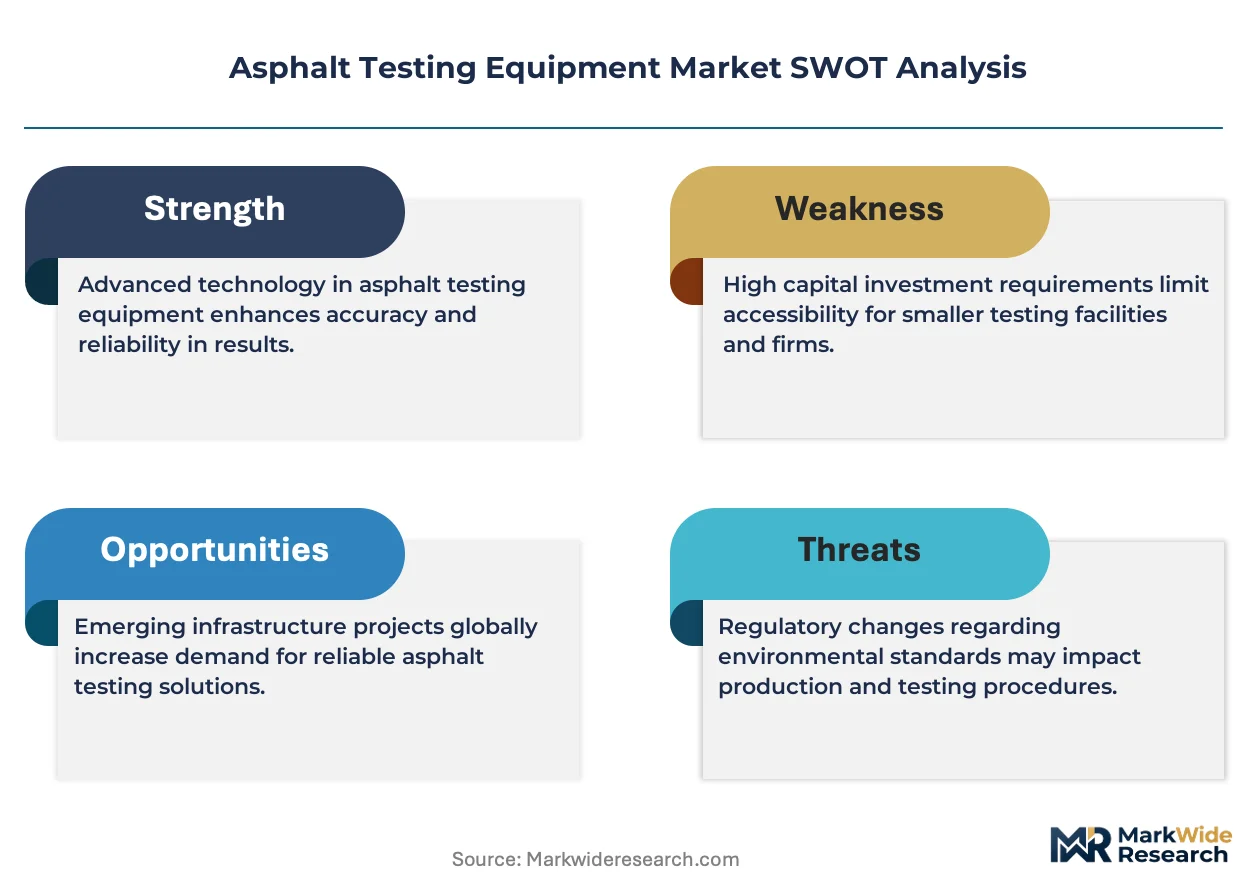
- Precision Sensor Input Costs:Load cell and LVDT sensor price volatility constrains margin flexibility for mid-tier equipment manufacturers.
- European Supply Concentration:Laboratory automation subassemblies concentrate among German and Italian component suppliers, creating single-source exposure.
- Manual Marshall Protocol Persistence:Legacy empirical testing methods retain regulatory grandfathering in several state specifications, slowing full automation adoption.
Strategic Opportunities
- Carbon Disclosure Tailwinds:The EU Green Deal's embodied carbon tracking requirements are beginning to influence laboratory equipment procurement criteria in European infrastructure programs.
- Field-Laboratory Convergence:Portable NDIR spectroscopy and wireless data logging are enabling construction-site validation workflows previously restricted to central labs.
- China Highway Expansion:GB standards administration under MIIT is conditioning market access for imported performance test equipment as expressway construction accelerates.
Industry Challenges
- Mechatronics Skill Scarcity:Cross-functional technicians capable of calibrating hydraulic actuators, thermal chambers, and data acquisition systems simultaneously command premium compensation.
- AASHTO Requalification Timelines:Equipment recertification cycles for modified binder test protocols create revenue recognition delays for vendors serving state DOT channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asphalt Testing Equipment Market |
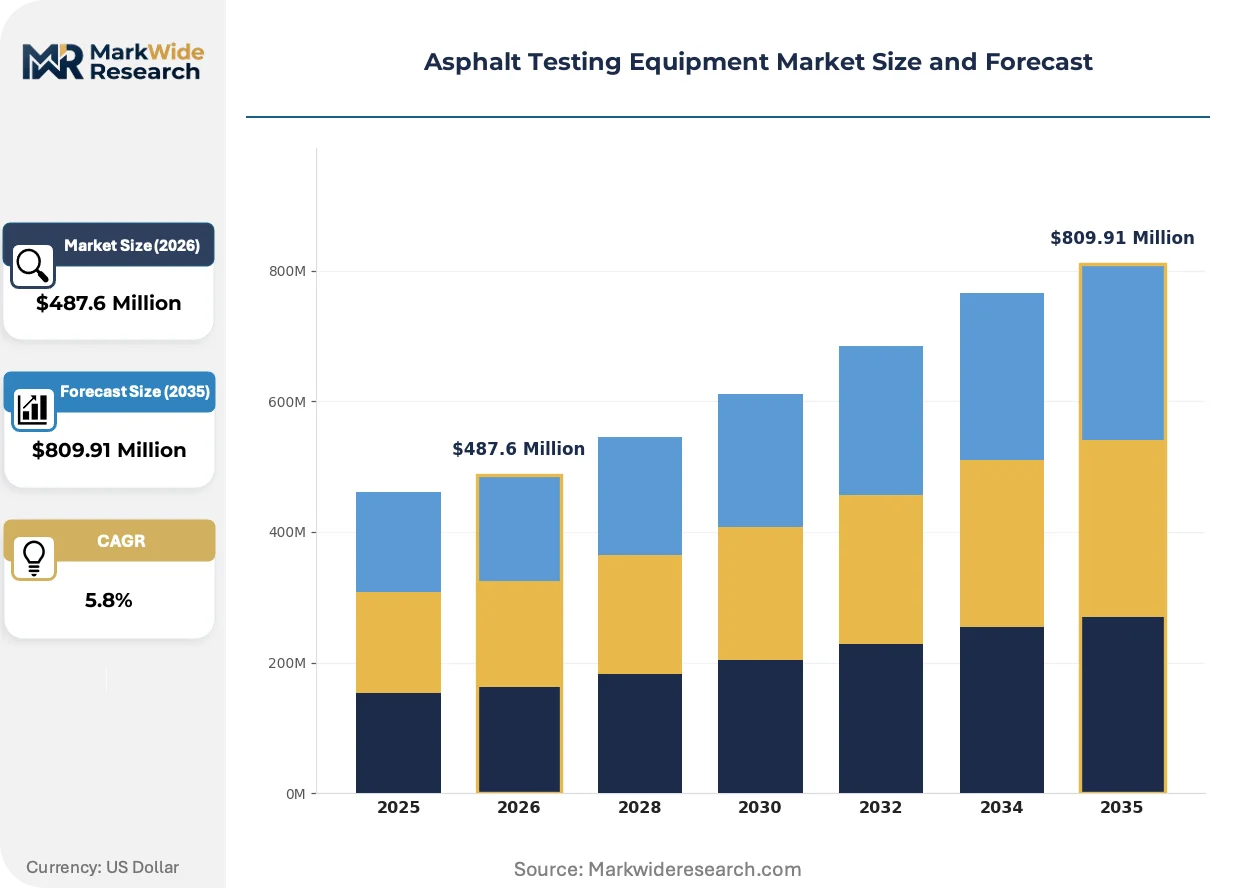
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Test Equipment, Performance Test Equipment, Laboratory Testing Equipment, Field Testing Equipment Technology: Static Testing, Dynamic Testing, Microwave Testing, Automated Testing End User: Construction Companies, Research Institutions, Government Agencies, Quality Control Laboratories Application: Pavement Design, Quality Assurance, Material Evaluation, Research Development |
| Companies Covered | Hunan BASF Testing Technology, Shanghai Yiqi Intelligent Technology, PULUODY Group, Cangzhou Luyi Testing Instrument, Matest, Humboldt Manufacturing, Gilson Company, Shanghai Changji Geological Instrument, Controls Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asphalt Testing Equipment Market Emerging Trajectories
Automation architectures are compressing the boundary between empirical index testing and fundamental material characterization, enabling predictive pavement performance modeling earlier in the mix design process. Three concurrent developments are restructuring competitive positioning in asphalt testing equipment.
Automated gyratory compaction systems are migrating from research institution installations toward routine quality control laboratories in state DOT facilities. These systems eliminate operator-induced variability in specimen preparation while generating continuous density-gradient data that manual hammer compaction cannot replicate. Equipment vendors are bundling gyratory platforms with integrated shear test modules to capture share in laboratories seeking consolidated Superpave validation workflows.
The EU Green Deal's carbon-footprint disclosure requirements are beginning to influence laboratory equipment procurement criteria in European infrastructure programs. Contractors bidding on autobahn rehabilitation contracts must now document embodied carbon in construction materials, creating demand for thermal analysis equipment capable of quantifying binder aging and recycling agent effectiveness. German equipment suppliers are prioritizing energy consumption specifications in new product development to align with federal transport ministry sustainability scoring.
State DOT procurement offices are consolidating vendor relationships through multi-year framework agreements that bundle equipment supply with calibration services and software subscriptions. This purchasing pattern favors suppliers with established North American service networks over European manufacturers dependent on third-party distributor arrangements. The shift is most visible in the southeastern United States, where highway construction volume expansion has compressed equipment delivery timelines from sixteen weeks to eight weeks.
Asphalt Testing Equipment Market Segmentation
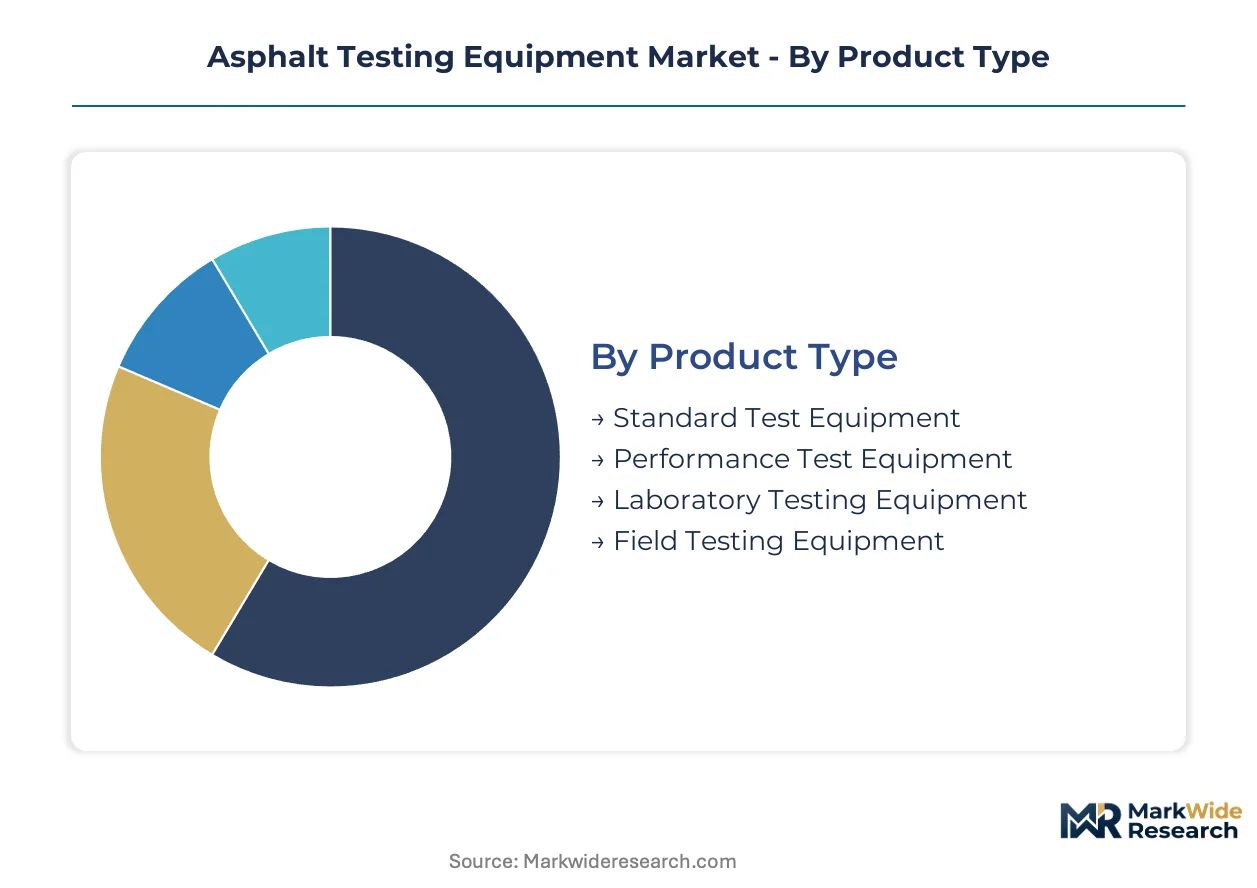
Asphalt testing equipment procurement cycles vary dramatically by segment, with field-deployed units turning over every 3-5 years while central laboratory installations persist for 10-15 years. Understanding these replacement rhythms helps vendors align service revenue models and inventory planning with actual demand pulses.
Product Type:
Replacement velocity separates this category: field units cycle fastest due to jobsite wear, while laboratory platforms anchor long-term capital budgets with extended depreciation schedules.
- Standard Test Equipment:Marshall stability frames, penetration apparatus, and ductility meters constitute the baseline instrumentation for routine binder characterization. State DOT quality control laboratories in Texas and California drive replacement demand as AASHTO specification updates render legacy analog dial gauges non-compliant.
- Performance Test Equipment:Asphalt pavement analyzers, Hamburg wheel trackers, and dynamic modulus systems simulate traffic loading and environmental stress under controlled conditions. Federal Highway Administration Superpave validation mandates are concentrating procurement among central laboratories seeking long-life pavement design certification.
- Laboratory Testing Equipment:Gyratory compactors, rotational viscometers, and bending beam rheometers support mix design and binder grading workflows.
- Field Testing Equipment:Portable nuclear density gauges, non-nuclear electromagnetic density meters, and handheld spectroscopic analyzers enable construction-site verification without specimen transport delays.
Standard test equipment dominates installed base across state DOT facilities. Performance test equipment is where expansion concentrates as agencies adopt mechanistic-empirical design protocols.
Technology:
Capital intensity stratifies this dimension, with automated platforms commanding 3-4x the upfront investment of static configurations but compressing per-test labor costs by 60-70 percent.
- Static Testing:Manual load application and visual measurement reading characterize this legacy approach, persisting in budget-constrained municipal laboratories and developing market facilities. Equipment longevity exceeds 20 years with proper maintenance, creating a fragmented installed base resistant to wholesale replacement.
- Dynamic Testing:Servo-hydraulic actuators apply repeated loading patterns that replicate traffic-induced fatigue and permanent deformation mechanisms. German autobahn rehabilitation contractors prioritize DIN EN-compliant dynamic systems for rutting susceptibility validation in high-volume traffic corridors.
- Microwave Testing:Rapid binder content determination replaces solvent extraction methods, cutting analysis time from hours to minutes.
- Automated Testing:Robotic specimen handling and unattended data acquisition eliminate operator variability while enabling 24-hour throughput in high-volume quality control environments.
Static testing retains the largest legacy footprint. Automated testing is climbing the fastest as labor scarcity and reproducibility requirements reshape procurement priorities.
End User:
Budget authority and specification influence diverge sharply: government agencies set standards that cascade through private sector procurement, while research institutions pioneer methods that later diffuse to routine quality control.
- Construction Companies:Field verification priorities dominate, with equipment selection driven by project-scale rental economics and rapid turnaround requirements. Large infrastructure contractors in the southeastern United States are consolidating vendor relationships through multi-year framework agreements.
- Research Institutions:Fundamental material characterization and next-generation test method development define demand, with equipment specifications exceeding commercial laboratory requirements. University transportation centers with Federal Highway Administration funding drive adoption of advanced imaging and micro-mechanical analysis systems.
- Government Agencies:State DOT central laboratories and federal highway administration facilities establish certification protocols that condition market access for all downstream users.
- Quality Control Laboratories:Third-party testing services and contractor-affiliated facilities balance throughput volume against accreditation maintenance costs.
Government agencies anchor specification authority. Quality control laboratories represent the steepest expansion trajectory as outsourcing trends accelerate among mid-tier construction firms.
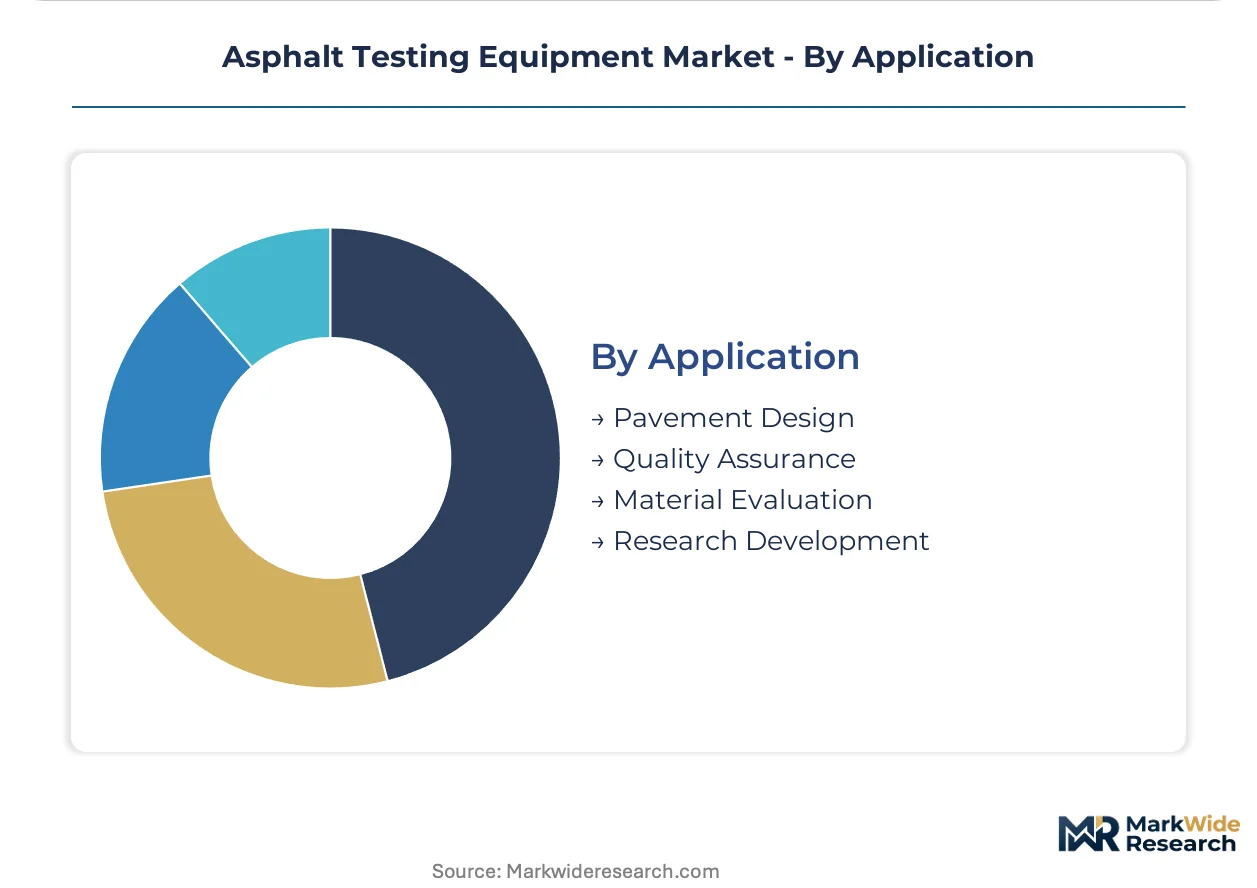
Application:
Technical complexity escalates from routine quality assurance through predictive pavement design, with research development commanding specialized configurations that resist standardization.
- Pavement Design:Mechanistic-empirical calibration requires performance test data linking material properties to structural response models. State DOTs implementing AASHTOWare Pavement ME design software are procuring dynamic modulus and repeated load permanent deformation systems to populate input libraries.
- Quality Assurance:Specification compliance verification dominates volume, with rapid test methods prioritized over fundamental characterization. German federal transport ministry contracts now require carbon-footprint documentation, creating demand for thermal analysis equipment in quality assurance workflows.
- Material Evaluation:Aggregate source approval and binder supplier certification support pre-qualification testing.
- Research Development:Novel binder modification, recycling agent effectiveness, and climate adaptation studies drive custom instrumentation requirements.
Quality assurance commands the largest equipment population. Pavement design is gaining share fastest as agencies transition from empirical thickness charts to mechanistic performance prediction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State DOT procurement offices and federal highway laboratories concentrate equipment demand across North America, Europe, and Asia-Pacific. Highway construction agencies in the United States are expanding laboratory capacity for Superpave mix design validation. Demand is concentrating in Germany, where federal transport investment in autobahn rehabilitation is accelerating equipment procurement cycles.
United States
Federal Highway Administration MAP-21 performance management requirements are tightening material certification protocols across state DOT facilities. AASHTO specification mandates govern procurement standards from Texas to California, rendering legacy analog dial gauges non-compliant. The southeastern United States has compressed equipment delivery timelines from sixteen weeks to eight weeks as highway construction volume expands.
Germany
Federal transport ministry contracts for autobahn rehabilitation are accelerating DIN EN-compliant asphalt quality certification system procurement. The EU Green Deal's carbon-footprint disclosure requirements are influencing laboratory equipment procurement criteria in federal infrastructure programs. Equipment suppliers in Baden-Württemberg and Bavaria are prioritizing energy consumption specifications to align with sustainability scoring mandates.
China
MIIT administration of GB standards for highway material testing is conditioning market access for imported performance test equipment as expressway construction accelerates. The country's national transport regulator enforces certification protocols that cascade through provincial procurement systems. Yangtze River Delta infrastructure clusters are driving demand for automated testing platforms in high-throughput quality control environments.
India
National highway expansion programs under the central government's infrastructure investment plans are stimulating demand for field testing equipment across state public works departments. BIS standards for road construction materials govern laboratory accreditation requirements in third-party testing facilities. Maharashtra and Gujarat industrial corridors are concentrating contractor procurement of portable density verification systems for construction-site workflows.
Japan
METI coordination of infrastructure resilience programs is directing investment toward performance test equipment for climate-adapted pavement design. JIS standards for asphalt mixture testing condition procurement by prefectural road authorities and metropolitan expressway operators. Kanto region transportation laboratories are adopting dynamic modulus systems to populate mechanistic-empirical design input libraries.
Asphalt Testing Equipment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented vendor tiers. North American distribution networks anchor field equipment sales through state DOT relationships, while European laboratory automation specialists sustain premium positioning in research institution procurement. Three archetypes dominate: integrated instrumentation conglomerates with multi-product portfolios, regional fabrication specialists serving domestic specification requirements, and technology-focused innovators in rapid testing methodologies. Consolidation is occurring through multi-year framework agreements that bundle equipment supply with calibration services, while geographic expansion into emerging highway construction markets represents the second dominant competitive vector.
Within the North American channel-control tier, Humboldt Manufacturing and Gilson Company represent established distribution-network anchors. Controls Group occupies a position exemplifying European laboratory automation specialization. PULUODY Group sits within the rapid-testing technology archetype, reflecting microwave binder analysis innovation. These three companies illustrate how geographic origin and structural focus shape competitive positioning without converging on identical capability profiles.
| Leading Market Players |
|---|
| Hunan BASF Testing Technology |
| Shanghai Yiqi Intelligent Technology |
| PULUODY Group |
| Cangzhou Luyi Testing Instrument |
| Matest |
| Humboldt Manufacturing |
| Gilson Company |
| Shanghai Changji Geological Instrument |
| Controls Group |
| Others |
Supply Flow & Price Mechanics
German and Italian component suppliers for precision sensor subassemblies anchor upstream concentration, directing margin pools toward equipment vendors with captive calibration service networks and multi-year state DOT framework agreements.
Pricing Analysis
Cost-plus contracts with load cell and LVDT sensor price indexation dominate equipment procurement between mid-tier manufacturers and state DOT facilities. Three-tier pricing structure across automated platforms, dynamic testing systems, and static configurations separates premium laboratory installations from field-deployed units. Cost compression in standard test equipment intensifies as AASHTO specification updates render legacy analog systems non-compliant. Construction companies exhibit highest price sensitivity due to project-scale rental economics, while research institutions accept premium positioning for fundamental material characterization capabilities.
Supply Chain Analysis
Precision sensor feedstock draws from German load cell manufacturers, Italian LVDT specialists, and North American data acquisition module fabricators. Hydraulic actuator assemblies, thermal chamber subsystems, and robotic specimen handling mechanisms rest on specialized component sourcing. Single-source vulnerability concentrates in European laboratory automation subassemblies, exposing equipment vendors to procurement disruption. Distribution runs through state DOT central laboratories, federal highway administration facilities, and third-party quality control laboratories serving construction verification workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as digital sensor integration fragments traditional workflows into modular platforms, spawning niches for rapid testing innovators and field-laboratory convergence specialists.
For Market Incumbents: Harden service network density across southeastern United States state DOT channels to defend against compressed delivery timeline demands. Deepen backward integration into precision sensor calibration capabilities to offset load cell price volatility. Lock in multi-year framework agreements bundling equipment supply with software subscriptions before European manufacturers establish third-party distributor alternatives. For New Entrants and Emerging Players: India's state public works departments represent underpenetrated demand for portable density verification systems as national highway expansion accelerates. Target microwave binder analysis technology for rapid quality control turnaround in high-throughput Chinese Yangtze River Delta laboratories. Pursue OEM partnerships with German autobahn rehabilitation contractors seeking DIN EN-compliant dynamic systems for carbon-footprint documentation requirements. For Investors and Strategic Acquirers: Capital is best deployed toward rapid-testing technology innovators with microwave spectroscopy or NDIR portable platforms, positioned for field-laboratory convergence trends. Long-term viability hinges on software-driven platform architectures rather than hardware-only equipment vendors. Monitor AASHTO requalification timeline compression as signal for vendor revenue recognition stress and consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Framework Agreement Consolidation | Bundles Humboldt Manufacturing equipment with calibration services across Texas and California state DOT channels. |
| Microwave Testing Technology Licensing | Enables PULUODY Group rapid binder content analysis penetration into Chinese GB-standard laboratories. |
| European Laboratory Automation Acquisition | Extends Controls Group DIN EN-compliant positioning into German federal transport ministry sustainability scoring mandates. |
| Field-Laboratory Convergence Platform Launch | Integrates portable NDIR spectroscopy with wireless data logging for construction-site validation workflows. |
| Backward Integration into Sensor Calibration | Captures margin pools from load cell price volatility through in-house precision sensor servicing capabilities. |
Methodological Framework
A spread of perspectives from state DOT laboratory directors, federal highway administration specification engineers, equipment vendor sales executives, and third-party quality control laboratory managers converged on the working assumptions shaping this analysis. Primary interview data combined with secondary validation from AASHTO specification documents, ASTM standard filings, DIN EN certification records, and MIIT GB standards administration. Customs and trade data, SEC equipment manufacturer filings, and federal highway construction budget disclosures anchored bottom-up and top-down triangulation.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by replacement velocity, technology stratification by capital intensity, and end-user budget authority divergence. Modeled dimensions span standard versus performance test equipment, static versus automated testing platforms, and government agency versus construction company procurement patterns. CAGRs derived from equipment installation base turnover rhythms, specification mandate adoption curves, and regional highway construction volume trajectories. Superpave validation mandate penetration and EU Green Deal carbon disclosure compliance served as industry-specific forecast inputs.
Practitioners should monitor AASHTO requalification timeline delays, precision sensor input cost volatility, and European supply concentration disruption for early signals necessitating forecast revision. Cross-checking against Federal Highway Administration MAP-21 performance management implementation progress is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Heating Roller Press Calender Machine Market
Construction Equipment
Piling Machine Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Grout Bags Market
Construction Equipment
Friction Stir Welding Market
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Dust Suppression Fog Cannon Market
Construction Equipment
India Construction Equipment Rental Market