
 Felling Heads Market | 2026-2036
Felling Heads Market Size, Share, and Industry Trends Forecast 2026-2036
Felling Heads Market Analytics
Mechanized timber harvesting is restructuring the felling heads landscape as logging contractors scale up fleet automation. Tigercat anchors its position through deep specialization in tracked carrier integration for steep-slope applications. Deere & Company leverages its agricultural dealer network to cross-sell forestry attachments across Midwestern markets. Waratah dominates the Nordic region with purpose-built heads optimized for spruce and pine stem geometries.
A felling head is a hydraulically or mechanically powered cutting attachment mounted on excavators or purpose-built forestry carriers, typically incorporating a bar saw or disc saw with delimbing knives and accumulating arms to sever, process, and bunch trees into merchantable stems. The attachment interfaces with carrier hydraulics through standardized quick-coupler systems rated for pressures exceeding 350 bar to deliver clean crosscuts in dense stands. High-performance felling heads command the dominant share of value owing to integrated measuring systems that optimize stem-length bucking for sawmill specifications. Lightweight variants represent the fastest-expanding category as urban landscaping services and small-scale woodland owners adopt mini-excavator-mounted solutions for restricted-access sites.
EPA Tier 4 Final and EU Stage V emissions frameworks are forcing engine downsizing in carrier platforms, which in turn constrains hydraulic power availability and accelerates electric actuator development in head designs. ISO 11850 safety standards for forestry machinery govern guarding, emergency stop integration, and operator protection zones, directly influencing R&D allocation among manufacturers. Stakeholders must monitor battery-electric carrier platform maturation and its compatibility with legacy hydraulic head architectures as electrification timelines compress.
Market Dynamics
Mechanized harvesting adoption is compressing replacement cycles as forestry contractors consolidate holdings and standardize on purpose-built carriers with integrated felling heads. Hydraulic power constraints from emissions-compliant engines are forcing actuator redesigns across equipment portfolios.
Growth Catalysts
- Emissions compliance mandates:EPA Tier 4 Final and EU Stage V regulations are accelerating carrier platform turnover, creating pull-through demand for compatible head attachments in North America and Nordic markets.
- Softwood harvest intensity:Sustained rotation cycles in Sweden and Finland sustain replacement demand for high-duty-cycle equipment optimized for spruce and pine geometries.
- Urban canopy management:Municipalities and utility arborists are mini-excavator mounting lightweight felling heads for restricted-access vegetation control along transmission corridors.
Market Restraints
- Steel and alloy input volatility:High-strength plate and wear-resistant steel price swings compress fabrication margins for head manufacturers with fixed-price OEM contracts.
- Hydraulic component supply concentration:Precision pump and valve sourcing clusters in Germany and Japan create vulnerability to logistics disruptions and extended lead times.
- Technical integration barriers:Legacy carrier fleets with pre-Tier 4 hydraulic architectures cannot accommodate electric actuator heads without complete power system overhaul.
Strategic Opportunities
- Battery-electric carrier maturation:OEM development of electric forestry carriers creates white space for purpose-designed low-voltage head architectures with native CAN bus integration.
- Precision bucking automation:Machine vision and LiDAR stem profiling converging with existing measuring systems enables real-time optimization for sawmill-specific log specifications.
- Rental and service channel expansion:Contractor fleet flexibility preferences are opening dedicated forestry equipment rental networks as an alternative to direct purchase.
Industry Challenges
- Field technician specialization gaps:Hydraulic-electric hybrid systems demand cross-trained service personnel with both fluid power and embedded electronics competencies that remain scarce in rural forestry regions.
- ISO 11850 certification timelines:Revised guarding and emergency stop standards require extensive third-party validation, extending product launch schedules by 8-14 months for new head designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Felling Heads Market |
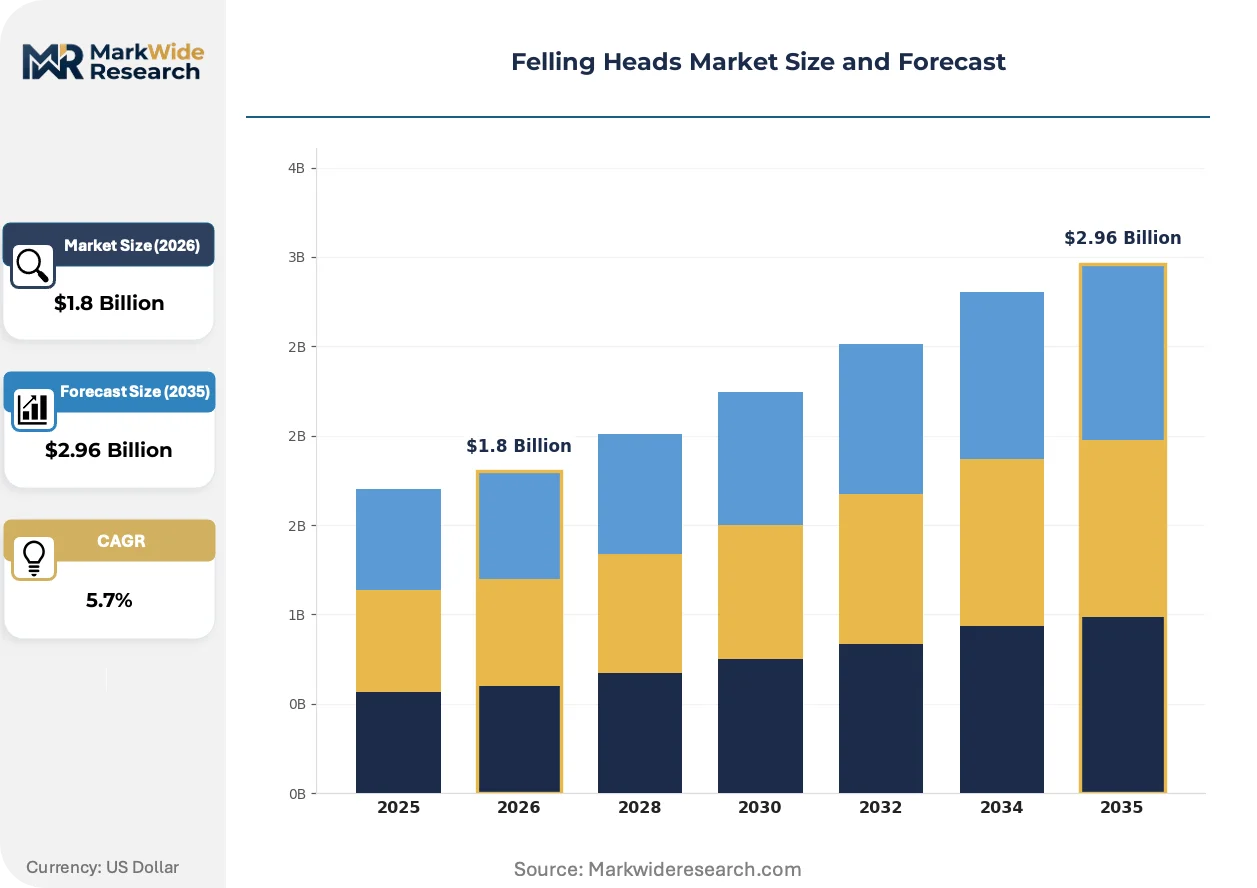
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Felling Heads, High-Performance Felling Heads, Lightweight Felling Heads, Heavy-Duty Felling Heads End User: Forestry Companies, Landscaping Services, Logging Contractors, Construction Firms Technology: Hydraulic Technology, Mechanical Technology, Electric Technology, Pneumatic Technology Application: Tree Cutting, Land Clearing, Timber Harvesting, Site Preparation |
| Companies Covered | Caterpillar, Waratah, Tigercat, Deere & Company, TimberPro Inc., AFM-Forest Ltd, Kesla Oyj, Les Produits Gilbert, Komatsu Forest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Felling Heads Market Evolving Landscape
Actuator electrification is restructuring power transmission architectures as hydraulic efficiency losses become unacceptable under downsized carrier engines. Equipment portfolios are splitting between legacy hydraulic heads and native electric designs.
Electrification of felling head actuators is electrifying competitive positioning across the attachment market. Linear electric motors and servo-driven accumulating arms replace hydraulic cylinders in prototype designs from Nordic specialists. Forestry contractors with sustainability mandates and urban noise restrictions are piloting these systems at 3-5x conventional pricing. The technology is electrifying R&D allocation, compressing hydraulic component supplier relationships as electric drivetrain partnerships take precedence.
EU Stage V and EPA Tier 4 Final frameworks are constraining diesel engine displacement in carrier platforms. Hydraulic pump output curves flatten as engines downsize, forcing head manufacturers to improve mechanical efficiency or bypass hydraulics entirely. Nordic markets with the strictest emissions enforcement are seeing fastest adoption of electric auxiliary functions on otherwise hydraulic heads.
Service unbundling is fragmenting traditional OEM-captive aftermarket relationships. Large contractor fleets with in-house maintenance capabilities are sourcing wear parts and rebuild kits directly from component suppliers, bypassing dealer networks. This pattern concentrates in North American markets with established independent logging companies and mature parts distribution infrastructure.
Felling Heads Market Segmentation
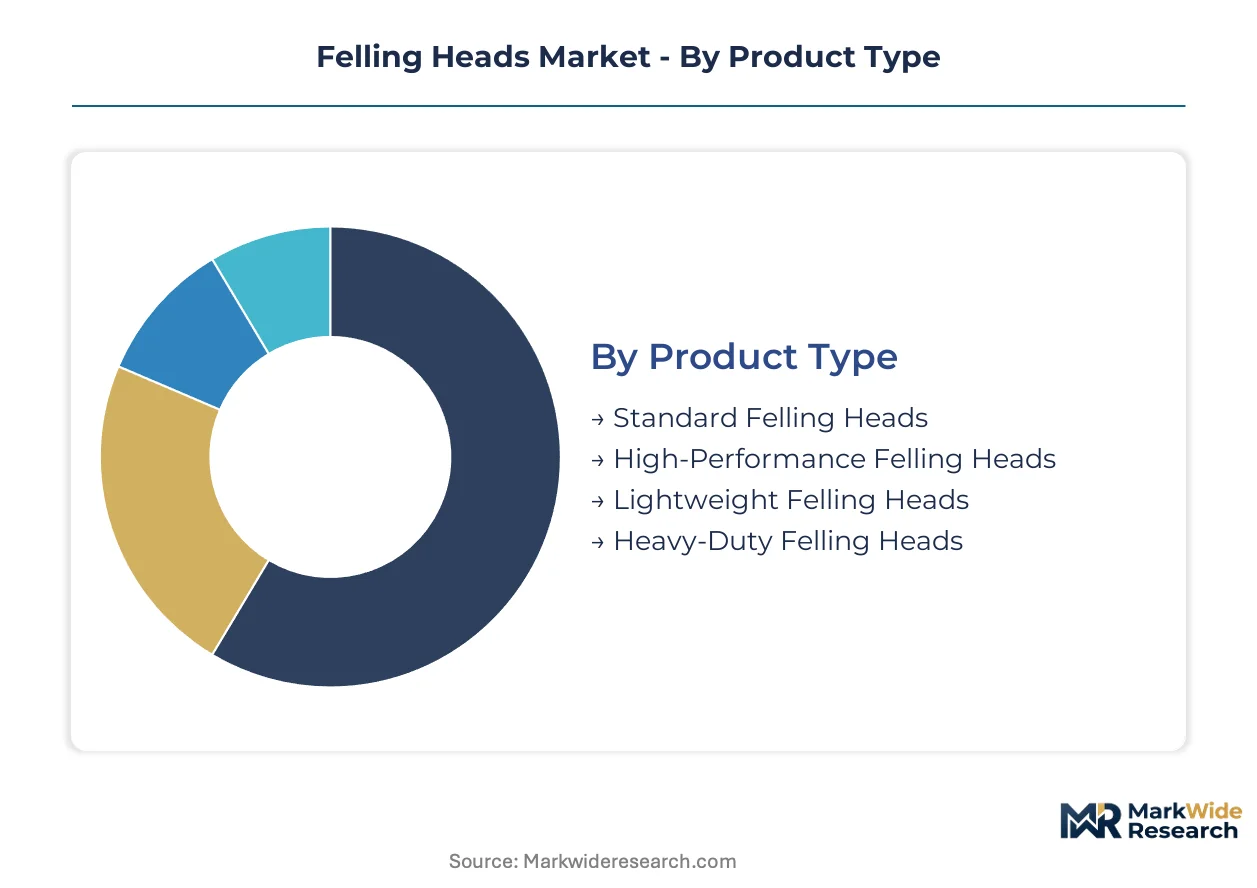
Segmentation in felling heads reveals how carrier platform specifications, stem geometry requirements, and emissions compliance timelines fragment demand across equipment tiers. Contractors select head architectures based on hydraulic power availability, stand density, and bucking precision needs.
Product Type:
Cutting mechanism sophistication and accumulating arm capacity define the performance tier of each product category.
- Standard Felling Heads:Bar saw configurations with fixed delimbing knives serve small-to-mid diameter stands where stem geometry variation remains limited. Demand concentrates among independent logging contractors in the US Southeast and Baltic states where replacement cycles follow carrier platform turnover rather than performance upgrades.
- High-Performance Felling Heads:Integrated measuring systems with variable delimbing knife spacing optimize bucking for sawmill-specific log specifications. Swedish and Finnish forestry companies sustain replacement demand for these systems as rotation cycles intensify softwood harvest density.
- Lightweight Felling Heads:Mini-excavator compatibility opens urban canopy management and utility corridor maintenance to mechanized cutting. Municipal arborists in Germany and France are expanding fleets for restricted-access vegetation control.
- Heavy-Duty Felling Heads:Reinforced frames and oversized disc saws handle large-diameter hardwood and steep-slope extraction. Steep-terrain contractors in British Columbia and New Zealand deploy these for coastal old-growth operations.
Mature deployment sits with High-Performance Felling Heads. Newer deployment is concentrated in Lightweight Felling Heads.
End User:
Capital intensity and in-house maintenance capability determine which user categories specify integrated versus attachment-based systems.
- Forestry Companies:Vertically integrated timberland owners with captive harvesting operations standardize on purpose-built carriers with native head integration. Sustained rotation cycles in Nordic countries sustain fleet replacement programs with emissions-compliant platforms.
- Logging Contractors:Independent operators with mixed carrier fleets prioritize attachment flexibility and quick-coupler compatibility across hydraulic architectures. North American markets with fragmented land ownership patterns concentrate demand here.
- Landscaping Services:Urban tree care specialists source mini-excavator-mounted lightweight heads for residential and commercial site work. German municipal contracts are driving electrification pilots in this segment.
- Construction Firms:Site preparation and land clearing for infrastructure projects demand heavy-duty durability under abrasive conditions. Road and pipeline corridor development in Canada and Australia sustains intermittent procurement.
Volume concentration sits with Forestry Companies. Margin expansion is strongest in Landscaping Services.
Technology:
Power transmission architecture determines compatibility with emissions-downsized carrier engines and electrification roadmaps.
- Hydraulic Technology:Proportional valve control of bar saw feed and accumulating arm motion dominates legacy fleet compatibility. Pre-Tier 4 carrier architectures in Eastern Europe and Russia sustain demand despite efficiency limitations.
- Electric Technology:Linear motors and servo drives eliminate hydraulic losses and enable precision positioning for measuring systems. Nordic markets with strict Stage V enforcement are seeing fastest adoption of electric auxiliary functions.
- Mechanical Technology:Direct mechanical linkages from carrier power take-off units persist in low-cost markets with limited service infrastructure. Select Central European and South American contractors maintain these for simplicity.
- Pneumatic Technology:Compressed air actuation for delimbing functions appears in specialized underwater and explosive atmosphere applications. Niche demand from salvage logging in flooded timber stands.
Installed base concentration sits with Hydraulic Technology. Steepest expansion trajectory is in Electric Technology.
Application:
Stem processing requirements and stand conditions dictate head specification across use cases.
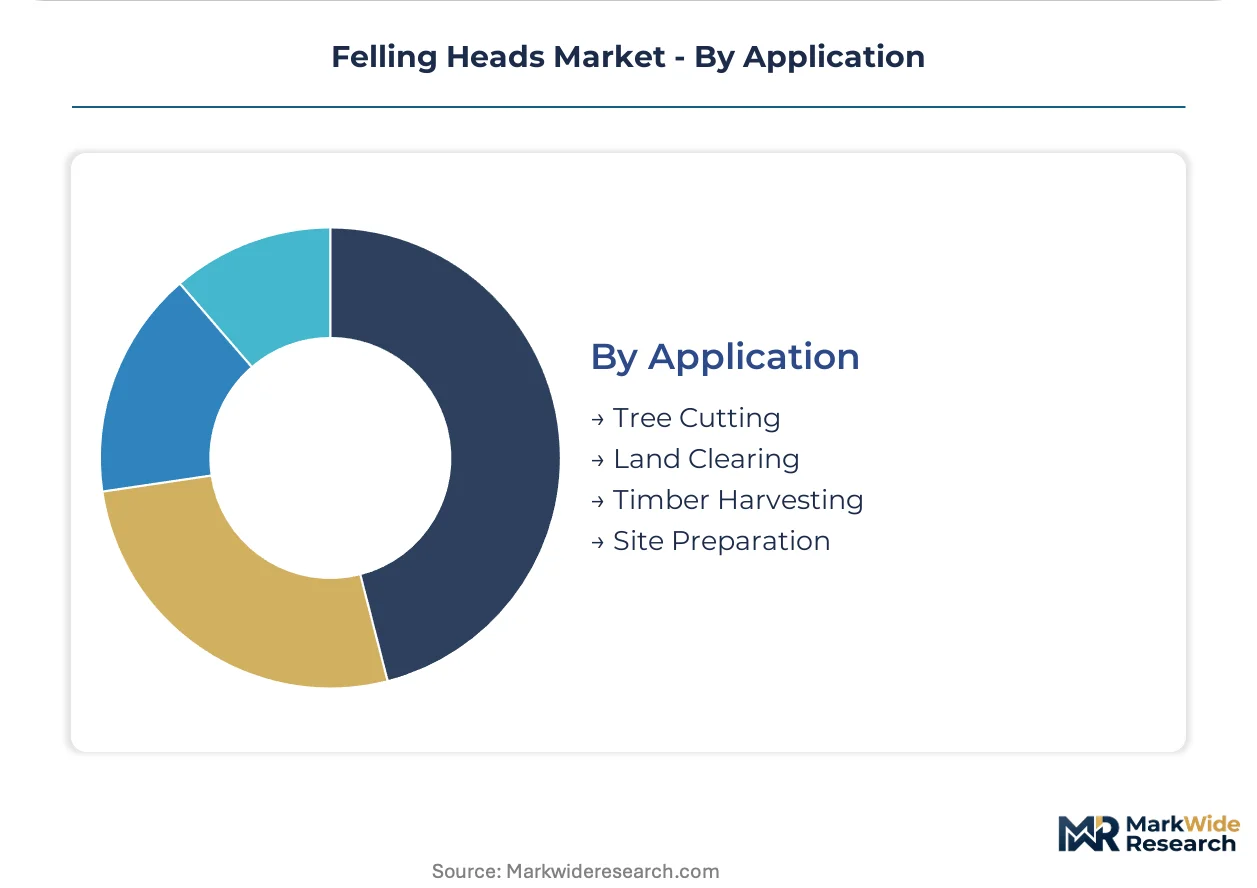
- Timber Harvesting:Production logging with integrated measuring and bucking optimization for sawmill supply chains. Softwood plantations in Sweden, Finland, and the US South sustain high-duty-cycle deployment.
- Tree Cutting:Single-stem removal with precision fall control for urban and utility corridor work. German and French utility arborists are expanding mini-excavator fleets for transmission line maintenance.
- Land Clearing:High-volume biomass removal without stem processing for site preparation and fuel reduction. Wildfire mitigation contracts in California and Australia are accelerating procurement.
- Site Preparation:Stump-to-stump clearing with minimal residual stand damage for plantation establishment. Brazilian eucalyptus and Indonesian acacia expansion programs drive demand.
Revenue concentration sits with Timber Harvesting. Fastest volume growth is in Land Clearing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden and Finland concentrate manufacturing capacity for high-performance felling heads, while the United States and Canada absorb the dominant share of trade flow through mechanized harvesting deployment. Demand fragmentation across regulatory environments produces distinct equipment specifications by destination market.
United States
Independent logging contractors in the Southeast and Pacific Northwest drive replacement demand for quick-coupler-compatible heads across mixed carrier fleets. EPA Tier 4 Final enforcement accelerates pre-2015 platform retirement, pulling through attachment sales from equipment dealers concentrated in Mississippi and Alabama timber corridors.
Sweden
Vertically integrated forestry companies sustain high-duty-cycle procurement for spruce and pine optimized systems through intensive rotation management. EU Stage V compliance timelines compress replacement windows, with Södra and SCA operating captive fleets around Växjö and Sundsvall manufacturing clusters.
Finland
Metä Group and UPM-Kymmme standardize on purpose-built carriers with native head integration for boreal softwood stands. Finnish Safety and Chemicals Agency (Tukes) machinery certification requirements extend validation timelines, concentrating R&D activity around Tampere and Joensuu equipment engineering centers.
Canada
Steep-slope contractors in British Columbia deploy heavy-duty disc saw configurations for coastal old-growth extraction. Natural Resources Canada fuel reduction contracts accelerate land clearing procurement, with Vancouver Island and Interior BC operations driving specialized attachment demand.
Germany
Municipal arborists in Bavaria and Baden-Württemberg expand mini-excavator-mounted lightweight fleets for urban canopy management. Federal Motor Transport Authority (KBA) Stage V enforcement creates pull-through demand for electric auxiliary function heads, with Stuttgart and Munich utility districts piloting low-noise configurations.
Felling Heads Market Competitive Landscape
Top-tier vendors anchor the premium-performance tier, while mid-scale fabricators compete on attachment flexibility and regional service density. The vendor base stratifies across three archetypes: forestry carrier OEMs with captive head integration, independent attachment specialists with multi-platform compatibility, and regional fabricators serving replacement part demand. Consolidation pressure concentrates among hydraulic component suppliers as electrification roadmaps disrupt legacy sourcing relationships. Strategic moves center on electric actuator partnerships and quick-coupler standardization alliances.
Among North American equipment manufacturers, Caterpillar, Deere & Company, and Tigercat occupy positions spanning integrated carrier-head systems and aftermarket attachment supply. Waratah and Komatsu Forest exemplify the independent specialist archetype with purpose-built designs for specific stem geometries. These five names represent the competitive core around which regional fabricators and component suppliers orbit.
| Leading Market Players |
|---|
| Caterpillar |
| Waratah |
| Tigercat |
| Deere & Company |
| TimberPro Inc. |
| AFM-Forest Ltd |
| Kesla Oyj |
| Les Produits Gilbert |
| Komatsu Forest |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators in Finland and Sweden anchor high-performance felling head production, their generational capital structures enabling patient pricing discipline through steel price cycles while resisting private-equity rollup pressure that might sacrifice margin stability for growth velocity.
Pricing Analysis
Margin tightening in standard felling heads reflects fixed-price OEM contracts confronting volatile high-strength plate and wear-resistant steel input costs. Three-tier pricing structure across premium, standard, and economy levels separates integrated measuring systems from bar saw configurations and mini-excavator attachments. Price differentiation hinges on ISO 11850 certification grade and after-sales service bundling. Independent logging contractors in the US Southeast exhibit acute price sensitivity, while Nordic forestry companies prioritize performance over unit cost.
Supply Chain Analysis
Precision pump and valve supply rests on German and Japanese hydraulic component specialists, with high-strength steel plate sourcing concentrated in Sweden and Finland. Raw material dependencies span wear-resistant alloys, precision-machined valve bodies, and specialized hydraulic seals. Single-source vulnerability in precision valve manufacturing creates extended lead time exposure. Distribution runs through captive OEM dealer networks in North America and direct mill relationships in Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final and EU Stage V emissions compliance function as a structural moat, elevating capital requirements for new entrants while rewarding incumbents with certified platform portfolios and established validation relationships with regulators.
For Market Incumbents: Lock in electric actuator development partnerships before battery-electric carrier platforms mature, securing native CAN bus integration capabilities that legacy hydraulic architectures cannot replicate. Deepen backward integration into precision valve manufacturing to reduce exposure to German and Japanese supply concentration. Prioritize certification investment for ISO 11850 revised guarding standards to compress competitor launch timelines. For New Entrants and Emerging Players: Enter via municipal arborist segments in Germany and France, where urban noise restrictions and sustainability mandates justify 3-5x pricing premiums for electric auxiliary function heads. Target landscaping services as the most penetrable vertical, exploiting incumbent neglect of mini-excavator compatibility. Pursue go-to-market alignment with rental channel expansion to bypass capital-intensive dealer network buildout. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent attachment specialists with multi-platform quick-coupler expertise in Nordic manufacturing clusters, where generational ownership transitions create acquisition windows. Long-term viability centers on electric-native head architectures compatible with emerging battery-electric carrier platforms. Watch battery-electric forestry carrier pilot programs as the inflection signal for electric head demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Actuator Partnership | Linear motor development with Nordic specialists secures positioning ahead of battery-electric carrier maturation. |
| ISO 11850 Certification Investment | Third-party validation compression accelerates product launch timelines relative to competitors. |
| Quick-Coupler Standardization Alliance | Cross-platform hydraulic compatibility expands addressable market among mixed-fleet contractors. |
| Rental Channel Development | Dedicated forestry equipment networks capture contractor preference for fleet flexibility over ownership. |
| Precision Bucking Automation R&D | Machine vision integration with measuring systems enables real-time sawmill specification optimization. |
Research Methodology
Multi-period observation of carrier platform turnover rates, emissions compliance timelines, and replacement cycle patterns anchored the trend analysis, supplemented by interviews with forestry equipment procurement managers, hydraulic systems engineers, dealer network operators, and aftermarket service heads. Secondary validation drew from EPA certification databases, EU Stage V type-approval records, customs trade data for high-strength steel plate, and SEC filings from disclosed forestry equipment manufacturers. Bottom-up triangulation across individual carrier fleet data and top-down reconciliation against aggregate softwood harvest volumes ensured consistency.
Segment-weighting applied product type, end user category, technology architecture, and application intensity dimensions across the modeling period. CAGRs derived from regression analysis of historical replacement cycles against emissions mandate enforcement dates, with cross-validation against regional softwood harvest forecasts and carrier platform retirement schedules. Industry-specific inputs included hydraulic power availability curves from downsized engine specifications and electric actuator cost-down trajectories from adjacent mobile equipment sectors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended hydraulic component supply disruptions or accelerated battery-electric carrier adoption. Forecasts reflect documented assumptions regarding emissions enforcement consistency and steel input price normalization. A small set of triggers—including EU Stage V implementation delays, breakthroughs in solid-state battery density for mobile equipment, and trade policy shifts affecting precision valve sourcing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Construction Equipment Tire Market
Construction Equipment
Cold Planers Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Piles Turner Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market