
 Compaction Machines Market | 2026-2036
Compaction Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Compaction Machines Market Analysis
ISO 14001 environmental management certification is bifurcating the competitive landscape for compaction equipment suppliers. Caterpillar leverages its captive engine manufacturing and dealer network to sustain North American market presence. BOMAG GmbH anchors European demand through specialized asphalt compaction technology and precision controls. Ammann Group competes on compact equipment specialization for urban job sites where maneuverability limits larger rivals.
Compaction machines apply static or dynamic force to densify soil, aggregate, or asphalt layers through vibratory, impact, or kneading action, typically achieving 90-95% modified Proctor density for engineered fill applications. Single drum rollers dominate earthworks and subgrade preparation where traction and gradeability matter, while double drum rollers command premium positioning in asphalt finishing due to surface quality requirements. Plate compactors occupy the entry-tier segment for landscaping and utility trenches, though electric drive variants are gaining specification in noise-restricted European urban zones.
EPA Tier 4 Final and EU Stage V emissions standards have forced engine redesigns and after-treatment adoption, raising OEM engineering costs while filtering out smaller suppliers lacking R&D scale. OSHA noise exposure limits and CE machinery directives further constrain product design, pushing manufacturers toward acoustic enclosures and operator isolation systems. Stakeholders must monitor battery-electric platform viability against diesel-hybrid architectures as total cost of ownership equations shift across regional energy price structures.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are compressing supplier margins while forcing engine architecture redesigns across the compaction equipment sector. The cost burden of after-treatment systems and selective catalytic reduction hardware is filtering out smaller OEMs lacking captive engine manufacturing scale.
Growth Catalysts
- China infrastructure stimulus:Central government bond issuance for transport and urban densification projects sustains fleet procurement by state-owned construction enterprises. Municipal governments in tier-two cities accelerate subway and highway expansion.
- EU Stage V compliance retrofit cycles:Rental fleet operators across Germany, France, and Italy replace legacy diesel units ahead of low-emission zone expansion in urban cores. Equipment lessors prioritize newer machines to maintain utilization rates.
- Intelligent compaction (IC) technology:Real-time density measurement and GPS-integrated pass-counting systems reduce rework costs for asphalt contractors. Highway agencies in the US specify IC-equipped rollers for federal-aid projects.
Market Restraints
- Steel and hydraulic component cost volatility:Roller drum fabrication and high-pressure hose assemblies face input price swings tied to commodity markets. OEMs struggle to pass through material cost increases in competitive bid environments.
- Engine supply concentration:Cummins, Deutz, and Kubota dominate sub-175hp off-highway diesel production. Disruptions at any single supplier cascade through multiple compaction equipment brands simultaneously.
- Battery energy density limitations:Current lithium-ion packs cannot match diesel energy storage for continuous vibratory operation in heavy soil compaction. Electric variants remain restricted to plate compactors and small tandem rollers.
Strategic Opportunities
- India Bharatmala highway program:The 83,677km road development initiative creates sustained demand for soil and asphalt compaction equipment. State public works departments expand mechanized construction capacity.
- CE marking alignment with ISO 14001:Environmental management certification opens specification pathways for municipal and institutional buyers prioritizing ESG compliance in equipment procurement.
- Telematics and usage-based rental models:Hourly compaction output metering enables equipment-as-a-service offerings for small contractors. Rental platforms in the Netherlands and Denmark pilot subscription-based fleet access.
Industry Challenges
- After-treatment technician scarcity:Diesel particulate filter regeneration and SCR system diagnostics require specialized training that vocational programs have not scaled to match fleet growth.
- Multi-certification compliance timelines:Simultaneous EPA, EU Stage V, and China VI validation stretches engineering resources and delays product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compaction Machines Market |
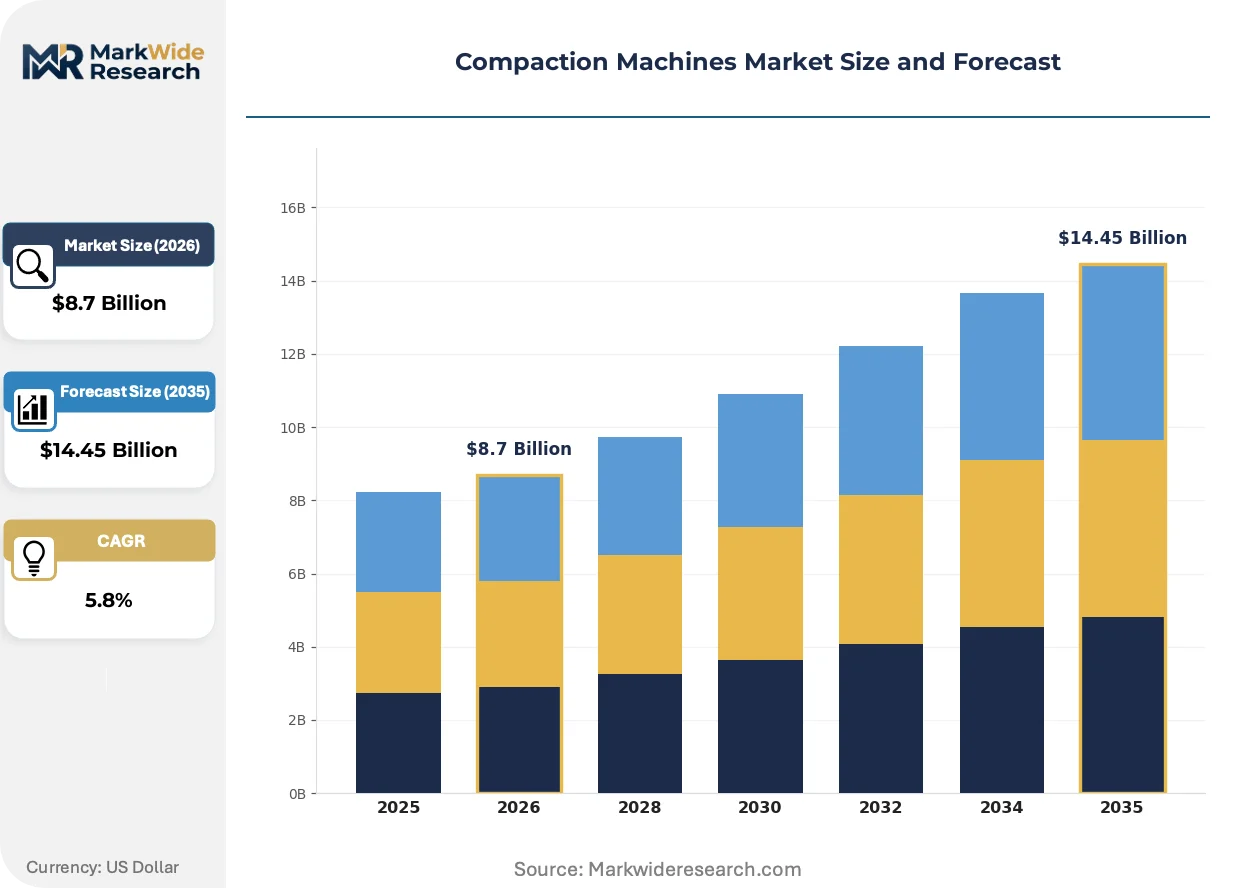
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Drum Rollers, Double Drum Rollers, Plate Compactors, Sheepsfoot Rollers Application: Soil Compaction, Asphalt Compaction, Concrete Compaction, Backfill Compaction End User: Construction, Road Building, Earthworks, Landscaping Drive Type: Hydraulic, Mechanical, Diesel, Electric |
| Companies Covered | Caterpillar, Volvo Construction Equipment, Komatsu Ltd., Hitachi Construction Machinery Co., Ltd., J C Bamford Excavators Ltd., BOMAG GmbH, Ammann Group, Wacker Neuson SE, Terex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compaction Machines Market Emerging Trajectories
Electrification architectures and connected fleet management systems are bifurcating product development roadmaps across the compaction equipment sector. Manufacturers must now engineer for both diesel-hybrid过渡 platforms and full battery-electric futures.
Electric plate compactors with swappable battery packs are displacing small gasoline engines in European urban construction zones. Municipal maintenance crews in Amsterdam and Copenhagen specify zero-emission variants for noise-restricted nighttime work. The technology is displacing traditional two-stroke engine suppliers from the sub-100kg equipment segment entirely.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in operator cab climate systems. OEMs redesign HVAC architectures to accommodate lower-GWP alternatives before 2027 supply quotas tighten. Tandem roller operators in Germany and Austria now demand R-1234yf compatibility as a specification threshold.
Rental fleet operators are consolidating supplier relationships around full-service maintenance agreements. Large highway contractors in Texas and California negotiate multi-year contracts bundling equipment, telematics, and predictive parts replacement. The model concentrates procurement authority with national rental platforms and marginalizes independent dealers.
Compaction Machines Market Segmentation
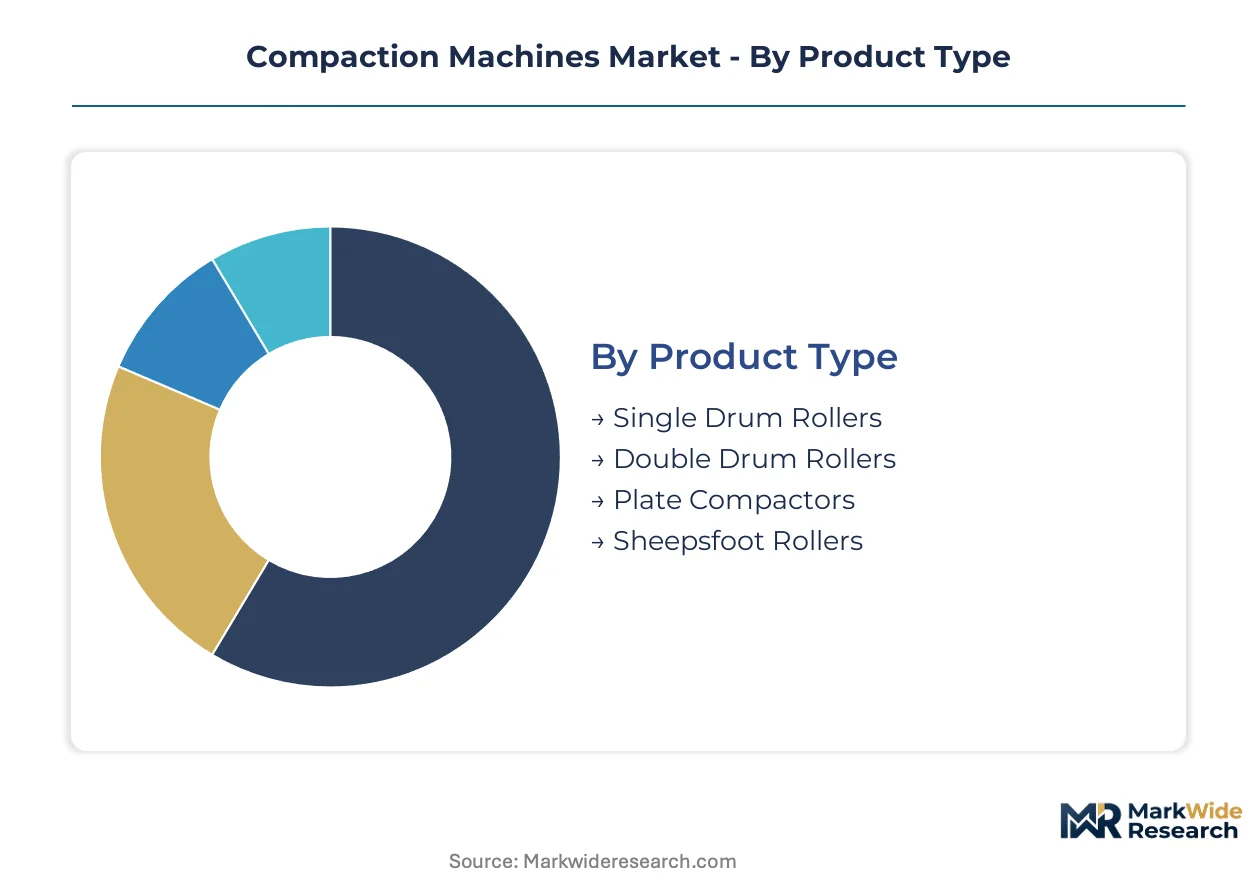
Compaction equipment segmentation reveals distinct procurement patterns across infrastructure verticals. Product architecture, application intensity, and powertrain configuration each impose unique total cost of ownership calculations on fleet operators.
Product Type:
Single drum rollers dominate domestic procurement in China and India where earthworks contractors prioritize gradeability and traction. Export flows concentrate double drum rollers toward European and North American asphalt finishing markets.
- Single Drum Rollers:These machines combine a steel vibratory drum with pneumatic or cleated rear tires to maintain traction on unbound surfaces. Demand clusters in China where state-owned construction enterprises expand highway subgrade fleets under infrastructure stimulus programs. The design sacrifices surface finish precision for slope-climbing torque and loose-soil flotation.
- Double Drum Rollers:Tandem drum configurations deliver uniform asphalt mat density through front and rear oscillation or vibration. German and French road contractors specify these units for federal-aid highway projects where intelligent compaction measurement validates layer quality. Premium positioning reflects surface tolerance requirements rather than raw compaction force.
- Plate Compactors:Flat-plate vibratory units address utility trenches and landscaping finish work where maneuverability outweighs throughput.
- Sheepsfoot Rollers:Pad-foot drum designs concentrate static pressure for cohesive soil densification in dam embankment and landfill cell construction.
Single drum rollers command the established base. The steepest expansion runs through double drum rollers.
Application:
Cost tier stratification separates high-specification asphalt work from commodity soil preparation. Premium application segments absorb emissions compliance costs more readily than price-sensitive earthworks.
- Soil Compaction:Subgrade and embankment preparation consumes the highest machine-hour volumes across infrastructure programs. Indian Bharatmala highway contractors deploy large single drum fleets for cut-and-fill earthmoving sequences. Density specifications of 90-95% modified Proctor drive repeat-pass operations and fuel consumption.
- Asphalt Compaction:Mat finishing demands precise temperature-window timing and uniform density distribution. US state highway agencies increasingly mandate intelligent compaction systems with real-time density feedback and GPS pass-counting. The application commands rental rate premiums that justify newer Tier 4 Final equipment.
- Concrete Compaction:Vibratory screeds and roller-compacted concrete units serve dam spillway and industrial pavement specifications.
- Backfill Compaction:Trench and foundation backfill work favors plate compactors and small remote-controlled rollers for confined access.
Soil compaction absorbs the largest equipment population. Asphalt compaction is climbing the fastest on technology upgrade cycles.
End User:
Customer type determines fleet scale and financing structure. National contractors negotiate multi-year rental platforms while municipal maintenance crews prioritize compact equipment for restricted access.
- Construction:General building contractors deploy mixed fleets across foundation, grading, and paving phases. Chinese private developers and state-owned enterprises drive procurement through project finance arrangements tied to municipal bond issuance.
- Road Building:Specialized highway contractors concentrate the highest-value equipment holdings. Texas and California fleet operators consolidate supplier relationships around full-service maintenance agreements bundling telematics and predictive parts replacement.
- Earthworks:Mining reclamation and landfill operators run continuous-duty cycles that accelerate machine wear and replacement frequency.
- Landscaping:Municipal parks departments and residential contractors specify lightweight plate compactors and walk-behind rollers for noise-restricted urban zones.
Road building concentrates the premium installed base. Landscaping is gaining share fastest on electric equipment substitution.
Drive Type:
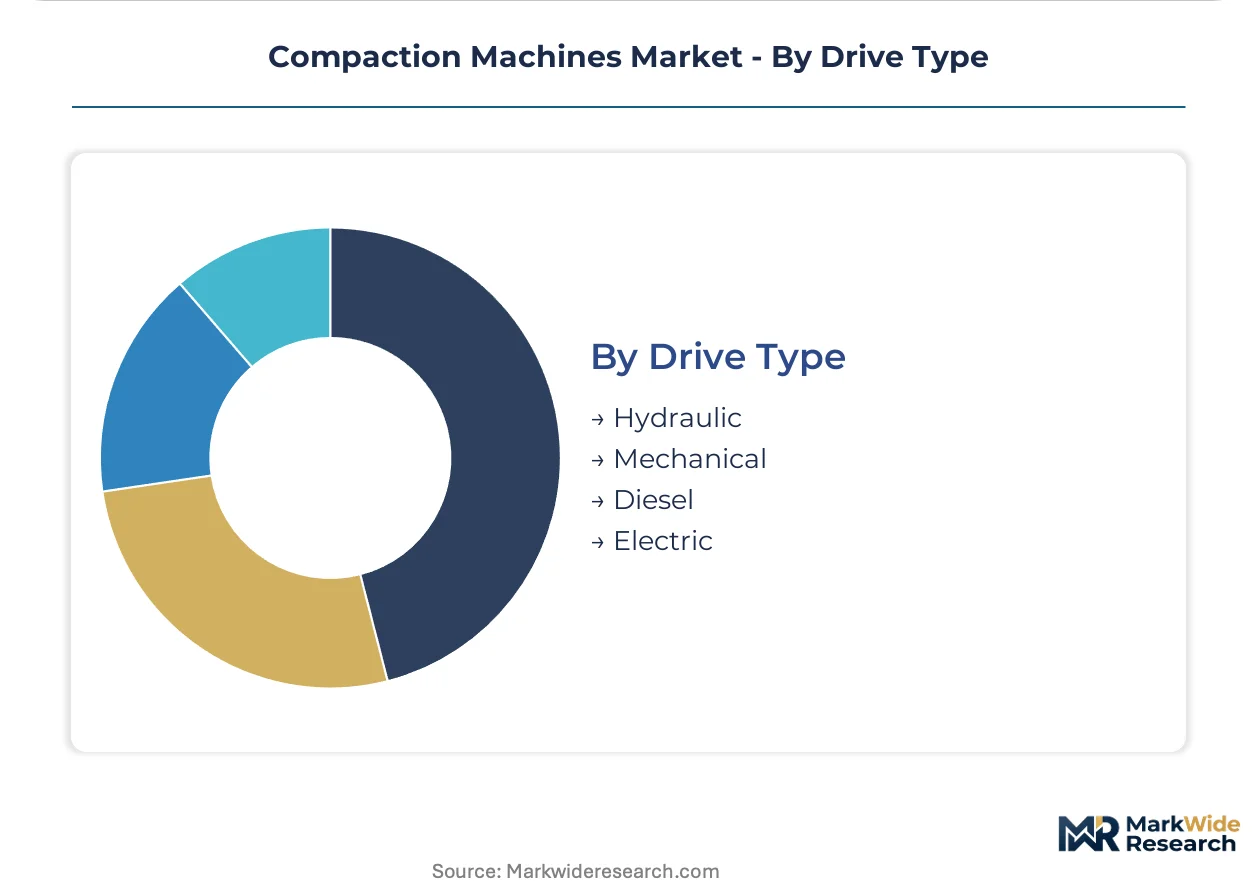
Powertrain architecture faces forced transition as emissions mandates and energy price structures reshape total cost equations. Hydraulic systems retain dominance in heavy soil compaction where torque density matters.
- Hydraulic:Hydrostatic transmissions deliver infinite speed variation and dynamic braking for slope work. The architecture dominates sheepsfoot and large single drum rollers where creep speed precision controls lift thickness.
- Mechanical:Direct mechanical drive persists in entry-tier plate compactors and legacy fleet holdings where capital constraints block replacement cycles.
- Diesel:Compression-ignition engines face after-treatment cost burdens from EPA Tier 4 Final and EU Stage V mandates. Cummins and Deutz supply concentration creates vulnerability to single-supplier disruption.
- Electric:Battery-powered variants penetrate plate compactors and small tandem rollers for European urban low-emission zones. Amsterdam and Copenhagen municipal crews specify swappable battery packs for nighttime noise-restricted operations.
Hydraulic drive commands the established base. Electric drive is expanding most quickly on regulatory pressure in dense urban cores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central government bond programs and emissions compliance deadlines are redirecting fleet procurement toward newer equipment across major construction economies. Municipal infrastructure stimulus and rental fleet replacement cycles sustain demand even as material costs pressure margins.
China
State-owned construction enterprises expand single drum roller fleets under transport infrastructure bond issuance. The Ministry of Ecology and Environment enforces China VI emissions standards for off-highway equipment in key metropolitan zones. Tier-two cities including Chengdu and Xi'an accelerate subway and highway densification projects.
United States
Federal-aid highway contractors specify intelligent compaction systems for asphalt quality validation. EPA Tier 4 Final mandates drive rental fleet turnover ahead of state-level low-emission zone adoption. Equipment lessors in Texas and California consolidate procurement around full-service telematics bundles.
Germany
Rental operators replace legacy diesel units ahead of municipal low-emission zone expansion in urban cores. EU Stage V compliance requirements filter equipment specifications for federal and state road contracts. Bavarian highway maintenance crews prioritize precision asphalt finishing equipment for autobahn resurfacing programs.
India
The Bharatmala highway initiative sustains soil compaction equipment procurement across state public works departments. The Central Pollution Control Board tightens construction equipment emissions norms in Delhi-NCR and other critical airsheds. Maharashtra and Gujarat contractors mechanize earthworks capacity for expressway corridors.
Netherlands
Municipal maintenance crews specify electric plate compactors for nighttime noise-restricted operations in Amsterdam and Rotterdam. EU F-Gas Regulation phase-down schedules accelerate refrigerant transitions in operator cab systems. Dutch rental platforms pilot subscription-based fleet access with hourly compaction output metering.
Compaction Machines Market Vendor Landscape
Player mix skews toward diversified heavy equipment conglomerates with captive engine manufacturing and specialized compaction technology specialists. Market structure concentrates procurement authority with national rental platforms and full-service maintenance providers. Two strategic archetypes dominate: integrated construction equipment manufacturers leveraging dealer networks, and compact equipment specialists targeting urban maneuverability requirements. Competitive moves center on telematics integration and multi-year service bundling rather than pure equipment sales.
Among integrated manufacturers, Caterpillar and Komatsu Ltd. exemplify the scale-driven archetype with captive supply chains and established distribution infrastructure. BOMAG GmbH occupies a specialist position within the precision asphalt compaction tier, while Ammann Group anchors the compact equipment segment for restricted-access urban job sites. Wacker Neuson SE sits within the lighter equipment category where electric drive variants are displacing traditional powertrains.
| Leading Market Players |
|---|
| Caterpillar |
| Volvo Construction Equipment |
| Komatsu Ltd. |
| Hitachi Construction Machinery Co., Ltd. |
| J C Bamford Excavators Ltd. |
| BOMAG GmbH |
| Ammann Group |
| Wacker Neuson SE |
| Terex Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term equipment lease agreements with bundled maintenance provisions lock in supply access and price visibility for fleet operators navigating EPA Tier 4 Final and EU Stage V compliance cycles. These contract structures insulate rental platforms from steel and hydraulic component volatility while committing OEMs to predictable aftermarket revenue streams.
Pricing Analysis
Certification level (ISO 14001/CE marking) creates the primary spread between premium and standard equipment tiers. Three-tier pricing structure across premium, standard, and economy levels reflects emissions compliance status, telematics integration depth, and after-sales service bundling. Price erosion runs through the economy tier as Chinese manufacturers expand export capacity for entry-level single drum rollers. Municipal buyers in Europe exhibit lowest price sensitivity due to ESG procurement mandates, while Indian earthworks contractors face acute capital constraints.
Supply Chain Analysis
China and Germany anchor steel drum fabrication and precision hydraulic component manufacturing for the compaction equipment sector. Production draws from high-grade steel sheet from integrated mills in Hebei and ThyssenKrupp operations in the Ruhr region. Cummins engine supply concentration in the sub-175hp segment creates single-source vulnerability for multiple OEM brands simultaneously. Distribution runs through captive dealer networks in North America and consolidated rental platforms in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full-service maintenance agreements and telematics subscriptions expand faster than hardware sales as rental fleet operators consolidate procurement around usage-based models. This service-attach dynamic repositions OEM economics toward recurring revenue streams.
For Market Incumbents: Consolidate supplier relationships around predictive parts replacement and remote diagnostics capabilities to defend against emerging electric equipment specialists. Secure backward integration into battery pack assembly or captive engine manufacturing to mitigate Tier 4 Final after-treatment cost compression. Prioritize certification investment in ISO 14001 environmental management to maintain specification access for municipal buyers. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany or Italy accelerates market access for compact electric plate compactor variants. Target Netherlands and Denmark municipal maintenance crews with swappable battery architectures for nighttime noise-restricted operations. Pursue direct rental platform partnerships rather than dealer network buildout to bypass incumbent channel control. For Investors and Strategic Acquirers: Capital is best deployed toward compact equipment specialists with demonstrated electric drive platforms and urban low-emission zone positioning. Long-term viability hinges on battery energy density improvements enabling heavy soil compaction electrification. Monitor India Bharatmala highway program execution rates as demand inflection indicator for soil compaction equipment procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Intelligent Compaction Technology Integration | GPS-integrated pass-counting systems satisfy US state highway agency specifications for federal-aid projects. |
| Electric Drive Platform Development | Swappable battery packs enable Amsterdam and Copenhagen municipal crews to meet nighttime noise restrictions. |
| Full-Service Maintenance Agreement Expansion | Multi-year telematics bundles concentrate procurement authority with Texas and California rental platforms. |
| ISO 14001 Certification Investment | Environmental management certification opens specification pathways for ESG-prioritizing institutional buyers. |
| India Distribution Partnership Establishment | State public works department relationships secure access to Bharatmala highway program equipment procurement. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet maintenance directors, OEM procurement teams, rental platform operations heads, and aftermarket service managers. Secondary validation drew from EPA regulatory filings, EU Stage V implementation guidance, China VI emissions standards documentation, and construction equipment customs trade data. Bottom-up equipment shipment modeling and top-down infrastructure spending allocation triangulated market sizing across the analysis window.
Across the projection horizon, volume and value outputs segment by product architecture (single drum, double drum, plate compactor, sheepsfoot), application intensity (soil, asphalt, concrete, backfill), end-user type (construction, road building, earthworks, landscaping), and powertrain configuration (hydraulic, mechanical, diesel, electric). CAGRs derive from infrastructure stimulus program trajectories, emissions compliance retrofit cycles, and regional energy price structures. Model inputs include China central government bond issuance flows, India Bharatmala highway kilometer completion rates, and EU low-emission zone expansion schedules.
Decision-makers should treat outputs as directional under sustained infrastructure stimulus and emissions compliance enforcement assumptions; material deviation in commodity steel pricing or battery energy density improvement would warrant model refresh. Recalibration cycles align with material shifts in regulatory enforcement timelines and central government infrastructure program announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Global Metal Expansion Joints Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Hoist Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Ball Screw Support Unit Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Vertical Reciprocating Conveyor Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market