
 Cold Planers Market | 2026-2036
Cold Planers Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Planers Market Analysis
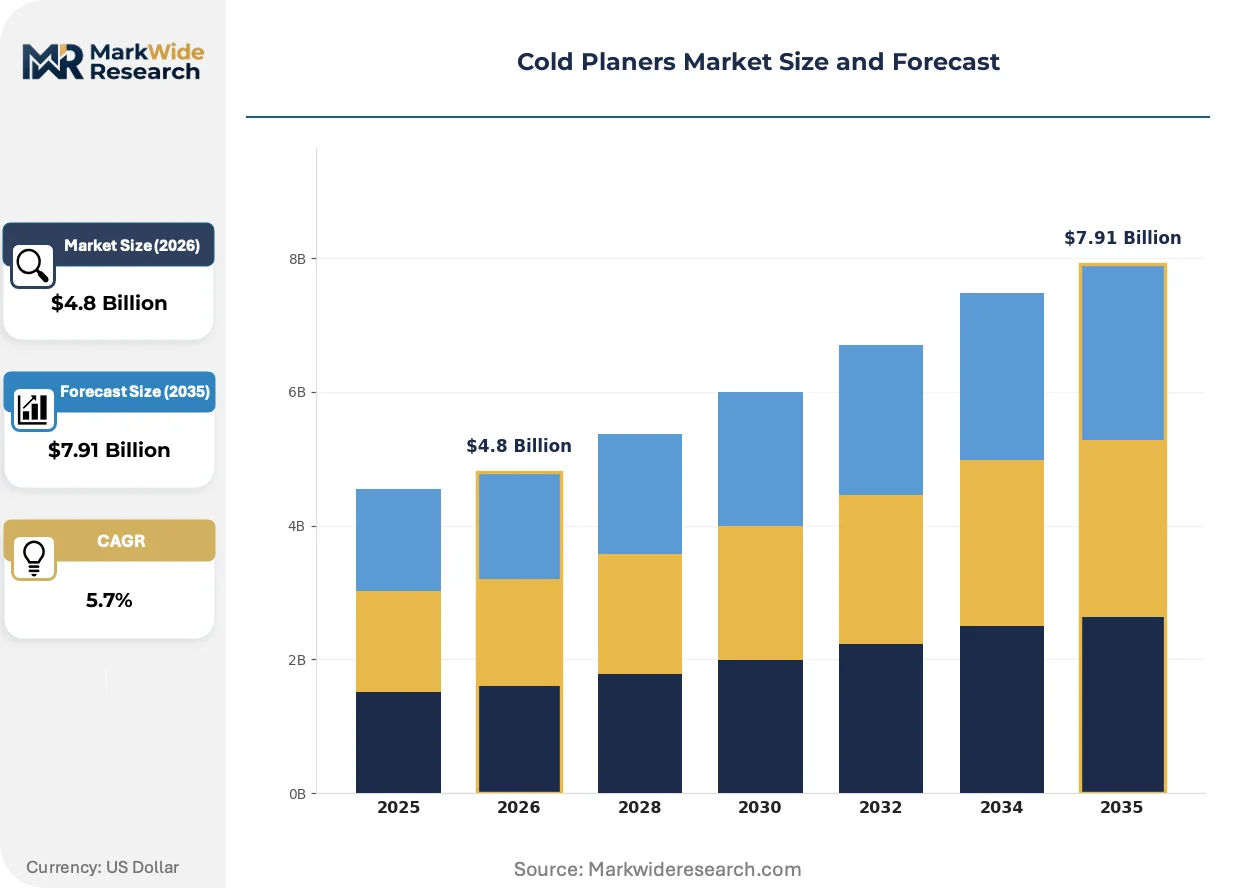
Equipment leasing and project-based financing is tilting competitive access toward mid-tier contractors who previously lacked capital for cold planer ownership. Wirtgen GmbH leverages its German engineering heritage to dominate precision milling technology. Caterpillar Inc. sustains global parts availability through an extensive dealer network. SANY Group anchors its position with cost-competitive manufacturing scale.
A cold planer, or pavement milling machine, is a specialized construction vehicle equipped with a rotating drum fitted with carbide-tipped teeth that remove asphalt or concrete layers to controlled depths, typically between inches and full pavement removal, producing reclaimed material for recycling. The machine grades and profiles road surfaces to prepare substrates for resurfacing. Milling machines lead product type demand due to their versatility across highway and urban applications, while hybrid technology represents the fastest-expanding segment as contractors face emission compliance costs. Road Maintenance Services command premium pricing for specialized urban work where maneuverability constraints limit machine selection.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe enforce stringent particulate and NOx limits that elevate R&D costs and filter system complexity for diesel-powered cold planers. China's MEE enforces domestic emission zones that accelerate electric and hybrid adoption in municipal fleets. Stakeholders must weigh powertrain transition timing against residual value risk in diesel-dominant secondary markets.
Market Dynamics
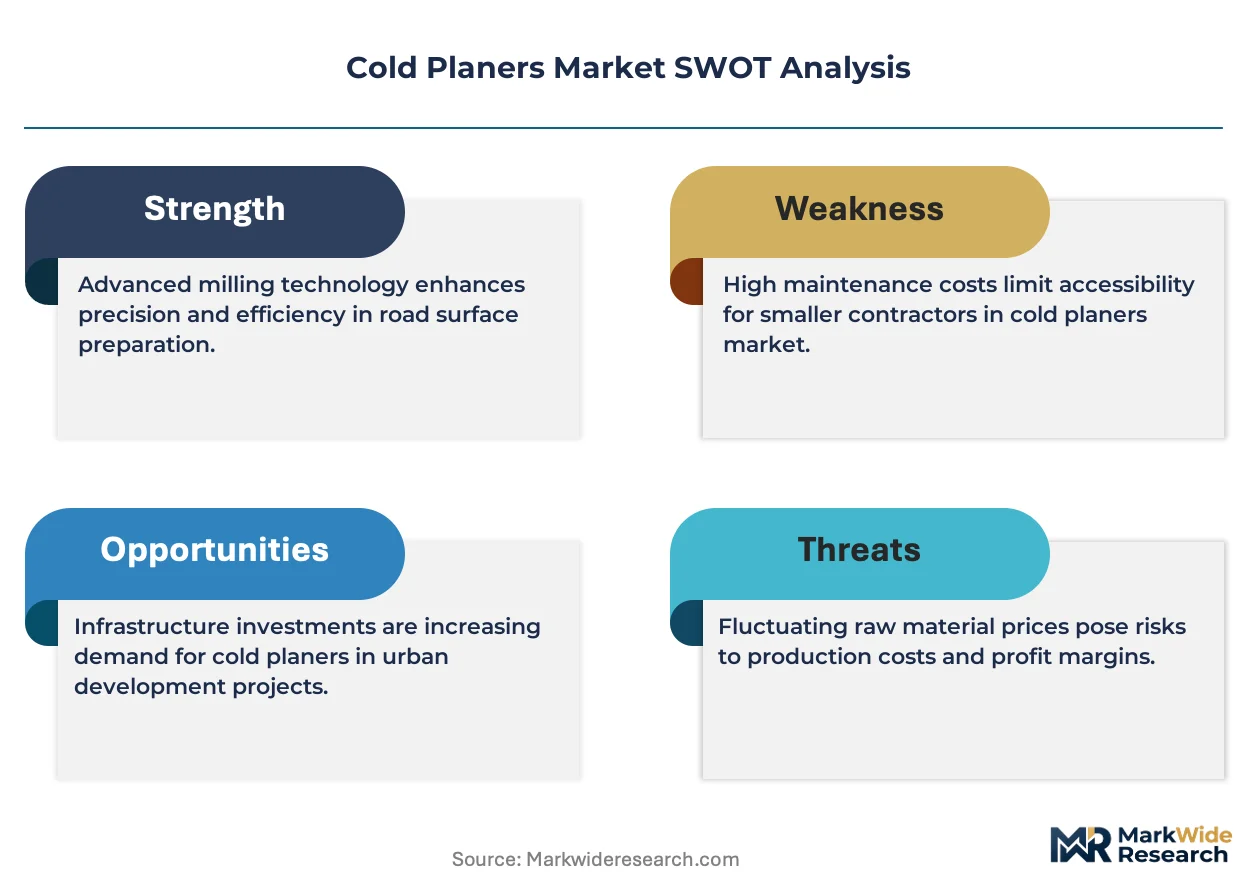
EPA Tier 4 Final emission standards are compressing diesel powertrain margins while forcing rapid hybrid-electric R&D investment across cold planer OEMs, fundamentally restructuring competitive economics.
Growth Catalysts
- Hybrid Powertrain Mandates:EPA Tier 4 Final and EU Stage V regulations are compelling fleet operators toward electrified cold planers to avoid non-compliance penalties and operational restrictions in urban zones.
- German Municipal Fleet Renewal:Road maintenance agencies in Germany are accelerating capital deployment for precision milling equipment as federal infrastructure rehabilitation budgets expand.
- China's Provincial Highway Rehabilitation:Aging infrastructure across China's provincial networks is generating sustained demand for full-depth removal capabilities and reclaimed asphalt processing.
Market Restraints
- Battery Cost Volatility:Lithium-ion cell price fluctuations are elevating total cost of ownership for hybrid-electric cold planers versus conventional diesel units.
- Filter System Complexity:Diesel particulate filter and selective catalytic reduction maintenance requirements under Tier 4 Final are extending downtime intervals and service costs.
- Secondary Market Diesel Dominance:Residual value risk in used equipment markets favors conventional powertrains, slowing fleet transition timing for capital-constrained contractors.
Strategic Opportunities
- Project-Based Financing Expansion:Equipment leasing structures are opening cold planer access to mid-tier contractors previously excluded by ownership capital requirements.
- Reclaimed Material Processing Integration:Convergence of milling and on-site recycling technologies is creating bundled service offerings for highway rehabilitation contracts.
- Urban Maneuverability Specialization:Compact cold planer variants for constrained municipal environments command premium positioning in European and North American cities.
Industry Challenges
- Powertrain Technician Scarcity:Hybrid-electric system diagnostics and high-voltage maintenance require specialized training programs that OEM dealer networks are racing to deploy.
- Emission Certification Timelines:EPA and EU type-approval processes for new powertrain configurations are extending product launch cycles and freezing engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Planers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trencher, Milling Machine, Road Repair Machine, Combination Machine Technology: Pneumatic, Hydraulic, Electric, Hybrid End User: Construction Companies, Municipalities, Contractors, Road Maintenance Services Distribution Channel: Direct Sales, Online Retail, Distributors, Dealers |
| Companies Covered | Caterpillar Inc., Wirtgen GmbH, BOMAG GmbH, Dynapac AB, SANY Group, XCMG Group, Roadtec Inc., Volvo Construction Equipment, Liugong Machinery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Planers Market Emerging Trajectories
Telematics integration and precision control systems are virtualizing traditional operator-dependent milling workflows, while regulatory pressure and financing innovation reshape how contractors access and deploy cold planer capacity.
Machine guidance systems utilizing real-time elevation sensing and automated drum control are virtualizing operator skill requirements for grade-critical milling operations. Municipal agencies in Germany and the Netherlands are specifying these systems for urban resurfacing contracts where substrate preparation tolerances are tight. The technology is virtualizing competitive differentiation from hardware durability toward software precision and data integration capabilities.
EPA Tier 4 Final enforcement is eliminating non-compliant diesel cold planers from US municipal fleet eligibility, compressing resale values and accelerating hybrid development timelines. Equipment lessors are restructuring contract terms to transfer emission compliance risk from contractors to financing entities. The regulatory pressure is concentrating most intensely in California air districts and Northeast state implementation plans.
Outcome-based service agreements are displacing traditional equipment purchase models among mid-tier highway contractors facing capital constraints. Leasing providers are bundling maintenance, telematics, and emission compliance into per-meter-milled pricing structures. This procurement evolution is most advanced in Germany's federal highway maintenance sector and spreading through US state department of transportation contractor tiers.
Cold Planers Market Segmentation
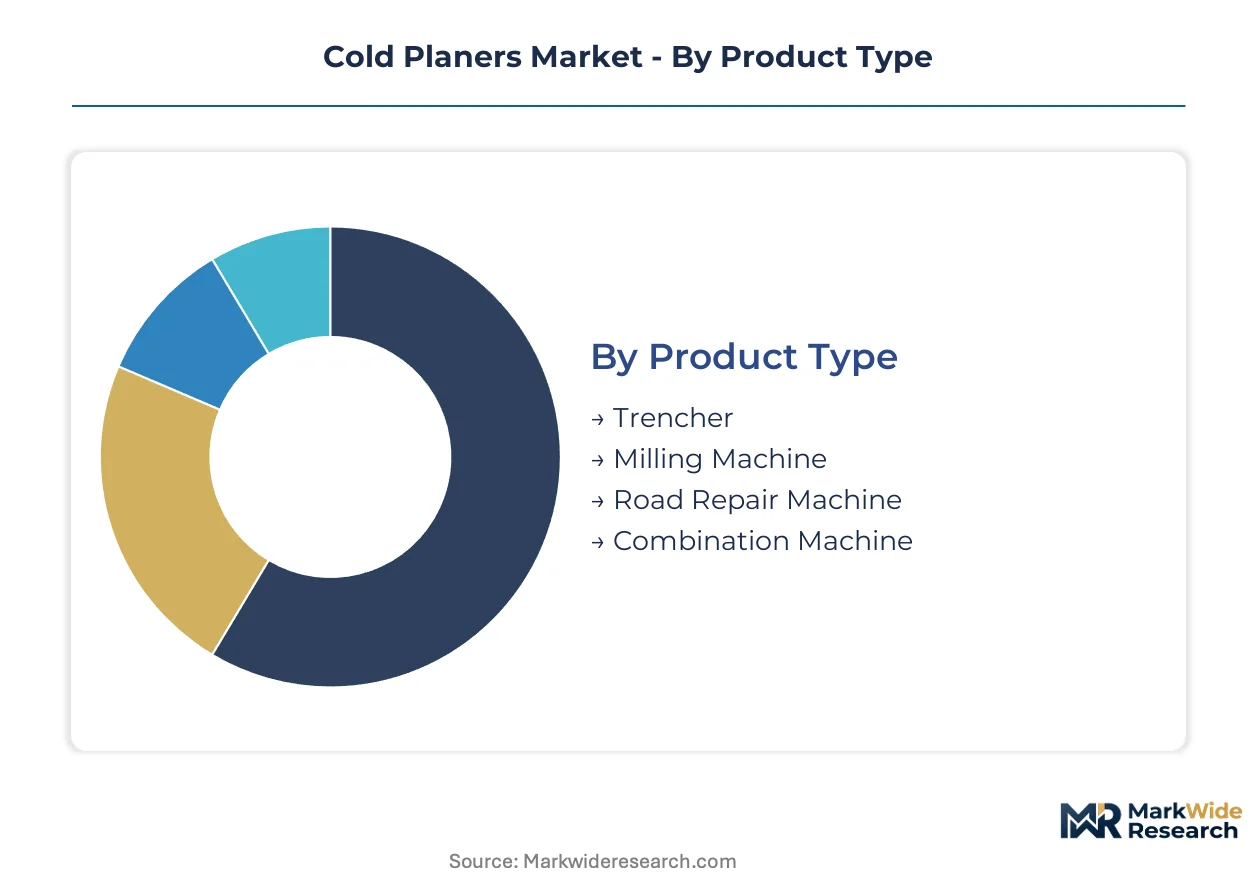
Cold planer procurement patterns diverge sharply across user sophistication, project scale, and regulatory exposure. Segment boundaries increasingly blur as hybrid powertrains and telematics bundles reshape traditional equipment categories.
Product Type:
Municipal agencies and highway contractors deploy distinct form factors based on maneuverability constraints and cut-depth specifications.
- Milling Machine:Rotating drum systems with carbide-tipped teeth execute controlled-depth asphalt removal across highway and urban substrates. German federal highway maintenance contracts specify these units for precision substrate preparation where grade tolerances are tight.
- Combination Machine:Integrated milling and paving functions reduce equipment mobilization costs for continuous rehabilitation workflows. Chinese provincial highway authorities favor these configurations for aging infrastructure corridors requiring rapid turnaround.
- Trencher:Narrow-cut drum assemblies target utility trenching and edge milling applications.
- Road Repair Machine:Compact chassis designs navigate constrained urban environments for patchwork resurfacing.
Established volume favors Milling Machine; emerging adoption favors Combination Machine.
Technology:
Powertrain selection now hinges on emission zone access and total cost of ownership calculations across depreciation horizons.
- Hybrid:Dual diesel-electric architectures deliver torque for drum operation while enabling zero-emission idle and transit modes. EPA Tier 4 Final enforcement in California air districts and Northeast state implementation plans accelerates fleet eligibility requirements for these configurations.
- Hydraulic:Proportional valve systems govern drum elevation and conveyor positioning with established service infrastructure. Contractors in secondary markets with residual value concerns favor these units for diesel-dominant resale liquidity.
- Electric:Battery-dominant architectures suit enclosed municipal depots with charging infrastructure.
- Pneumatic:Compressed air actuation persists in specialized cutting head adjustments for legacy equipment.
Contractor procurement tilts toward Hydraulic for immediate deployment; regulatory pressure concentrates fastest on Hybrid.
End User:
Capital structure and project duration dictate ownership versus leasing preferences across user categories.
- Road Maintenance Services:Specialized urban contractors command premium positioning where maneuverability constraints limit machine selection. Dutch municipal agencies specify these providers for grade-critical resurfacing in historic city centers.
- Construction Companies:Diversified equipment fleets amortize cold planer capital across highway, commercial, and residential paving portfolios. German mid-tier contractors access these assets through project-based financing structures that transfer compliance risk to lessors.
- Municipalities:Direct fleet ownership dominates federal highway maintenance programs with multi-year rehabilitation budgets.
- Contractors:Project-specific leasing arrangements predominate for capital-constrained operators in competitive bidding environments.
Procurement concentration sits with Road Maintenance Services; financing innovation opens fastest access for Construction Companies.
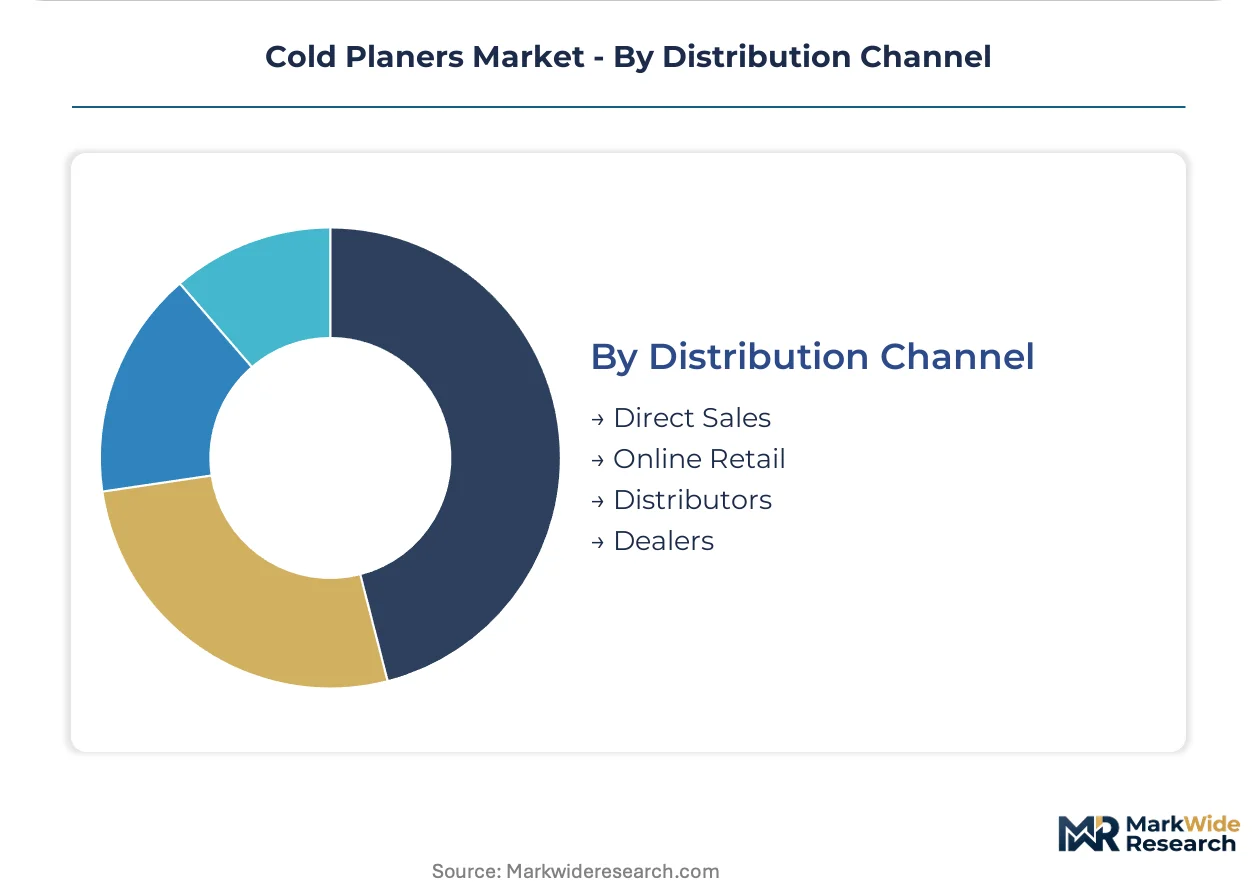
Distribution Channel:
Channel selection reflects equipment complexity, service dependency, and buyer sophistication gradients.
- Direct Sales:OEM field organizations manage specification-intensive municipal and federal highway contracts. Wirtgen GmbH deploys German engineering teams for precision milling technology consultations with state road authorities.
- Dealers:Extensive parts availability networks sustain uptime commitments for fleet operators. Caterpillar Inc. leverages this infrastructure across North American maintenance corridors.
- Distributors:Regional inventory positioning serves time-sensitive project mobilization requirements.
- Online Retail:Digital channels facilitate consumables and attachment procurement for established fleet operators.
Service intensity preserves Dealer dominance; digital efficiency gains concentrate fastest in Online Retail for aftermarket segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure rehabilitation budgets and emission zone enforcement are redirecting cold planer procurement toward compliant powertrains across major highway maintenance markets.
United States
State department of transportation contractors face compressed diesel resale values as EPA Tier 4 Final enforcement eliminates non-compliant units from municipal fleet eligibility. California air districts and Northeast state implementation plans concentrate regulatory pressure most intensely. Equipment lessors in Texas and Florida restructuring contract terms to transfer emission compliance risk to financing entities.
Germany
Road maintenance agencies accelerate capital deployment for precision milling equipment as federal infrastructure rehabilitation budgets expand. KBA emission standards align with EU Stage V regulations enforcing stringent particulate limits. Municipal fleet renewal programs in Bavaria and North Rhine-Westphalia specify machine guidance systems for grade-critical urban resurfacing.
China
Aging infrastructure across provincial highway networks generates sustained demand for full-depth removal capabilities and reclaimed asphalt processing. MEE domestic emission zones accelerate electric and hybrid adoption in municipal fleets. Highway rehabilitation corridors in Jiangsu and Guangdong provinces drive combination machine procurement for rapid turnaround requirements.
India
National highway expansion programs and urban road resurfacing initiatives create dual-track demand for highway-scale and compact cold planer configurations. BIS certification requirements and state-level emission norms shape equipment import and local assembly decisions. Construction clusters in Maharashtra and Gujarat concentrate contractor fleet investments.
Japan
Metropolitan highway maintenance agencies prioritize compact cold planer variants for constrained urban environments with tight maneuverability requirements. METI energy efficiency guidelines influence municipal fleet procurement specifications. Infrastructure renewal projects in the Tokyo-Osaka corridor drive precision milling technology adoption.
Cold Planers Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where dealer network density and engineering heritage determine positioning. The vendor base organizes around three strategic archetypes: German precision engineering specialists, North American parts availability leaders, and Chinese manufacturing scale operators. Competitive moves concentrate on hybrid powertrain R&D acceleration and project-based financing partnership structures.
Within the precision engineering tier, Wirtgen GmbH and BOMAG GmbH exemplify German heritage positioning. Caterpillar Inc. anchors the North American channel-control archetype through extensive dealer infrastructure. SANY Group occupies the manufacturing scale position among Chinese fabricators.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Wirtgen GmbH |
| BOMAG GmbH |
| Dynapac AB |
| SANY Group |
| XCMG Group |
| Roadtec Inc. |
| Volvo Construction Equipment |
| Liugong Machinery Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
German precision-milling component suppliers anchor upstream concentration, directing margin capture toward OEMs with captive engineering capabilities and dealer-controlled aftermarket channels. Battery cell sourcing from South Korean and Chinese manufacturers feeds cost volatility into hybrid-electric cold planer pricing, compressing assembler margins while elevating financing entity risk absorption.
Pricing Analysis
Certification level (EPA Tier 4 Final / EU Stage V) creates the primary spread between compliant hybrid-electric units and legacy diesel configurations. Three-tier pricing structure across premium precision-milling, standard highway-grade, and economy compact urban tiers reflects after-sales service bundling and telematics integration depth. Cost compression in mid-tier diesel inventory is intensifying because secondary market liquidity favors conventional powertrains. Municipal fleet operators show lowest price sensitivity due to federal budget insulation; mid-tier contractors exhibit highest sensitivity, driving project-based financing proliferation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for carbide-tipped cutting teeth and high-torque electric drivetrain components. Manufacturing concentrates in Germany for precision milling assemblies, China for structural fabrications and battery packs, and Japan for compact hydraulic systems. Raw material dependencies span lithium carbonate for hybrid powertrains, tungsten carbide for cutting inserts, and high-grade steel alloys for drum assemblies. Single-source vulnerability persists in machine guidance sensor modules. Distribution runs through OEM-captive dealer networks for specification-intensive municipal contracts and regional distributors for time-sensitive project mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold planer OEMs face substitution pressure from reclaimed asphalt processing technologies that reduce milling intensity requirements in highway rehabilitation workflows. Incumbents must defend against equipment-as-a-service models that displace ownership economics.
For Market Incumbents: Pre-empt hybrid powertrain margin erosion by securing captive battery supply agreements with South Korean cell manufacturers. Accelerate machine guidance software development to shift competitive differentiation from hardware durability toward data-driven precision services. Vertical integration into reclaimed material processing equipment reduces exposure to pure-play milling demand cycles. Channel control through dealer network service capacity investments defends against leasing company disintermediation.
For New Entrants and Emerging Players: Pursue compact urban cold planer specialization for European municipal markets where maneuverability constraints limit incumbent machine selection. Target Chinese provincial highway contractors with cost-competitive combination machine offerings that integrate milling and paving functions. Equipment-as-a-service go-to-market structures bypass capital ownership barriers for mid-tier contractors in Germany's federal maintenance sector.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German precision engineering specialists holding machine guidance intellectual property. Long-term viability hinges on hybrid powertrain transition timing against residual value risk in diesel-dominant secondary markets. Acquisition candidates with captive software development capabilities and established municipal agency relationships offer defensive positioning. Watch EPA enforcement intensity in California air districts and Northeast state implementation plans as fleet eligibility inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain R&D Acceleration | EPA Tier 4 Final compliance in California and Northeast districts mandates electrified fleet eligibility. |
| Machine Guidance Software Development | German municipal agencies specify real-time elevation sensing for grade-critical urban resurfacing contracts. |
| Project-Based Financing Partnerships | Equipment lessors in Texas and Florida transfer emission compliance risk from capital-constrained contractors. |
| Reclaimed Material Processing Integration | Chinese provincial highway authorities bundle milling and on-site recycling for rapid turnaround requirements. |
| Dealer Network Service Capacity Expansion | Caterpillar's North American infrastructure sustains uptime commitments for fleet operators across maintenance corridors. |
Methodological Framework
Desk research of customs trade databases, OEM technical specifications, and federal infrastructure budget disclosures preceded structured interviews with municipal fleet managers, highway contractor equipment procurement leads, OEM aftermarket service directors, and equipment leasing company risk officers. Secondary validation drew from EPA enforcement records, EU Stage V type-approval documentation, and Chinese provincial highway rehabilitation tender announcements. Bottom-up unit deployment estimates triangulated against top-down infrastructure spending allocation models.
Assumptions held fixed include prevailing emission regulatory enforcement timelines and lithium-ion cell cost trajectories; sensitivity analysis varied hybrid powertrain adoption rates and secondary market diesel residual value recovery patterns. Segmentation dimensions spanned product type (milling machine, combination machine, trencher, road repair machine), powertrain technology (hybrid, hydraulic, electric, pneumatic), and end-user capital structure (municipal ownership, contractor leasing, project-based financing). CAGRs derived from equipment replacement cycle analysis and federal rehabilitation budget growth projections. Industry-specific inputs included reclaimed asphalt pavement utilization rates and machine guidance system specification penetration in European municipal contracts.
Macroeconomic conditions sit as an overlay; deviation in federal infrastructure appropriations, construction labor availability, or battery raw material prices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and powertrain technology maturation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Excavator Attachments Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Electric Shovel Market
Construction Equipment
Yard Crane Market
Construction Equipment
North America: Heavy Construction Equipment Market
Construction Equipment
Extrusion Machinery Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
Concrete Chain Saw Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Global Mobile Concrete Mixer Market