
 Global Portable Sawmills Market | 2026-2036
Global Portable Sawmills Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Sawmills Market Outlook
Canadian band saw manufacturers is expanding production lines to serve backlogged orders from remote forestry camps. Wood-Mizer leverages its established dealer network across six continents to sustain replacement parts revenue. Hud-Son Forest Equipment specializes in entry-level hydraulic models that anchor its position among hobbyist landowners. Peterson Portable Sawmills competes through swing-blade technology that reduces kerf waste in tropical hardwood applications.
Portable sawmills are self-contained milling machines, typically mounted on trailers or skids, that convert logs into dimensional lumber using band saw or circular saw blades with cutting widths ranging from 26 to 72 inches. Their primary commercial purpose is enabling on-site timber processing for small to medium-scale operators without the capital burden of stationary mill infrastructure. Electric and hydraulic product types command margin pools in professional contractor segments where throughput reliability outweighs purchase price, while manual units retain dominance among hobbyist end users seeking sub-five-thousand-dollar entry points. Compact size classifications are experiencing the fastest volume growth as urban woodworkers and farmstead operators seek space-efficient equipment for intermittent use.
EPA Phase 3 small engine emissions standards and the EU Machinery Directive's CE marking requirements are elevating compliance costs for gasoline-powered manual units while accelerating electric platform development. ISO 19085 safety standards for woodworking machinery are reshaping guard and emergency-stop specifications across export-oriented manufacturers. Stakeholders must monitor evolving carbon-accounting frameworks for harvested wood products, as lifecycle certification becomes a procurement filter for sustainable construction supply chains.
Market Dynamics
EPA Phase 3 small engine emissions standards and the EU Machinery Directive are compressing gasoline-powered manual unit margins while forcing rapid electric platform development across North American and European manufacturers.
Growth Catalysts
- EPA Phase 3 Compliance Deadlines:Tiered implementation through 2025-2027 is accelerating dealer inventory turnover and replacement demand for certified equipment in the United States.
- Decentralized Forestry Models:Small private woodlot ownership in Scandinavia and the Pacific Northwest is creating sustained demand for on-site processing capability without stationary mill investment.
- Band Saw Blade Advancements:Bi-metal and carbide-tipped blade technologies are extending service intervals and reducing downtime for remote forestry camps.
Market Restraints
- Steel Price Volatility:Fluctuations in high-carbon steel and alloy inputs are compressing fabrication margins for trailer-mounted chassis and blade components.
- CE Marking Complexity:The EU Machinery Directive's conformity assessment procedures are extending time-to-market for North American exporters by 4-8 months.
- Stationary Mill Competition:Regional mini-mills with automated optimization systems are capturing dimensional lumber contracts previously served by portable operators.
Strategic Opportunities
- Battery-Electric Platforms:Lithium-ion powertrains paired with solar charging kits are opening sales channels among off-grid farmstead operators and conservation land managers.
- Urban Woodworker Segment:Compact 26-inch cutting width units are penetrating metropolitan maker spaces and craft woodworking collectives in Germany and the United Kingdom.
- Carbon Accounting Integration:Lifecycle certification frameworks for harvested wood products are creating procurement preference for documented low-emission milling equipment in sustainable construction supply chains.
Industry Challenges
- Skilled Blade Maintenance Shortage:Experienced technicians capable of precision band saw tensioning and alignment are concentrated among aging workforce cohorts in rural sawmill service regions.
- ISO 19085 Certification Timelines:Guard redesign and emergency-stop system validation for woodworking machinery safety standards are delaying new model launches by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Sawmills Market |
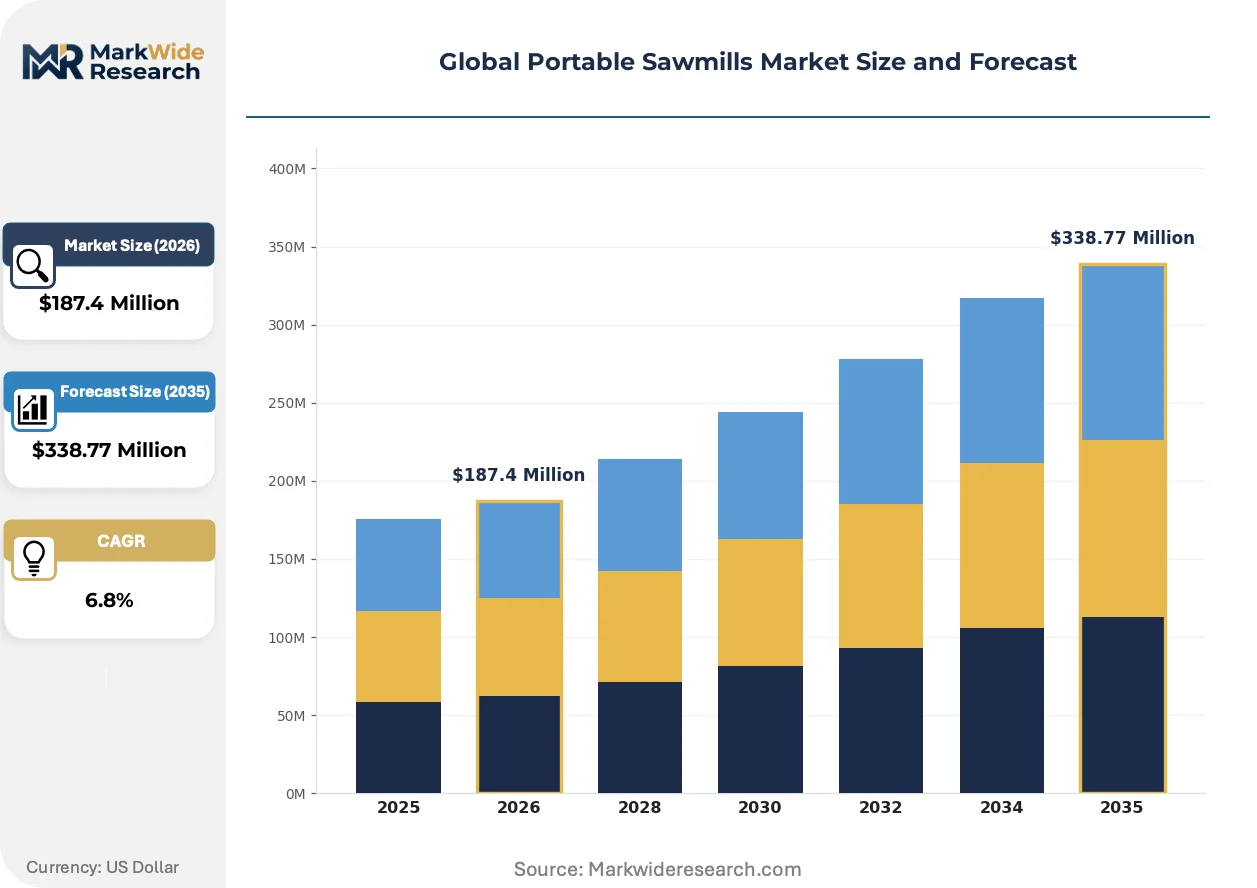
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Hydraulic, Electric, Band Saw Application: Lumber Production, Woodworking, Timber Processing, Furniture Manufacturing End User: Contractors, Hobbyists, Manufacturers, Retail Outlets Size: Compact, Standard, Heavy-Duty, Industrial |
| Companies Covered | Logosol, Hud-Son Forest Equipment, Wood-Mizer, Serra Maschinenbau, Woodland Mills, Norwood Industries, Baker Products, Peterson Portable Sawmills, TimberKing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Sawmills Market Strategic Shifts
Electrification and digital control systems are displacing mechanical-hydraulic architectures across professional-grade equipment, while regulatory pressure on small-engine emissions is bifurcating product development roadmaps between compliance-focused and exemption-seeking manufacturers.
Brushless DC electric drivetrains with integrated variable frequency control are absorbing the performance requirements previously met by gasoline engines in 35-50 horsepower equivalent classes. Professional contractors in the United States Pacific Northwest are specifying electric platforms for indoor and noise-restricted milling operations. This technology is absorbing capital allocation from hydraulic system R&D and compressing the price premium between electric and combustion alternatives.
REACH substance restrictions on chromium VI in surface treatments are forcing blade coating suppliers to accelerate tungsten carbide and ceramic alternative development. European manufacturers face reformulation costs for corrosion-resistant chassis finishes. The professional contractor segment in Germany and Austria is absorbing price increases for compliant equipment while demanding extended warranty terms.
Direct-to-operator digital sales channels are displacing traditional agricultural equipment dealer networks for entry-level and hobbyist segments. Manufacturers in Canada and the United States are building configuration tools and video-based setup support to reduce pre-purchase friction. This pattern is most visible among farmstead operators aged 35-50 seeking sub-ten-thousand-dollar hydraulic entry points without dealer markup.
Global Portable Sawmills Market Segmentation
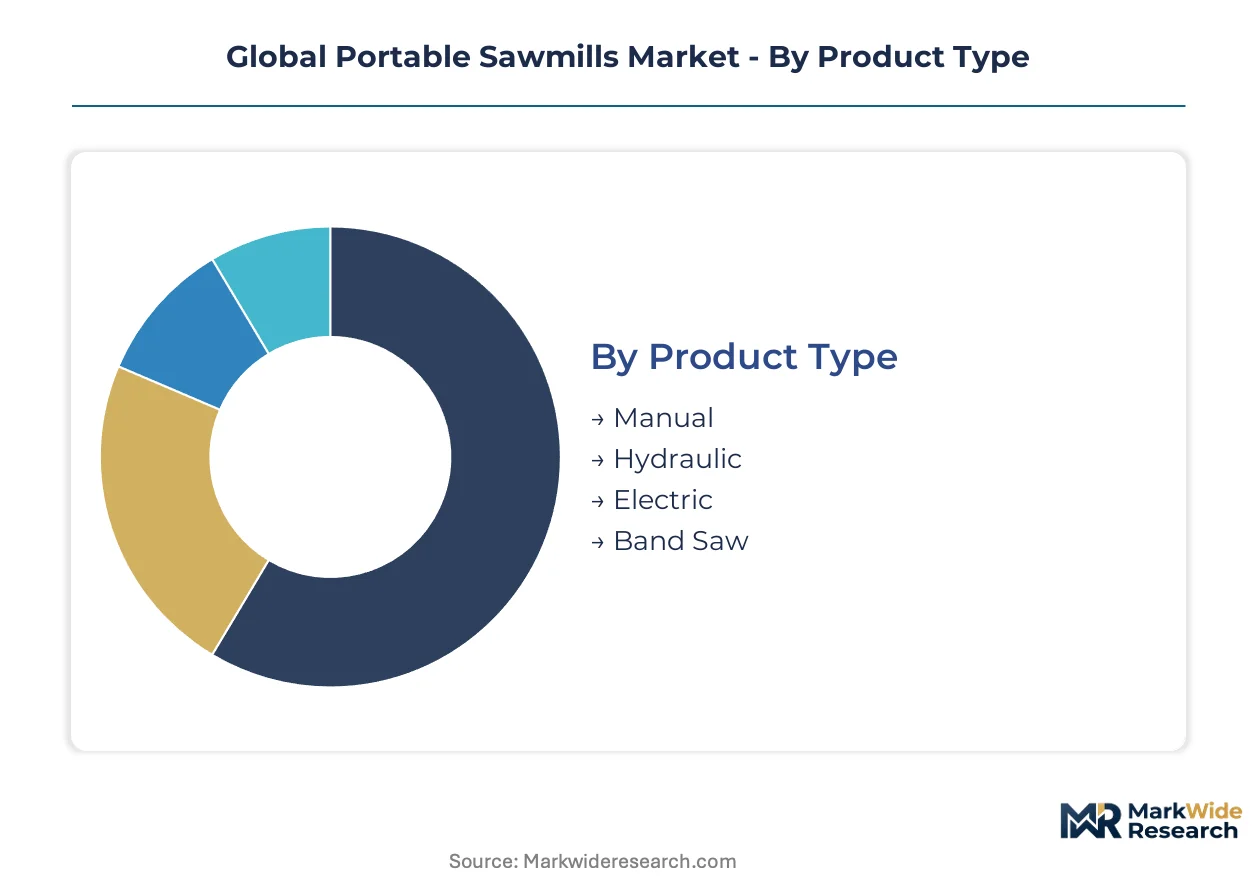
Portable sawmill segmentation reveals divergent margin pools between price-sensitive hobbyist entry points and professional-grade throughput systems. Equipment specifications, powertrain architecture, and cutting width dimensions create distinct procurement filters across decentralized forestry operations and urban woodworking collectives.
Product Type:
Volume concentration sits with sub-five-thousand-dollar manual units, while premium pools concentrate in electric and hydraulic platforms where reliability commands price tolerance.
- Manual:Hand-cranked mechanical systems with 26-36 inch cutting widths and minimal engine components. Demand concentrates among hobbyist landowners in the United States Appalachian region and Scandinavian summer cabin operators seeking sub-$5,000 entry points without emissions compliance burdens.
- Hydraulic:Self-powered log handling and blade positioning systems with 40-60 inch cutting capacities. Professional contractors in the United States Pacific Northwest and British Columbia remote forestry camps specify these units for sustained daily throughput where labor efficiency outweighs capital cost.
- Electric:Brushless DC drivetrains with integrated variable frequency control delivering 35-50 horsepower equivalent performance. Indoor milling operations in Germany and noise-restricted urban zones in the United Kingdom are absorbing these platforms fastest.
- Band Saw:Continuous loop blade architecture with bi-metal and carbide-tipped variants. Precision dimensional cutting for tropical hardwood applications in Southeast Asian decentralized milling operations.
Mature deployment sits with Manual units in established rural hobbyist markets. Newer deployment is concentrated in Electric platforms responding to EPA Phase 3 compliance deadlines and EU Machinery Directive emissions restrictions.
Application:
Commercial throughput requirements separate professional timber contracts from intermittent craft production, with certification demands fragmenting procurement criteria across construction supply chains.
- Lumber Production:Primary dimensional output for structural framing and construction-grade material. Small private woodlot owners in Sweden and Finland deploy portable units to bypass stationary mill aggregation economics.
- Woodworking:Specialty dimensioning for craft furniture and architectural millwork. Metropolitan maker spaces in Germany and the United Kingdom specify compact 26-inch units for intermittent batch production.
- Timber Processing:On-site conversion of felled logs at remote forestry camps. Canadian manufacturers report backlogged orders from backcountry operations requiring trailer-mounted mobility.
- Furniture Manufacturing:Custom dimensioning for boutique production runs and heritage restoration. Conservation land managers in Austria source documented low-emission equipment for carbon-accounting compliance.
Revenue concentration clusters in Lumber Production for professional contractor segments. Steepest expansion trajectory is appearing in Woodworking applications as urban craft collectives absorb compact electric platforms.
End User:
Procurement authority splits between fleet-scale equipment decisions and individual purchase thresholds, with digital sales channels displacing traditional dealer networks at the hobbyist tier.
- Contractors:Professional milling service providers operating multiple units across dispersed job sites. The United States Pacific Northwest and Scandinavia host the densest contractor populations serving small private woodlot owners.
- Hobbyists:Individual landowners and farmstead operators seeking intermittent personal-use capacity. Direct-to-operator digital configuration tools are penetrating this segment among United States and Canadian buyers aged 35-50.
- Manufacturers:Secondary wood products companies supplementing stationary mill capacity with portable on-site processing. Austrian and German firms lead adoption for certified sustainable construction supply chains.
- Retail Outlets:Equipment dealers and agricultural machinery distributors stocking entry-level inventory. Traditional networks persist in rural United States markets while eroding in European metropolitan zones.
Established procurement patterns dominate Contractor segments with multi-unit fleet refresh cycles. Digital-native purchasing is expanding fastest among Hobbyists bypassing dealer markup through manufacturer-direct channels.
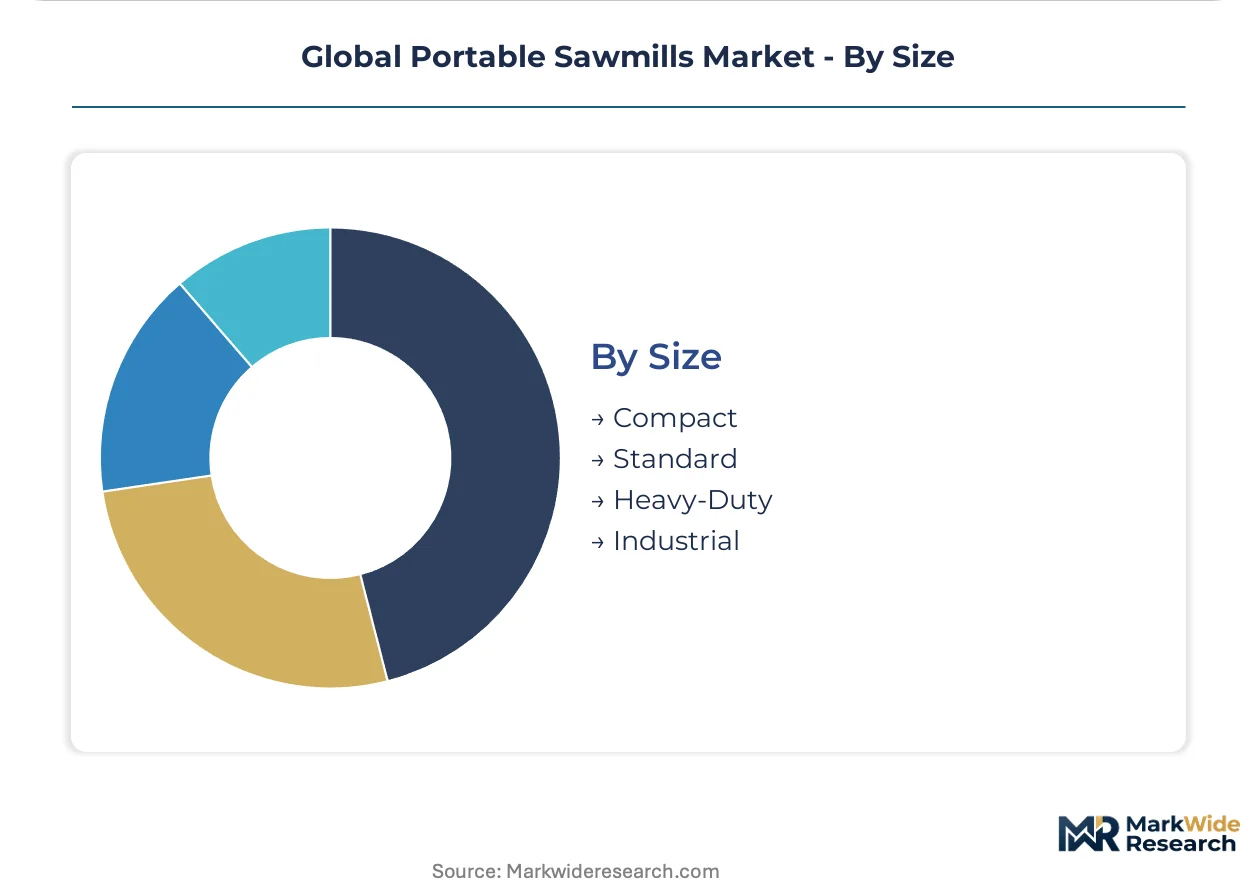
Size:
Physical footprint constraints create divergent addressable markets between space-limited urban environments and unrestricted rural operations.
- Compact:26-inch cutting width units with trailer-mounted or skid-based mobility. Urban woodworkers in Germany and the United Kingdom drive volume as metropolitan maker spaces prioritize space efficiency.
- Standard:36-48 inch cutting widths balancing throughput and transportability. Scandinavian farmstead operators and United States rural landowners form the core installed base.
- Heavy-Duty:50-60 inch capacities with reinforced chassis for sustained commercial use. Remote forestry camps in British Columbia and Alaska specify these for daily production schedules.
- Industrial:72-inch maximum cutting widths approaching stationary mill capability. Limited deployment concentrated among specialized contractors serving tropical hardwood extraction in Southeast Asia.
Volume leadership remains with Standard sizes in mature rural markets. Gaining share fastest are Compact units penetrating European urban woodworking collectives and farmstead operators seeking intermittent-use flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Softwood timber belts in the United States Pacific Northwest and Scandinavian lake districts anchor portable sawmill deployment density. Small private woodlot ownership patterns in these regions bypass stationary mill aggregation economics. Regulatory pressure on small-engine emissions is fragmenting equipment certification pathways across national markets.
United States
EPA Phase 3 small engine emissions standards are accelerating dealer inventory turnover in the Pacific Northwest and Appalachian timber regions. Tiered compliance deadlines through 2027 are compressing margins for gasoline-powered manual unit manufacturers. Oregon and Washington host the densest contractor populations serving decentralized forestry operations on federal and private timberlands.
Canada
Remote forestry camps in British Columbia and Alberta are absorbing trailer-mounted hydraulic units for backcountry timber processing. Health Canada's emissions alignment with EPA standards is elevating certification costs for cross-border equipment shipments. Quebec's hardwood regions are emerging as a secondary demand node for compact electric platforms among farmstead operators.
Germany
REACH substance restrictions on chromium VI in surface treatments are forcing blade coating reformulation for corrosion-resistant chassis finishes. The EU Machinery Directive's CE marking requirements are extending time-to-market for imported equipment by 4-8 months. Bavarian and Baden-Württemberg woodworking collectives are driving compact 26-inch electric unit adoption in metropolitan maker spaces.
Sweden
Small private woodlot ownership around Lake Vänern and Lake Vättern sustains demand for on-site processing without stationary mill investment. The Swedish Environmental Protection Agency's alignment with EU Green Deal carbon-accounting frameworks is filtering procurement toward documented low-emission equipment. Småland's forest cooperatives are standardizing fleet specifications around certified electric and hydraulic platforms.
Australia
Conservation land managers in Victoria and New South Wales are sourcing battery-electric platforms with solar charging kits for off-grid milling operations. The country's national environmental regulator is tightening noise restrictions in protected forest zones. Tasmania's specialty timber sector is absorbing swing-blade technology for precision cutting of native hardwood species.
Global Portable Sawmills Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue battery-electric specialization and direct-to-operator digital channels. The vendor base clusters around three maturity tiers: legacy manufacturers with continental dealer networks, regional fabricators serving backlogged forestry camp orders, and digital-native entrants targeting hobbyist price points. Strategic archetypes include throughput-focused contractors, carbon-accounting-compliant suppliers, and space-constrained urban woodworker specialists. Competitive moves concentrate on electric platform R&D acceleration and ISO 19085 safety certification pre-emption.
Within the legacy network tier, Wood-Mizer and TimberKing exemplify established dealer infrastructure models spanning multiple continents. Hud-Son Forest Equipment represents the entry-level hydraulic specialization archetype among North American fabricators. Peterson Portable Sawmills occupies a position within the precision-cutting technology segment, particularly for tropical hardwood applications. These anchors illustrate how competitive positioning fragments across powertrain architecture, distribution channel strategy, and end-user price tolerance rather than consolidating around scale advantages.
| Leading Market Players |
|---|
| Logosol |
| Hud-Son Forest Equipment |
| Wood-Mizer |
| Serra Maschinenbau |
| Woodland Mills |
| Norwood Industries |
| Baker Products |
| Peterson Portable Sawmills |
| TimberKing |
| Others |
Value Chain & Pricing Dynamics
High-carbon steel price indices cascade through portable sawmill fabrication economics, compressing margins on trailer-mounted chassis while amplifying price premiums for carbide-tipped blade configurations. Electric platform manufacturers absorb lithium-ion cell cost volatility through warranty bundling strategies that shift buyer preference toward total-cost-of-ownership framing.
Pricing Analysis
Warranty and service bundling separates premium electric platforms from unbundled manual entry points, with three-tier pricing structure across premium, standard, and economy levels anchored by blade technology grade and EPA certification status. Professional contractors in the Pacific Northwest exhibit lowest price sensitivity, prioritizing throughput reliability and ISO 19085 safety compliance over capital outlay. Hobbyist landowners aged 35-50 demonstrate acute price sensitivity, driving demand for sub-five-thousand-dollar hydraulic entry points through direct-to-operator digital channels. Cost compression in gasoline-powered manual tiers stems from Tiered EPA Phase 3 compliance investments.
Supply Chain Analysis
Skilled band saw technicians concentrate in aging workforce cohorts across rural Ontario and Michigan fabrication centers, constraining precision tensioning capacity for bi-metal blade production. Supply chains draw from Swedish specialty steel mills, Chinese lithium-ion cell manufacturers, and Canadian trailer chassis fabricators. REACH substance restrictions on chromium VI surface treatments create regulatory friction for corrosion-resistant finishes. Distribution runs through legacy agricultural equipment dealer networks in rural United States markets while digital-native channels penetrate European metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where blade coating technology and battery-electric drivetrain production constitute the decisive upstream levers. Players securing captive supply of carbide-tipped cutting edges and brushless DC motor assemblies will capture margin pools unavailable to assembly-only competitors.
For Market Incumbents: Extend certification pre-emption strategies by accelerating ISO 19085 guard redesign timelines ahead of competitor launches. Deepen backward integration into bi-metal blade foundries to offset steel price volatility and secure service-interval advantages against emerging electric entrants. Lock in dealer network exclusivity across Pacific Northwest timber regions where contractor fleet refresh cycles concentrate replacement demand.
For New Entrants and Emerging Players: Capture the urban woodworker white space in German and United Kingdom metropolitan maker spaces through compact 26-inch electric platforms with video-based setup support. Penetrate the off-grid farmstead segment via solar charging kit bundling that incumbent hydraulic specialists have neglected. Deploy direct-to-operator configuration tools to bypass dealer markup and access price-sensitive hobbyist buyers aged 35-50.
For Investors and Strategic Acquirers: Distressed-cycle entries favor battery-electric platform specialists with validated lithium-ion supply agreements in Quebec and Bavaria. Long-term viability over the next decade hinges on carbon-accounting certification integration for sustainable construction procurement filters. Monitor EPA Phase 3 compliance deadline acceleration as the inflection signal for gasoline-powered manual unit obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform R&D Acceleration | Brushless DC drivetrains absorb 35-50 horsepower equivalent performance requirements previously met by gasoline engines. |
| ISO 19085 Safety Certification Pre-emption | Guard redesign validation compresses competitor time-to-market by 6-12 months in export-oriented segments. |
| Bi-metal Blade Foundry Integration | Captive supply of carbide-tipped edges insulates margins from high-carbon steel price volatility. |
| Direct-to-Operator Digital Channel Buildout | Configuration tools and video support reduce pre-purchase friction among farmstead operators aged 35-50. |
| Carbon-Accounting Certification Alignment | Documented low-emission equipment procurement preference filters into Austrian and German sustainable construction supply chains. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this portable sawmill market assessment. Primary interviews with equipment procurement managers at remote forestry camps, aftermarket service heads at Canadian manufacturers, plant engineers at Swedish steel suppliers, and channel sales directors at agricultural equipment distributors validated demand patterns. EPA Phase 3 implementation timelines, EU Machinery Directive conformity assessments, and ISO 19085 safety standard drafts supplemented bottom-up and top-down triangulation.
Granularity-level modeling captured product type differentiation across manual, hydraulic, and electric powertrain architectures alongside cutting width dimensions from 26-inch compact units through 72-inch industrial configurations. Application segmentation distinguished lumber production, woodworking, timber processing, and furniture manufacturing end uses. End-user archetypes separated contractor fleet operators, hobbyist landowners, and secondary wood products manufacturers. CAGRs derived from volume trajectory analysis across these intersecting dimensions, with steel price indices and lithium-ion cell cost curves as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA Phase 3 compliance deadline shifts and EU Green Deal carbon-accounting framework evolution. Forecasts reflect documented assumptions regarding battery-electric platform adoption rates and REACH substance restriction implementation timelines. Material deviation in steel price volatility or skilled technician workforce availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Dozer Blade Market
Construction Equipment
Crane Rail Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Autonomous Cranes Market
Construction Equipment
Jackhammer Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Global Excavator Attachments Market