
 Communication Platform-As-A-Service (Cpaas) Market | 2026-2036
Communication Platform-As-A-Service (Cpaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Communication Platform-As-A-Service (Cpaas) Market Intelligence
API-first communication architecture is rewriting how enterprises embed real-time engagement into customer workflows. Twilio Inc. leverages its developer ecosystem to dominate programmable messaging and voice infrastructure globally. Sinch AB anchors European enterprise demand through localized routing and operator partnerships. Infobip Ltd. competes in emerging markets with direct carrier integrations and regional data centers.
Communication Platform-as-a-Service denotes a cloud delivery model where programmable APIs enable voice, video, SMS, and authentication functions without on-premises telephony infrastructure. The stack typically operates over RESTful interfaces with sub-second latency SLAs, serving use cases from appointment reminders to two-factor verification and embedded video banking. Messaging and authentication services command disproportionate margin pools as regulatory compliance drives premium pricing for verified identity flows. Public cloud deployment retains volume leadership, though hybrid configurations are gaining traction among BFSI and healthcare end users with strict data residency requirements.
The FCC enforces STIR/SHAKEN caller ID authentication mandates in the United States, elevating demand for certified voice API providers. EMA and national health regulators across Europe require HIPAA-equivalent safeguards for clinical communications, filtering market access to platforms with ISO 27001 and GDPR-aligned certifications. Stakeholders must evaluate whether their CPaaS architecture can absorb emerging sovereign cloud requirements without fragmenting their API integration layer.
Market Dynamics
API abstraction layers are collapsing the distinction between telecom infrastructure and software development, forcing carriers to reprice wholesale voice and messaging as programmable commodities rather than regulated utilities.
Growth Catalysts
- STIR/SHAKEN Mandates:FCC caller ID authentication rules in the United States are compelling enterprises to migrate from unverified PSTN trunks to certified CPaaS voice stacks with attestation-grade provenance.
- Healthcare Workflows:HIPAA-equivalent clinical communication requirements across European national health regulators are filtering procurement toward platforms with ISO 27001 and GDPR-aligned certifications.
- Germany's Data Residency Concentration:Automotive and industrial buyers in Baden-Württemberg and Bavaria are mandating sovereign cloud voice orchestration, pulling vendor investment toward localized routing infrastructure.
Market Restraints
- Carrier Consolidation Risk:Wholesale SMS termination rates concentrate among tier-one mobile network operators in France and Spain, exposing API providers to asymmetric pricing power.
- Input Cost Volatility:Sub-second latency SLAs require premium colocation at internet exchange points, where rack space and cross-connect pricing fluctuates with data center construction cycles.
- Regulatory Fragmentation:Divergent national implementations of the EU AI Act create compliance multiplicity, forcing vendors to maintain parallel architecture stacks for member-state deployments.
Strategic Opportunities
- India's Underpenetrated Enterprise Segment:TRAI cloud telephony guidelines are unlocking programmable voice for mid-market manufacturers in Pune and Chennai industrial corridors.
- Converged Authentication:Biometric voiceprint verification layered over CPaaS voice APIs is creating premium pricing tiers for financial services onboarding workflows.
- Edge-Native Messaging:5G network slicing is enabling sub-50ms latency messaging for autonomous vehicle coordination, opening new procurement channels with automotive OEMs.
Industry Challenges
- Telecom Software Talent Scarcity:SIP protocol engineering and real-time media server optimization skills concentrate among legacy carrier workforces, constraining platform scaling velocity.
- Legacy PBX Integration Complexity:Hybrid cloud-on-premises voice architectures require maintaining parallel SS7 and WebRTC signaling paths, doubling operational overhead for healthcare and BFSI migrations.
- Certification Timeline Compression:ISO 27001 and SOC 2 Type II audit cycles extend 12-18 months, delaying market entry for new entrants targeting regulated European healthcare buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communication Platform-As-A-Service (Cpaas) Market |
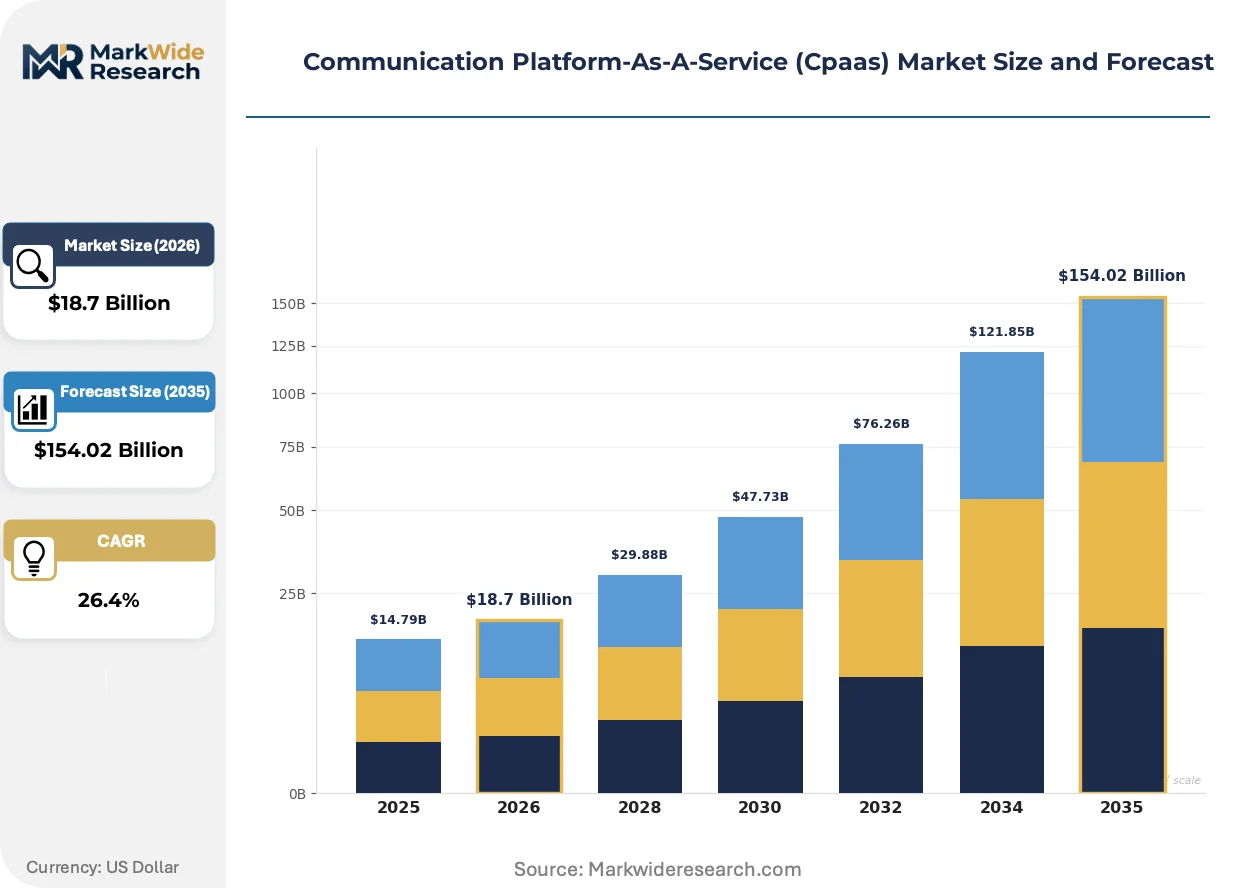
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $154.02 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice, Video, Messaging, Authentication Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: IT & Telecom, BFSI, Healthcare, Retail Customer Type: SMEs, Large Enterprises, Startups, Educational Institutions |
| Companies Covered | Twilio Inc., Vonage Holdings Corp., Sinch AB, Infobip Ltd., Bandwidth Inc., MessageBird BV, 8x8 Inc., Avaya LLC, Plivo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communication Platform-As-A-Service (Cpaas) Market Strategic Shifts & Innovations
Real-time communication infrastructure is shedding its hardware dependency as containerized media servers and serverless functions rewrite deployment economics. Three developments are compressing time-to-market for embedded voice and video capabilities.
WebRTC is virtualizing browser-native real-time media transport, eliminating plugin dependencies that previously gated video banking and telehealth adoption. European healthcare providers in the Netherlands and Sweden are deploying WebRTC-based patient portals at 3x the pace of native app alternatives. This virtualization is collapsing the distinction between communication infrastructure and application code, enabling product teams to ship video features without dedicated telecom engineering.
The EU AI Act's risk classification framework is redefining which AI-powered communication features require conformity assessment before deployment. High-risk applications including biometric voice authentication and emotion detection in customer service must undergo notified body review, extending commercialization timelines. German automotive call centers and French insurance providers are front-loading compliance investment to secure first-mover positioning in verified AI voice stacks.
Consumption-based pricing is displacing committed-use contracts as the dominant procurement model for mid-market enterprises. Buyers in Brazil and Mexico are negotiating per-message rates with volume floors rather than fixed monthly minimums, transferring demand volatility risk to platform providers. This shift is most visible among e-commerce marketplaces and on-demand logistics platforms where message volume correlates directly with transaction seasonality.
Communication Platform-As-A-Service (Cpaas) Market Segmentation
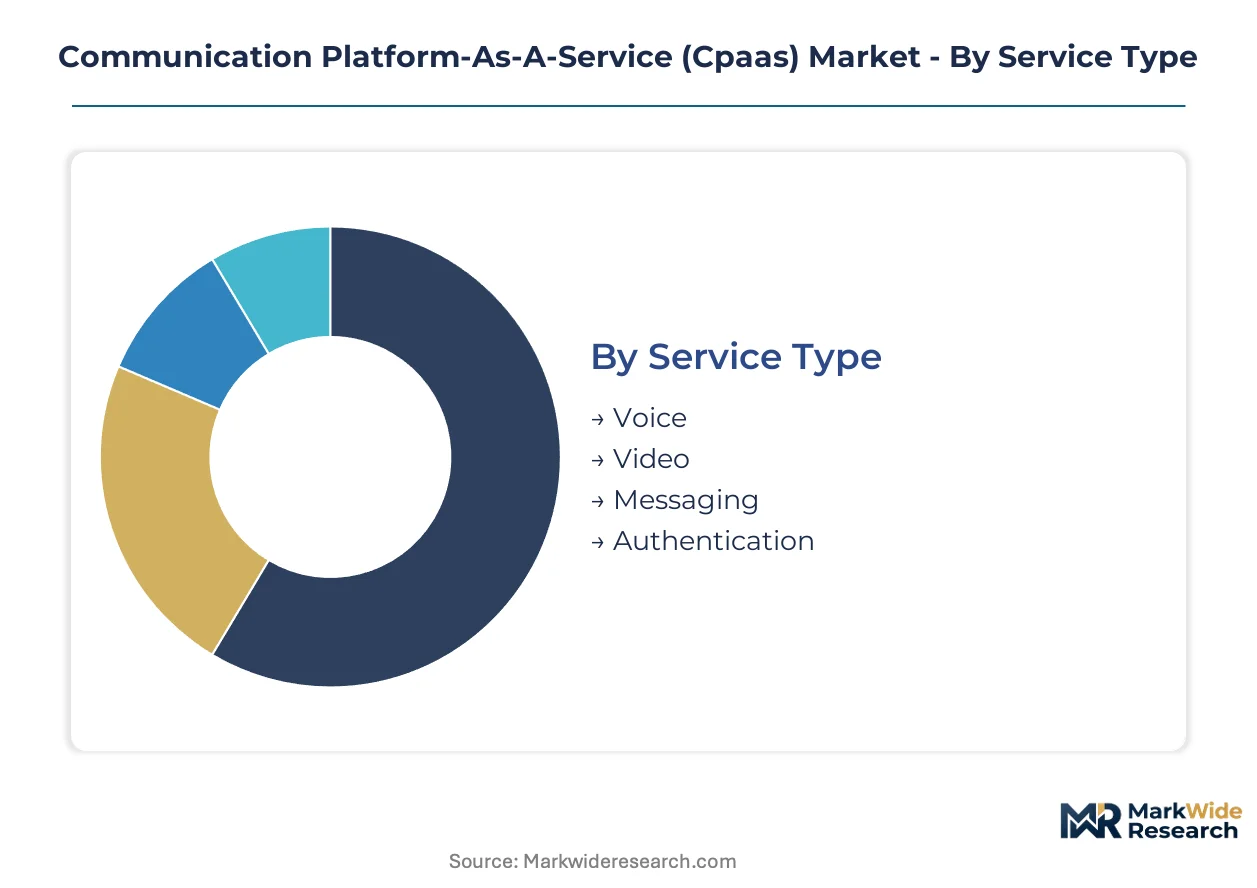
CPaaS procurement patterns diverge sharply across deployment sovereignty requirements and message volume economics. Service type selection maps directly to regulatory exposure, while customer scale determines API contract structures and latency SLA tiers.
Service Type:
Cost tier differentiation separates commodity messaging from premium authenticated flows with compliance overhead.
- Voice:Programmable PSTN termination and WebRTC browser calling enable embedded dialer functions without carrier infrastructure. German automotive call centers and French insurance providers are migrating to attestation-grade voice stacks under STIR/SHAKEN mandates and EU AI Act biometric authentication rules.
- Authentication:Two-factor SMS, voice OTP, and biometric voiceprint verification carry premium pricing due to ISO 27001 certification requirements and GDPR-aligned data handling. Healthcare providers in the Netherlands and Sweden filter procurement toward platforms with notified body review for high-risk AI voice classification.
- Video:WebRTC-based real-time media transport virtualizes browser-native video banking and telehealth without plugin dependencies.
- Messaging:Programmable SMS and rich communication services APIs handle appointment reminders and transactional notifications at volume-scaled per-message rates.
Authentication holds installed capacity. Voice is rotating up the share rankings.
Deployment Model:
Application criticality and data residency mandates determine cloud architecture selection across regulated industries.
- Public Cloud:Multi-tenant RESTful APIs with sub-second latency SLAs serve high-volume messaging without infrastructure ownership. Brazilian e-commerce marketplaces and Mexican on-demand logistics platforms negotiate consumption-based per-message rates with volume floors rather than fixed commitments.
- Hybrid Cloud:Split architectures route sensitive voice and authentication through sovereign infrastructure while burst traffic hits public endpoints. BFSI and healthcare end users in Germany's Baden-Württemberg and Bavaria industrial corridors mandate this configuration for GDPR compliance.
- Private Cloud:Single-tenant deployments with dedicated media servers and carrier interconnections address strict data localization requirements.
- On-Premises:Containerized media servers and SS7 signaling gateways maintain parallel legacy PBX integration for healthcare migrations with extended certification timelines.
Public Cloud maintains volume leadership. Hybrid Cloud is expanding most quickly among regulated European buyers.
End User:
Margin pools concentrate where compliance certification creates procurement barriers for uncertified platforms.
- Healthcare:HIPAA-equivalent clinical communication requirements across European national health regulators filter market access to ISO 27001 and GDPR-aligned platforms. Dutch and Swedish providers deploy WebRTC patient portals at accelerated pace versus native app alternatives.
- BFSI:Embedded video banking and biometric voiceprint verification for onboarding workflows command premium pricing tiers under EMA and national financial regulator oversight.
- IT & Telecom:Developer-centric API consumption drives programmable messaging volume with tiered pricing stratification across premium, standard, and economy certification grades.
- Retail:Seasonal transaction messaging correlates directly with e-commerce volume spikes, transferring demand volatility risk to platform providers under flexible rate structures.
Healthcare commands premium margin concentration. BFSI is climbing the fastest as video banking adoption accelerates.
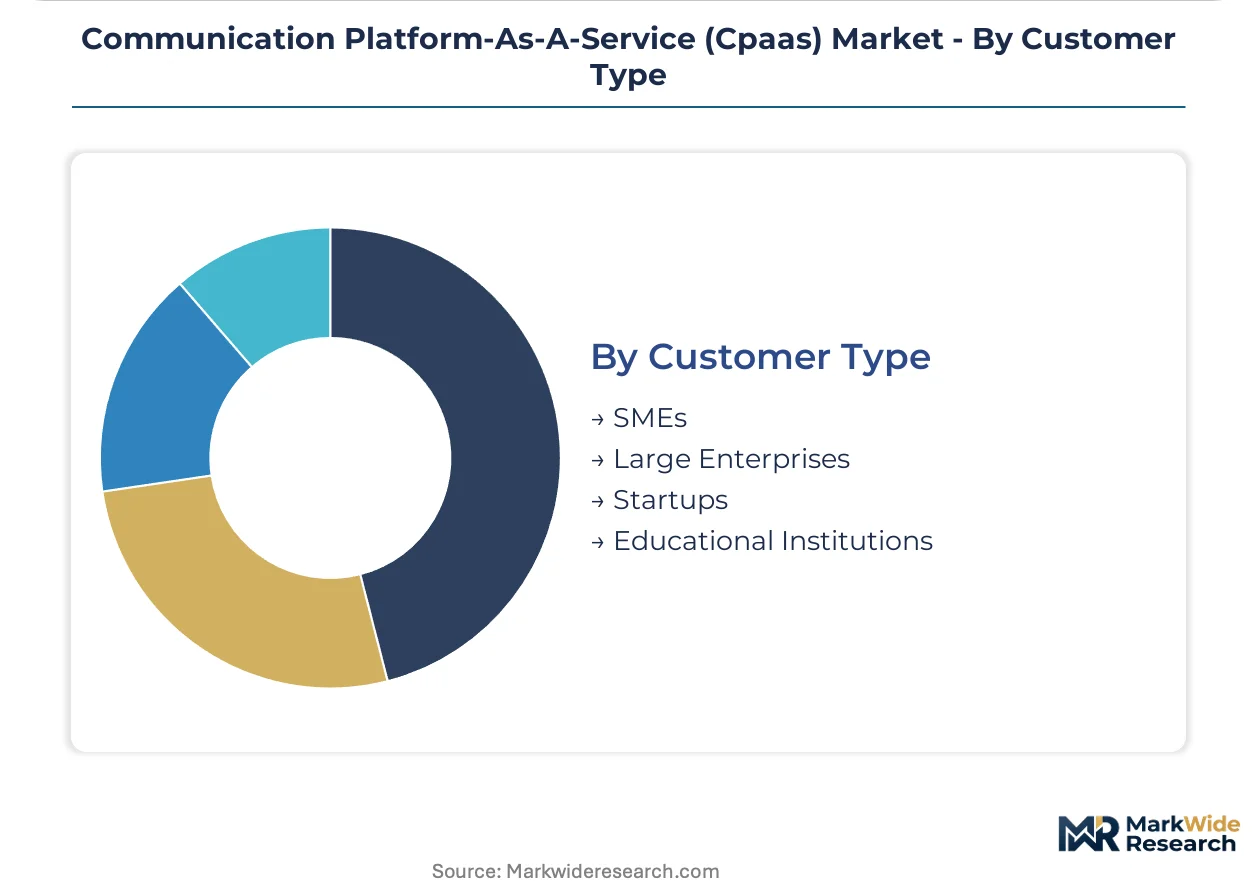
Customer Type:
Contract structure and API integration complexity scale inversely with customer technical maturity and message volume predictability.
- Large Enterprises:Committed-use contracts with dedicated technical account management and custom SLA negotiations support complex multi-region orchestration. Automotive OEMs in Germany require edge-native messaging with sub-50ms latency for autonomous vehicle coordination.
- SMEs:Self-service developer portals with consumption-based pricing and pre-built integrations enable rapid deployment without telecom engineering specialization. Mid-market manufacturers in India's Pune and Chennai industrial corridors access programmable voice under TRAI cloud telephony guidelines.
- Startups:Freemium tiering with volume-based graduation thresholds minimizes upfront commitment for pre-revenue ventures.
- Educational Institutions:Campus-wide emergency notification systems and virtual classroom APIs operate under procurement frameworks with extended security review cycles.
Large Enterprises anchor contract value. SMEs are gaining share fastest as self-service tooling matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany's industrial corridors anchor sovereign cloud voice procurement, while healthcare providers in the Netherlands and Sweden accelerate WebRTC patient portal deployment. Brazilian e-commerce marketplaces and Indian mid-market manufacturers represent emerging volume concentrations under flexible consumption frameworks.
United States
FCC STIR/SHAKEN mandates compel enterprises to abandon unverified PSTN trunks for attestation-grade CPaaS voice stacks. The regulatory framework elevates certified API providers above commodity carriers. Financial services call centers in Chicago and Charlotte are front-loading biometric voiceprint verification investment.
Germany
Automotive and industrial buyers in Baden-Württemberg and Bavaria mandate localized data residency for voice orchestration. The EU AI Act's high-risk classification for biometric authentication filters procurement toward notified body-reviewed platforms. Stuttgart-based OEMs require edge-native messaging with sub-50ms latency for autonomous vehicle coordination.
Netherlands
Healthcare providers deploy WebRTC-based patient portals at triple the pace of native app alternatives. GDPR-aligned clinical communication requirements filter market access to ISO 27001-certified platforms. Amsterdam and Rotterdam hospital networks drive concentrated demand for programmable video banking and telehealth APIs.
Brazil
E-commerce marketplaces negotiate consumption-based per-message rates with volume floors rather than fixed commitments. Seasonal transaction messaging correlates directly with volume spikes, transferring demand volatility risk to platform providers. São Paulo and Rio de Janeiro logistics platforms anchor flexible procurement frameworks.
India
TRAI cloud telephony guidelines unlock programmable voice for mid-market manufacturers in Pune and Chennai industrial corridors. Self-service developer portals enable rapid deployment without telecom engineering specialization. Bengaluru IT services clusters represent adjacent demand for embedded authentication workflows.
Communication Platform-As-A-Service (Cpaas) Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered certification grades. The vendor base organizes around three strategic archetypes: developer-centric API platforms, carrier-integrated regional specialists, and legacy telephony incumbents with cloud migration services. Dominant competitive moves include M&A to absorb carrier partnerships and geographic expansion through localized data center deployment.
Within the developer-centric tier, Twilio Inc. and Bandwidth Inc. exemplify API-first architectures that collapse telecom infrastructure into software consumption models. Sinch AB anchors European demand through operator partnerships and localized routing infrastructure. These three occupy positions across the premium-mid-economy pricing spectrum, with certification grade and latency SLA tiers determining contract value capture.
| Leading Market Players |
|---|
| Twilio Inc. |
| Vonage Holdings Corp. |
| Sinch AB |
| Infobip Ltd. |
| Bandwidth Inc. |
| MessageBird BV |
| 8x8 Inc. |
| Avaya LLC |
| Plivo Inc. |
| Others |
Cost & Logistics Intelligence
Frankfurt-London internet exchange corridors govern colocation pricing for sub-second latency SLAs, concentrating cost pressure where tier-one carriers negotiate asymmetric termination rates and downstream API providers stratify across certification-grade tiers.
Pricing Analysis
Cost-plus contracts indexed to IX port fees and carrier wholesale rates dominate enterprise voice procurement. Three-tier pricing structure across premium, standard, and economy levels separates attestation-grade STIR/SHAKEN stacks from commodity SMS termination. Pricing pressure stems from carrier consolidation in France and Spain, where tier-one MNOs extract premium SMS termination. Mid-market manufacturers in India's industrial corridors exhibit highest price sensitivity, while German automotive OEMs prioritize latency SLAs over unit economics.
Supply Chain Analysis
Contract manufacturing concentration rests with hyperscale cloud providers AWS, Microsoft Azure, and Google Cloud Platform for public cloud media server deployment, alongside regional data center operators in Germany and the Netherlands for sovereign cloud configurations. Taiwan and South Korea anchor semiconductor supply for edge-native messaging hardware. Silicon wafer and optical transceiver dependencies create single-source vulnerability through TSMC and Samsung foundry concentration. Distribution runs through direct carrier interconnections and API aggregator platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API abstraction is collapsing telecom infrastructure into software consumption, with EU AI Act biometric authentication mandates creating immediate compliance inflection for voice stack providers.
For Market Incumbents: Entrench through backward integration into carrier partnerships and ISO 27001 certification acceleration. Acquire regional data center capacity in Baden-Württemberg to defend against sovereign cloud challengers. Prioritize notified body review for high-risk AI voice classification before EU AI Act enforcement tightens procurement filters. For New Entrants and Emerging Players: Mid-market manufacturers in Pune and Chennai industrial corridors represent the most penetrable entry point under TRAI cloud telephony deregulation. Brazilian e-commerce marketplaces offer consumption-based pricing traction with volume-floor contracts. Lead with self-service developer portals and WebRTC-native architectures to bypass legacy PBX integration complexity. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy carrier cloud migration divisions with captive enterprise relationships and regional spectrum licenses. Position for 5-10 year infrastructure consolidation as programmable APIs displace on-premises telephony. Monitor TRAI guideline expansion and EU AI Act notified body designation timelines as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Partnership Acquisition | Secures asymmetric termination rate leverage against tier-one MNO concentration in France and Spain. |
| Sovereign Cloud Data Center Deployment | Captures German automotive and industrial demand under GDPR-aligned data residency mandates. |
| Notified Body Certification Investment | Unlocks high-risk AI voice authentication procurement under EU AI Act biometric classification rules. |
| WebRTC-Native Platform Development | Eliminates plugin dependencies driving Dutch and Swedish healthcare portal deployment acceleration. |
| Consumption-Based Pricing Model | Transfers demand volatility risk from Brazilian e-commerce seasonal spikes to platform balance sheets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with CPaaS platform engineers, carrier wholesale managers, enterprise IT procurement officers, and healthcare compliance leads. Secondary validation drew from FCC STIR/SHAKEN implementation reports, EMA clinical communication guidelines, TRAI cloud telephony circulars, and SEC filings of publicly traded API providers. Bottom-up message volume modeling and top-down infrastructure spend estimates were triangulated to anchor market sizing.
Calibration against historical API consumption patterns and carrier termination rate trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, deployment sovereignty tier, end-user vertical, and customer scale archetype. CAGRs derived from elasticity-adjusted adoption curves for WebRTC virtualization and biometric authentication penetration. Edge-native messaging latency requirements and EU AI Act compliance timelines served as CPaaS-specific forecast inputs.
Stress conditions across carrier consolidation velocity, data center construction cycles, and notified body certification backlogs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation timelines and enterprise cloud migration willingness. Quarterly review of FCC attestation mandate enforcement rates and EU AI Act high-risk classification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Fixed Business Voice Platforms and Services Market
Communication Services
Pcaas Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Managed Communication Services Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Postal Services Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Broadcasting Solutions Market
Communication Services
North America Postal Services Market
Communication Services
Global Critical Communication Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
Voice Commerce Market
Communication Services
Green Communication Market
Communication Services
Voip Services Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Video Managed Services Market