
 Video Managed Services Market | 2026-2036
Video Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
Video Managed Services Market Analysis
Enterprise streaming demand is consolidating around cloud-native platforms, pulling Video Managed Services away from legacy broadcast-centric models. Cisco Systems, Inc. anchors its position through infrastructure control across hybrid deployment environments. Amazon Web Services leverages hyperscale data center density to dominate encoding and delivery economics. Microsoft competes through tight integration between its communication suite and enterprise video workflows.
Video Managed Services encompass the outsourced design, operation, and optimization of video infrastructure spanning ingestion, transcoding, storage, distribution, and real-time analytics, typically delivered via SLA-governed contracts with 99.9% uptime commitments and sub-two-second latency thresholds for live applications. Content Delivery services capture the largest revenue pool due to bandwidth scaling requirements, while Cloud-Based deployment is displacing on-premises estates fastest among mid-market clients. Security Surveillance applications generate premium margins where AI-enhanced analytics integrate with physical access systems.
FCC regulations govern closed-captioning and emergency alert distribution for US broadcast streams, while GDPR and the EU AI Act constrain biometric video analytics deployment across European client sites. The US national security framework adds compliance layers for government agency contracts through FedRAMP and NIST controls. Stakeholders must monitor how fragmented sovereignty requirements across Germany, Japan, and India reshape multi-cloud architecture decisions.
Market Dynamics
Cloud-native video infrastructure is consolidating enterprise streaming demand, pulling service contracts away from broadcast-centric legacy estates toward API-driven platforms with sub-two-second latency SLAs. This structural migration reconfigures vendor economics around hyperscale data center density rather than hardware ownership.
Growth Catalysts
- AI-enhanced analytics integration:Security surveillance deployments now require computer vision overlays for physical access control, expanding premium-margin service tiers.
- FCC closed-captioning mandates:US broadcast compliance requirements drive recurring managed service contracts for live stream captioning and emergency alert distribution.
- Mid-market cloud displacement:On-premises video estates among mid-sized enterprises are migrating fastest to cloud-based deployment models.
Market Restraints
- GDPR biometric constraints:The EU AI Act and GDPR data localization rules create friction for facial recognition analytics deployment across European client sites.
- Bandwidth cost volatility:Content delivery services face margin pressure from peering agreement renegotiations and transit pricing swings.
- FedRAMP certification timelines:US government agency contracts require NIST control implementations that extend sales cycles by 12-18 months.
Strategic Opportunities
- India sovereignty requirements:Fragmented data localization mandates across Indian states are reshaping multi-cloud architecture decisions for service providers.
- Edge encoding convergence:5G network slicing combined with containerized encoding is opening low-latency live event workflows.
- Japan METI digital infrastructure incentives:Government subsidies for enterprise video modernization are accelerating replacement of legacy broadcast hardware.
Industry Challenges
- Live streaming engineer scarcity:Talent capable of architecting sub-two-second latency pipelines with redundant failover remains concentrated among hyperscale operators.
- Legacy codec integration:Enterprises maintaining MPEG-2 broadcast estates face complex migration paths to HEVC and AV1 transcoding stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Managed Services Market |
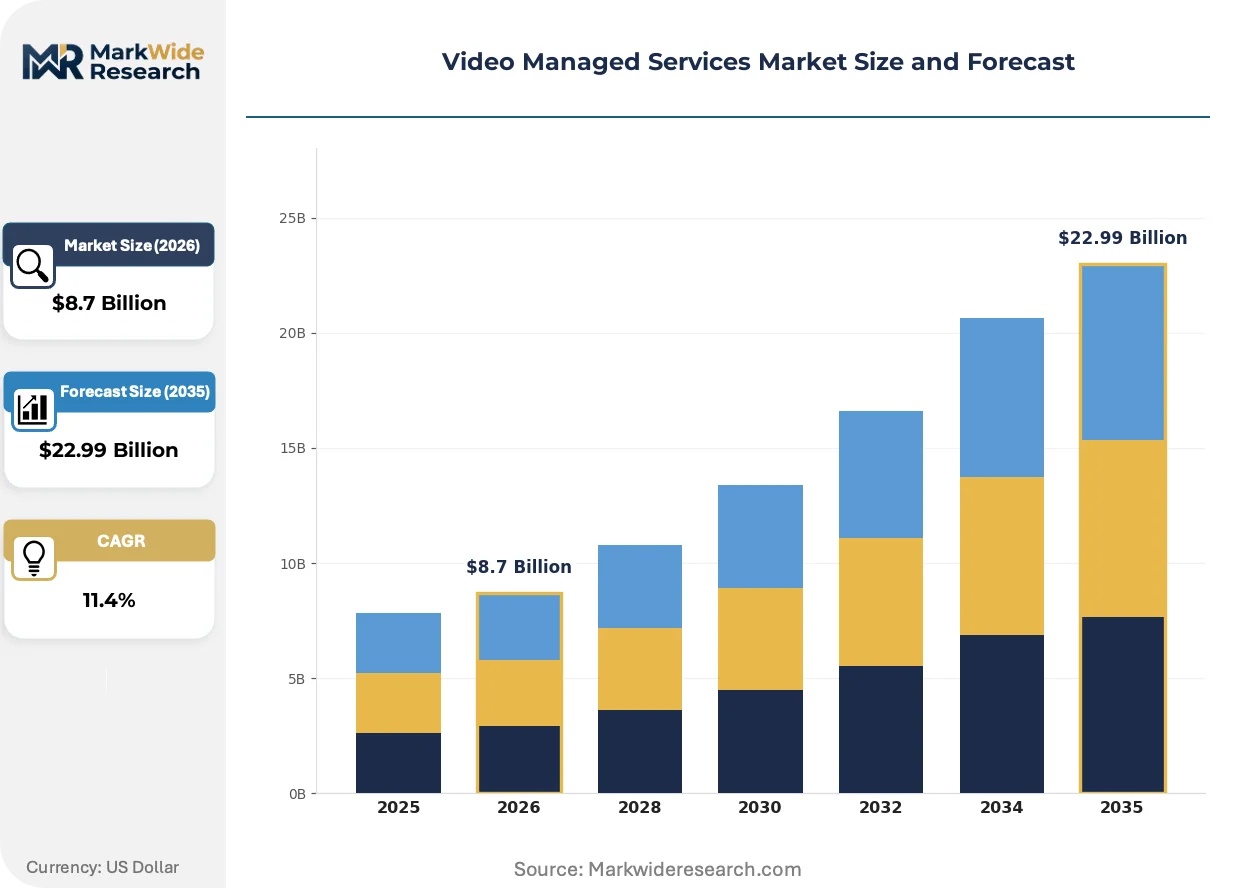
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Content Delivery, Content Management, Network Monitoring, Video Encoding Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Client Type: Enterprises, Media Companies, Educational Institutions, Government Agencies Application Area: Broadcasting, E-Learning, Corporate Communication, Security Surveillance |
| Companies Covered | Cisco Systems, Inc., Amazon Web Services, Microsoft, Google, IBM, AT&T Business, ZTE Enterprise, Applied Global Technologies, Akamai Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Managed Services Market Emerging Trajectories
Video service architectures are pivoting from hardware ownership to consumption-based API models, compressing traditional capex cycles into monthly operational commitments. This shift redefines competitive advantage around software velocity rather than equipment scale.
AV1 codec adoption is overtaking HEVC in live streaming workflows due to royalty-free licensing and superior compression efficiency. Mid-market broadcasters are deploying AV1 encoding pipelines to reduce bandwidth egress costs. This technology is overtaking legacy H.264 infrastructure in cost-sensitive verticals.
The EU AI Act classification rules for biometric identification systems are forcing service providers to segregate European video analytics workloads. High-risk AI system designations trigger conformity assessments that extend deployment timelines. Security surveillance vendors are responding by isolating EU data processing within regional cloud regions.
Consumption-based pricing for transcoding minutes is replacing perpetual license models among enterprise buyers. Procurement teams now benchmark vendors on marginal cost per stream-hour rather than upfront capacity. This behavioral shift is most visible in Germany, where mid-sized manufacturers are unbundling video infrastructure from IT managed services contracts.
Video Managed Services Market Segmentation
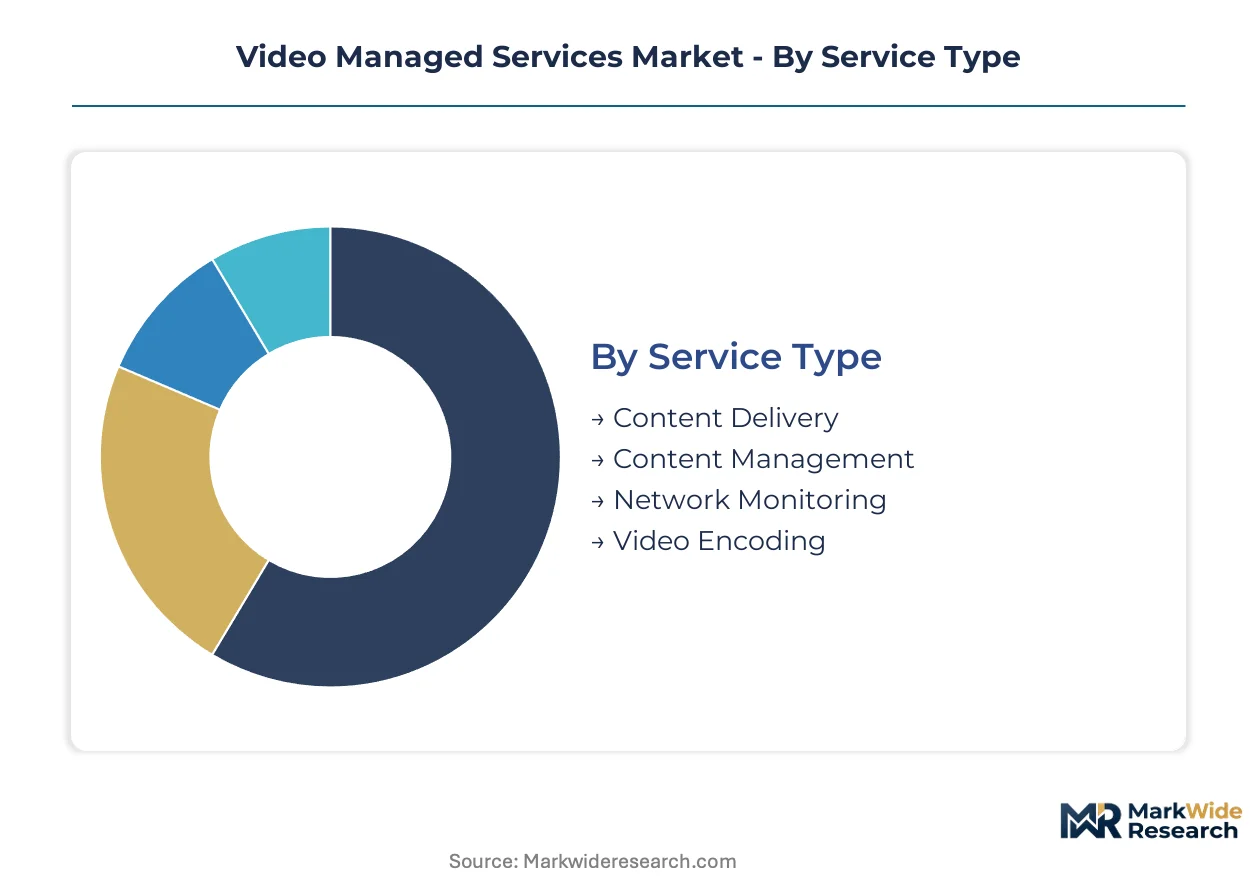
Video Managed Services vendors architect their portfolios around four distinct segmentation axes. Service type determines margin structure and renewal cadence. Deployment model governs infrastructure ownership economics. Client type shapes compliance requirements and sales cycle length. Application area dictates latency thresholds and analytics complexity.
Service Type:
Upgrade cycles vary dramatically across service tiers, with bandwidth-intensive offerings refreshing faster than configuration-heavy platforms.
- Content Delivery:CDN infrastructure handles edge caching and last-mile distribution for live and on-demand streams. Demand concentrates among US broadcasters and streaming platforms facing FCC closed-captioning mandates and emergency alert distribution requirements. Peering agreement renegotiations create margin volatility.
- Content Management:Metadata tagging, digital rights enforcement, and archive orchestration form the operational core. Media companies in Germany drive replacement of legacy broadcast asset management systems with API-driven cloud platforms. GDPR data localization rules constrain multi-tenant architectures.
- Network Monitoring:Real-time QoS dashboards track packet loss, jitter, and bandwidth utilization across distributed video pipelines.
- Video Encoding:Transcoding farms convert source feeds into adaptive bitrate ladders for heterogeneous device endpoints.
Content Delivery sits at the top of the volume ranking, with Content Management climbing the fastest.
Deployment Model:
Customer procurement patterns split sharply by organizational scale and regulatory exposure.
- Cloud-Based:Hyperscale data center density enables consumption-based pricing for transcoding minutes and storage. Mid-market enterprises across Japan are abandoning on-premises estates fastest, drawn by METI digital infrastructure subsidies and opex conversion benefits.
- Hybrid:Split architectures keep sensitive ingest on-premises while pushing distribution to cloud edge nodes. Financial services firms in the United States favor this model for FedRAMP compliance without sacrificing elastic burst capacity.
- On-Premises:Dedicated hardware estates persist where air-gapped security or legacy MPEG-2 integration requirements dominate.
- Multi-Cloud:Workload portability across AWS, Azure, and Google Cloud regions addresses sovereignty fragmentation.
Cloud-Based deployment commands the largest revenue pool, while Hybrid configurations gain share fastest among regulated verticals.
Client Type:
Contract structures and SLA terms diverge meaningfully across buyer categories.
- Enterprises:Corporate video platforms integrate with Microsoft Teams and Slack workflows for all-hands broadcasts and training distribution. German manufacturers are unbundling video infrastructure from broader IT managed services contracts, benchmarking vendors on marginal cost per stream-hour.
- Government Agencies:FedRAMP and NIST 800-53 controls extend sales cycles but lock in multi-year recurring revenue. US national security frameworks add compliance layers for closed-captioning and emergency alert systems.
- Media Companies:Broadcasters and streaming platforms require sub-two-second latency SLAs with redundant failover architectures.
- Educational Institutions:Campus-wide lecture capture and remote learning platforms drive seasonal demand spikes.
Enterprises generate the highest contract volume, with Government Agencies showing the steepest expansion trajectory as sovereign video infrastructure modernizes.
Application Area:
Latency requirements and AI integration depth create tiered margin profiles across use cases.
- Security Surveillance:Computer vision overlays for facial recognition and physical access control command premium service tiers. EU AI Act high-risk system designations force segregation of European biometric workloads, extending deployment timelines for conformity assessments.
- Broadcasting:Live event workflows demand containerized encoding with 5G network slicing for low-latency contribution. AV1 codec adoption is displacing HEVC among cost-sensitive verticals due to royalty-free licensing.
- E-Learning:Asynchronous video platforms prioritize storage economics over real-time performance.
- Corporate Communication:Internal streaming integrates with existing identity providers and calendar systems.
Security Surveillance delivers the highest margin profile, with Broadcasting expanding most quickly as legacy hardware replacement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping service provider footprints, with vendors routing video workloads through jurisdictions offering favorable compliance cost structures. The United States, Germany, and Japan anchor demand concentration, while India and Brazil emerge as contested expansion zones where data localization mandates create operational complexity.
United States
Enterprise streaming contracts from Fortune 500 corporations and federal agencies drive volume concentration. FCC closed-captioning mandates and FedRAMP certification requirements extend sales cycles but lock in multi-year recurring revenue. Dallas-Fort Worth and Northern Virginia host dense hyperscale data center clusters where AWS, Microsoft, and Google operate primary video encoding farms.
Germany
Mid-sized manufacturers are unbundling video infrastructure from IT managed services contracts, benchmarking vendors on marginal cost per stream-hour. GDPR data localization rules and EU AI Act biometric constraints force segregation of analytics workloads. Munich and Frankfurt anchor cloud region density, with Berlin emerging as a compliance engineering hub for pan-European deployments.
Japan
METI digital infrastructure subsidies accelerate replacement of legacy broadcast hardware among enterprise buyers. Sub-two-second latency requirements for live event streaming concentrate demand in Tokyo and Osaka metro areas. Kansai region broadcasters are deploying AV1 encoding pipelines to reduce bandwidth egress costs under cost-sensitive procurement mandates.
India
Fragmented data localization mandates across Maharashtra, Karnataka, and Telangana reshape multi-cloud architecture decisions for service providers. TRAI regulations on content delivery network interconnection create compliance friction. Mumbai and Bengaluru host primary video engineering talent pools, though live streaming engineer scarcity constrains pipeline architecture capacity.
Brazil
Enterprise video modernization lags North American and European adoption curves by 36-48 months, creating replacement demand backlog. ANATEL broadcasting regulations and emerging data protection frameworks add compliance layers. São Paulo anchors service provider operations, with Rio de Janeiro emerging as a secondary hub for Portuguese-language content delivery optimization.
Video Managed Services Market Vendor Landscape
Strategic partnerships dominate the current landscape as hyperscale cloud operators align with specialized video infrastructure vendors to capture enterprise migration budgets. The market structure consolidates around three tiers: hyperscale platforms with data center density advantages, network equipment incumbents with hybrid deployment expertise, and niche analytics specialists serving regulated verticals. Two archetypes define competitive positioning: infrastructure control players leveraging hardware-software integration, and API-native platforms optimizing for consumption-based pricing. M&A activity and geographic expansion represent the primary competitive vectors, with vendors acquiring regional compliance capabilities and edge encoding assets.
Within the hyperscale platform tier, Amazon Web Services and Microsoft exemplify divergent positioning strategies. AWS anchors its approach through data center density and encoding economics, while Microsoft competes through communication suite integration. Cisco Systems, Inc. occupies a distinct infrastructure control position, bridging on-premises estates and cloud-native deployments for hybrid-sensitive buyers. These three entities collectively represent the competitive archetypes—hyperscale density, platform integration, and hybrid infrastructure—that structure vendor selection criteria across enterprise procurement teams.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Amazon Web Services |
| Microsoft |
| IBM |
| AT&T Business |
| ZTE Enterprise |
| Applied Global Technologies |
| Akamai Technologies |
| Others |
Supply Flow & Price Mechanics
AV1 codec adoption simultaneously compresses transcoding cost economics and redistributes supplier leverage toward royalty-free encoding stack vendors, while hyperscale data center density in Northern Virginia and Tokyo reshapes regional pricing benchmarks for bandwidth-intensive delivery tiers.
Pricing Analysis
Distributor margins on legacy broadcast hardware contracts face compression as cloud-native API platforms displace perpetual license models. Consumption-based pricing for transcoding minutes dominates enterprise procurement, with marginal cost per stream-hour becoming the primary benchmark. Price differentiation stems from latency tier guarantees and FedRAMP certification overhead. Mid-market manufacturers in Germany exhibit highest price sensitivity, while government agencies tolerate premium pricing for compliance-assured SLAs.
Supply Chain Analysis
Cross-border bandwidth provisioning costs fluctuate with peering agreement renegotiations between Tier 1 network operators. Encoding hardware fabrication concentrates in Taiwan, South Korea, and the United States. Cloud region infrastructure draws from specialized server chassis, high-density storage arrays, and low-latency networking silicon. Single-source vulnerability exists in advanced GPU supply for AI-enhanced analytics workloads. Distribution runs through hyperscale operator direct sales channels and systems integrator partnerships for hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between GDPR-constrained European deployments and METI-subsidized Japanese modernization programs creates geographic cost differentials exceeding infrastructure efficiency gaps.
For Market Incumbents: Hedge against hyperscale encroachment by deepening hybrid deployment expertise and acquiring regional compliance engineering capabilities in Germany and India. FedRAMP certification timelines represent a defensive moat against cloud-native entrants lacking government sales infrastructure. Prioritize backward integration into edge encoding hardware to preserve margin on latency-critical live event workflows. For New Entrants and Emerging Players: Channel partners specializing in mid-market manufacturing verticals offer the most penetrable entry path. Brazil's 36-48 month adoption lag against North American curves creates replacement demand backlog with lower competitive density. Target ANATEL compliance engineering as a differentiated service wrapper for Portuguese-language content delivery optimization. For Investors and Strategic Acquirers: Valuations sit cheapest among niche analytics specialists serving security surveillance verticals with EU AI Act segregation capabilities. Long-term viability hinges on software velocity rather than equipment scale across the projection horizon. Monitor AV1 encoding pipeline deployment rates as an inflection indicator for legacy HEVC infrastructure obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Encoding Hardware Acquisition | Captures margin on sub-two-second latency SLAs for live event broadcasters. |
| Regional Compliance Engineering Buildout | Addresses GDPR biometric constraints and EU AI Act conformity assessment requirements. |
| AV1 Transcoding Pipeline Deployment | Reduces bandwidth egress costs for cost-sensitive Kansai region broadcasters. |
| Strategic Partnership with Hyperscale Cloud Operator | Combines data center density advantages with specialized video workflow expertise. |
| Multi-Cloud Architecture Certification | Enables workload portability across fragmented Indian state-level data localization mandates. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and Brazil, with primary inputs from each market. The approach combines structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners alongside secondary validation through SEC filings, hyperscaler capex disclosures, and TRAI regulatory records. Bottom-up service provider revenue aggregation and top-down enterprise IT spending allocation were triangulated to establish market sizing.
Granularity extends to deployment model, organization size, vertical industry, and regional regulatory cluster. The analytical framework models volume and value outputs across the projection horizon, with CAGRs derived from historical trajectory analysis and forward-looking adoption curve assumptions. Forecast inputs include METI subsidy disbursement rates, FedRAMP certification pipeline velocity, and AV1 codec deployment tracking.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bandwidth cost volatility, EU AI Act enforcement interpretation, and live streaming engineering talent scarcity. Forecasts reflect documented assumptions regarding cloud displacement velocity and regulatory implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Audio Conferencing Services Market
Communication Services
Web Conferencing Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Pcaas Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Outbound Telemarketing Market
Communication Services
India Communication Platform As a Service (Cpaas) Market
Communication Services
Speech to Speech Translation Market
Communication Services
Meeting Solutions Market
Communication Services
Managed Communication Services Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Latin America Postal Service Market
Communication Services
Green Communication Market
Communication Services
Fixed Business Voice Platforms and Services Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Asia-Pacific Postal Services Market