
 Voice Commerce Market | 2026-2036
Voice Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Commerce Market Insights
China's manufacturing corridor for smart speaker components is reconfiguring supply dynamics for voice-enabled hardware worldwide. Amazon.com Inc. leverages its Alexa ecosystem to dominate in-home commerce activation, while Google LLC anchors its position through Android voice integration across mobile search and payment flows. Apple Inc. differentiates via on-device speech processing that limits data exposure, appealing to privacy-sensitive consumer segments in premium markets.
Voice commerce denotes the execution of commercial transactions through spoken natural language interfaces, relying on automatic speech recognition, natural language understanding, and secure payment tokenization operating beneath 500-millisecond response thresholds. Its primary commercial purpose is to eliminate tactile and visual friction from purchasing workflows, converting intent into transaction through conversational interaction. Smart speakers and mobile devices represent the most mature deployment vectors, with cloud-based architectures capturing the dominant margin pool due to recurring platform fees and data monetization potential. Edge computing deployments are gaining structural traction among enterprises seeking sub-100-millisecond latency for high-frequency retail environments.
The Federal Trade Commission scrutinizes voice data collection practices, while the EU AI Act imposes transparency obligations on automated decision systems that process consumer payment authorizations. China's SAMR enforces algorithmic recommendation regulations that affect voice-driven product curation and pricing personalization. Stakeholders must monitor diverging jurisdictional standards for biometric voiceprint storage, as fragmentation between GDPR-derived consent frameworks and sector-specific US state laws will determine which platform architectures achieve cross-border scalability.
Market Dynamics
Latency compression below 300 milliseconds is collapsing the friction barrier that historically prevented voice interfaces from handling high-velocity retail transactions, forcing platform providers to re-architect cloud-to-edge processing pipelines.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision systems for payment authorization now face disclosure requirements, pushing voice commerce platforms toward explainable NLP architectures that build consumer trust.
- Edge computing migration:Retail chains deploy on-premise speech processing to achieve sub-100-millisecond response times for in-store voice checkout, reducing cloud dependency for transaction-critical workloads.
- Smart speaker component manufacturing:China's electronics corridor supplies cost-optimized microphone arrays and neural processing units, enabling hardware price points that accelerate mass-market penetration.
Market Restraints
- Biometric voiceprint storage fragmentation:Divergent consent frameworks between GDPR-derived EU standards and US state-level privacy laws create architectural incompatibility for cross-border platform scaling.
- Natural language training data concentration:High-quality multilingual speech corpora remain concentrated among a handful of cloud providers, limiting competitive entry for specialized voice commerce vendors.
- Payment tokenization certification timelines:PCI DSS compliance for voice-initiated transactions extends deployment cycles by 8-14 months versus traditional card-present systems.
Strategic Opportunities
- India's digital payment infrastructure:UPI integration with regional language voice interfaces opens transaction volume in a market with 400 million feature phone users transitioning to smartphones.
- Automotive voice commerce:In-vehicle purchasing for fuel, parking, and drive-through food represents an untapped channel as connected car penetration accelerates.
- On-device speech processing convergence:Neural engine maturation in mobile chipsets enables privacy-preserving transactions that bypass cloud latency entirely.
Industry Challenges
- Conversational AI talent scarcity:Shortage of engineers with production-grade NLU optimization skills drives compensation inflation and project delays.
- Legacy POS integration complexity:Voice checkout systems require middleware development for 15-20 year-old retail terminal infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Commerce Market |
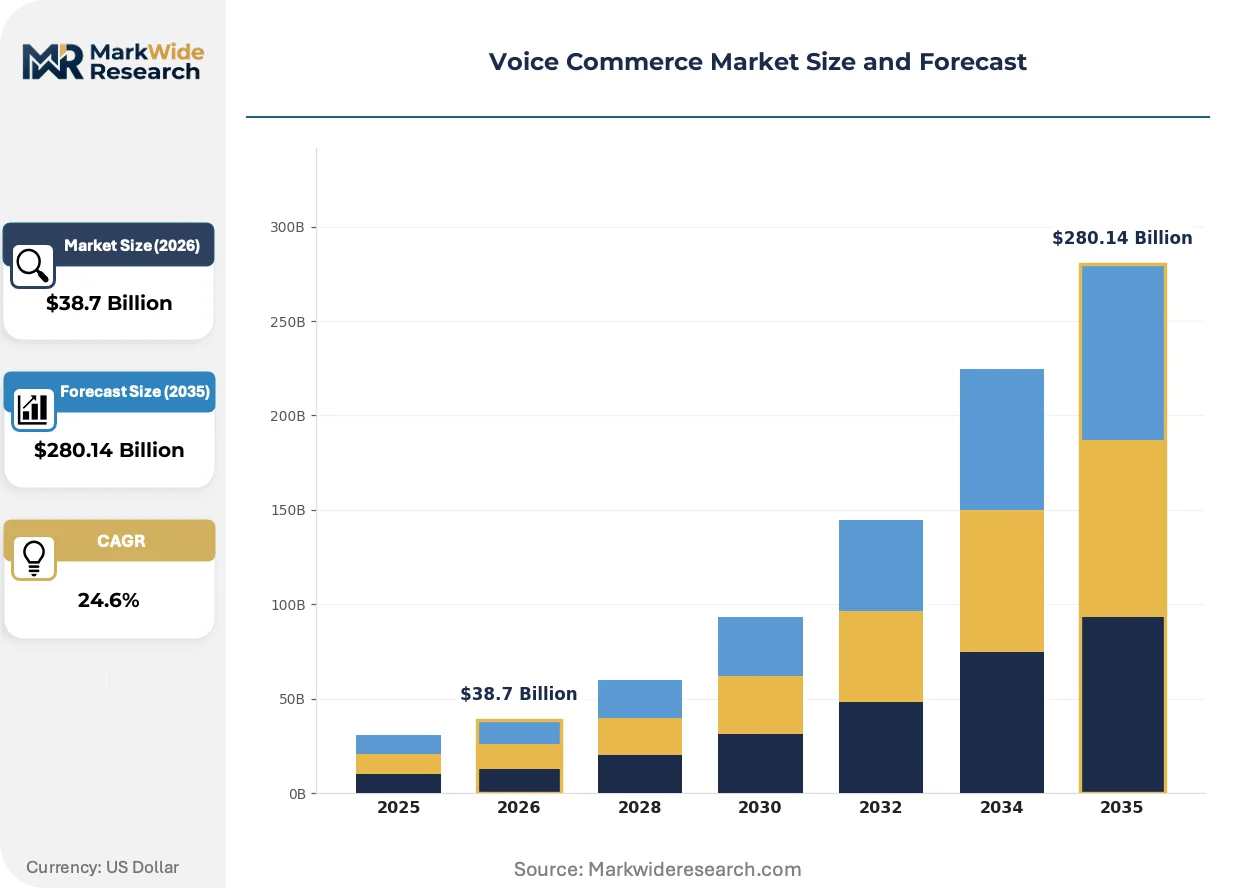
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Voice Assistants, Mobile Devices, Wearables Application: Retail, Banking, Travel, Entertainment End User: Consumers, Businesses, Service Providers, OEMs Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Amazon.com Inc., Google LLC, Apple Inc., Adobe Inc., Alibaba Group Holding Ltd., Baidu Inc., Samsung Electronics Co. Ltd., Salesforce Inc., SoundHound AI Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Commerce Market Trends and Innovations
Speech recognition latency is collapsing the final technical barrier to conversational commerce viability, while regulatory frameworks for biometric data and automated decision-making reshape platform architecture requirements across major economies.
Edge-deployed neural speech models are collapsing cloud dependency for transaction-critical voice processing. Grocery and quick-service restaurant chains pilot on-device NLU to eliminate network-induced latency spikes during peak hours. This migration compresses infrastructure costs while satisfying GDPR data-localization requirements for European deployments.
China's SAMR algorithmic recommendation regulations now extend to voice-driven product curation, mandating audit trails for pricing personalization. Platforms serving Chinese consumers must architect explainable ranking systems that disclose why specific products surface in voice search results. Compliance investments are diverting engineering resources from feature development.
Subscription fatigue among digital consumers is accelerating preference for transactional voice interfaces that bypass app download friction. Quick-service restaurants report voice channel capture rates 40% above mobile web for repeat purchase scenarios. This behavioral shift concentrates platform investment toward friction-minimizing checkout flows rather than feature-rich companion applications.
Voice Commerce Market Segmentation
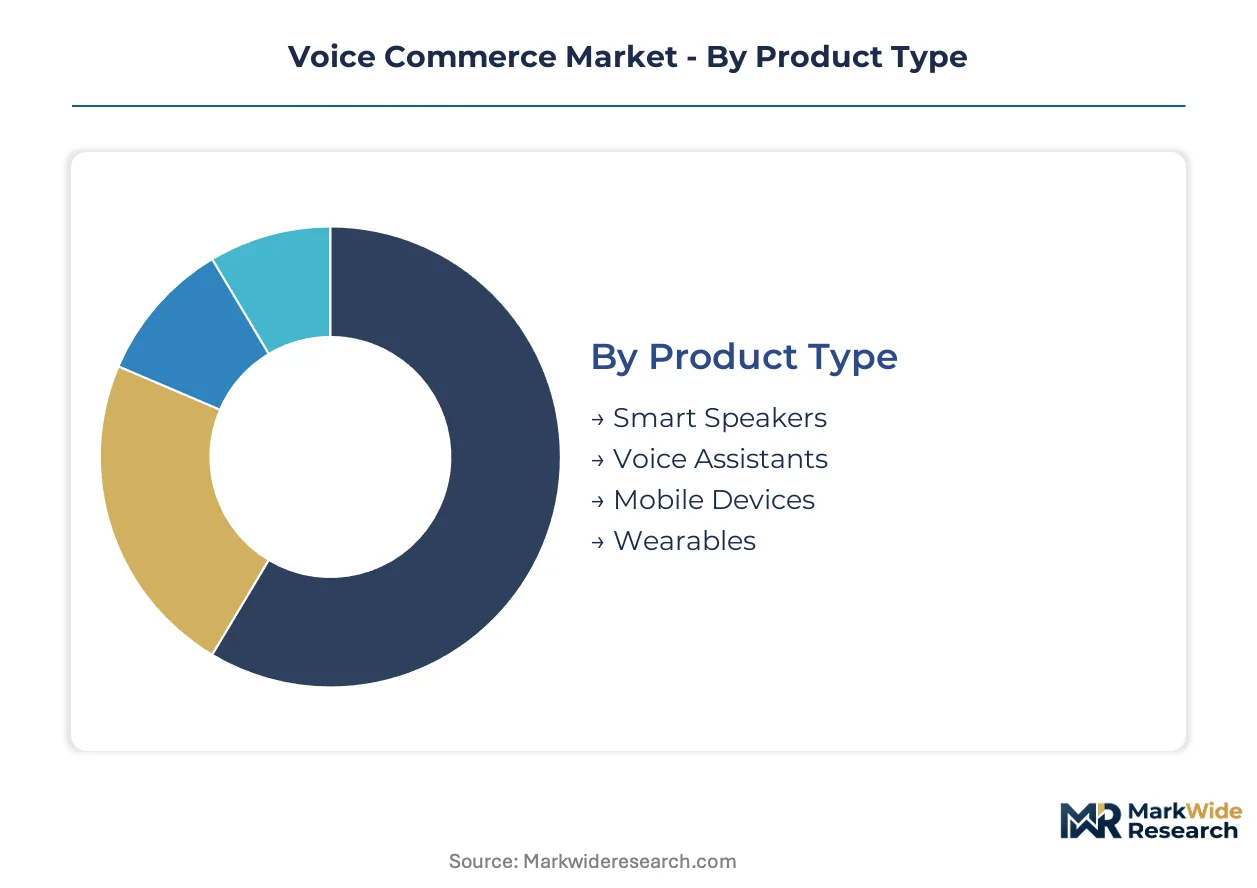
Voice commerce segmentation reveals distinct service intensity profiles across hardware, software, and infrastructure layers. Each category demands specialized technical support, from smart speaker firmware updates to edge deployment maintenance contracts.
Product Type:
After-sales service intensity varies dramatically across voice-enabled hardware categories, with enterprise deployments requiring multi-year technical support agreements.
- Smart Speakers:Fixed-location devices with microphone arrays and neural processing units for far-field speech recognition. Demand concentrates in United States households with Amazon Alexa and Google Assistant ecosystems, driven by friction reduction in repeat purchasing workflows. OEMs monetize through platform fees and voice skill developer revenue shares.
- Voice Assistants:Software layers processing natural language understanding and intent classification beneath 300-millisecond latency thresholds. Banking and quick-service restaurant chains in Germany and France deploy white-label assistants to maintain brand control while outsourcing speech recognition infrastructure.
- Mobile Devices:Smartphones with on-device neural engines enabling offline speech processing. Privacy-sensitive consumer segments in Switzerland and Japan favor Apple Siri's local execution that limits cloud data exposure.
- Wearables:Smartwatches and hearables with constrained battery budgets requiring ultra-low-power speech coprocessors. Fitness and wellness applications in South Korea drive specialized form factors with health-monitoring integration.
Smart Speakers holds the largest share; momentum sits with Voice Assistants as enterprise white-label deployments accelerate.
Application:
Cost tier differentiation separates high-frequency transactional applications from subscription-heavy entertainment use cases.
- Retail:Grocery and quick-service restaurant voice checkout systems eliminating tactile friction from omnichannel purchasing. United States chains deploy edge computing for sub-100-millisecond response times during peak traffic hours.
- Banking:Voice-authenticated balance inquiries and payment initiations requiring PCI DSS compliance extending deployment cycles. India's UPI integration with regional language interfaces opens transaction volume among feature phone transitions.
- Travel:Flight booking and hotel reservation workflows leveraging conversational interfaces for complex multi-parameter searches. European carriers face EU AI Act transparency mandates for automated pricing decisions.
- Entertainment:Media streaming control and ticket purchasing with lower authentication requirements than financial applications. Subscription fatigue accelerates preference for transactional voice interfaces bypassing app download friction.
Retail commands premium pricing for latency-critical infrastructure; Travel climbs the fastest as post-pandemic booking volumes recover.
End User:
Customer type determines procurement complexity, with enterprise buyers negotiating multi-year platform agreements and consumers activating pre-installed device capabilities.
- Consumers:Individual purchasers activating voice commerce through existing smart speaker and smartphone ecosystems. Privacy regulations in California and Illinois create compliance fragmentation for biometric voiceprint storage.
- Businesses:Corporate procurement of voice-enabled checkout and inventory management systems requiring custom integration with legacy POS infrastructure. Quick-service restaurant chains report voice channel capture rates substantially above mobile web for repeat scenarios.
- Service Providers:Telecommunications and financial institutions white-labeling voice commerce platforms for subscriber retention. China's SAMR algorithmic recommendation regulations mandate audit trails for pricing personalization affecting product curation.
- OEMs:Automotive and appliance manufacturers embedding voice commerce capabilities into connected products. In-vehicle purchasing for fuel and parking represents an untapped channel as connected car penetration accelerates.
Consumers generate the highest transaction volumes; Businesses drive the steepest expansion trajectory through enterprise deployment cycles.
Deployment:
Supply concentration in cloud infrastructure contrasts with emerging edge computing migration among latency-sensitive retail operators.
- Cloud-Based:Centralized speech processing capturing dominant margin pools through recurring platform fees and data monetization. Natural language training data concentration among major cloud providers limits competitive entry for specialized vendors.
- On-Premises:Enterprise-owned infrastructure for highly regulated financial and healthcare voice applications requiring data sovereignty. GDPR data-localization requirements in Germany and France drive European adoption.
- Hybrid:Architectures routing simple queries to cloud while reserving sensitive transactions for local processing. Balances latency optimization with compliance flexibility across jurisdictional boundaries.
- Edge Computing:On-premise neural speech models eliminating network-induced latency spikes during peak retail hours. Grocery chains pilot sub-100-millisecond response times while compressing infrastructure costs.
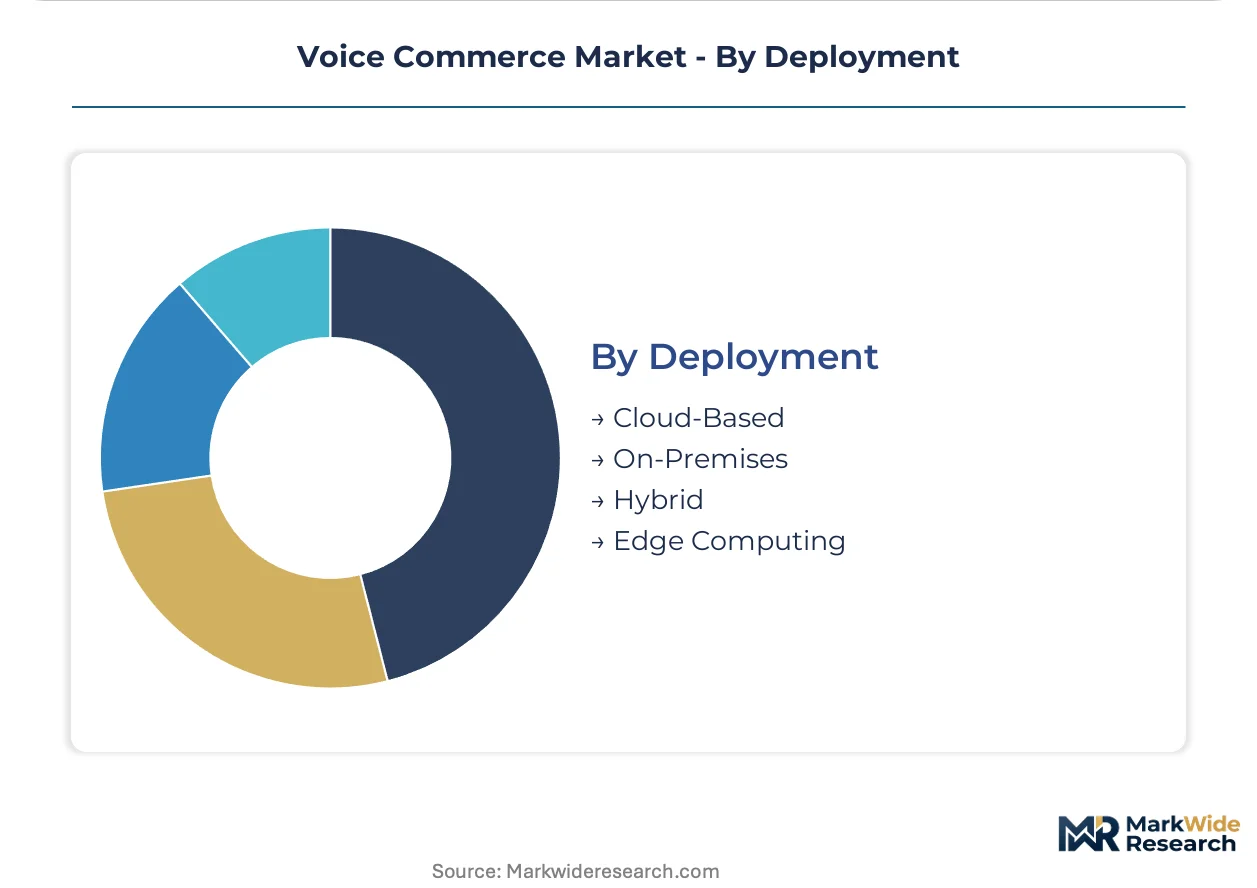
Cloud-Based retains the largest installed base; Edge Computing gains share fastest as neural engine maturation enables privacy-preserving local execution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households activate voice commerce through smart speaker ecosystems at substantially higher frequency than Japanese or German consumers, who favor mobile-first voice interfaces with stricter data localization requirements.
United States
Amazon Alexa and Google Assistant ecosystems command the largest installed smart speaker bases, driving friction reduction in repeat grocery and quick-service restaurant purchases. The FTC scrutinizes voice data collection practices under Section 5 of the FTC Act. Seattle and San Francisco anchor cloud-to-edge processing pipeline development for sub-300-millisecond latency targets.
China
Smart speaker component manufacturing concentrates in Shenzhen and Dongguan, supplying cost-optimized microphone arrays and neural processing units worldwide. SAMR enforces algorithmic recommendation regulations affecting voice-driven product curation and pricing personalization. The Yangtze River Delta corridor reconfigures supply dynamics for voice-enabled hardware exports.
Germany
Banking and quick-service restaurant chains deploy white-label voice assistants to maintain brand control while outsourcing speech recognition infrastructure. GDPR-derived consent frameworks impose strict biometric voiceprint storage requirements. Berlin and Munich host edge computing pilots achieving sub-100-millisecond response times for in-store voice checkout systems.
India
UPI integration with regional language voice interfaces opens transaction volume among 400 million feature phone users transitioning to smartphones. RBI oversees payment tokenization certification for voice-initiated transactions. Bangalore and Hyderabad drive multilingual natural language understanding development for Indic language speech corpora.
United Kingdom
Retail chains pilot hybrid cloud-edge architectures routing simple queries to cloud while reserving sensitive transactions for local processing. The UK Information Commissioner's Office enforces GDPR-aligned transparency obligations on automated decision systems. London anchors fintech voice authentication development for balance inquiries and payment initiations.
Voice Commerce Market Competitive Landscape
Capability concentration sits with cloud-scale platform providers; scale advantage sits with consumer electronics OEMs embedding pre-installed voice interfaces. The market structures around three tiers: ecosystem orchestrators commanding platform fees and data monetization, white-label specialists serving enterprise brand-control requirements, and component suppliers capturing hardware margins. Dominant competitive moves include strategic partnerships between cloud providers and retail chains for checkout system integration, plus geographic expansion through regional language model localization.
Within the ecosystem orchestrator tier, Amazon.com Inc. and Google LLC occupy positions defined by smart speaker installed base and mobile voice integration reach. Apple Inc. exemplifies the privacy-differentiated archetype through on-device speech processing that limits cloud data exposure. Among China-based platform providers, Alibaba Group Holding Ltd. and Baidu Inc. represent the regional ecosystem alternative, anchoring voice commerce activation within domestic smart speaker and mobile payment infrastructures.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| Google LLC |
| Apple Inc. |
| Adobe Inc. |
| Alibaba Group Holding Ltd. |
| Baidu Inc. |
| Samsung Electronics Co. Ltd. |
| Salesforce Inc. |
| SoundHound AI Inc. |
| Others |
Pricing and Supply Chain Analysis
China's Shenzhen-Dongguan electronics corridor concentrates smart speaker component manufacturing, anchoring hardware cost structures that determine where platform providers capture recurring software margin pools.
Pricing Analysis
Long-term platform licensing contracts dominate enterprise voice assistant deployments, while transactional per-query pricing governs cloud-based speech processing. Three-tier pricing structure across premium latency-grade, standard cloud, and economy batch-processing levels separates banking clients from quick-service restaurant chains. Cost compression in standard-tier cloud services intensifies as neural engine maturation enables edge alternatives. Quick-service restaurant chains exhibit highest price sensitivity due to thin transaction margins, while financial institutions prioritize sub-100-millisecond certification tiers regardless of premium.
Supply Chain Analysis
US export-control restrictions on advanced neural processing units limit flows to Chinese smart speaker OEMs, fragmenting hardware sourcing strategies. Taiwan, South Korea, and Japan anchor semiconductor fabrication for speech-optimized silicon. China's rare earth processing and Vietnam's final assembly feed microphone array production. Single-source vulnerability concentrates in TSMC's advanced node capacity for edge-computing chipsets. Distribution runs through cloud provider marketplaces and direct enterprise procurement channels rather than traditional hardware distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
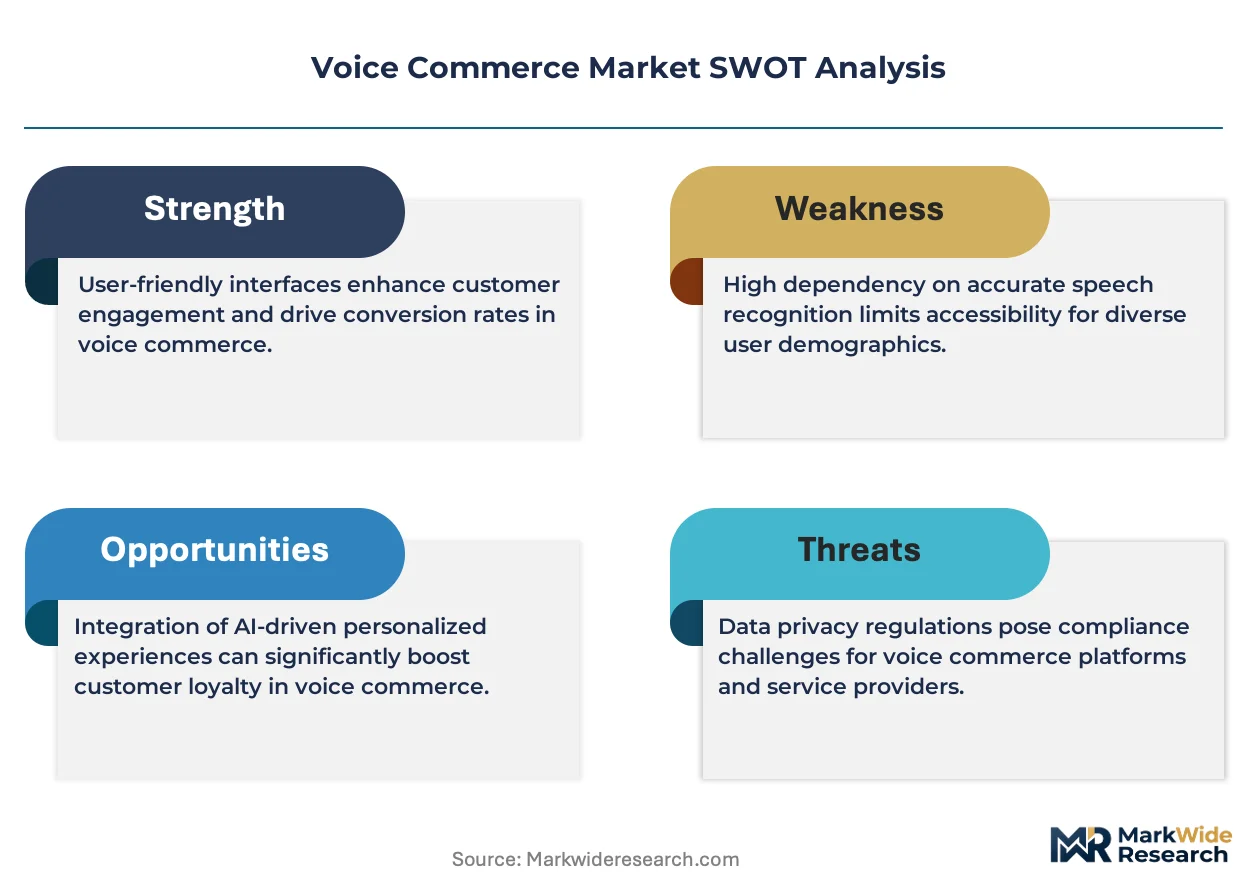
Voice commerce is approaching a platform-economics inflection where Alexa and Google Assistant interoperability decisions will determine which third-party developers capture transaction flow.
For Market Incumbents: Insulate platform fee structures by deepening backward integration into edge-computing silicon design, reducing dependency on TSMC allocation cycles. Secure PCI DSS certification moats before payment tokenization timelines extend competitive gaps. Threat substitution from on-device Apple Siri transactions demands preemptive latency investment in sub-100-millisecond architectures. For New Entrants and Emerging Players: Establish a beachhead in India's UPI-integrated regional language voice interfaces, where 400 million feature phone transitions create whitespace unclaimed by Alexa and Google Assistant. Target automotive OEM voice commerce pilots for fuel and parking as connected car penetration accelerates. Go-to-market through white-label partnerships with quick-service restaurant chains seeking brand-controlled checkout experiences. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed voice analytics specialists possessing production-grade NLU optimization talent scarce in labor markets. Five-to-ten year viability hinges on regulatory navigation capabilities across GDPR-derived consent frameworks and EU AI Act transparency mandates. Watch for SAMR algorithmic recommendation enforcement patterns as signal for Chinese market re-entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Migration | Grocery chains achieve sub-100-millisecond response times while satisfying GDPR data-localization requirements in Germany and France. |
| Regional Language Localization | UPI integration with Indic speech corpora captures transaction volume among India's 400 million feature phone transitions. |
| On-Device Neural Engine Development | Apple's local execution architecture limits cloud data exposure for privacy-sensitive consumer segments in Switzerland and Japan. |
| White-Label Enterprise Deployment | Banking chains in Germany and France maintain brand control while outsourcing speech recognition infrastructure to specialized vendors. |
| Automotive Voice Commerce Integration | In-vehicle purchasing for fuel and parking taps untapped channels as connected car penetration accelerates across OEM platforms. |
Research Methodology
Desk research of SEC filings from Amazon and Google, EU AI Act regulatory texts, and SAMR algorithmic recommendation guidelines preceded structured interviews with voice platform engineering directors, quick-service restaurant chain CTOs, and payment tokenization compliance officers. Primary fieldwork with smart speaker OEM procurement teams and cloud provider solution architects validated hardware cost assumptions. Bottom-up transaction volume estimates triangulated against top-down platform revenue disclosures.
Assumptions held fixed include latency compression trajectories below 300 milliseconds and smart speaker installed base growth curves, while regulatory enforcement intensity and edge-computing adoption rates varied across sensitivity scenarios. Segmentation modeling spanned deployment architecture, application vertical, and regional regulatory cluster dimensions. CAGRs derived from S-curve penetration modeling against historical mobile payment adoption patterns. Key inputs included PCI DSS certification timeline data and multilingual speech corpus availability indices.
Sensitivities concentrate around FTC enforcement actions on voice data collection and EU AI Act transparency mandate implementation timelines. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in biometric voiceprint storage jurisprudence or TSMC capacity allocation for neural processing units would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Message Handling Systems Market
Communication Services
Voip Services Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Mobile Messaging Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Web Conferencing Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Latin America Postal Service Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Broadcasting Solutions Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Video Managed Services Market
Communication Services
Meeting Solutions Market
Communication Services
Green Communication Market
Communication Services
Dispatch Console Market