
 Cloud Communication Platform Software Market | 2026-2036
Cloud Communication Platform Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Communication Platform Software Market Outlook
Enterprise-grade SLA reliability is unwinding legacy on-premises telephony migrations across Fortune 500 accounts. RingCentral leverages its channel partner density to sustain North American enterprise penetration. Dialpad anchors its position through native AI transcription specialization.
Cloud communication platform software delivers real-time voice, video, and messaging services over IP infrastructure with sub-150ms latency thresholds, replacing circuit-switched PBX systems for distributed workforce coordination. Unified Communications and Contact Center solutions capture the deepest margin pools as enterprises consolidate vendor relationships. Video Conferencing growth decelerates toward commoditization while AI-powered APIs command premium pricing for embedded communication workflows.
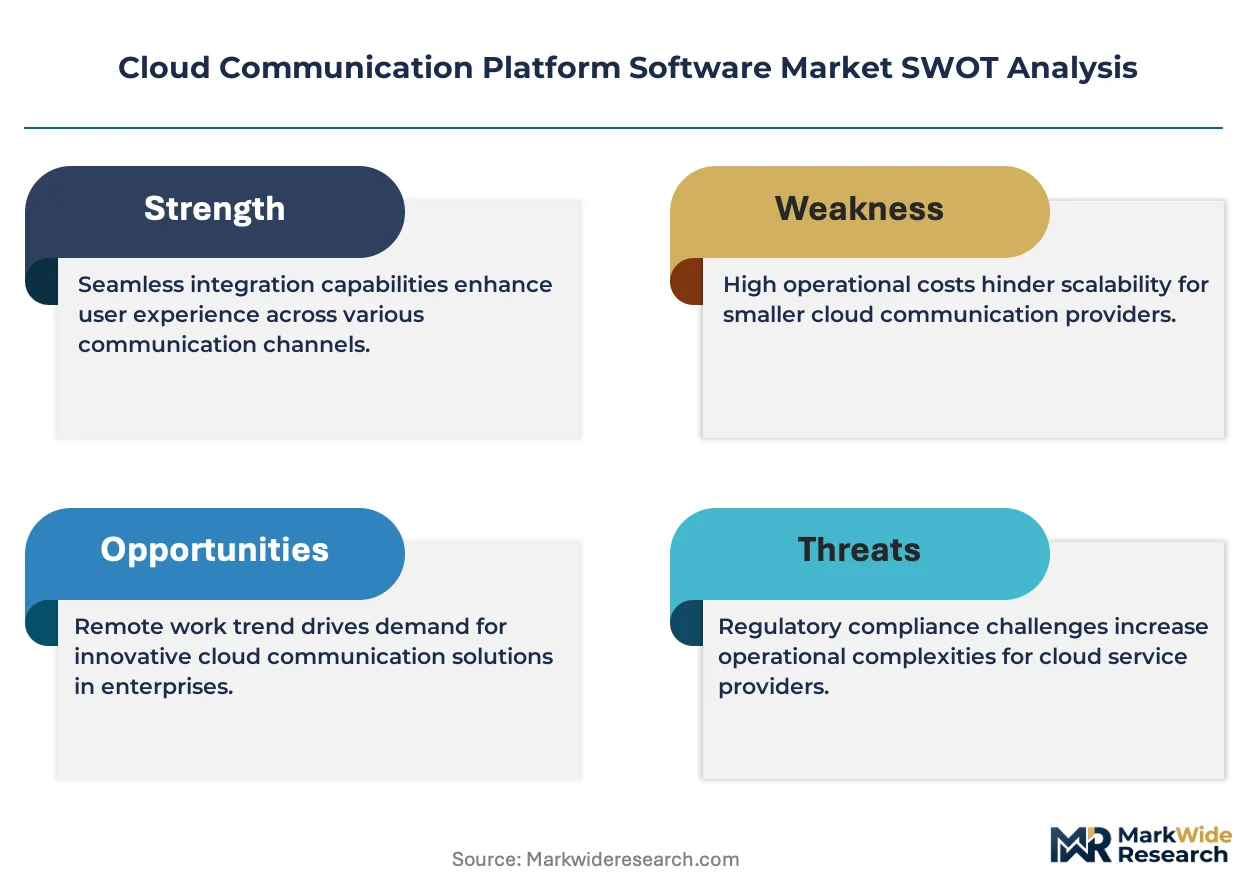
FCC net neutrality rulings and GDPR cross-border data transfer rules shape architecture decisions for US and European deployments, forcing regional data residency investments. HIPAA compliance requirements constrain healthcare messaging configurations. ISO 27001 certification operates as a de facto market access filter for financial services procurement. Stakeholders must weigh API ecosystem extensibility against sovereign cloud mandates as regulatory fragmentation intensifies.
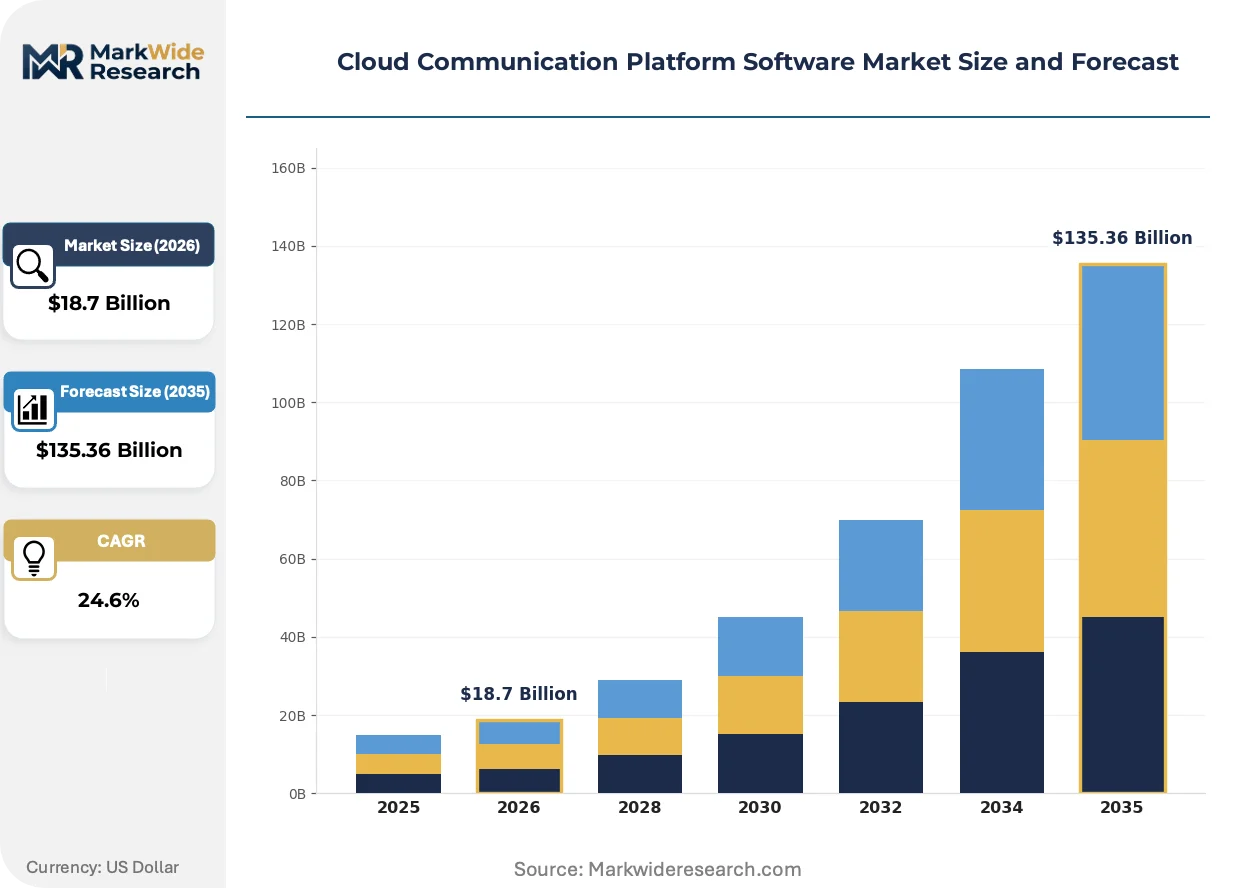
Market Dynamics
Enterprise telephony replacement cycles are compressing as AI-native communication stacks displace decade-old PBX infrastructure, forcing vendors to rearchitect around sub-100ms latency guarantees and sovereign data residency mandates.
Growth Catalysts
- HIPAA-compliant messaging:Healthcare systems in the United States are mandating encrypted patient communication channels, expanding procurement of cloud-native engagement platforms with clinical workflow integration.
- EU AI Act classification:Automated customer interaction systems face new transparency obligations across European deployments, creating certified-vendor preference effects in procurement.
- API-first architecture:Embedded communication workflows in SaaS applications are pulling voice and video services directly into CRM and ERP environments without standalone UC purchases.
Market Restraints
- Cross-border data transfer friction:GDPR adequacy decisions and Schrems II rulings force redundant regional infrastructure investments, elevating total cost of ownership for multi-national deployments.
- Specialized talent scarcity:SRE and cloud-native telephony engineering expertise concentrates in Silicon Valley and Bangalore, constraining vendor scaling velocity.
- Circuit-switched substitution:Legacy ISDN trunking persists in regulated financial services and government accounts, delaying full IP migration timelines.
Strategic Opportunities
- India enterprise digitization:TRAI's cloud telephony liberalization and PLI scheme incentives for data center infrastructure are opening mid-market SaaS penetration.
- Edge-AI inference convergence:On-device transcription and real-time translation are enabling offline-capable communication stacks for field workforce segments.
- Embedded finance integration:Payment-enabled messaging workflows in insurance and lending verticals are creating new ARPU expansion vectors beyond seat-based pricing.
Industry Challenges
- ISO 27001 certification timelines:Financial services procurement gates require 12-18 month audit cycles, constraining vendor market access velocity.
- Legacy PBX integration complexity:Hybrid coexistence requirements with Siemens, Avaya, and Cisco on-premises systems extend implementation durations and elevate professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Communication Platform Software Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Enterprise, SMBs, Government, Educational Institutions Solution: Unified Communications, Video Conferencing, Contact Center, Messaging Technology: VoIP, WebRTC, AI, APIs |
| Companies Covered | Nextiva, Zendesk Talk, Microsoft Teams, Dialpad, Intermedia Cloud Communications, RingCentral, CloudTalk, Mitel, Zoom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Communication Platform Software Market Strategic Shifts
Real-time communication infrastructure is bifurcating between commodity video conferencing and premium AI-orchestrated workflow layers, with vendor differentiation migrating toward embedded intelligence and vertical-specific compliance automation.
CPaaS architecture is fragmenting as modular API stacks displace monolithic UCaaS bundles. Mid-market enterprises in Germany and the United Kingdom are adopting best-of-breed voice, SMS, and verification APIs from specialized providers rather than single-vendor suites. This unbundling is compressing margins on standardized conferencing while expanding addressable spend on programmable communication layers.
The EU AI Act's risk-based classification system is reshaping procurement criteria for automated contact center systems. High-risk conversational AI deployments now require conformity assessments, human oversight protocols, and training data documentation. European financial services and healthcare buyers are prioritizing vendors with established notified body relationships and pre-certified model cards.
Enterprise buyers are consolidating vendor relationships around communication platforms that embed directly into Salesforce, ServiceNow, and Microsoft Teams environments. Seat-based pricing is giving way to consumption models tied to API call volumes and workflow automation triggers. This shift is most pronounced in United States technology and professional services verticals, where procurement teams favor outcome-linked contracts over fixed per-user fees.
Cloud Communication Platform Software Market Segmentation
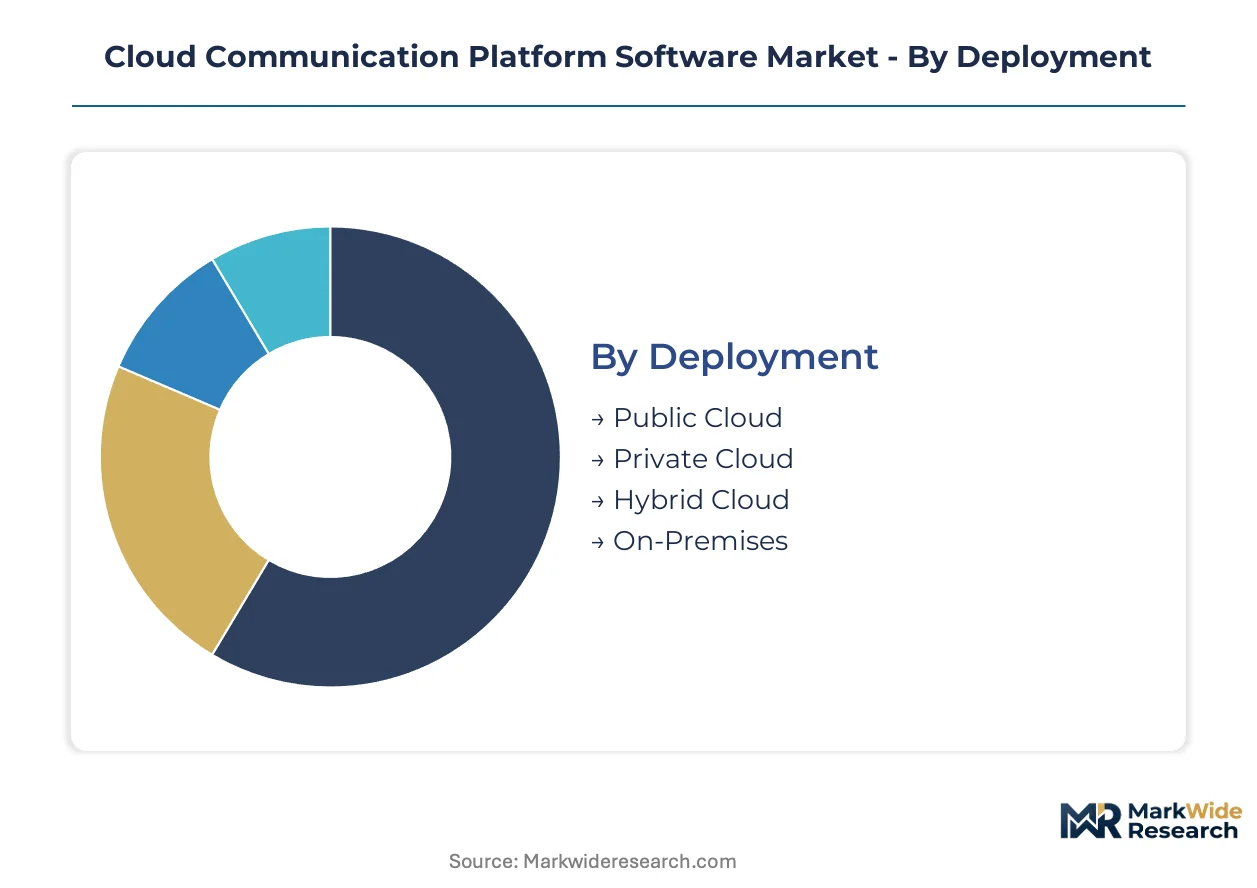
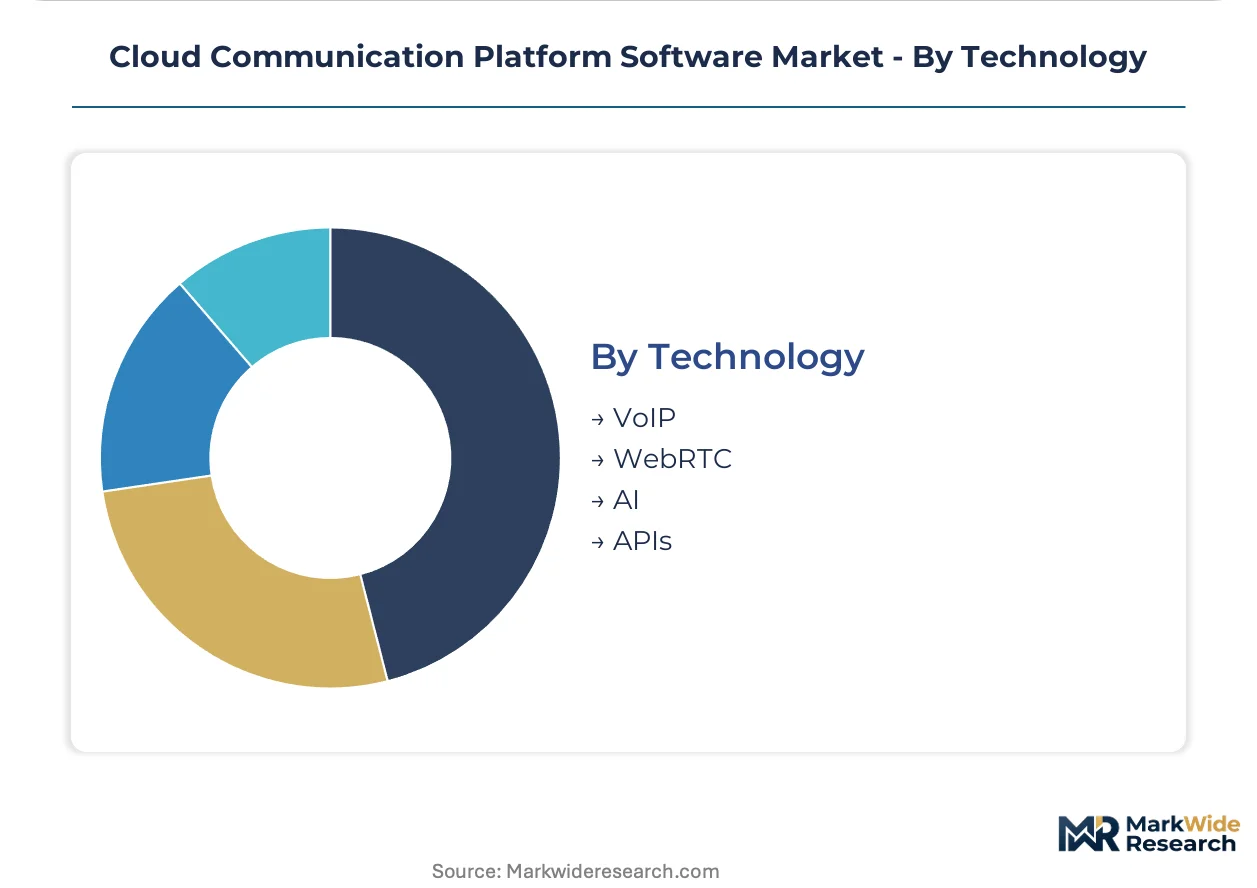
Cloud communication platform software segments along deployment architecture, buyer scale, solution stack, and underlying protocol layers. Procurement patterns diverge sharply between regulated verticals requiring sovereign data control and technology firms prioritizing API extensibility over compliance overhead.
Deployment:
Channel mix varies dramatically by deployment mode—systems integrators dominate private cloud implementations while direct SaaS sales capture public cloud volumes.
- Public Cloud:Multi-tenant infrastructure delivers sub-150ms latency through geographically distributed points of presence. Technology and professional services firms in the United States concentrate procurement here, driven by consumption-based pricing and rapid provisioning cycles.
- Private Cloud:Single-tenant environments with dedicated compute and storage clusters meet data residency mandates. German financial institutions and French healthcare networks drive demand, constrained by GDPR Article 44 transfer restrictions and national cloud sovereignty policies.
- Hybrid Cloud:Split architectures route sensitive workloads to on-premises nodes while bursting traffic spikes to public infrastructure. Manufacturing and logistics operators across India favor this model, balancing TRAI compliance requirements against cloud cost optimization.
- On-Premises:Legacy PBX coexistence configurations persist in government and defense accounts with air-gapped security requirements.
Public Cloud dominates installed base. Private Cloud is where expansion concentrates.
End User:
Customer type dictates sales cycle length and pricing architecture—enterprise accounts demand outcome-based contracts while SMBs transact through self-serve channels.
- Enterprise:Fortune 500 accounts with 10,000+ seats negotiate custom SLAs around 99.999% uptime guarantees and dedicated support tiers. HIPAA and ISO 27001 certification gates filter vendor eligibility in United States healthcare and financial services procurement.
- SMBs:Sub-500 seat organizations purchase through channel partners and digital marketplaces, prioritizing Microsoft Teams and Salesforce native integration over standalone feature depth.
- Government:Federal and state agencies require FedRAMP or equivalent national security certifications, extending sales cycles to 18-24 months.
- Educational Institutions:K-12 and university systems procure through cooperative purchasing agreements, with FERPA compliance shaping messaging and video retention policies.
Enterprise captures the deepest margin pools. SMBs represent the steepest expansion trajectory.
Solution:
Solution bundling determines revenue recognition—unified communications and contact center combinations command 40-60% price premiums over standalone video or messaging.
- Unified Communications:Integrated voice, video, and messaging stacks with presence management and calendar integration. United States professional services and consulting firms drive replacement of legacy PBX infrastructure, motivated by remote workforce coordination requirements.
- Contact Center:Omnichannel routing, workforce management, and quality analytics for customer service operations. European financial services and telecommunications providers expand investment, compelled by EU AI Act transparency obligations for automated interaction systems.
- Video Conferencing:Standalone meeting infrastructure faces commoditization pressure as embedded video in UC suites and productivity platforms displaces point solutions.
- Messaging:SMS, MMS, and rich communication services APIs power transactional notifications and two-factor authentication workflows.
Unified Communications anchors vendor revenue. Contact Center is climbing the fastest.
Technology:
Protocol layer selection shapes gross margins—proprietary VoIP stacks retain pricing power while WebRTC and open APIs compress differentiation.
- VoIP:Session Initiation Protocol-based voice transmission with codec optimization for bandwidth-constrained environments. Legacy carriers and regional telecom operators in India maintain substantial installed bases, though migration toward WebRTC accelerates.
- WebRTC:Browser-native real-time communication eliminating plugin dependencies and reducing client-side friction. Technology startups and embedded communication providers across Germany and the United Kingdom standardize on this stack, driven by developer experience and rapid deployment cycles.
- AI:Natural language processing for transcription, sentiment analysis, and conversational automation. High-risk classification under EU AI Act mandates conformity assessments for European deployments.
- APIs:Programmable interfaces enabling voice, video, and messaging embedding into third-party applications.
VoIP retains legacy lock-in. APIs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial services trade surplus in cloud communication platforms, while Germany and India import embedded communication infrastructure to support domestic enterprise digitization. Cross-border data transfer restrictions are fragmenting regional deployment architectures.
United States
Fortune 500 telephony replacement cycles and healthcare HIPAA compliance mandates drive procurement of AI-native communication stacks. FCC net neutrality rulings shape architecture decisions for multi-tenant deployments. Silicon Valley and Seattle clusters concentrate vendor engineering talent and channel partner density.
Germany
Financial services and automotive OEMs demand sovereign cloud configurations with dedicated compute clusters. GDPR Article 44 transfer restrictions and national cloud sovereignty policies constrain public cloud adoption. Frankfurt and Munich host private cloud infrastructure investments from regulated verticals.
India
Mid-market SaaS penetration accelerates through TRAI cloud telephony liberalization and PLI scheme data center incentives. Manufacturing and logistics operators favor hybrid architectures balancing compliance against cost optimization. Bengaluru and Hyderabad concentrate SRE and cloud-native telephony engineering expertise.
United Kingdom
Professional services firms and fintech startups standardize on WebRTC stacks for rapid deployment cycles. Post-Brexit data adequacy negotiations complicate cross-border service delivery. London anchors financial services procurement of contact center infrastructure with EU AI Act conformity requirements.
Japan
Enterprise buyers prioritize Microsoft Teams native integration over standalone UC purchases. METI digital transformation subsidies support SMB migration from legacy PBX systems. Tokyo and Osaka metropolitan areas concentrate demand for embedded communication workflows in manufacturing supply chains.
Cloud Communication Platform Software Market Competitive Environment
Concentration sits with North American SaaS incumbents that have achieved channel partner density and enterprise certification gates. The vendor base stratifies across three tiers: cloud-native specialists with AI-first architectures, legacy telecom operators pivoting from circuit-switched infrastructure, and API-first developers embedding communication into vertical SaaS applications. Dominant competitive moves include strategic partnerships with CRM and ERP platforms and portfolio diversification into contact center workforce management.
Within the cloud-native tier, RingCentral and Dialpad exemplify divergent specialization strategies, with the former anchoring channel-driven enterprise penetration and the latter occupying a position around native AI transcription. Zoom sits within the video-first archetype that is migrating toward unified platform bundling. These three represent the competitive vectors reshaping procurement criteria across United States technology and professional services verticals.
| Leading Market Players |
|---|
| Nextiva |
| Zendesk Talk |
| Microsoft Teams |
| Dialpad |
| Intermedia Cloud Communications |
| RingCentral |
| CloudTalk |
| Mitel |
| Zoom |
| Others |
Value Chain & Pricing Dynamics
Consumption-based API contracts lock in multi-year supply commitments for cloud infrastructure providers while capping unit-price exposure for enterprise buyers across United States and European deployments. This structure ties pricing visibility directly to hyperscaler capacity reservations in Frankfurt, Virginia, and Mumbai data center clusters.
Pricing Analysis
Enterprise buyers anchor seat-based pricing erosion through consolidated vendor negotiations and outcome-linked contract structures. Three-tier pricing structure across premium AI-orchestrated, standard unified communications, and economy messaging-only tiers separates compliance-automation depth from basic connectivity. Cost compression in the standard tier intensifies because WebRTC commodification erodes voice transport margins. SMB buyers exhibit highest price sensitivity, while Fortune 500 accounts prioritize SLA guarantees over per-seat economics.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for server hardware destined to Bengaluru and Hyderabad co-location facilities. Supply concentrates in Taiwan for advanced semiconductors, China for optical networking components, and Ireland for GDPR-compliant data center infrastructure. Raw material dependencies span silicon wafers, rare earth magnets for power systems, and lithium-ion battery arrays. Single-source vulnerability in Taiwan-based chip fabrication threatens infrastructure scaling timelines. Distribution runs through hyperscaler-direct procurement channels and systems integrator-led private cloud deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensive moats in this market rest on regulatory certification entrenchment—ISO 27001, HIPAA, and EU AI Act conformity create multi-year procurement friction that protects incumbent positions against pure-play challengers.
For Market Incumbents: Consolidate channel partner density in North American enterprise accounts to defend against API-first challengers embedding voice services directly into Salesforce and ServiceNow environments. Deepen vertical integration into sovereign cloud infrastructure in Frankfurt and Paris to preempt GDPR Article 44 compliance-driven vendor switches. Prioritize FedRAMP and EU AI Act notified body relationships as certification gates that delay competitor market access by 12-18 months. For New Entrants and Emerging Players: ISO 27001 fast-track programs for financial services procurement unlock mid-market penetration in Germany and the United Kingdom where audit cycle delays filter established vendors. Target India's TRAI-liberalized cloud telephony segment where PLI scheme data center incentives reduce infrastructure cost barriers. Lead with embedded finance integration in insurance and lending workflows to bypass seat-based pricing commoditization. For Investors and Strategic Acquirers: AI-native transcription specialists with healthcare HIPAA certification and European GDPR deployment track records command scarcity premiums in consolidation scenarios. Long-term viability hinges on API ecosystem extensibility rather than standalone UCaaS bundle retention. Monitor EU AI Act conformity assessment timelines as inflection signals—vendors with pre-certified model cards will capture accelerated procurement cycles in European financial services.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native embedding into Microsoft Teams and Salesforce environments captures procurement consolidation in United States technology verticals. |
| Strategic Partnership | Notified body relationships for EU AI Act conformity assessments accelerate European financial services sales cycles. |
| Acquisition of Specialist Firm | AI transcription engines with clinical workflow integration deepen healthcare vertical penetration beyond generic UCaaS. |
| Geographic Expansion | Frankfurt and Mumbai data center investments satisfy GDPR and TRAI data residency mandates for regulated accounts. |
| Product Launch | Edge-AI inference stacks enable offline-capable field workforce communication in manufacturing and logistics segments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory notification databases to validate market sizing and competitive positioning. Interviews with CTOs, IT procurement officers, channel partners, and integration specialists across United States, Germany, and India inform deployment architecture preferences and vendor selection criteria. Bottom-up triangulation from vendor revenue disclosures and top-down validation from enterprise technology spending surveys ensure cross-verified outputs.
Segmentation dimensions modeled span deployment architecture, organization size, solution stack composition, and underlying protocol layer across the projection horizon. CAGRs derive from regression analysis against enterprise telephony replacement cycle compression and API-first adoption curves. Industry-specific inputs include HIPAA compliance mandate timelines in United States healthcare and EU AI Act risk classification thresholds for automated contact center systems.
Underlying assumptions cover sustained enterprise digital transformation budgets, stable hyperscaler infrastructure pricing, and regulatory enforcement consistency, with deviation risk concentrated in cross-border data transfer adequacy rulings and circuit-switched legacy persistence in financial services. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Resonator Design Software Market
Software & Services
Search and Discovery Software Market
Software & Services
Stock Footage Software Market
Software & Services
Saas-Based SCM Market
Software & Services
Content Services Platforms Market
Software & Services
Global Online Proofing Software Market
Software & Services
Point of Sale (Pos) Software Market
Software & Services
Global Voip Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Automated Testing Software Market
Software & Services
Global Catalog Management Software Market
Software & Services
Data Exchange Platform Services Market
Software & Services
Global Test Data Management Market
Software & Services
Enterprise Mobility Software Market
Software & Services
Cursor Reviewer Market
Software & Services
Computer Assisted Translation Software Market