
 Telecommunications Relay Service (TRS) Market | 2026-2036
Telecommunications Relay Service (TRS) Market Size, Share, and Industry Trends Forecast 2026-2036
Telecommunications Relay Service (TRS) Market Analytics
Subscription-based leasing of relay infrastructure is tilting competitive dynamics toward providers with capital-light operating models. Purple Communications leverages cloud-native architectures to reduce upfront deployment costs for enterprise clients. Sorenson Communications anchors its position through proprietary video compression technology that sustains call quality at lower bandwidth thresholds. AT&T competes by extending its nationwide fiber backbone into dedicated TRS traffic prioritization.
Telecommunications Relay Service encompasses systems that translate between voice, text, and video formats to enable real-time communication for individuals with hearing or speech disabilities, operating through human interpreters, automated speech recognition engines, or hybrid workflows with latency targets under 300 milliseconds. Video Relay Service leads solution-type revenue due to interpreter labor costs and premium pricing for American Sign Language sessions, while Captioned Telephone Service penetrates fastest among aging populations with late-onset hearing loss. Cloud-Based deployment dominates new installations as state relay administrators migrate from legacy TTY infrastructure, though Hybrid models persist in educational institutions with intermittent connectivity.
The FCC enforces minimum service quality benchmarks and fund allocation through the Interstate Telecommunications Relay Services Fund, while the ADA mandates employer provision of accessible communication tools shaping enterprise procurement patterns. State-level public utility commissions in California, Texas, and New York layer additional interpreter certification requirements that filter market access. Stakeholders must monitor FCC proceedings on next-generation TRS standards and fund contribution methodology reform to anticipate margin compression or eligibility expansion.
Market Dynamics
FCC fund contribution methodology reform is compressing margins across the Telecommunications Relay Service ecosystem while accelerating cloud migration mandates for state relay administrators.
Growth Catalysts
- ADA Employer Mandates:Federal accessibility requirements compel enterprise procurement of video relay platforms for deaf and hard-of-hearing employees, expanding commercial subscriber bases beyond traditional consumer segments.
- Cloud-Native Architectures:State relay administrators in California, Texas, and New York are abandoning legacy TTY infrastructure for scalable IP-based deployments that reduce maintenance overhead.
- Late-Onset Hearing Loss Demographics:Aging populations in metropolitan corridors drive Captioned Telephone Service penetration among seniors requiring real-time text transcription during voice calls.
Market Restraints
- Interpreter Labor Cost Inflation:American Sign Language certification scarcity in concentrated urban markets elevates per-minute service delivery costs for Video Relay Service providers.
- FCC Fund Allocation Uncertainty:Contribution methodology reform debates create pricing volatility for interstate relay services dependent on universal service fund subsidies.
- Legacy TTY Infrastructure Stranded Assets:Educational institutions with intermittent rural connectivity face capital write-downs during hybrid migration timelines.
Strategic Opportunities
- AI-Assisted Interpretation Convergence:Automated speech recognition engines hybridizing with human interpreter workflows promise latency compression below 300-millisecond thresholds.
- Enterprise Leasing Models:Subscription-based infrastructure access displaces upfront capital expenditure requirements for mid-market employers.
- State-Level Certification Arbitrage:Public utility commissions in Texas and New York impose interpreter standards that create competitive moats for compliant providers.
Industry Challenges
- Interpreter Talent Pipeline Constraints:RID certification backlogs and regional concentration of qualified professionals limit service scaling in secondary metropolitan areas.
- Hybrid Integration Complexity:Educational institutions struggle to synchronize cloud-based relay platforms with existing campus telephony and emergency notification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecommunications Relay Service (TRS) Market |
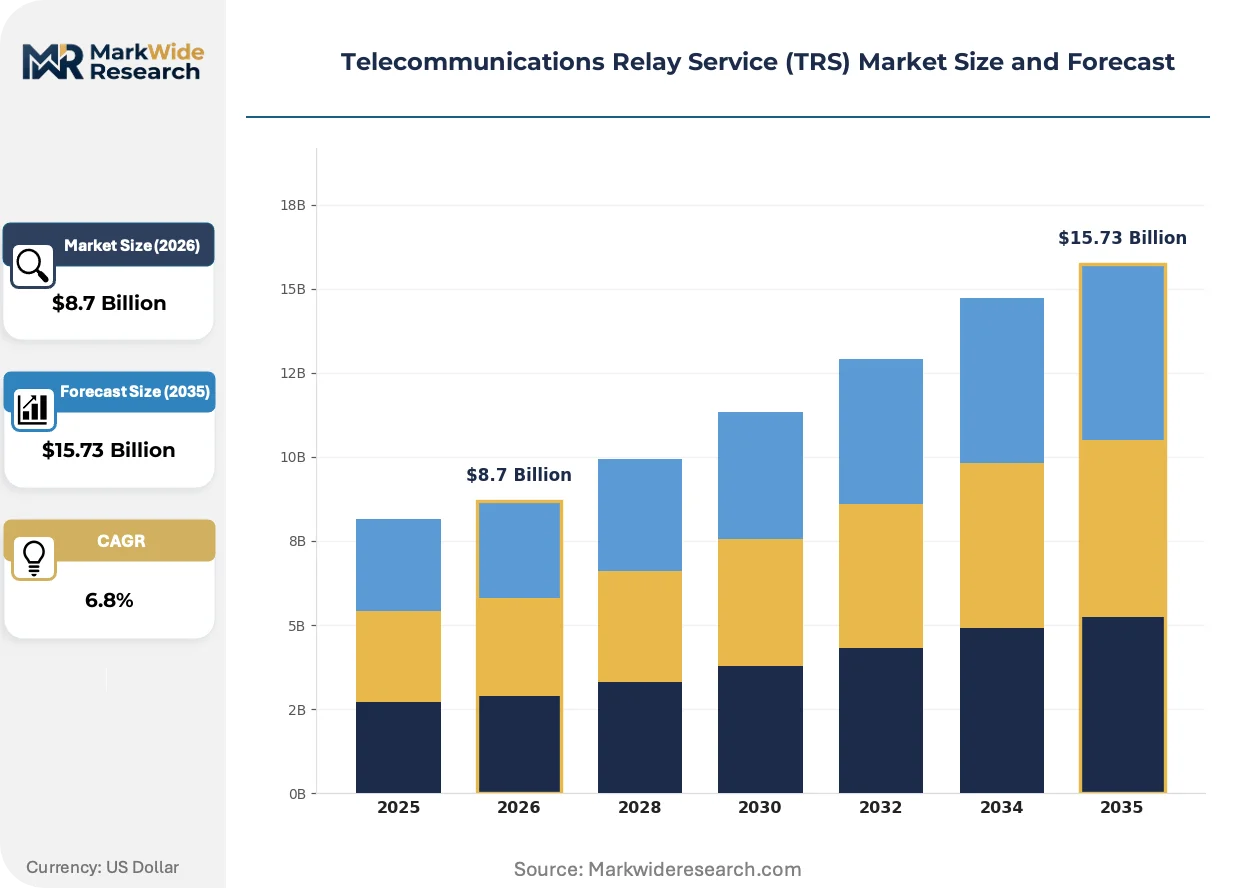
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Video Relay Service, Text Relay Service, Captioned Telephone Service, Next Generation TRS End User: Individuals with Hearing Loss, Government Agencies, Businesses, Educational Institutions Deployment Model: Cloud-Based, On-Premises, Hybrid, Third-Party Hosted Technology: Voice Recognition, Video Conferencing, Text-to-Speech, Mobile Applications |
| Companies Covered | AT&T, Purple Communications, Sorenson Communications, ZVRS, Hamilton Relay, Communication Service for the Deaf, Verizon, CaptionCall, Bell Canada, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecommunications Relay Service (TRS) Market Evolving Landscape
Real-time communication infrastructure is undergoing fundamental restructuring as automated systems interweave with human expertise, regulatory frameworks tighten quality benchmarks, and procurement patterns pivot toward operational expenditure models.
Automated speech recognition engines with neural machine translation capabilities are hybridizing traditional interpreter-dependent workflows. State relay administrators in California and Texas are piloting these platforms for high-volume, low-complexity call types. This convergence is compressing labor cost structures while preserving human escalation pathways for nuanced medical and legal conversations.
The FCC's next-generation TRS standards proceeding is mandating latency benchmarks and interoperability protocols for emerging IP-based services. Equipment manufacturers must certify devices against updated technical requirements before fund eligibility. Video relay providers with proprietary compression architectures face adaptation costs to meet open-standards compliance.
Enterprise buyers are unbundling relay service procurement from bundled telecommunications contracts. Fortune 500 accessibility officers now issue standalone RFPs for platform-agnostic solutions with SLA-backed uptime guarantees. This pattern is most visible in financial services and healthcare verticals with federally mandated accommodation requirements.
Telecommunications Relay Service (TRS) Market Segmentation
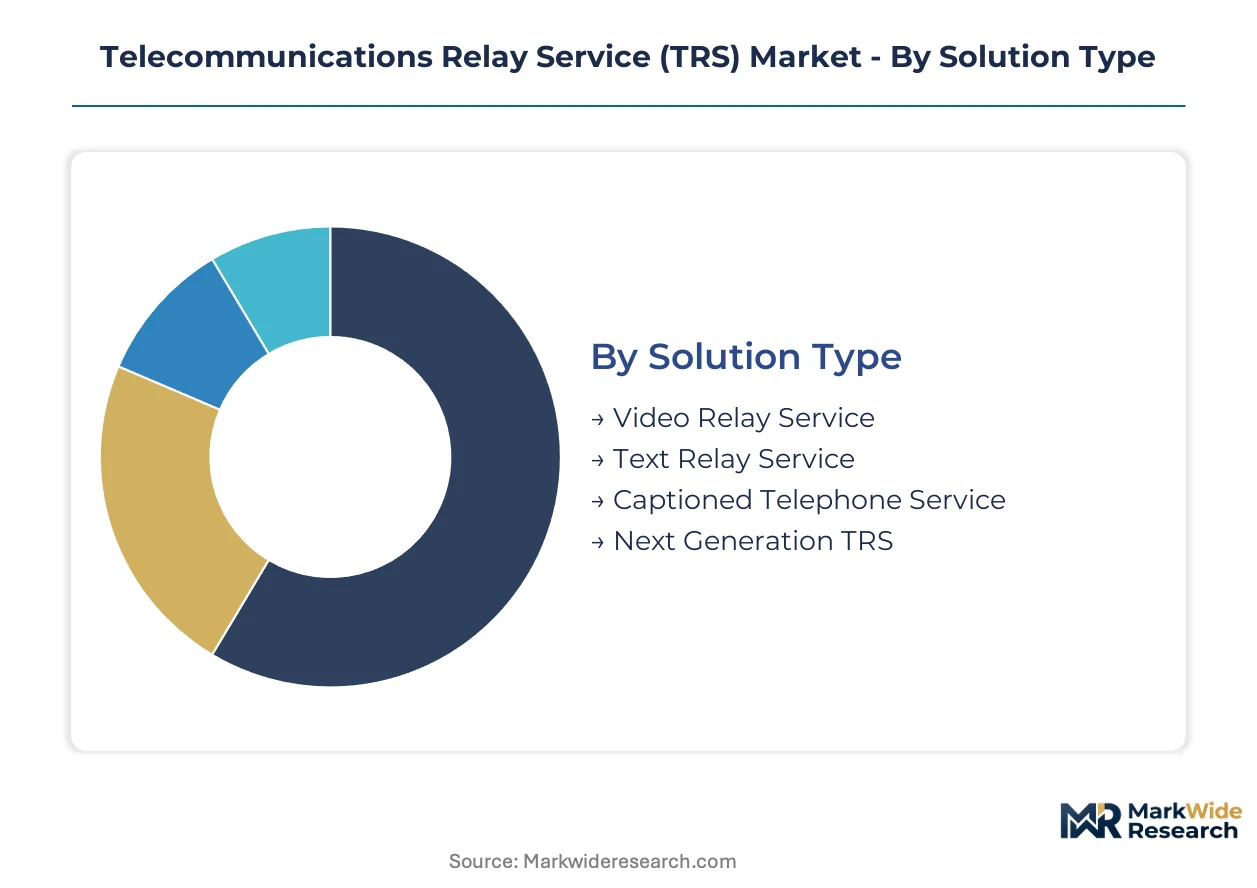
TRS procurement patterns diverge sharply across solution architectures and buyer profiles, with interpreter labor economics and compliance mandates dictating segment prioritization. Understanding these fault lines reveals where margin pools concentrate and which deployment models face obsolescence pressure.
Solution Type:
After-sales service intensity varies dramatically across solution types, with Video Relay Service requiring 24/7 interpreter staffing and Captioned Telephone Service demanding minimal live support.
- Video Relay Service:Real-time American Sign Language interpretation delivered through video endpoints, requiring certified interpreter pools and sub-300-millisecond latency infrastructure. Demand concentrates in California, Texas, and New York metropolitan corridors where FCC fund allocation and state certification requirements create competitive moats for compliant providers.
- Captioned Telephone Service:Synchronous text transcription overlaying voice calls, leveraging automated speech recognition with human backup for accuracy validation. Late-onset hearing loss among aging populations in suburban and rural markets drives penetration, with lower per-minute delivery costs than video alternatives.
- Text Relay Service:Keyboard-based communication bridging text and voice formats through human operators or automated systems.
- Next Generation TRS:IP-native platforms integrating multiple modalities under unified interfaces, pending FCC interoperability certification.
By volume, Captioned Telephone Service leads. By growth pace, Next Generation TRS is ahead.
End User:
Cost tier stratification separates enterprise buyers with SLA requirements from individual consumers dependent on subsidized access.
- Individuals with Hearing Loss:Consumer segment accessing services through FCC-mandated fund subsidies, with quality sensitivity concentrated among American Sign Language users requiring nuanced interpretation.
- Government Agencies:Federal, state, and local entities procuring under Section 508 and ADA compliance mandates, with California and Texas public utility commissions layering additional interpreter certification standards that filter vendor eligibility.
- Businesses:Employers providing reasonable accommodation under ADA Title I, increasingly favoring subscription-based leasing over capital-intensive infrastructure ownership.
- Educational Institutions:K-12 and higher education balancing cloud migration imperatives against legacy TTY system stranded assets in rural campuses with intermittent connectivity.
By contract value, Government Agencies dominate. By expansion velocity, Businesses are climbing fastest.
Deployment Model:
Application context determines architecture choice, with emergency services and healthcare demanding latency guarantees that hybrid models struggle to satisfy.
- Cloud-Based:Scalable IP-native infrastructure eliminating upfront capital expenditure, now dominant for new installations as state relay administrators abandon legacy TTY systems.
- Hybrid:Mixed cloud-edge configurations persisting in educational institutions and rural healthcare networks where bandwidth inconsistency threatens call continuity.
- On-Premises:Dedicated hardware deployments retained by defense contractors and financial institutions with data sovereignty requirements.
- Third-Party Hosted:Managed service arrangements where specialized TRS providers operate infrastructure on behalf of enterprise clients.
By new installation share, Cloud-Based leads. By retention complexity, Hybrid faces the steepest operational burden.
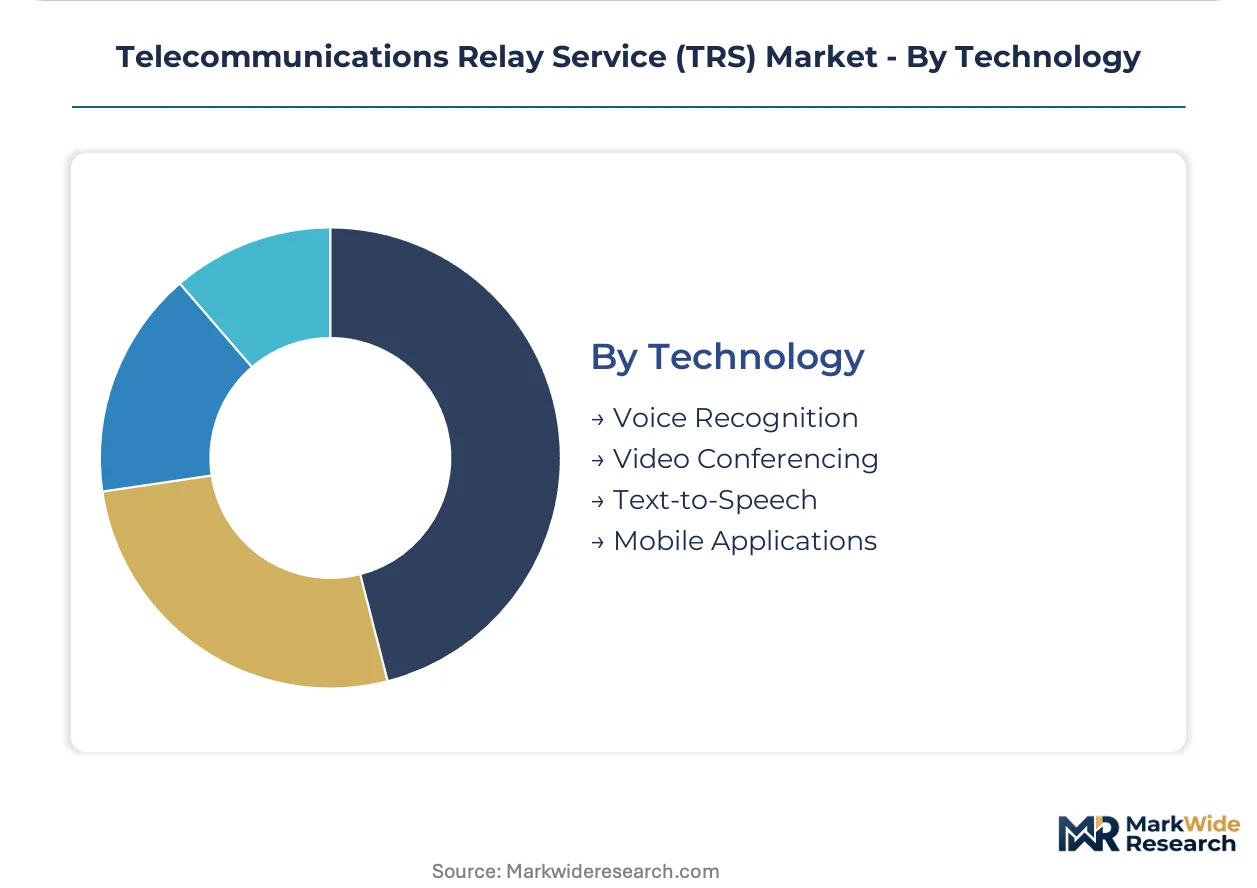
Technology:
Customer type segmentation separates consumer-grade mobile accessibility from enterprise-grade platform integration requiring API interoperability.
- Voice Recognition:Automated speech-to-text engines hybridizing with human workflows, piloted by California and Texas administrators for high-volume, low-complexity call types.
- Video Conferencing:Proprietary compression architectures sustaining quality at lower bandwidth thresholds, facing adaptation costs for FCC open-standards compliance.
- Text-to-Speech:Synthesis technologies for voice output from text inputs, deployed in Captioned Telephone Service backends.
- Mobile Applications:Smartphone-native interfaces displacing dedicated hardware endpoints among younger users with hearing loss.
By deployment scale, Video Conferencing leads. By disruption potential, Voice Recognition is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in relay services through technology licensing and interpreter training exports, while import dependency concentrates on specialized video compression hardware from Asian component suppliers.
United States
Federal procurement under Section 508 and ADA Title I mandates drives enterprise demand for video relay platforms. The FCC enforces minimum service quality benchmarks and fund allocation through the Interstate Telecommunications Relay Services Fund. California, Texas, and New York metropolitan corridors concentrate interpreter certification programs and cloud-native deployment pilots.
Canada
Universal service obligations under the Canadian Radio-television and Telecommunications Commission expand accessibility procurement across federal agencies. Bell Canada operates under mandated service quality frameworks for deaf and hard-of-hearing subscribers. Ontario and Quebec host the primary interpreter training institutions serving North American certification requirements.
United Kingdom
Equality Act 2010 compliance obligations shape employer-provided communication accommodation demand in financial services and healthcare verticals. Ofcom regulates text relay and video relay minimum service standards with fund contribution mechanisms. London anchors European interpreter talent pools and enterprise sales operations for multinational relay providers.
Germany
Social Code Book IX mandates employer accommodation for employees with hearing disabilities, expanding commercial relay procurement. The Federal Network Agency oversees quality benchmarks for telecommunications accessibility services. Bavaria and North Rhine-Westphalia concentrate manufacturing enterprises with established accessibility officer functions.
Australia
National Relay Service funding through the Department of Infrastructure maintains consumer access while enterprise procurement grows under Disability Discrimination Act obligations. The Australian Communications and Media Authority sets service standards for text and video relay platforms. New South Wales and Victoria host the primary interpreter workforce development programs.
Telecommunications Relay Service (TRS) Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: national telecommunications carriers with fiber infrastructure, specialized relay providers with interpreter workforce control, and cloud-native entrants with subscription-based delivery models. Strategic archetypes include infrastructure-anchored incumbents, interpreter-labor specialists, and capital-light platform operators. Competitive moves concentrate on FCC certification acquisition and state-level public utility commission compliance to secure fund eligibility.
Among specialized relay providers, Purple Communications, Sorenson Communications, and ZVRS occupy positions within the interpreter-dependent tier, each representing distinct approaches to workforce certification and technology architecture. AT&T and Verizon exemplify the carrier-integrated archetype, leveraging existing network infrastructure for traffic prioritization. These named entities anchor competitive dynamics without constituting exhaustive market coverage.
| Leading Market Players |
|---|
| AT&T |
| Purple Communications |
| Sorenson Communications |
| ZVRS |
| Hamilton Relay |
| Communication Service for the Deaf |
| Verizon |
| CaptionCall |
| Bell Canada |
| Others |
Value Network & Pricing Analysis
Interstate fiber corridors linking California, Texas, and New York relay hubs concentrate logistics costs for interpreter deployment while enabling FCC fund allocation efficiencies that separate premium-certified providers from economy-tier competitors.
Pricing Analysis
Enterprise buyers with ADA compliance mandates anchor subscription-based pricing structures across cloud-native platforms. Three-tier pricing stratifies across premium RID-certified interpretation, standard automated-hybrid workflows, and economy-tier text-only services. Cost compression in the premium tier stems from interpreter labor scarcity in metropolitan corridors. Small employers and individual consumers exhibit highest price sensitivity, while Fortune 500 accessibility officers prioritize SLA-backed uptime over per-minute rates.
Supply Chain Analysis
Export controls on specialized video compression hardware from Taiwan and South Korea constrain component flows for proprietary relay infrastructure. Interpreter talent pipelines draw from domestic certification programs in California, Texas, and New York, while cloud infrastructure rests on hyperscaler data centers concentrated in Virginia and Oregon. Single-source vulnerability concentrates in ASIC suppliers for low-latency encoding. Distribution runs through state relay administrators and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FCC next-generation TRS standards proceedings are accelerating market disruption as interoperability mandates force architectural pivots across incumbent and emerging providers.
For Market Incumbents: Entrench proprietary interpreter certification programs in California, Texas, and New York to maintain state-level compliance moats against cloud-native entrants. Deepen backward integration into ASIC design for video compression to preserve latency advantages under open-standards pressure. For New Entrants and Emerging Players: Secondary metropolitan areas with RID certification backlogs represent the most penetrable entry point for automated-hybrid relay platforms. Target mid-market employers in healthcare and financial services verticals with subscription-based leasing models that displace capital-intensive infrastructure procurement. For Investors and Strategic Acquirers: Cloud-native platform operators with established FCC fund eligibility and scalable IP architectures offer the strongest acquisition profile for long-term positioning. Monitor FCC proceedings on contribution methodology reform as the critical inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| FCC Certification Acquisition | Fund eligibility unlocks access to subsidized consumer segments and enterprise procurement pipelines. |
| Interpreter Workforce Expansion | RID-certified talent pools in California and Texas create defensible service quality differentiation. |
| Cloud-Native Platform Migration | IP-based architectures reduce stranded asset risk from legacy TTY infrastructure retirement. |
| Enterprise Subscription Pivot | Operational expenditure models align with Fortune 500 accessibility officer procurement preferences. |
| AI-Hybrid Workflow Deployment | Automated speech recognition integration compresses labor costs while preserving human escalation pathways. |
Research Methodology
A spread of perspectives from relay service administrators, interpreter certification directors, enterprise accessibility officers, and FCC policy staff converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC proceeding documents, state public utility commission filings, and ADA enforcement records. Bottom-up segment sizing triangulated against top-down fund allocation data.
Demand-supply balance modeling across the projection horizon incorporated solution type, deployment model, end-user category, and state-level regulatory cluster as core segmentation dimensions. CAGRs derived from fund flow trajectories, interpreter workforce growth rates, and cloud migration adoption curves. Analysis window assumptions reflect FCC fund contribution methodology stability and ADA employer mandate enforcement continuity.
Macroeconomic conditions sit as an overlay; deviation in universal service fund solvency or federal accessibility enforcement intensity would shift the trajectory. Material shifts in FCC next-generation TRS standards timing or interpreter certification backlog resolution would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
North America Postal Services Market
Communication Services
Postal Services Market
Communication Services
Fixed Business Voice Platforms and Services Market
Communication Services
Industrial Communication Market
Communication Services
Outbound Telemarketing Market
Communication Services
Global Communications Interface Market
Communication Services
Walkie Talkie Market
Communication Services
Broadcasting Solutions Market
Communication Services
Message Handling Systems Market
Communication Services
Managed Communication Services Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Pcaas Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Web Conferencing Market
Communication Services
Voip Services Market