
 Fixed Business Voice Platforms and Services Market | 2026-2036
Fixed Business Voice Platforms and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Business Voice Platforms and Services Market Foresight
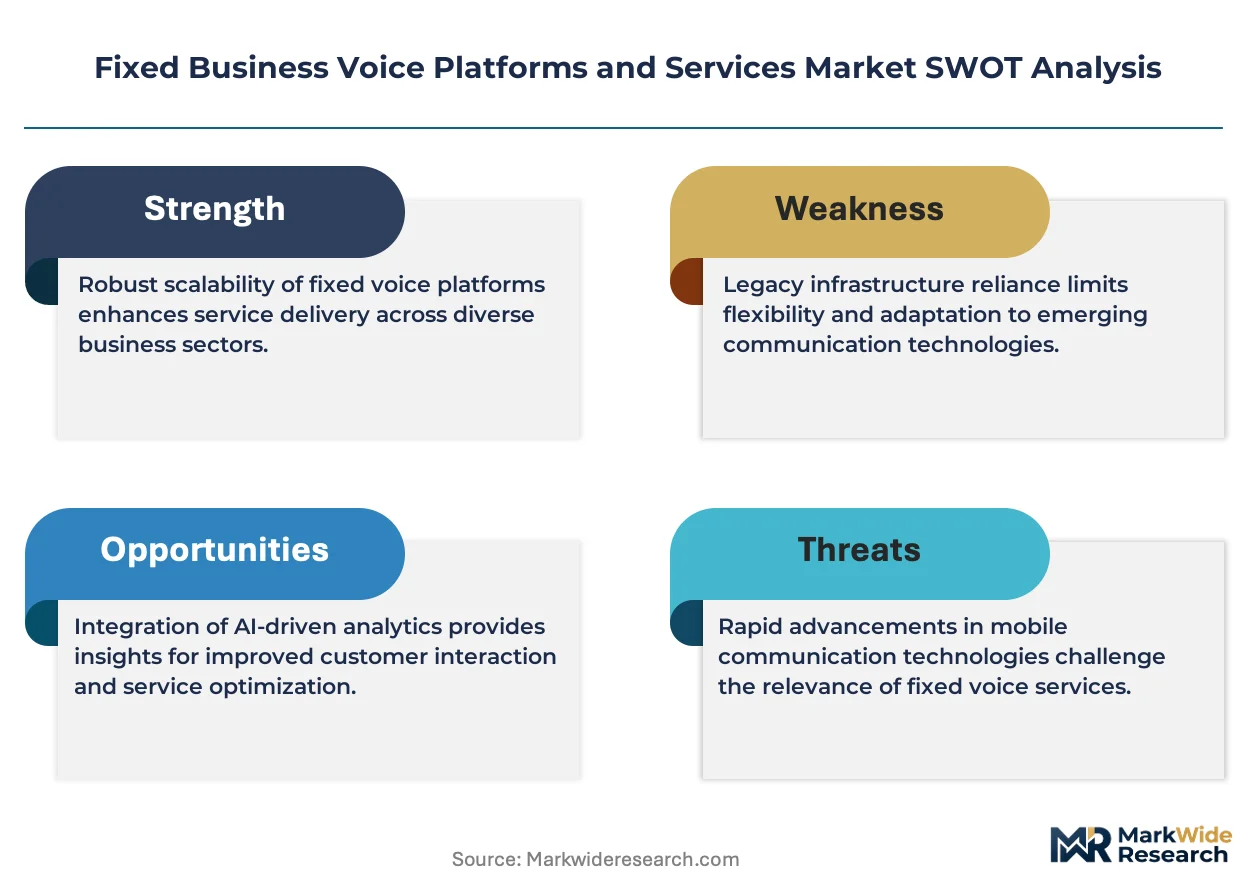
Indirect distribution through value-added resellers and managed service providers is reconfiguring how enterprises procure voice infrastructure. Cisco Systems leverages its channel partner ecosystem to sustain hardware attach rates for on-premises IP-PBX deployments. Mitel Networks Corporation specializes in hybrid cloud premises solutions, competing for mid-market customers seeking staged migration paths. RingCentral dominates the hosted segment, extending its platform through API-first integrations with workforce collaboration tools.
Fixed business voice platforms and services encompass the hardware, software, and managed offerings that enable circuit-switched and packet-based enterprise telephony, typically operating over T1/E1 PRI, SIP trunking, or dedicated Ethernet handoffs with sub-150ms latency requirements for toll-quality voice. These systems serve commercial organizations requiring reliable person-to-person communication, emergency calling compliance, and integration with customer relationship management workflows. Cloud telephony deployments are capturing the fastest expansion as enterprises shed capital-intensive PBX ownership, while on-premises IP-PBX installations retain margin concentration in regulated verticals with strict data sovereignty requirements. Session Initiation Protocol trunking occupies a transitional growth position, bridging legacy TDM investments toward fully hosted consumption models across finance and government end user industries.
The Federal Communications Commission enforces STIR/SHAKEN caller ID authentication rules that compel voice service providers to upgrade signaling infrastructure, directly shaping enterprise platform procurement timelines. E911 regulations from the FCC and state public utility commissions mandate granular location reporting for multi-line telephone systems, forcing platform vendors to embed advanced emergency routing capabilities. Enterprises must evaluate whether hybrid architectures or full cloud migration better satisfy emerging compliance burdens while containing total cost of ownership.
Market Dynamics
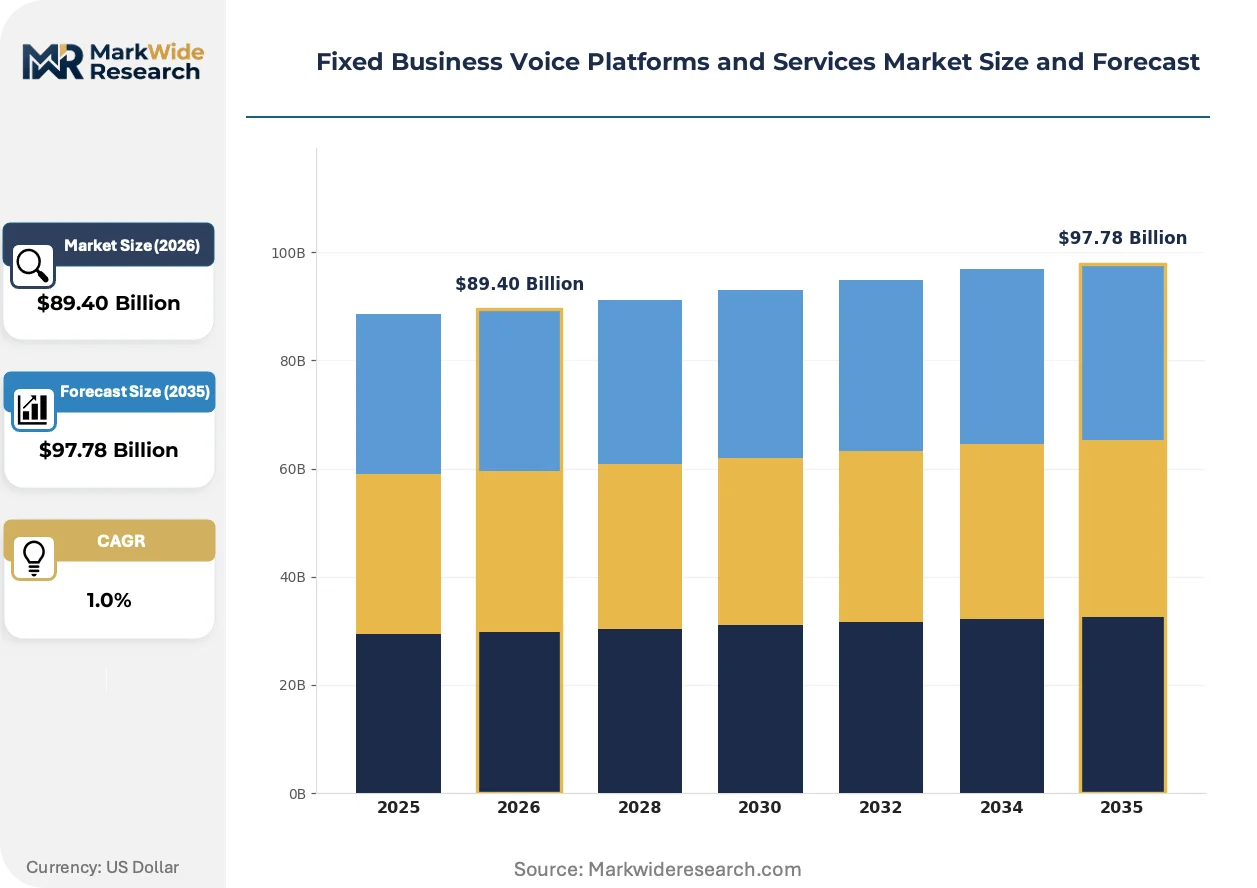
Enterprise voice infrastructure is undergoing a forced transition as FCC mandates around caller authentication and emergency location reporting compel platform refreshes, while cloud consumption models simultaneously erode the economic rationale for capital-intensive on-premises ownership.
Growth Catalysts
- FCC STIR/SHAKEN Mandates:The Federal Communications Commission requires voice service providers to implement cryptographic caller ID authentication, accelerating enterprise platform replacement cycles.
- Finance Sector Migration:Financial services firms are abandoning legacy TDM infrastructure for packet-based systems to enable CRM integration and real-time analytics.
- SIP Trunking Bridge Technology:Session Initiation Protocol trunking offers staged migration paths for mid-market enterprises unwilling to commit immediately to full cloud deployment.
Market Restraints
- Copper Loop Retirement Costs:Incumbent local exchange carriers face substantial capital burdens to decommission aging TDM access infrastructure while maintaining service continuity.
- Hybrid Architecture Complexity:Enterprises pursuing staged cloud migrations encounter integration friction between legacy PBX systems and hosted platforms.
- Specialized Technician Scarcity:The shrinking pool of engineers proficient in both legacy TDM signaling and modern IP protocols constrains deployment velocity.
Strategic Opportunities
- API-First Platform Extensions:Voice platforms integrating with workforce collaboration tools through open APIs capture expanding enterprise software budgets.
- Regulated Vertical Cloud Capture:Healthcare and government entities with strict data sovereignty requirements represent underpenetrated hosted voice demand.
- Managed Service Provider Channel:Value-added resellers are consolidating procurement influence, creating new paths to mid-market customers.
Industry Challenges
- E911 Location Granularity Compliance:Multi-line telephone systems must now report precise dispatchable location data, requiring expensive platform upgrades or replacements.
- Legacy System Integration Burden:Enterprises maintaining hybrid environments face ongoing operational complexity from parallel TDM and IP management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Business Voice Platforms and Services Market |
| Market Size in 2026 | $89.40 Billion |
| Market Size in 2035 | $97.78 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: IP-PBX, Hosted PBX, Unified Communications, Cloud Telephony, Session Initiation Protocol Service Type: Voice Calling, Call Recording, Interactive Voice Response, Voicemail, Call Analytics, Conferencing Deployment Mode: On-Premises, Hosted, Cloud-Based, Hybrid End User Industry: Telecommunications, Finance, Education, Government, Manufacturing, Legal |
| Companies Covered | Cisco Systems, Inc., Avaya Inc., Mitel Networks Corporation, NEC Corporation, Microsoft Corporation, RingCentral Inc., Vonage Holdings Corp., 8x8, Inc., AT&T Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Business Voice Platforms and Services Market Shifts & Advancements
Voice platform architecture is converging with broader enterprise software stacks, as embedded communications capabilities displace standalone telephony systems and regulatory compliance becomes a primary design constraint rather than afterthought.
Enterprise telephony infrastructure is migrating from circuit-switched TDM architectures to packet-based IP systems. Large financial institutions and healthcare networks are driving this transition to enable unified communications integration. The technology shift is compressing hardware refresh cycles while expanding addressable market for software-centric vendors.
STIR/SHAKEN caller ID authentication rules from the Federal Communications Commission mandate cryptographic verification of calling party identity. Voice service providers must upgrade signaling infrastructure or face enforcement action. Mid-market enterprises are accelerating procurement timelines to ensure compliance before regulatory deadlines.
Enterprise buyers are consolidating voice procurement through managed service providers rather than direct carrier relationships. Channel partners are capturing margin previously retained by incumbent local exchange carriers. This pattern is most pronounced in the United States, where value-added resellers have built specialized practices around Cisco and Mitel deployments.
Fixed Business Voice Platforms and Services Market Segmentation
Platform refresh cycles vary dramatically across voice infrastructure categories, with compliance-driven replacements accelerating some segments while capital constraints prolong others. Understanding these temporal patterns helps vendors align R&D investment with revenue timing and helps buyers negotiate from position of replacement urgency or patience.
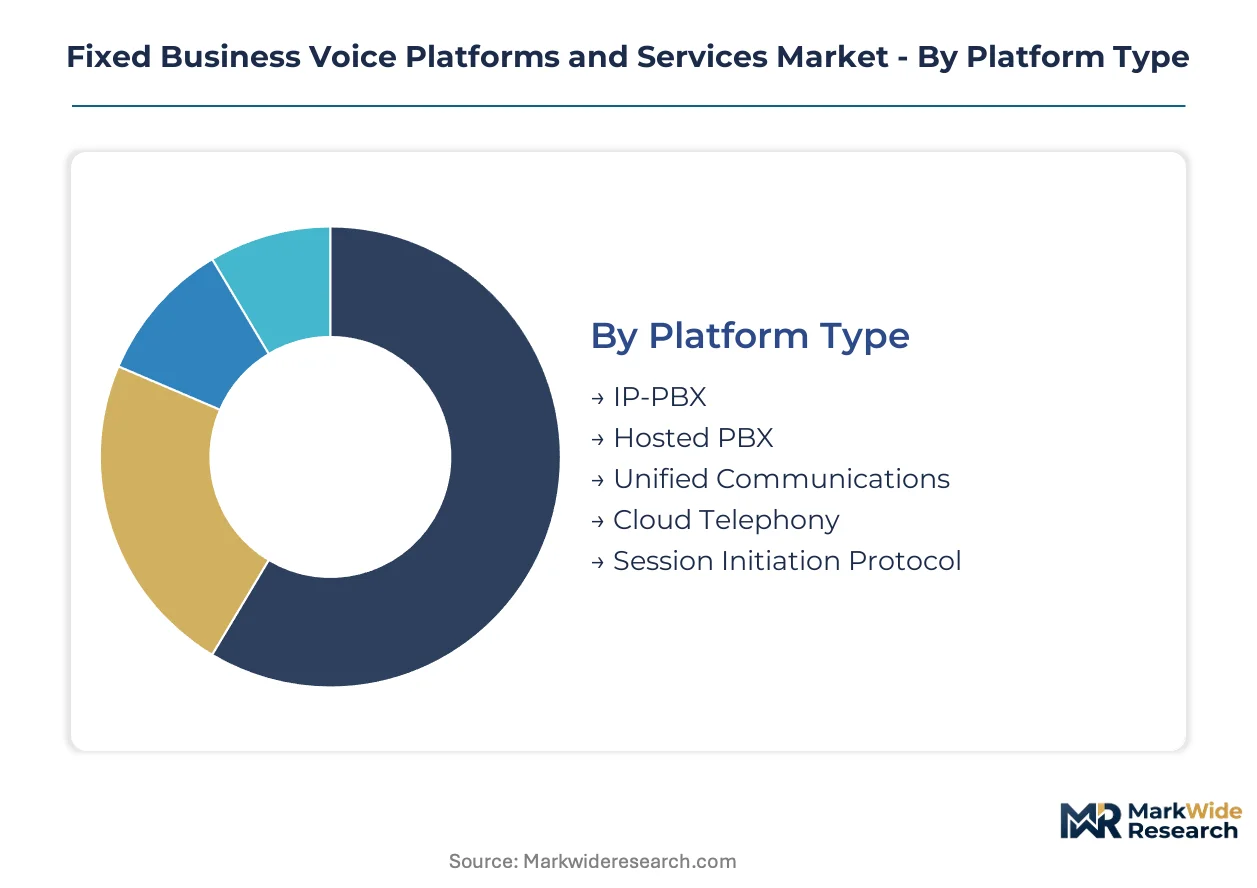
Platform Type:
Replacement velocity diverges sharply: premises hardware operates on 7-10 year depreciation schedules, while cloud subscriptions turn over in 1-3 year commitment cycles.
- IP-PBX:Packet-based private branch exchange systems replace legacy TDM installations using SIP trunking backhaul. Finance and legal verticals in the United States concentrate demand here, driven by FCC STIR/SHAKEN compliance deadlines that force authentication-capable signaling infrastructure.
- Hosted PBX:Third-party managed platforms delivered over dedicated circuits eliminate capital ownership burdens. Mid-market enterprises across manufacturing and education sectors favor this model where IT staffing scarcity constrains on-premises management.
- Unified Communications:Integrated voice, video, and messaging stacks with presence awareness and calendar integration.
- Cloud Telephony:Fully virtualized voice services with API programmability and consumption-based pricing.
- Session Initiation Protocol:Signaling protocol enabling VoIP session establishment, modification, and termination across heterogeneous networks.
IP-PBX dominates installed base. Cloud Telephony is where expansion concentrates.
Service Type:
Margin structure separates commoditized transport from value-added applications with software-like gross profiles.
- Voice Calling:Core person-to-person audio communication with toll-quality latency requirements below 150 milliseconds. Government agencies in the United States sustain demand for circuit-switched reliability where packet loss tolerance approaches zero.
- Call Recording:Regulatory-mandated capture and archival of voice interactions with search and retrieval capabilities. Financial services firms concentrate procurement here, compelled by SEC and FINRA retention rules alongside internal quality assurance workflows.
- Interactive Voice Response:Automated menu systems routing callers through keypad or speech inputs.
- Voicemail:Store-and-forward messaging with notification integration to email and mobile applications.
- Call Analytics:Speech-to-text transcription, sentiment analysis, and operational dashboards.
- Conferencing:Multi-party audio bridges with moderator controls and recording options.
Voice Calling dominates installed base. Call Analytics is where expansion concentrates.
Deployment Mode:
Capital intensity and operational control trade off across options, with hybrid architectures capturing complexity premiums from enterprises unable to commit fully either direction.
- On-Premises:Customer-owned hardware residing in enterprise data centers with direct physical access. Telecommunications carriers and government entities in the United States favor this mode where data sovereignty requirements and emergency calling liability demand local control.
- Hosted:Single-tenant infrastructure operated by service providers in dedicated facilities. Legal and manufacturing verticals concentrate here, seeking compliance documentation without assuming full operational burden.
- Cloud-Based:Multi-tenant platforms with geographic redundancy and automatic software updates.
- Hybrid:Mixed environments preserving legacy TDM investments while selectively migrating traffic to IP.
On-Premises dominates installed base. Cloud-Based is where expansion concentrates.
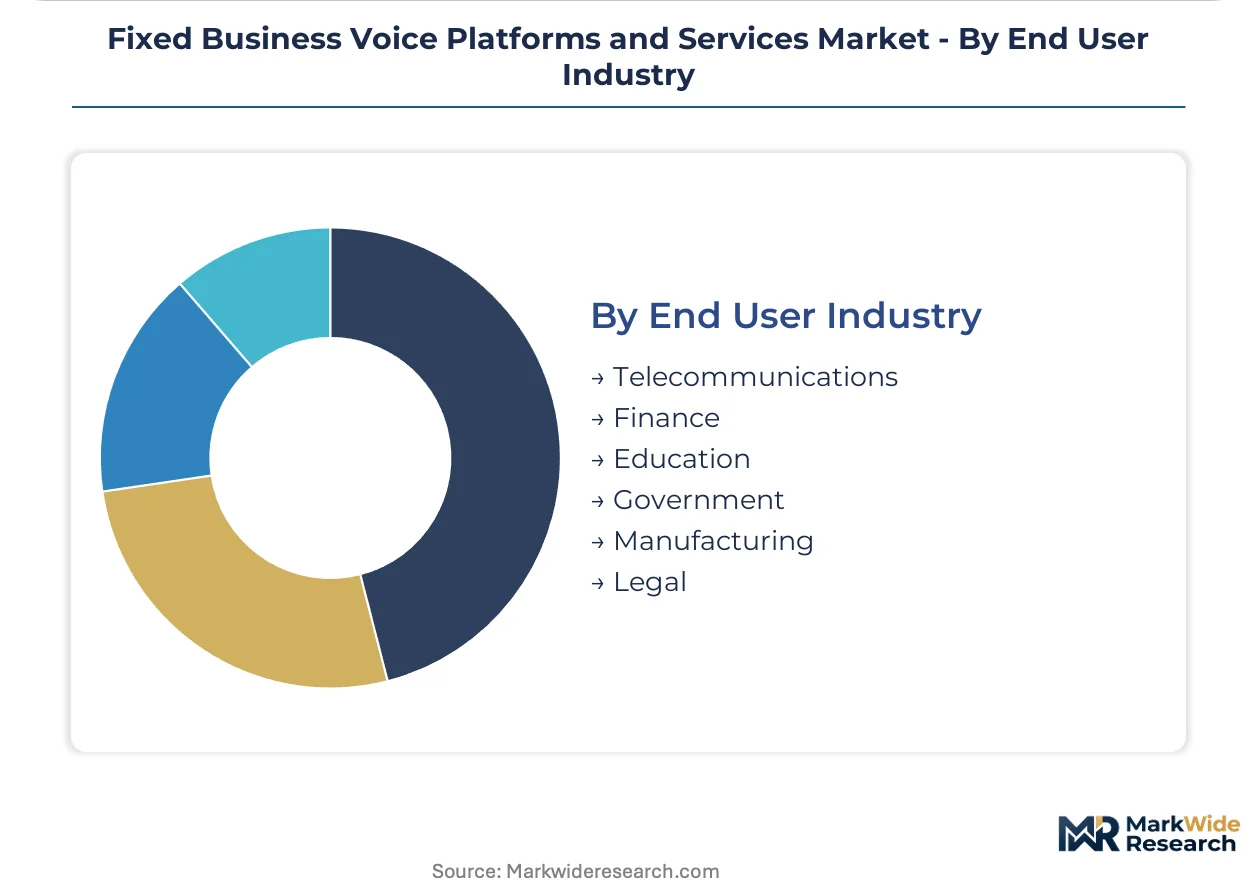
End User Industry:
Regulatory exposure and communication criticality shape procurement sophistication and price elasticity across verticals.
- Telecommunications:Service providers themselves requiring carrier-grade voice infrastructure for resale and interconnection. United States-based competitive local exchange carriers and wireless operators concentrate demand here, driven by FCC universal service and numbering administration obligations.
- Finance:Banks, insurers, and securities firms with strict record-keeping and authentication requirements. This vertical sustains premium pricing for compliant platforms, with STIR/SHAKEN implementation timelines forcing accelerated procurement cycles.
- Education:K-12 districts and higher education institutions with seasonal usage patterns and grant-funded capital constraints.
- Government:Federal, state, and municipal agencies with emergency calling mandates and procurement transparency rules.
- Manufacturing:Industrial facilities requiring plant-floor communications and integration with operational technology systems.
- Legal:Law firms and court systems with client confidentiality requirements and billing precision needs.
Telecommunications dominates installed base. Finance is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where carrier-grade IP trunking commands premium rates, while European procurement cycles stretch longer under fragmented national regulatory regimes. The United States sustains the highest per-seat voice platform expenditure globally. Emerging markets in Asia-Pacific compress margins through aggressive cloud-native competition.
United States
Financial services firms in New York and Chicago drive demand for STIR/SHAKEN-compliant platforms with embedded call recording. FCC mandates around caller authentication and E911 location granularity force accelerated replacement cycles. Dallas-Fort Worth anchors managed SIP service provider consolidation, where value-added resellers capture procurement influence from incumbent carriers.
Germany
Industrial manufacturers in Bavaria and Baden-Württemberg sustain on-premises IP-PBX demand for plant-floor integration with operational technology systems. Germany's national telecommunications regulator enforces strict data sovereignty requirements that slow cloud migration in regulated verticals. Frankfurt's financial district concentrates hybrid deployment adoption, balancing legacy TDM investments with selective IP migration.
United Kingdom
Legal services firms in London and Edinburgh prioritize call recording platforms with granular search and retrieval for billing precision. The Financial Conduct Authority and Information Commissioner's Office impose overlapping compliance burdens on voice data retention. Manchester's technology corridor hosts emerging managed service providers specializing in mid-market hosted PBX transitions.
Japan
Enterprise buyers in Tokyo and Osaka favor single-tenant hosted deployments over multi-tenant cloud platforms due to reliability expectations. METI guidelines on critical infrastructure protection shape procurement specifications for financial and telecommunications sectors. Osaka's manufacturing belt sustains demand for premises-based systems with integration into legacy operational technology environments.
India
BPO and IT services firms in Bangalore and Hyderabad drive consumption of cloud telephony with API programmability for workforce management integration. TRAI regulations on interconnection and quality of service create compliance complexity for multinational platform deployments. Mumbai's financial district concentrates hybrid architecture adoption as banks navigate data localization requirements alongside cloud efficiency demands.
Fixed Business Voice Platforms and Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying signaling protocols and session border controllers. The vendor base organizes around three strategic archetypes: legacy hardware incumbents defending installed base through hybrid cloud bridges, pure-play cloud natives capturing greenfield mid-market demand, and carrier-affiliated providers bundling voice with connectivity. Dominant competitive moves include channel partner consolidation among value-added resellers and API-first platform extensions embedding voice into workforce collaboration stacks.
Within the legacy-to-cloud transition archetype, Cisco Systems, Mitel Networks Corporation, and RingCentral occupy distinct positioning. Cisco Systems exemplifies the hardware-anchored integrator leveraging extensive channel relationships to sustain on-premises attach rates. Mitel Networks Corporation represents the hybrid specialization path targeting staged migration scenarios. RingCentral anchors the cloud-native tier, extending platform reach through integration marketplaces rather than direct infrastructure ownership.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Avaya Inc. |
| Mitel Networks Corporation |
| NEC Corporation |
| Microsoft Corporation |
| RingCentral Inc. |
| Vonage Holdings Corp. |
| 8x8, Inc. |
| AT&T Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in Asian electronics manufacturing is compressing margins for session border controllers and IP-PBX hardware, forcing suppliers to absorb input cost volatility while carriers negotiate shorter contract terms. This utilization squeeze simultaneously erodes pricing power for standardized SIP trunking services and accelerates consolidation among value-added resellers seeking volume discounts.
Pricing Analysis
The customization-premium spread separates configured-to-order on-premises IP-PBX deployments from standardized hosted PBX subscriptions. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by SLAs guaranteeing sub-150ms latency and geographic redundancy. Pricing pressure stems from cloud-native competitors offering consumption-based models that undercut capital-intensive ownership. Mid-market enterprises exhibit highest price sensitivity, while financial services firms absorb premiums for STIR/SHAKEN-compliant authentication infrastructure.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Jabil, and Flex holding capacity for enterprise voice hardware assembly in China, Mexico, and Vietnam. Semiconductor components for DSPs and voice processing chipsets draw from Taiwan and South Korea, while copper and fiber optic cabling feed from domestic U.S. and Chinese suppliers. Single-source vulnerability concentrates in specialized voice codec ASICs. Distribution runs through carrier-direct channels and value-added reseller networks with regional stocking points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a capital expenditure trough as FCC-mandated platform refreshes synchronize replacement cycles across financial services and government verticals.
For Market Incumbents: Insulate installed base revenue by embedding API-first integrations with workforce collaboration platforms before cloud-native competitors capture attach rates. Accelerate certification investment for E911 location granularity compliance to lock in government procurement. Channel control through exclusive value-added reseller agreements defends against direct-to-enterprise SaaS disintermediation.
For New Entrants and Emerging Players: Build out managed service provider partnerships as the most penetrable route to mid-market customers bypassing incumbent carrier relationships. Target healthcare verticals with strict data sovereignty requirements where hybrid cloud solutions address unmet compliance needs. Lead with consumption-based pricing and rapid deployment timelines to exploit IT staffing scarcity at prospective accounts.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud telephony providers with API marketplaces and integration ecosystems. Long-term viability favors vendors capturing regulatory-driven replacement cycles with embedded compliance features. Acquisition targets should demonstrate STIR/SHAKEN implementation traction and E911 routing certification. Watch for inflection in carrier-grade IP trunking contract renewals as indicator of platform refresh velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Extension | RingCentral's integration marketplace embeds voice into Salesforce and Microsoft Teams workflows. |
| Hybrid Cloud Bridge Deployment | Mitel Networks Corporation captures staged migration demand from TDM-retaining manufacturing clients. |
| Channel Partner Consolidation | Cisco Systems leverages 10,000+ reseller relationships to sustain on-premises hardware attach rates. |
| Regulatory Compliance Certification | STIR/SHAKEN attestation capabilities differentiate platforms for FCC-mandated financial services procurement. |
| Managed Service Provider Acquisition | Consolidation among value-added resellers redirects procurement influence from incumbent local exchange carriers. |
Research Methodology
A spread of perspectives from voice platform engineering directors, carrier procurement officers, value-added reseller principals, and FCC regulatory affairs specialists converged on the working assumptions. Primary interviews with enterprise IT decision-makers at financial services and healthcare organizations were cross-validated against secondary sources including FCC rulemaking dockets, SEC 10-K filings of public voice platform vendors, and TRAI quality of service reports. Bottom-up sizing of SIP trunking ports and cloud telephony seats was triangulated against top-down carrier revenue disclosures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling replacement cycles for premises hardware against greenfield cloud adoption curves. Segmentation dimensions included platform type, deployment mode, end-user industry vertical, and geographic regulatory cluster. CAGRs were derived from installed base turnover rates and compliance-driven procurement acceleration. Industry-specific inputs incorporated FCC STIR/SHAKEN implementation timelines and E911 location granularity mandate deadlines.
Stress conditions across copper loop retirement cost trajectories, hybrid architecture integration failure rates, and specialized technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and enterprise cloud migration appetite. Quarterly review of carrier IP trunking contract renewal volumes and value-added reseller consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Asia-Pacific Postal Services Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Web Conferencing Market
Communication Services
Latin America Postal Service Market
Communication Services
Meeting Solutions Market
Communication Services
Broadcasting Solutions Market
Communication Services
Cloud Communication Platform Market
Communication Services
Postal Services Market
Communication Services
Outbound Telemarketing Market
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Speech to Speech Translation Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Global Critical Communication Market
Communication Services
Message Handling Systems Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Push-To-Talk Market