
 Slovenia E-Commerce Market | 2026-2036
Slovenia E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Slovenia E-Commerce Market Analytics
Subscription bundling of electronics with installation services is pivoting how Slovenian households evaluate online purchases. Mimovrste d.o.o. leverages its logistics network to anchor next-day delivery promises across the country. Mercator d.d. competes through click-and-collect integration with its physical store footprint. Petrol d.d. extends its fuel-station network into parcel pickup nodes, occupying a unique last-mile position.
Slovenia E-Commerce encompasses digitally mediated transactions for goods and services executed through web-based platforms and mobile applications, relying on encrypted payment gateways and automated inventory synchronization to complete commercial exchanges. Fashion and electronics command the largest transaction volumes, while social commerce represents the fastest-expanding sales channel as influencer-driven purchasing shortens consumer decision cycles. Mobile apps capture disproportionate engagement among Gen Z buyers, whereas bank transfer and credit card payment methods dominate transaction settlement due to established trust in domestic banking infrastructure.
The EU Digital Services Act and GDPR compliance requirements enforced by Slovenian data protection authorities shape platform operational costs and seller onboarding protocols. REACH and RoHS frameworks indirectly constrain electronics assortment available through domestic e-commerce channels by mandating substance declarations and circularity documentation. Stakeholders must monitor how forthcoming EU AI Act provisions governing recommendation algorithms will alter product discovery economics and customer acquisition costs.
Market Dynamics
The EU Digital Services Act is compressing platform accountability timelines and forcing domestic sellers to restructure data governance protocols ahead of enforcement deadlines.
Growth Catalysts
- Last-mile infrastructure densification:Fuel-station networks and urban retail footprints are converting into parcel pickup nodes, reducing delivery friction for time-sensitive categories.
- GDPR-compliant data portability:Streamlined consumer data transfer rights are lowering switching costs between competing platforms and accelerating merchant multi-homing.
- Mobile-first Gen Z engagement:Native app experiences with embedded social proof mechanisms are capturing disproportionate wallet share among first-time digital buyers.
Market Restraints
- REACH substance documentation:Electronics and fashion imports face mandatory circularity declarations that extend supplier onboarding cycles and constrain assortment breadth.
- Ljubljana logistics concentration:Fulfillment capacity clusters within a 50-kilometer urban corridor, creating single-point vulnerability for nationwide delivery promises.
- Bank transfer settlement rigidity:Domestic payment infrastructure lacks real-time interoperability with pan-European instant payment schemes, delaying cross-border merchant expansion.
Strategic Opportunities
- Maribor and Celje corridor penetration:Secondary urban centers outside the capital region show elevated digital commerce adoption velocity with underdeveloped local fulfillment options.
- Social commerce influencer infrastructure:Short-form video platforms are compressing consumer decision cycles and enabling direct-to-consumer brand building without platform intermediation.
- EU AI Act algorithmic transparency:Upcoming recommendation engine disclosure requirements will favor merchants with proprietary customer data and first-party analytics capabilities.
Industry Challenges
- Legacy ERP integration friction:Small merchant inventory systems lack automated synchronization with marketplace APIs, causing stock-out penalties and listing suspensions.
- Data protection officer scarcity:GDPR Article 37 compliance requires specialized legal-technical hybrid expertise that commands premium compensation in a shallow talent pool.
- Cross-border VAT complexity:One-Stop Shop regime participation demands continuous transaction classification accuracy that many domestic sellers lack operational bandwidth to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovenia E-Commerce Market |
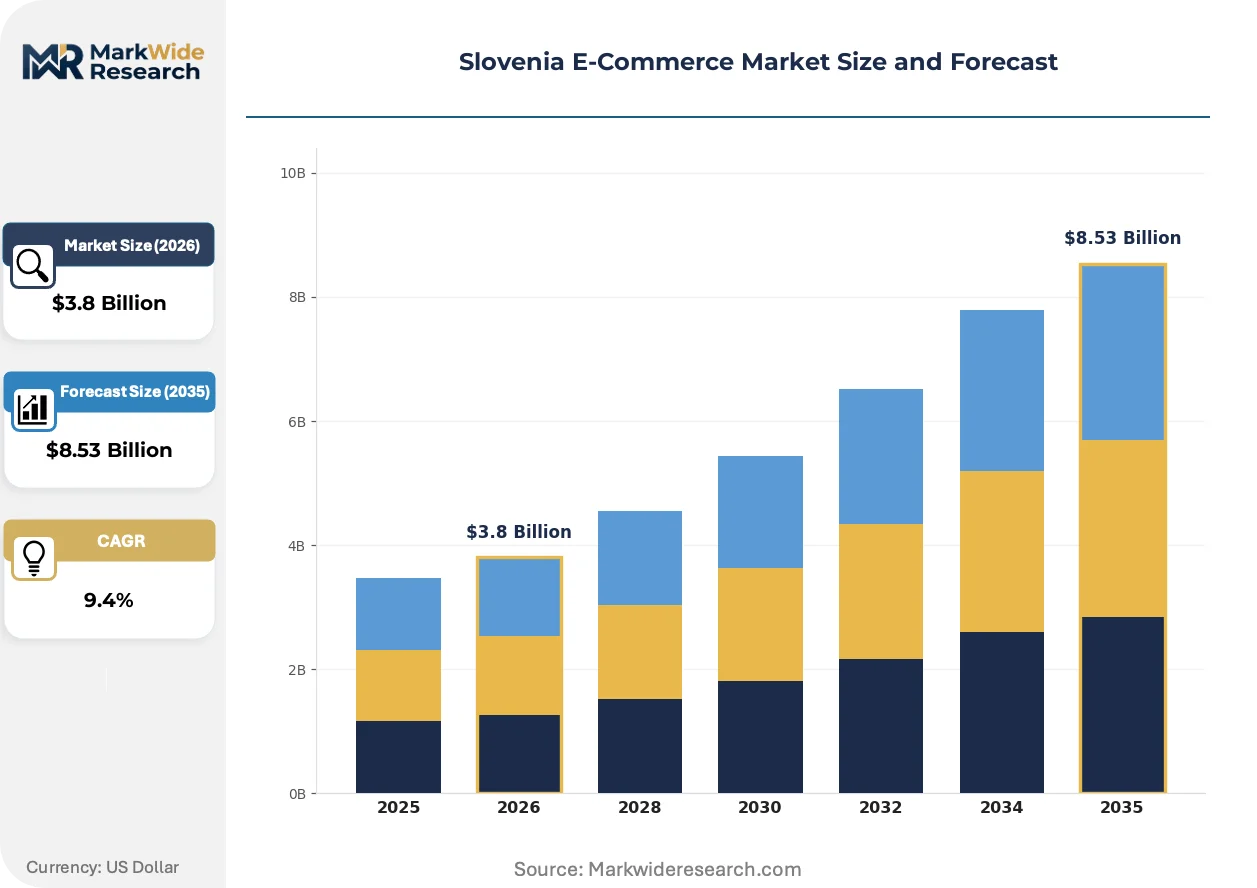
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Electronics, Home Appliances, Beauty Products Sales Channel: Online Marketplaces, Direct-to-Consumer, Mobile Apps, Social Commerce Customer Type: Millennials, Gen Z, Small Business Owners, Families Payment Method: Credit Card, PayPal, Bank Transfer, Cash on Delivery |
| Companies Covered | Mimovrste d.o.o., Merkur Trgovina d.o.o., Mercator d.d., Big Bang d.o.o., Petrol d.d., Lekarna Nove Poljane, Spar Slovenija d.o.o., Tuš Holding d.o.o., Harvey Norman Trading d.o.o., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovenia E-Commerce Market Evolving Landscape
Platform architecture and consumer interface design are converging around embedded service bundling and algorithmic personalization that compresses traditional purchase funnels.
Headless commerce architecture is modularizing storefront presentation layers from back-end order management systems. Mid-sized Slovenian merchants are adopting composable stacks to enable rapid channel experimentation without core platform migration. This technology is modularizing the traditional monolithic platform dependency that previously locked sellers into single-provider ecosystems.
The EU AI Act's risk-based classification system for automated decision-making will impose documentation burdens on product recommendation engines. E-commerce platforms must maintain algorithmic audit trails and human oversight protocols for high-risk personalization systems. Fashion and electronics marketplaces face the steepest compliance ramps given their reliance on behavioral targeting for cross-selling.
Subscription bundling of durable goods with installation and maintenance services is displacing transactional single-purchase models. Slovenian households are evaluating total cost of ownership rather than upfront price, particularly for home electronics categories. This pattern concentrates in Ljubljana's higher-income postal codes where service reliability outweighs price sensitivity in vendor selection.
Slovenia E-Commerce Market Segmentation
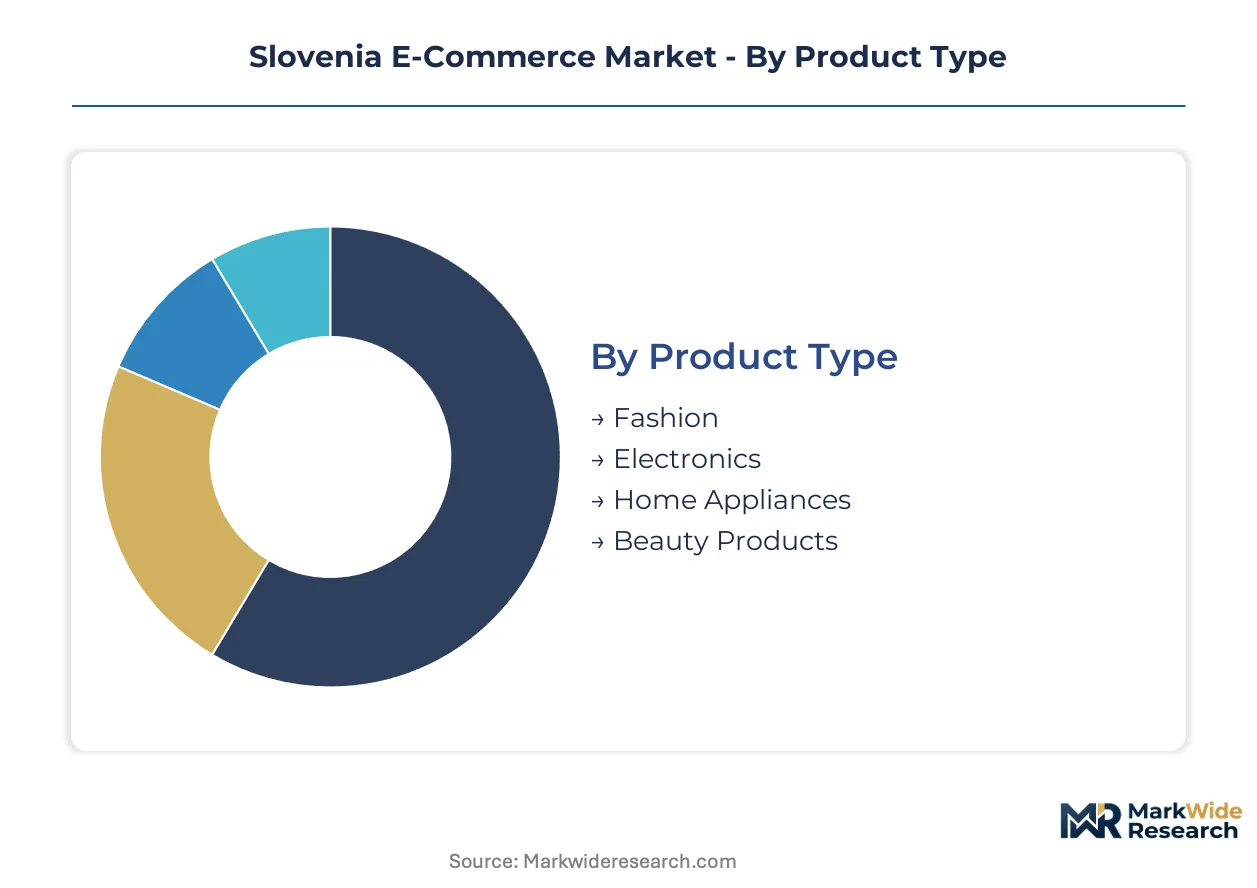
E-commerce segmentation in Slovenia reveals how digital procurement patterns fragment across product categories, channel preferences, and generational divides. Understanding these partitions exposes where fulfillment infrastructure investments yield disproportionate returns and which customer cohorts drive margin expansion.
Product Type:
Upgrade cycles for durable goods and discretionary refresh rates for consumables create divergent inventory velocity profiles across Slovenia's digital retail landscape.
- Fashion:Seasonal turnover demands rapid logistics synchronization with Ljubljana's urban corridor warehouses. Demand clusters among Gen Z buyers seeking influencer-curated assortments, with returns processing consuming 15-20% of operational overhead for domestic merchants.
- Electronics:High-value transactions require encrypted payment gateways and extended warranty integration that domestic banking infrastructure supports unevenly. REACH substance documentation mandates from ECHA constrain cross-border supplier onboarding, compressing available SKUs from non-EU sources.
- Home Appliances:Installation service bundling is displacing transactional purchase models in Ljubljana's higher-income postal codes.
- Beauty Products:Subscription replenishment models capture recurring revenue from millennial households in secondary urban centers.
Volume placements concentrate in Fashion; the faster expansion belongs to Electronics.
Sales Channel:
Channel economics in Slovenia stratify sharply between platform-dependent merchants and those building proprietary customer data assets.
- Online Marketplaces:Mercator d.d. and Mimovrste d.o.o. anchor this tier through fulfillment density and next-day delivery promises. GDPR-compliant data portability rights under EU regulation accelerate merchant multi-homing, eroding platform lock-in effects.
- Mobile Apps:Native experiences with embedded social proof mechanisms capture disproportionate engagement among first-time digital buyers. Gen Z wallet share concentrates here, with push notification-driven repurchase rates exceeding mobile web benchmarks.
- Direct-to-Consumer:Headless commerce architecture enables rapid channel experimentation without core platform migration for mid-sized Slovenian merchants.
- Social Commerce:Short-form video platforms compress consumer decision cycles, enabling direct-to-consumer brand building without platform intermediation.
Transaction value concentrates in Online Marketplaces; the steepest adoption curve belongs to Social Commerce.
Customer Type:
Generational digital fluency and business procurement automation create distinct service-level requirements across Slovenia's e-commerce demand base.
- Gen Z:Mobile-first engagement patterns prioritize native app experiences with influencer-validated product discovery. This cohort exhibits lowest loyalty to single platforms, exploiting GDPR data portability to switch merchants frictionlessly.
- Small Business Owners:Digital procurement channel expansion accelerates as EU Digital Services Act accountability rules reshape B2B platform relationships. Inventory synchronization demands with legacy ERP systems create onboarding friction for marketplace participation.
- Millennials:Subscription bundling evaluation criteria emphasize total cost of ownership over upfront price for household electronics.
- Families:Click-and-collect integration with physical retail footprints reduces delivery friction for time-sensitive categories.
Order frequency concentrates in Gen Z; the expanding wallet share belongs to Small Business Owners.
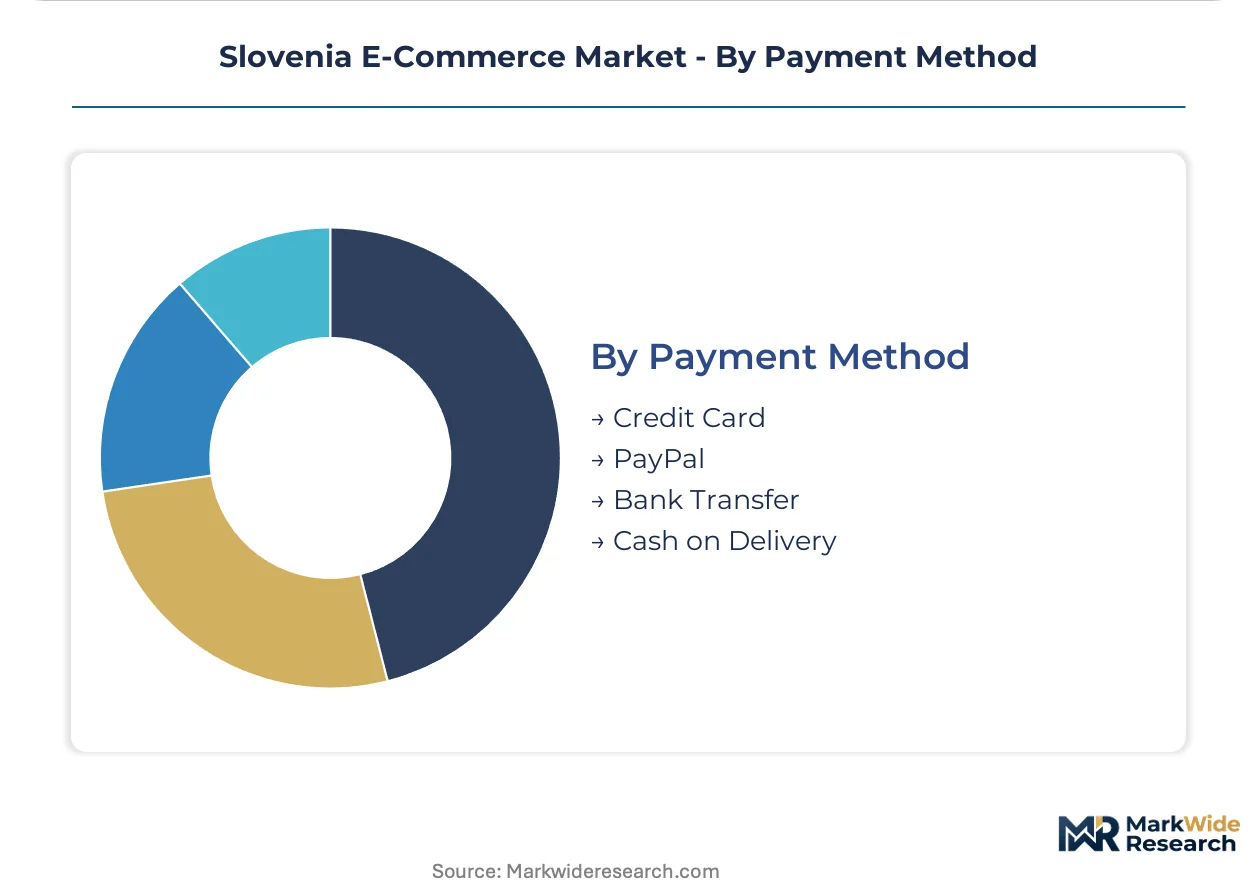
Payment Method:
Settlement infrastructure trust patterns in Slovenia reflect domestic banking system penetration and cross-border interoperability limitations.
- Bank Transfer:Established trust in domestic banking infrastructure sustains this method's dominance, though real-time interoperability with pan-European instant payment schemes remains incomplete. Settlement rigidity delays cross-border merchant expansion for Slovenian sellers.
- Credit Card:Encrypted gateway integration supports high-value electronics transactions, with chargeback protection influencing merchant preference for this channel.
- PayPal:Cross-border purchase facilitation appeals to consumers sourcing from EU marketplaces outside Slovenia.
- Cash on Delivery:Persistent preference in rural postal codes outside the Ljubljana logistics corridor reflects last-mile reliability concerns.
Transaction volume concentrates in Bank Transfer; the shifting preference trajectory belongs to Credit Card.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Slovenia's e-commerce production concentrates in Ljubljana's logistics corridor while consumption spreads across secondary urban centers. This geographic mismatch creates fulfillment bottlenecks outside the capital region. Regional development strategies aim to redistribute warehouse capacity toward Maribor and Celje.
Ljubljana Urban Corridor
Same-day delivery promises and premium service bundling drive warehouse investment in Ljubljana and its surrounding municipalities. The Slovenian Competition Protection Agency monitors platform concentration effects in this zone. Fulfillment centers cluster along the A1 motorway corridor connecting Ljubljana to Kranj and Novo Mesto.
Maribor
Digital commerce adoption velocity exceeds national averages in Slovenia's second-largest city. EU cohesion fund allocations support logistics infrastructure modernization in the Podravska statistical region. Regional distribution hubs are emerging near the Maribor Edvard Rusjan Airport to capture cross-border fulfillment traffic from Austria and Hungary.
Celje
Mid-sized merchant fulfillment demand outpaces available warehouse capacity in this Savinja statistical region anchor. The Slovenian Digital Coalition promotes SME digitalization programs targeting family-owned retailers. Industrial zones along the Celje-Ljubljana rail corridor attract automated sorting facility investments.
Koper
Port-adjacent logistics leverage the Adriatic gateway for cross-border e-commerce imports from Asia. Slovenian customs administration digitalization reduces clearance friction for containerized consumer goods. Free zone warehousing near the Luka Koper terminal serves Italian and Austrian marketplace sellers.
Novo Mesto
Automotive supplier networks in this Dolenjska region hub generate B2B procurement platform demand. The Slovenian Enterprise Fund supports supply chain digitization grants for manufacturing SMEs. Last-mile partnerships with Ljubljana-based platforms extend delivery coverage to rural Dolenjska municipalities.
Slovenia E-Commerce Market Competitive Landscape
The competitive structure tilts toward diversified retail conglomerates with physical footprint leverage. Marketplace density remains moderate with clear tiering between national chains and specialized vertical platforms. Two strategic archetypes dominate: integrated retail-logistics hybrids and fuel-station network parcel operators. Consolidation pressure manifests through click-and-collect integration and fulfillment network sharing agreements.
Among Ljubljana-based integrated retailers, Mimovrste d.o.o., Mercator d.d., and Petrol d.d. occupy distinct competitive positions. Mimovrste d.o.o. exemplifies the pure-play digital marketplace archetype with fulfillment infrastructure as core capability. Mercator d.d. represents legacy retail transformation through grocery-logistics integration. Petrol d.d. anchors the alternative last-mile archetype by converting fuel-station networks into parcel pickup nodes.
| Leading Market Players |
|---|
| Mimovrste d.o.o. |
| Merkur Trgovina d.o.o. |
| Mercator d.d. |
| Big Bang d.o.o. |
| Petrol d.d. |
| Lekarna Nove Poljane |
| Spar Slovenija d.o.o. |
| Tuš Holding d.o.o. |
| Harvey Norman Trading d.o.o. |
| Others |
Value Network & Pricing Analysis
REACH substance documentation mandates from ECHA gate qualified supplier access for Slovenian electronics merchants while simultaneously filtering premium-tier pricing eligibility to those with compliant circularity credentials. This environmental compliance layer stratifies procurement costs and final pricing power across domestic e-commerce channels.
Pricing Analysis
Margin tightening in economy-tier electronics traces to REACH documentation burdens that extend supplier onboarding cycles and compress available SKUs from non-EU sources. Three-tier pricing structure across premium, standard, and economy levels separates installation-bundled offerings from transactional single-purchase models, with after-sales service reliability and certification grade driving differentiation. Pricing pressure intensifies in standard tiers as GDPR-compliant data portability accelerates merchant multi-homing and erodes platform lock-in effects. Small business owners exhibit highest price sensitivity, whereas Ljubljana households in higher-income postal codes prioritize total cost of ownership over upfront expenditure.
Supply Chain Analysis
Regional distribution centers cluster along the A1 motorway corridor connecting Ljubljana to Kranj and Novo Mesto, creating hub-and-spoke patterns that feed last-mile nodes. Fulfillment infrastructure draws from German logistics technology providers, Chinese consumer electronics manufacturing, and Italian fashion supplier networks. Semiconductor components, lithium-ion cells, and textile raw materials anchor import dependencies with exposure to single-source vulnerability from concentrated Asian production zones. Distribution runs through fuel-station parcel pickup networks and urban retail click-and-collect points that extend coverage beyond the capital logistics corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slovenian e-commerce sits at a technology-transition phase where headless commerce architecture displaces legacy monolithic platform dependencies that previously locked merchants into single-provider ecosystems.
For Market Incumbents: Anticipate algorithmic transparency mandates from the EU AI Act by building proprietary first-party analytics capabilities and human oversight protocols for recommendation engines. Consolidate fulfillment density through automated sorting facility investments along the Celje-Ljubljana rail corridor to defend against emerging logistics competitors. Channel control through exclusive installation service partnerships represents the critical defensive lever against pure-play digital entrants.
For New Entrants and Emerging Players: Social commerce influencer infrastructure offers the most penetrable entry vector, enabling direct-to-consumer brand building without platform intermediation fees. Secondary urban centers in the Maribor and Celje corridor show elevated digital commerce adoption velocity with underdeveloped local fulfillment options. A go-to-market angle anchored on GDPR-compliant data portability messaging accelerates merchant acquisition from legacy platforms.
For Investors and Strategic Acquirers: EU cohesion fund allocations for Podravska region logistics modernization are the leading indicator that Maribor-adjacent distribution assets will appreciate disproportionately. Mid-sized merchants with headless commerce stacks and composable architecture represent the optimal acquisition archetype for platform consolidation plays. Watch for data protection officer hiring velocity as the inflection signal for GDPR enforcement intensity and compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Headless Commerce Migration | Composable stacks enable rapid channel experimentation without core platform migration for mid-sized merchants. |
| Fuel-Station Parcel Network Expansion | Petrol d.d.'s last-mile nodes reduce delivery friction for time-sensitive categories outside Ljubljana corridor. |
| Social Commerce Platform Integration | Short-form video mechanisms compress consumer decision cycles and enable direct-to-consumer brand building. |
| Automated Sorting Facility Investment | Industrial zones along Celje-Ljubljana rail corridor attract fulfillment infrastructure to ease capital-region concentration. |
| GDPR Compliance Service Bundling | Data protection officer scarcity creates premium service opportunities for specialized legal-technical hybrid providers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews with logistics operations directors, e-commerce platform engineers, merchant category managers, and data protection compliance officers. Slovenian Competition Protection Agency platform concentration monitoring, ECHA substance documentation databases, and EU Digital Services Act implementation guidance provided regulatory context. Bottom-up merchant revenue aggregation and top-down consumer expenditure surveys underwent cross-validation triangulation.
Granularity-level modeling addressed product category, sales channel, generational cohort, and payment method dimensions across the analysis window, with additional segmentation by urban corridor postal code for fulfillment cost analysis. CAGRs derived from trend extrapolation of digital commerce penetration rates, logistics infrastructure investment flows, and mobile app engagement metrics. Forecast inputs incorporated EU AI Act implementation timelines and cohesion fund allocation schedules for regional logistics development.
Several conditions sit outside the modeled scope, including macroeconomic shocks to consumer discretionary spending, abrupt regulatory enforcement pattern shifts, and technological disruption from immersive commerce interfaces. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
North Macedonia E-Commerce Market
E-Commerce Solutions
Global Healthcare E-Commerce Market
E-Commerce Solutions
Russia Alcohol E-Commerce Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
E-Commerce Logistics Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
M-Commerce Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
Europe FMCG B2B E-Commerce Market
E-Commerce Solutions
E-Commerce Electronics Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
E-Commerce in Nigeria Market
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
Japan E-Commerce Market