
 Self-Service Market | 2026-2036
Self-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Service Market Outlook
Asian kiosk manufacturers is recalibrating production schedules to match the surge in airport and quick-service restaurant deployments. NCR Corporation leverages its software-hardware integration to sustain pricing power across North American grocery chains. Diebold Nixdorf anchors financial self-service networks through ATM-to-digital-branch transitions in European banking.
Self-service denotes automated systems enabling end-users to complete transactions, retrieve information, or access services without direct human assistance, typically integrating touch interfaces, payment terminals, and networked software operating at sub-second response thresholds. Kiosks dominate current installed value due to their physical durability and high-throughput design for retail and travel hubs. Cloud computing infrastructure is expanding fastest among technology segments, as edge-to-core architectures allow real-time inventory synchronization and remote fleet management across dispersed device networks.
FDA guidelines shape food-service kiosk sanitation standards in the United States, while the EU AI Act imposes risk-classification obligations on automated decision systems processing consumer data. GDPR data-processing requirements constrain how European self-service platforms handle biometric authentication and purchase history retention. Stakeholders must weigh compliance investment against localization complexity when selecting expansion markets for next-generation deployment.

Market Dynamics
Cloud-to-edge infrastructure is compressing response latencies below 200 milliseconds, forcing hardware vendors to redesign kiosk architectures around distributed computing nodes rather than centralized data centers. This shift is redistributing value capture toward software-layer providers and away from legacy equipment manufacturers.
Growth Catalysts
- Labor Cost Compression:Quick-service restaurant chains in the United States are replacing front-counter staff with integrated ordering kiosks to offset minimum wage escalations in California and New York.
- EU AI Act Compliance Deadlines:Automated decision systems deployed in European retail must implement transparent consent mechanisms by 2025, creating replacement demand for older opaque platforms.
- Contactless Payment Maturation:Near-field communication terminals embedded in transit hubs across Tokyo, London, and Singapore are normalizing tap-to-pay behaviors that self-service hardware exploits.
Market Restraints
- Semiconductor Supply Concentration:Touchscreen controller chips depend on foundry capacity concentrated in Taiwan, exposing kiosk production schedules to geopolitical disruption risk.
- GDPR Biometric Friction:Facial recognition authentication for age-verified purchases faces explicit consent requirements under European data protection law, limiting deployment velocity.
- Maintenance Labor Scarcity:Field service technicians capable of diagnosing edge-compute hardware failures command premium wages in Germany and Japan, elevating total cost of ownership.
Strategic Opportunities
- Indian Airport Modernization:The Airports Authority of India's capital expenditure program for tier-2 cities creates greenfield deployment potential for biometric boarding kiosks.
- Healthcare Triage Convergence:Self-service terminals integrating symptom-checking algorithms with appointment scheduling are penetrating outpatient clinics in South Korea and Australia.
- US Inflation Reduction Act Incentives:Energy-efficient equipment tax credits apply to solar-powered outdoor kiosks deployed in municipal transit networks.
Industry Challenges
- Edge-AI Talent Gap:Firmware engineers capable of optimizing neural network inference on resource-constrained kiosk processors remain scarce in European labor markets.
- Legacy POS Integration Complexity:Supermarket chains operating 1990s-era inventory databases require expensive middleware development to connect modern self-checkout systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Service Market |
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $112.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Kiosks, Online Platforms, Mobile Apps, Automated Checkouts End User: Retail Chains, Restaurants, Airports, Banks Technology: Artificial Intelligence, Cloud Computing, IoT, QR Code Application: Order Management, Customer Support, Payment Processing, Inventory Tracking |
| Companies Covered | NCR Corporation, Diebold Nixdorf, Toshiba Global Commerce Solutions, Verifone, Ingenico, KIOSK Information Systems, Fujitsu, Zebra Technologies, Advantech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Service Market Strategic Shifts
Generative interfaces are replacing static touchscreen menus with conversational agents that adapt to user intent in real time. This shift demands recalibration of hardware specifications, software architectures, and staff training protocols across deployment organizations.
Computer vision systems equipped with depth-sensing cameras are rewriting loss-prevention economics in unattended retail environments. Grocery chains in the United Kingdom and Netherlands are piloting shelf-scanning kiosks that eliminate barcode friction entirely. The technology is compressing checkout duration from minutes to seconds, forcing competitors to accelerate hardware refresh cycles or cede throughput advantage.
The EU AI Act's risk-classification framework is mandating algorithmic impact assessments for customer-facing automation processing biometric data. Vendors serving European markets must now maintain technical documentation and human oversight protocols that increase compliance overhead. Food-service kiosks employing age-estimation software in Germany and France face the strictest scrutiny, driving redesign of verification workflows toward explicit ID-scanning alternatives.
Airport operators are consolidating procurement around full-service concession contracts that bundle kiosk deployment with digital menu management and predictive maintenance. This model displaces traditional equipment purchase arrangements in favor of performance-guaranteed subscriptions. The shift is most advanced in Middle Eastern hub airports, where long-term concession agreements now specify uptime thresholds and passenger throughput guarantees rather than hardware specifications.
Self-Service Market Segmentation
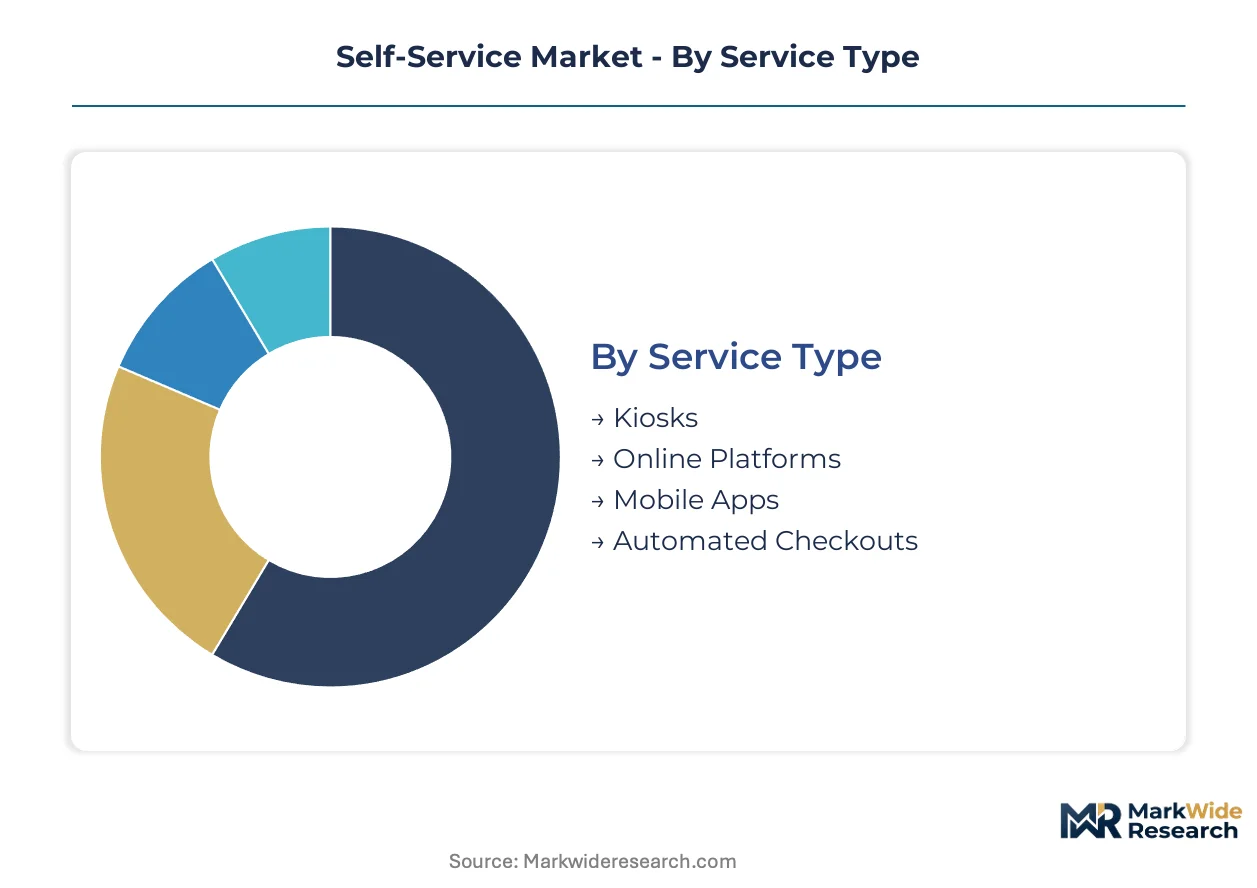
Self-service deployments fragment across hardware, software, and service layers, each carrying distinct capital requirements and operational constraints. Procurement decisions hinge on throughput demands, regulatory exposure, and legacy system compatibility rather than technology novelty alone.
Service Type:
Kiosks demand the heaviest upfront capital outlay due to physical fabrication, site preparation, and field maintenance infrastructure. Online platforms and mobile apps shift investment toward cloud infrastructure and continuous development cycles.
- Kiosks:Ruggedized terminals integrate touchscreens, payment modules, and edge-compute processors for sub-second response. Demand concentrates in North American grocery chains and Chinese unmanned convenience stores where labor cost compression justifies hardware expenditure. FDA sanitation guidelines govern food-service deployments in the United States.
- Automated Checkouts:Computer vision systems eliminate barcode scanning through shelf-mounted cameras and weight-sensing surfaces. UK and Netherlands grocery chains pilot these systems to compress transaction duration from minutes to seconds. The EU AI Act imposes algorithmic transparency requirements on automated decision systems processing biometric data.
- Online Platforms:Browser-based self-service portals serving account management and appointment scheduling.
- Mobile Apps:Smartphone-native interfaces leveraging NFC and QR code authentication for transit and retail payments.
Most installed capacity flows through Kiosks. Expansion is steepest in Automated Checkouts.
End User:
Retail chains and airports operate at the highest transaction volumes, driving economies of scale in fleet deployment. Restaurants and banks face tighter margin constraints and heavier regulatory scrutiny.
- Retail Chains:Supermarket operators deploy integrated checkout lanes and standalone kiosks to offset minimum wage escalations in California and New York. Legacy POS integration complexity forces expensive middleware development for chains operating 1990s-era inventory databases.
- Airports:Hub operators in Dubai and Singapore consolidate procurement around full-service concession contracts bundling hardware, digital menu management, and predictive maintenance. Uptime thresholds and passenger throughput guarantees replace traditional equipment purchase arrangements.
- Restaurants:Quick-service chains replace front-counter staff with ordering kiosks to compress labor costs.
- Banks:European institutions transition ATM networks toward digital-branch configurations with video teller integration.
Retail Chains absorb the largest hardware volumes. Airports are gaining share fastest.
Technology:
Cloud computing and artificial intelligence concentrate value capture in software layers, while IoT and QR code technologies remain commoditized connectivity components.
- Cloud Computing:Edge-to-core architectures enable real-time inventory synchronization and remote fleet management across dispersed device networks. Response latencies compress below 200 milliseconds, forcing hardware vendors to redesign kiosk architectures around distributed computing nodes.
- Artificial Intelligence:Generative interfaces replace static touchscreen menus with conversational agents adapting to user intent. Computer vision systems with depth-sensing cameras rewrite loss-prevention economics in unattended retail environments.
- IoT:Sensor networks monitoring device health, environmental conditions, and consumable levels for predictive maintenance.
- QR Code:Low-cost optical authentication for payment verification and menu access in cost-sensitive deployments.
Cloud Computing underpins the majority of new deployments. Artificial Intelligence commands the steepest investment trajectory.
Application:
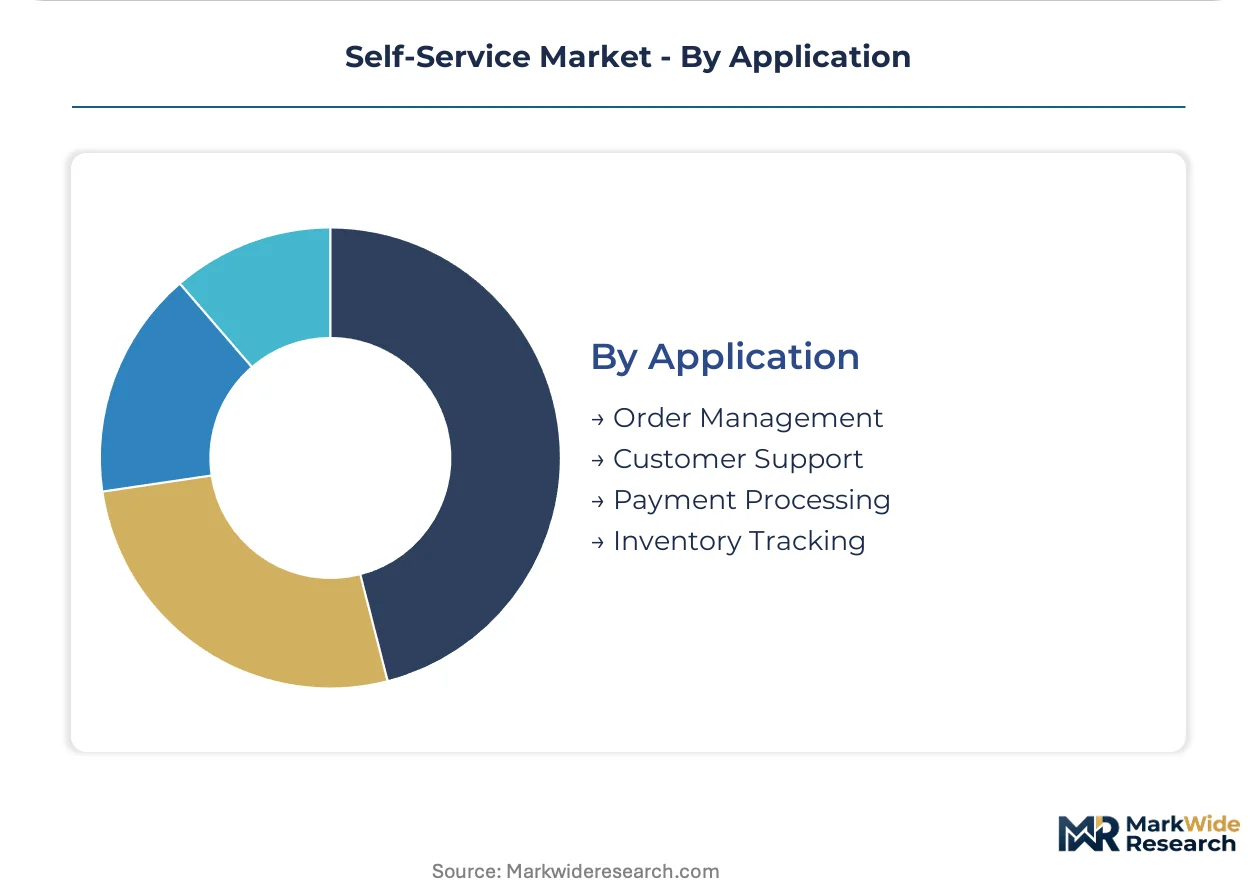
Payment processing and order management generate direct revenue impact, justifying premium hardware specifications. Customer support and inventory tracking serve operational efficiency goals with lower per-unit investment thresholds.
- Payment Processing:NFC terminals embedded in transit hubs across Tokyo, London, and Singapore normalize tap-to-pay behaviors. Contactless payment maturation drives hardware refresh cycles in municipal transit networks.
- Order Management:Self-service terminals integrate symptom-checking algorithms with appointment scheduling in South Korean and Australian outpatient clinics. Healthcare triage convergence expands addressable market beyond traditional retail and travel verticals.
- Customer Support:Automated ticketing and query resolution reducing call center labor requirements.
- Inventory Tracking:Real-time stock monitoring enabling automated replenishment triggers.
Payment Processing handles the highest transaction volumes. Order Management is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing self-service manufacturing capacity toward jurisdictions with lower compliance burdens, while demand concentrates in high-wage economies where labor substitution economics justify premium hardware investments.
United States
Quick-service restaurant chains in California and New York deploy integrated ordering kiosks to offset state minimum wage escalations. FDA sanitation guidelines govern food-service kiosk deployments, mandating specific cleaning protocols and material specifications. Dallas-Fort Worth and Atlanta metropolitan corridors host dense clusters of airport concession deployments where biometric boarding kiosks are modernizing passenger processing.
Germany
European banking institutions transition ATM networks toward digital-branch configurations with video teller integration. The EU AI Act imposes algorithmic transparency requirements on automated decision systems, compelling vendors to redesign consent flows. Frankfurt and Munich financial centers concentrate demand for financial self-service infrastructure as regional banks consolidate branch footprints.
China
Metropolitan retail corridors in Shanghai and Shenzhen scale unmanned convenience stores and smart vending networks fastest among global markets. SAMR technical standards govern payment terminal certification and data localization requirements. Yangtze River Delta manufacturing clusters produce touchscreen controller hardware for regional kiosk assembly, though foundry concentration in Taiwan exposes supply schedules to geopolitical disruption.
United Kingdom
Grocery chains pilot computer vision checkout systems eliminating barcode friction entirely, compressing transaction duration from minutes to seconds. GDPR biometric consent requirements constrain facial recognition authentication for age-verified purchases, limiting deployment velocity. London Heathrow and Gatwick airports consolidate procurement around full-service concession contracts bundling hardware with predictive maintenance guarantees.
Japan
Transit hubs across Tokyo normalize near-field communication tap-to-pay behaviors that self-service hardware exploits. METI industrial standards shape kiosk durability specifications for high-traffic deployment environments. Osaka-Kansai corridor quick-service operators replace front-counter staff with automated ordering terminals to address service sector labor shortages.
Self-Service Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cloud-native software layers and edge-AI specialization. The vendor base stratifies across three tiers: integrated hardware-software providers, component specialists, and platform-agnostic software vendors. Dominant competitive moves include strategic partnerships between kiosk fabricators and payment terminal manufacturers, plus geographic expansion through concession-based service contracts rather than equipment sales.
Within the integrated-system tier, NCR Corporation and Diebold Nixdorf represent archetypal hardware-software bundlers. NCR Corporation exemplifies sustained pricing power through software-hardware integration. Diebold Nixdorf anchors financial self-service network transitions. Toshiba Global Commerce Solutions occupies a position among diversified electronics conglomerates with retail technology divisions.
| Leading Market Players |
|---|
| NCR Corporation |
| Diebold Nixdorf |
| Toshiba Global Commerce Solutions |
| Verifone |
| Ingenico |
| KIOSK Information Systems |
| Fujitsu |
| Zebra Technologies |
| Advantech |
| Others |
Value Chain & Pricing Dynamics
Touchscreen controller chip costs cascade from Taiwan foundry capacity through three distinct hardware tiers, with premium kiosk fabricators absorbing wafer price volatility while economy-tier assemblers in Southeast Asia compress margins to maintain municipal transit contracts.
Pricing Analysis
Distributor margins separate integrated hardware-software bundles from component-only sales, with NCR Corporation and Diebold Nixdorf commanding 15-20 point markups through direct-to-retail-chain relationships that bypass wholesale channels. Pricing stratifies across premium, standard, and economy tiers based on edge-AI compute capability and FDA sanitation certification for food-service deployments. Cost compression in the standard tier intensifies because Chinese kiosk manufacturers are flooding European markets with EU AI Act-compliant alternatives. Quick-service restaurant chains in California exhibit highest price sensitivity due to minimum wage offset calculations, while Middle Eastern airport operators show lowest sensitivity under long-term concession structures.
Supply Chain Analysis
Refurbishment flows for edge-compute modules and payment terminals concentrate in Malaysia and Mexico, extending hardware lifecycle value for North American grocery chains facing compressed capital expenditure timelines. Component sourcing draws from Taiwan for touchscreen controllers, South Korea for NFC payment modules, and China for structural enclosures. Single-source vulnerability in Taiwan foundry capacity exposes kiosk production schedules to geopolitical disruption risk. Distribution runs through regional integrators who bundle hardware with software deployment and predictive maintenance subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in self-service hardware hinges on software-layer value capture, as cloud-native fleet management and generative interface licensing displace commoditized equipment sales.
For Market Incumbents: Acquire edge-AI firmware engineering teams to secure scarce talent capable of optimizing neural network inference on resource-constrained kiosk processors. NCR Corporation and Diebold Nixdorf must defend against cloud-native entrants by deepening captive supply of payment terminal hardware through backward integration into Taiwanese foundry relationships. Certification investment in EU AI Act technical documentation capabilities preserves European market access against regulatory displacement. For New Entrants and Emerging Players: The price-point gap between premium integrated bundles and economy kiosk hardware creates entry space for software-only vendors offering subscription-based fleet management to tier-2 retail chains. Indian airport modernization and South Korean healthcare triage deployments represent the most penetrable greenfield segments. A direct-to-operator sales model bypassing traditional distributor markups accelerates initial reference customer acquisition. For Investors and Strategic Acquirers: Consolidation pressure builds where component specialists lack software-layer differentiation and face margin compression from Chinese manufacturing scale. Long-term viability favors vendors with recurring revenue exposure through concession-based service contracts rather than equipment sales. The signal to watch is airport procurement committee shifts toward performance-guaranteed subscription models specifying uptime thresholds rather than capital expenditure approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Talent Acquisition | Firmware engineering scarcity in European labor markets constrains neural network optimization capabilities for kiosk processors. |
| EU AI Act Compliance Certification | Technical documentation and human oversight protocols unlock European retail and banking deployment opportunities. |
| Concession-Based Service Contracts | Middle Eastern hub airports now specify passenger throughput guarantees rather than hardware specifications in procurement. |
| Cloud-Native Fleet Management Platform | Edge-to-core architectures enable real-time inventory synchronization across dispersed self-service device networks. |
| Computer Vision Checkout Integration | Shelf-scanning systems in UK and Netherlands grocery chains compress transaction duration from minutes to seconds. |
Study Parameters
Direct dialogue with kiosk deployment managers, quick-service restaurant operations executives, airport procurement officers, and edge-AI firmware engineers grounded qualitative findings in operational reality. Secondary validation drew from FDA sanitation guidelines, EU AI Act regulatory filings, SAMR technical standards, and METI industrial specifications. Bottom-up and top-down triangulation cross-referenced hardware shipment data against cloud infrastructure spending patterns.
Bottom-up modeling aggregated unit economics across kiosk, automated checkout, online platform, and mobile app segments, while top-down analysis calibrated aggregate market expansion against labor cost compression trends in high-wage economies. Segmentation dimensions included service type, end user vertical, technology layer, and application function. CAGRs derived from regression analysis of historical deployment velocity against wage inflation differentials and regulatory compliance deadlines. Forecast inputs incorporated foundry capacity utilization rates and contactless payment terminal penetration curves.
Caveats apply where semiconductor supply disruption, GDPR biometric consent enforcement, or EU AI Act implementation delays could materially shift the outlook. Practitioners should monitor Taiwan foundry utilization rates and European data protection authority guidance for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Global Smart Retail Market
Retail Technology
America's AI in the Retail Market
Retail Technology
Smart Shelf Market
Retail Technology
E-Retail Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Alternative Retailing Technologies Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Smart Shelves Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
Connected Retail Market
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
AR in Retail Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Internet of Things (IoT) in Retail Market