
 Sales Dialer Software Market | 2026-2036
Sales Dialer Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Dialer Software Market Insights
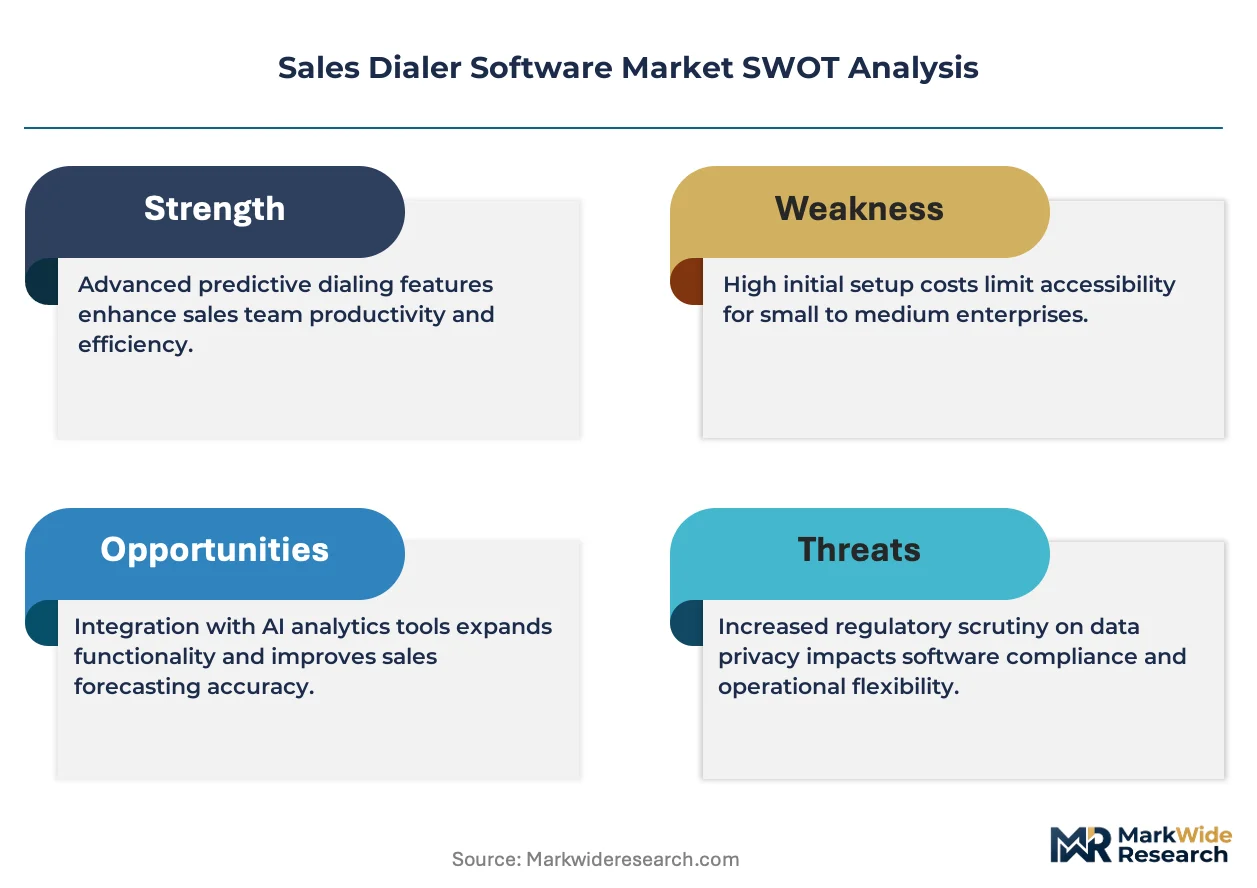
North American SaaS infrastructure is expanding capacity to support real-time voice automation at scale. Five9 leverages its cloud-native architecture to sustain enterprise-grade reliability across distributed agent networks. NICE Ltd anchors its position through deep workforce optimization integration with legacy telephony stacks. XANT differentiates via AI-driven conversation intelligence layered on top of core dialing engines.
Sales dialer software comprises programmable telephony systems that automate outbound call initiation, queue management, and agent connectivity through VoIP protocols and predictive algorithms. These platforms route calls based on real-time agent availability, customer data signals, and compliance timers to maximize contact rates while minimizing idle time. Cloud-based deployment leads structural adoption as organizations abandon on-premises PBX maintenance burdens for elastic capacity. Predictive dialing technology captures the fastest expansion trajectory among core engine types, driven by machine learning refinements that reduce abandoned call ratios below regulatory thresholds. CRM integration features command premium positioning within product tiers, since unified customer data streams determine agent scripting accuracy and conversion outcomes.
FCC regulations in the United States govern consent frameworks, abandoned call ceilings, and caller ID authentication through STIR/SHAKEN mandates, directly shaping platform compliance architecture. GDPR in Europe and state-level privacy statutes in California impose parallel constraints on call recording retention and consumer opt-out handling. Stakeholders must monitor evolving TCPA litigation patterns and cross-border data localization requirements as determinants of vendor selection and deployment geography.
Market Dynamics
Predictive dialing algorithms are compressing agent idle time while FCC abandoned-call ceilings force platform vendors to rebuild compliance architectures around real-time abandonment ratio monitoring.
Growth Catalysts
- STIR/SHAKEN Mandates:FCC caller ID authentication requirements are accelerating platform upgrades across US call centers, creating replacement demand for legacy systems lacking native spoofing protection.
- CRM Synchronization:Real-time data pipelines between dialer engines and Salesforce or HubSpot instances are shortening agent scripting cycles and lifting contact-to-conversion rates in enterprise sales operations.
- Cloud Elasticity:Elastic capacity provisioning through AWS and Azure infrastructure is eliminating PBX maintenance burdens and enabling seasonal scaling for retail and insurance verticals.
Market Restraints
- Telephony Cost Volatility:Per-minute VoIP termination rates through Tier-1 carriers fluctuate with cross-border routing agreements, squeezing margin structures for high-volume outbound operations.
- TCPA Litigation Exposure:Private right-of-action provisions in US federal telemarketing law expose dialer operators to statutory damages that scale with call volume, chilling aggressive contact strategies.
- Substitution by Messaging:WhatsApp Business API and SMS automation platforms are capturing appointment-setting and follow-up workflows that previously required live voice interaction.
Strategic Opportunities
- GDPR-Compliant Recording:EU call centers face retention and consent management gaps that vendors addressing Article 17 right-to-erasure workflows can capture through specialized compliance modules.
- AI-Voice Convergence:Synthetic voice agents from ElevenLabs and similar providers are merging with dialer queues to handle initial screening conversations before human handoff.
- Vertical-Specific Scripting:Healthcare patient outreach and debt collection represent underpenetrated segments requiring specialized compliance timers and disclosure sequencing that generic platforms lack.
Industry Challenges
- Agent Attrition Management:High turnover in outsourced call centers degrades predictive model accuracy as training data freshness decays, forcing continuous recalibration cycles.
- Legacy PBX Integration:Hybrid environments mixing cloud dialers with on-premises Avaya or Cisco infrastructure create signaling protocol mismatches that delay deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Dialer Software Market |
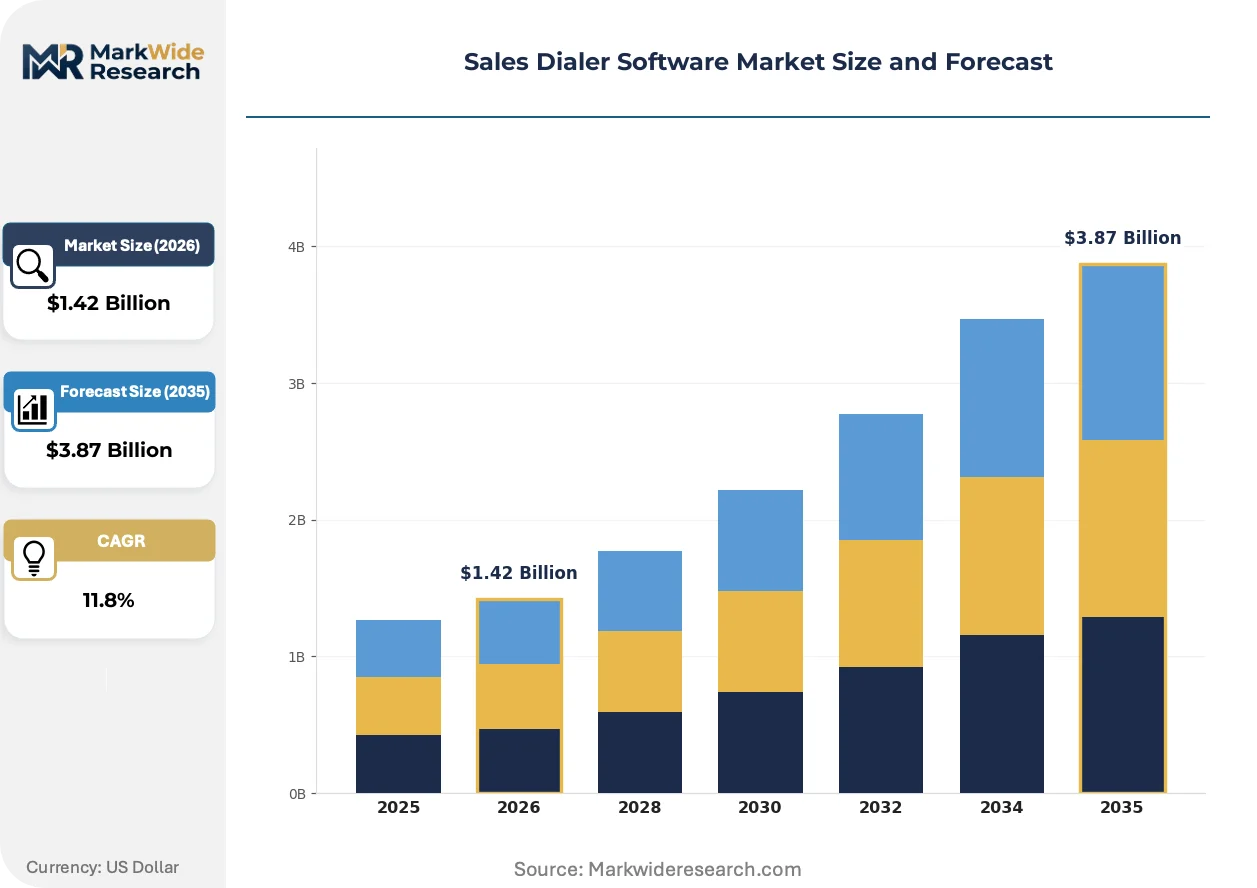
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.87 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Multi-tenant Customer Type: SMEs, Large Enterprises, Startups, Call Centers Technology: VoIP, Automatic Call Distribution, Predictive Dialing, Interactive Voice Response Feature: Call Recording, CRM Integration, Analytics, Multi-channel Support |
| Companies Covered | Five9, NICE Ltd, XANT, PhoneBurner, VanillaSoft, Convoso, CallFire, RingDNA, CloudTalk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Dialer Software Market Trends and Innovations
Machine learning refinements are compressing the latency between call disposition capture and algorithmic pacing adjustments, reshaping how platforms balance contact rate maximization against regulatory risk exposure.
Conversational AI middleware is absorbing post-call transcription and sentiment extraction workloads that previously required dedicated quality assurance staff. Enterprise buyers in financial services and insurance are deploying these layers at scale, with implementation timelines compressing from eighteen months to under ninety days. The technology is absorbing human capital costs while generating structured training data that feeds back into predictive models.
GDPR Article 5 data minimization requirements are forcing European deployments to adopt ephemeral storage architectures for call recordings and metadata. Platform vendors serving Germany and France are engineering automatic purge workflows and consent expiration tracking that satisfy CNIL and BfDI audit protocols. Healthcare and public sector buyers face the steepest compliance burden, with procurement cycles extending to accommodate legal review of cross-border data routing.
Subscription pricing with usage-tier escalators is displacing perpetual licensing in mid-market procurement, compressing upfront capital requirements while tying vendor revenue to actual dial volume. Channel partners and direct sales teams are restructuring compensation around annual recurring revenue metrics rather than license fees. This shift is most visible in United Kingdom and United States markets where private equity-backed call center rollups prioritize operational expenditure treatment for technology acquisitions.
Sales Dialer Software Market Segmentation
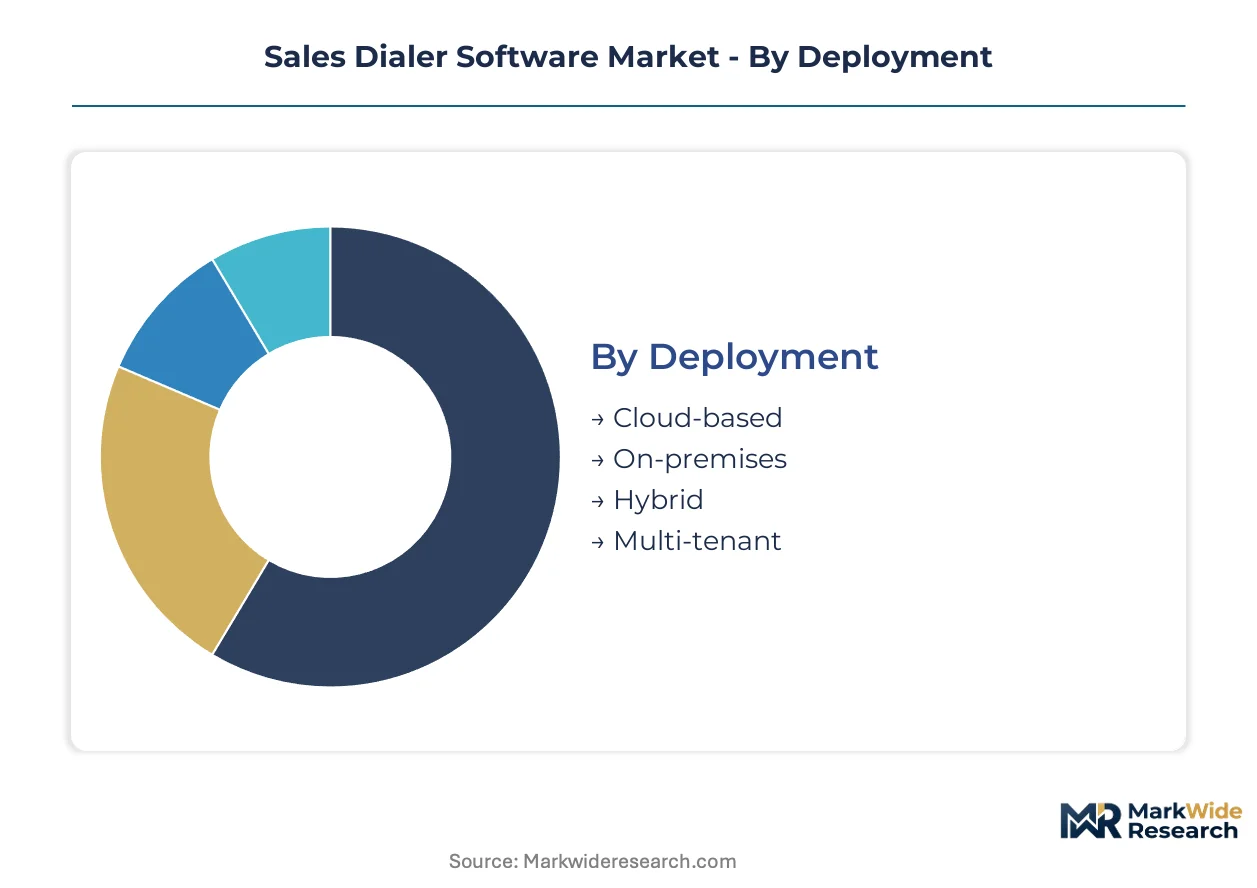
Sales dialer software architectures diverge sharply based on integration depth, with standalone deployments serving agile sales teams while embedded systems weave through complex enterprise telephony stacks. Segmentation choices directly determine compliance architecture, scaling economics, and the feasibility of real-time AI augmentation.
Deployment:
Cloud-native platforms dominate where elastic capacity and rapid provisioning outweigh legacy system preservation, while on-premises retention signals regulatory custody requirements or specialized latency constraints.
- Cloud-based:Multi-tenant architectures on AWS and Azure infrastructure eliminate hardware maintenance cycles and enable automatic compliance patching for FCC STIR/SHAKEN mandates. Demand concentrates in United States insurance and financial services verticals where seasonal call volume spikes require instant scaling without capital commitment.
- On-premises:Dedicated server installations retain sensitive call metadata within physical facility boundaries, satisfying healthcare HIPAA requirements and defense sector security protocols. German and French enterprises favor this model under GDPR Article 44 data localization pressures, accepting higher total cost of ownership for audit certainty.
- Hybrid:Split architectures route outbound campaigns through cloud dialers while preserving on-premises PBX for inbound customer service queues.
- Multi-tenant:Shared infrastructure instances partition tenant data through containerized isolation, reducing per-seat costs for mid-market buyers.
Volume placements concentrate in Cloud-based; the faster expansion belongs to Hybrid.
Customer Type:
Organizational scale dictates feature complexity tolerance, with procurement authority shifting from operational managers in smaller entities to dedicated vendor management offices in global enterprises.
- SMEs:Subscription-tier deployments with pre-configured Salesforce connectors serve revenue teams under fifty agents, prioritizing rapid deployment over customization depth. United Kingdom professional services firms and United States regional insurance brokers drive this segment through standardized SaaS procurement.
- Large Enterprises:Custom-integrated implementations spanning multiple business units demand workforce optimization layering, real-time analytics pipelines, and dedicated customer success engineering. Predictive model training on proprietary conversation datasets creates switching costs that entrench vendor relationships.
- Startups:Freemium-to-paid conversion models accommodate volatile headcount growth and minimal IT staffing.
- Call Centers:Business process outsourcing specialists prioritize per-minute cost optimization and agent utilization metrics above all other criteria.
Revenue concentration sits with Large Enterprises; steepest expansion trajectory belongs to Call Centers.
Technology:
Core engine selection determines abandonment ratio performance, regulatory risk exposure, and the technical feasibility of AI voice augmentation.
- Predictive Dialing:Machine learning algorithms forecast agent availability and customer answer likelihood, pacing call initiation to minimize idle time while maintaining FCC-compliant abandonment ratios below three percent. United States telemarketing operations and United Kingdom debt collection agencies invest heavily here, with algorithm refinement cycles compressing weekly.
- VoIP:Packet-switched voice transmission over IP networks replaces traditional circuit-switched telephony, enabling geographic flexibility and cost arbitrage across carrier termination routes.
- Automatic Call Distribution:Queue management engines route inbound interactions based on agent skill matrices and real-time availability.
- Interactive Voice Response:Pre-recorded menu trees and speech recognition layers filter and triage calls before human handoff.
Technology investment clusters around Predictive Dialing; IVR is climbing the fastest as synthetic voice capabilities mature.
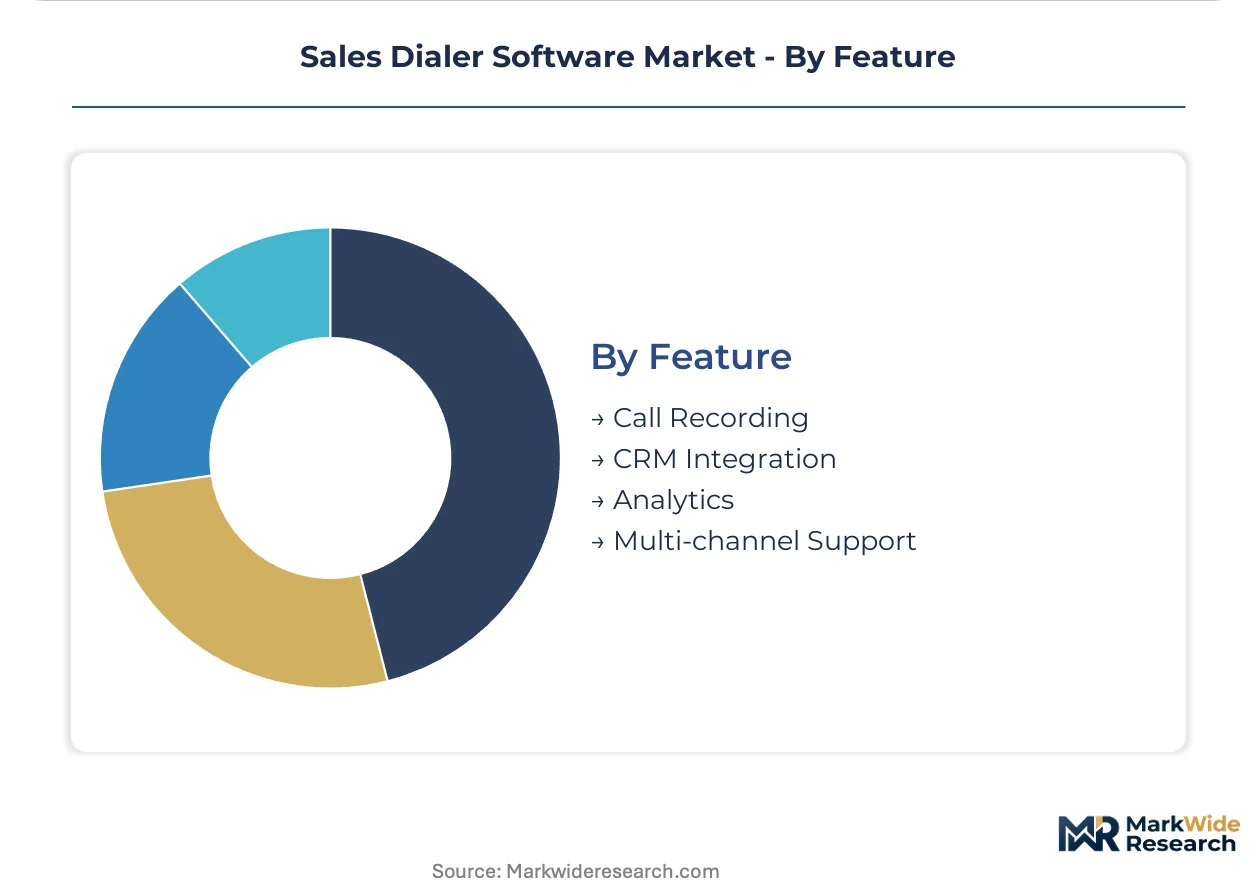
Feature:
Capability modularization allows buyers to match subscription tiers against actual workflow requirements rather than purchasing bundled functionality.
- CRM Integration:Bi-directional data synchronization with Salesforce, HubSpot, or Microsoft Dynamics surfaces customer history, purchase propensity scores, and scripted talking points within the agent desktop. United States enterprise sales organizations treat this as non-negotiable, with API reliability becoming a primary vendor selection criterion.
- Call Recording:Ephemeral or persistent audio capture supports quality assurance, dispute resolution, and conversational AI training data generation.
- Analytics:Real-time and retrospective dashboards track contact rates, conversion funnels, and agent performance distributions.
- Multi-channel Support:Unified queuing across voice, SMS, email, and chat interfaces enables omnichannel customer journey management.
Procurement prioritization favors CRM Integration; gaining share fastest is Multi-channel Support as messaging platforms capture appointment-setting workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure clusters in Northern Virginia and Frankfurt anchor the sales dialer software supply base, while carrier termination hubs in London and Singapore shape cross-border voice routing economics.
United States
Enterprise call centers in Texas and Florida drive predictive dialing adoption as insurance and debt collection verticals scale outbound operations. FCC STIR/SHAKEN mandates compel platform upgrades across Fortune 500 contact centers, with abandonment ratio monitoring now embedded in core architectures. Northern Virginia's AWS and Azure data center clusters host the majority of cloud-native deployments, processing real-time agent pacing algorithms at sub-100-millisecond latency.
United Kingdom
London-based financial services firms prioritize CRM-integrated dialers for wealth management client acquisition, with subscription pricing displacing perpetual licenses in mid-market procurement. FCA conduct rules and GDPR Article 17 right-to-erasure requirements force vendors to engineer automatic purge workflows for call recordings. Manchester and Birmingham contact center outsourcing hubs concentrate demand for multi-tenant cloud deployments serving retail and utilities verticals.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria deploy on-premises dialer installations to satisfy BfDI audit protocols for call metadata custody under GDPR Article 44 localization pressures. Predictive dialing adoption lags cloud-first markets due to Works Council consultation requirements for workforce monitoring technologies. Frankfurt's carrier-neutral data centers host hybrid architectures splitting outbound campaigns across cloud dialers and legacy PBX infrastructure.
India
Bangalore and Hyderabad technology parks house delivery centers for global business process outsourcing firms running high-volume outbound campaigns for US and UK clients. TRAI regulations on unsolicited commercial communications impose parallel consent frameworks that vendors must reconcile with FCC and GDPR requirements. Mumbai's financial services sector drives demand for voice biometrics integration within dialer queues to satisfy RBI authentication mandates for telephone banking.
Australia
Sydney and Melbourne insurance brokers adopt cloud-based predictive dialers to manage seasonal policy renewal campaigns, with elastic capacity provisioning through AWS Sydney regions. ACMA Do Not Call Register compliance adds screening layers that increase per-call processing overhead compared to North American deployments. Brisbane's government contact centers represent a specialized vertical requiring secure on-premises installations for citizen service hotlines.
Sales Dialer Software Market Competitive Landscape
Global majors compete with regional champions across compliance architecture and carrier integration depth. The vendor base stratifies into three tiers: cloud-native platforms with predictive AI engines, legacy workforce optimization suites with dialer modules, and vertical-specialist providers serving regulated industries. Dominant competitive moves include M&A to acquire conversation intelligence capabilities and strategic partnerships with Tier-1 carriers for preferential VoIP termination rates.
Among cloud-native specialists, Five9 and NICE Ltd exemplify the platform consolidation archetype, while XANT represents the AI-first positioning tier. Five9 anchors the elastic infrastructure segment through AWS-native reliability engineering. NICE Ltd occupies the workforce optimization integration position, embedding dialer functionality within broader contact center suites. XANT sits within the conversation intelligence specialization, layering predictive analytics atop core dialing engines to differentiate on agent scripting outcomes.
| Leading Market Players |
|---|
| Five9 |
| NICE Ltd |
| XANT |
| PhoneBurner |
| VanillaSoft |
| Convoso |
| CallFire |
| RingDNA |
| CloudTalk |
| Others |
Pricing and Supply Chain Analysis
VoIP termination rate indices from Tier-1 carriers cascade through sales dialer software supply chains, compressing margin structures for high-volume outbound operations while forcing vendors to unbundle compliance modules from core platform subscriptions. AWS and Azure infrastructure pricing arbitrage across Northern Virginia and Frankfurt data center clusters further stratifies end-user pricing tiers based on geographic deployment choice.
Pricing Analysis
Service-bundling decisions separate premium tiers with dedicated customer success engineering from economy tiers where compliance patching and API support carry separate per-seat surcharges. Three-tier pricing structure across premium, standard, and economy levels anchors on CRM integration depth and predictive model customization access. Cost compression in mid-market SaaS subscriptions is intensifying because hyperscaler infrastructure commoditization erodes platform differentiation. Call center outsourcing specialists exhibit highest price sensitivity, while financial services enterprises prioritize reliability premiums over per-seat cost minimization.
Supply Chain Analysis
GDPR Article 44 data localization mandates and India's TRAI domestic-content consultation requirements are reshaping sourcing patterns for call metadata storage and voice biometric processing modules. Software development concentrates in the United States, the United Kingdom, and India, with Bangalore and Hyderabad delivery centers feeding global business process outsourcing demand. Platform architectures rest on AWS and Azure compute instances, Twilio and Vonage VoIP termination routes, and Salesforce API ecosystem dependencies. Single-source vulnerability in hyperscaler infrastructure creates concentration risk for multi-tenant deployments. Distribution runs through direct enterprise sales teams and channel partners serving mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sales dialer software vendors are racing to deepen upstream control over conversation intelligence training data and downstream integration into workforce optimization suites, with AI-voice convergence creating new vertical-integration pressure points.
For Market Incumbents: Acquire conversational AI training datasets from debt collection and healthcare verticals where specialized compliance timers generate scarce labeled data. Build captive carrier relationships with Tier-1 VoIP termination providers to defend margin position against telephony cost volatility. Synthetic voice agent substitution from ElevenLabs-style providers threatens platform differentiation; entrench through proprietary predictive model refinement cycles.
For New Entrants and Emerging Players: Enter via GDPR-compliant ephemeral storage architectures serving German and French enterprises under CNIL and BfDI audit protocols. Target healthcare patient outreach and public sector citizen service hotlines where generic platforms lack specialized disclosure sequencing. Pursue channel partnerships with Avaya and Cisco systems integrators to bypass legacy PBX integration bottlenecks.
For Investors and Strategic Acquirers: The window for entry favors vertical-specialist providers with regulatory moats in healthcare and debt collection. Long-term viability hinges on AI-voice convergence readiness and workforce optimization suite integration depth. Monitor FCC TCPA litigation volume as inflection indicator for compliance architecture replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Conversation intelligence capabilities from vertical-specific providers accelerate predictive model training in regulated segments. |
| Strategic Partnership | Preferential VoIP termination rates with Tier-1 carriers defend margin structures against cross-border routing cost volatility. |
| Platform Integration | Deep Salesforce and HubSpot API synchronization shortens agent scripting cycles and lifts contact-to-conversion rates. |
| Geographic Expansion | Frankfurt and Sydney data center deployments satisfy GDPR Article 44 and ACMA compliance for European and Australian buyers. |
| Product Launch | AI-voice convergence modules handling initial screening conversations before human handoff capture emerging workflow demand. |
Research Methodology
Multi-period observation of predictive dialing abandonment ratios, FCC compliance upgrade cycles, and CRM integration adoption rates anchored the trend analysis, supplemented by interviews with contact center operations directors, SaaS procurement officers, workforce optimization vendors, and Tier-1 carrier account managers. Secondary validation drew from FCC STIR/SHAKEN implementation filings, AWS and Azure hyperscaler capex disclosures, SEC 10-K filings from public contact center technology vendors, and TRAI unsolicited commercial communications regulatory circulars. Bottom-up sizing of cloud-native and on-premises deployment volumes triangulated against top-down enterprise IT spending benchmarks across insurance, financial services, and healthcare verticals.
Segment-weighting approaches distributed value estimates across deployment models, organization size tiers, core engine technologies, and feature module configurations. Predictive dialing, VoIP infrastructure, automatic call distribution, and interactive voice response technologies were modeled separately with algorithm refinement cycles and synthetic voice maturity as technology-specific inputs. CAGRs were derived from elasticity-adjusted adoption curves and regulatory mandate timing across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated TCPA litigation exposure or wholesale substitution by WhatsApp Business API messaging platforms. Forecasts reflect documented assumptions on FCC enforcement intensity, hyperscaler infrastructure pricing trajectories, and AI-voice convergence adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Backend-As-A-Service Market
Software & Services
Construction Software As A Service Market
Software & Services
Software Repository Market
Software & Services
Global AB Testing Software Market
Software & Services
File Sharing Software Market
Software & Services
Jobsite Management Software Market
Software & Services
AI Sales Assistant Software Market
Software & Services
Middleware Market
Software & Services
Automotive Dealership Software Market
Software & Services
Global Award Management Software Market
Software & Services
Construction Estimating Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Storyboarding Software Market
Software & Services
Air Cargo Software Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Communication Software Market