
 Global Critical Communication Market | 2026-2036
Global Critical Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Critical Communication Market Intelligence
Component consolidation among specialist hardware manufacturers is shifting the supply base for critical communication equipment. Motorola Solutions Inc. leverages its extensive portfolio in land mobile radios and public safety software. Thales S.A. competes on the basis of its integrated systems for defense and transportation networks. L3Harris Technologies, Inc. specializes in secure communications for government and military clients, anchoring a significant part of the high-assurance segment.
Critical communication systems provide fail-safe, real-time voice and data connectivity for first responders and essential service operators. These networks are engineered for high availability and low latency, often operating on dedicated spectrum to ensure reliability during emergencies. While Land Mobile Radios constitute a mature and foundational product segment, Long-Term Evolution technology represents the fastest-growing area. Emergency services remain the primary application, with procurement focused on interoperability and data-centric capabilities.
Regulatory bodies such as the FCC in the United States and the MIIT in China govern spectrum allocation, a crucial resource for these networks. Standards from organizations like the European Telecommunications Standards Institute (ETSI) define interoperability for technologies like TETRA and DMR, shaping market access. Stakeholder decisions will center on balancing investment in legacy system maintenance against the strategic migration to next-generation broadband-based platforms.
Market Dynamics
The fundamental dynamic shaping the critical communication market is the architectural migration from narrowband, voice-centric Land Mobile Radio systems to data-intensive broadband networks based on Long-Term Evolution. This technological pivot creates a structural tension between maintaining mission-critical legacy assets and funding the transition to next-generation platforms.
Growth Catalysts
- Nationwide Public Safety Networks:Government-led initiatives, including the First Responder Network Authority in the United States, provide dedicated funding and policy frameworks that accelerate the upgrade from legacy radios to interoperable, broadband-based communication systems for emergency services.
- Data-Centric Operations:The operational requirement for real-time video streaming, geographic information system mapping, and biometric data within public safety and utility sectors drives the adoption of LTE-capable devices that extend beyond traditional voice communication.
- Infrastructure Modernization Mandates:In the transport and energy sectors, regulatory pressures to enhance grid reliability and transport safety necessitate overhauls of aging communication systems, creating demand for private LTE networks to support smart grid and intelligent transportation applications.
Market Restraints
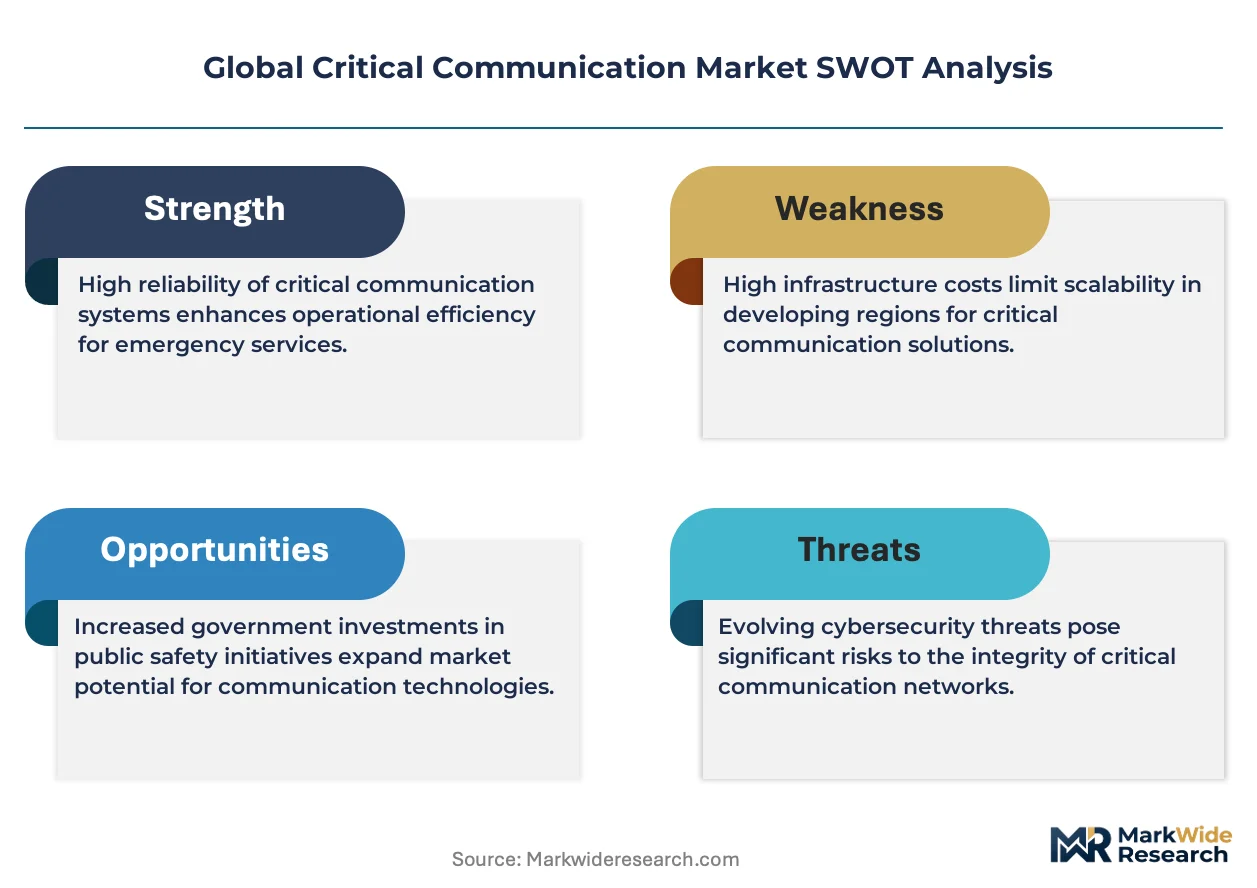
- High Capital Expenditure:The substantial upfront investment required to deploy new LTE network infrastructure and replace entire fleets of subscriber devices acts as a significant budgetary constraint for public agencies and enterprise operators.
- Spectrum Allocation and Cost:Dedicated spectrum is a finite and costly resource, with allocation and licensing governed by bodies like the FCC in the US and MIIT in China, which can limit the scale and pace of private network deployments.
- Legacy System Interoperability:Ensuring seamless, reliable communication between new LTE platforms and deeply embedded legacy radio technologies like TETRA or P25 during long migration periods presents considerable technical and financial challenges.
Strategic Opportunities
- Hybrid LMR-LTE Devices:Developing devices that operate on both legacy radio frequencies and modern broadband networks provides a crucial, phased migration path for customers, bridging the gap between old and new infrastructure investments.
- Expansion into Industrial Applications:Adapting critical communication hardware and software for private LTE and 5G networks in sectors like mining, manufacturing, and port operations opens significant new revenue streams beyond the traditional public safety market.
- Emerging Market Network Development:Governments in Latin America and Southeast Asia are initiating plans for national disaster recovery and public safety communication networks, representing largely underpenetrated markets for advanced systems.
Industry Challenges
- Complex System Integration:The operational difficulty of integrating disparate software systems, such as computer-aided dispatch, records management, and video feeds, onto a unified broadband platform creates significant implementation hurdles for agencies.
- Heightened Cybersecurity Threats:Migrating to IP-based LTE networks expands the potential attack surface for critical infrastructure, demanding more sophisticated security protocols and continuous monitoring to protect sensitive data from state-sponsored and criminal actors.
- Workforce Skill Gaps:A shortage of technicians possessing dual expertise in both traditional radio frequency engineering and modern IP networking complicates the deployment, maintenance, and optimization of converged communication systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Critical Communication Market |
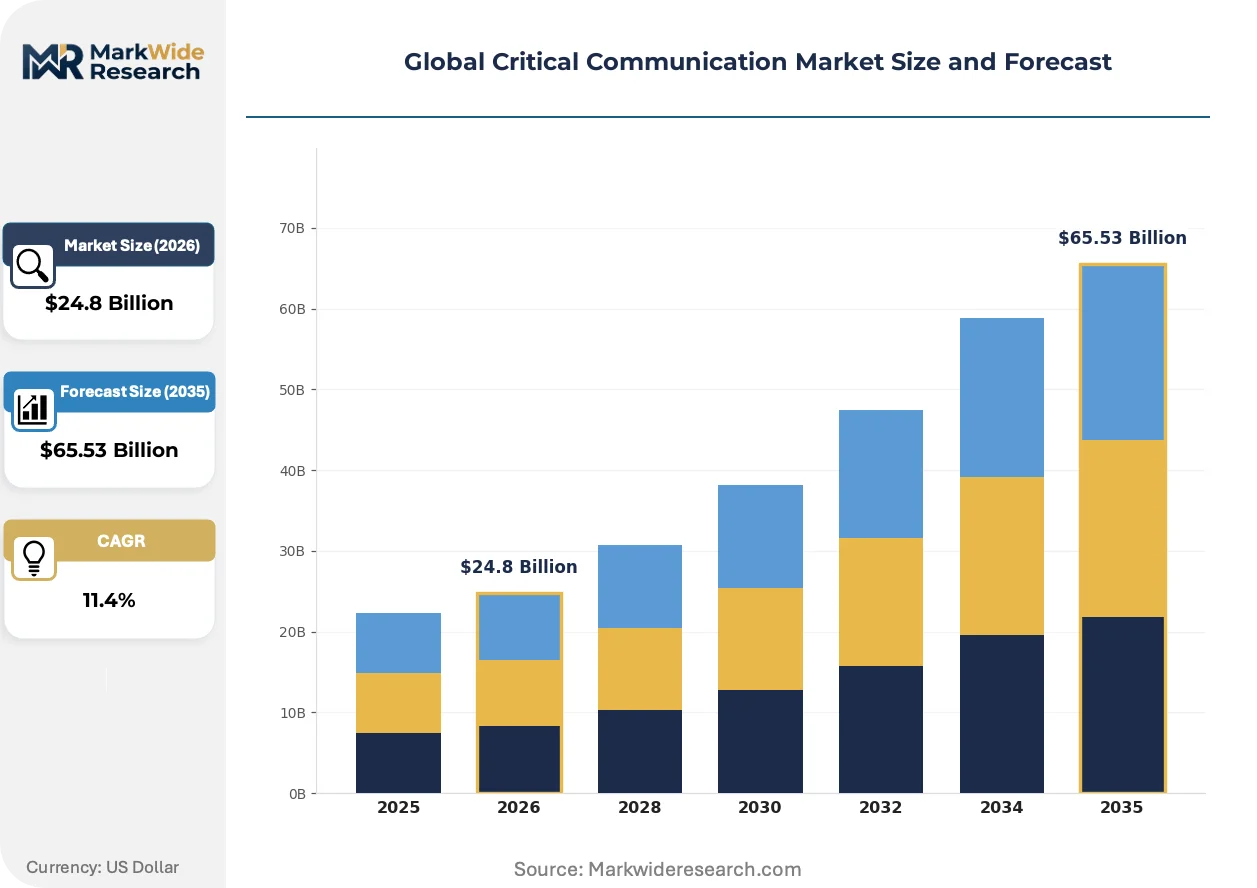
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $65.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
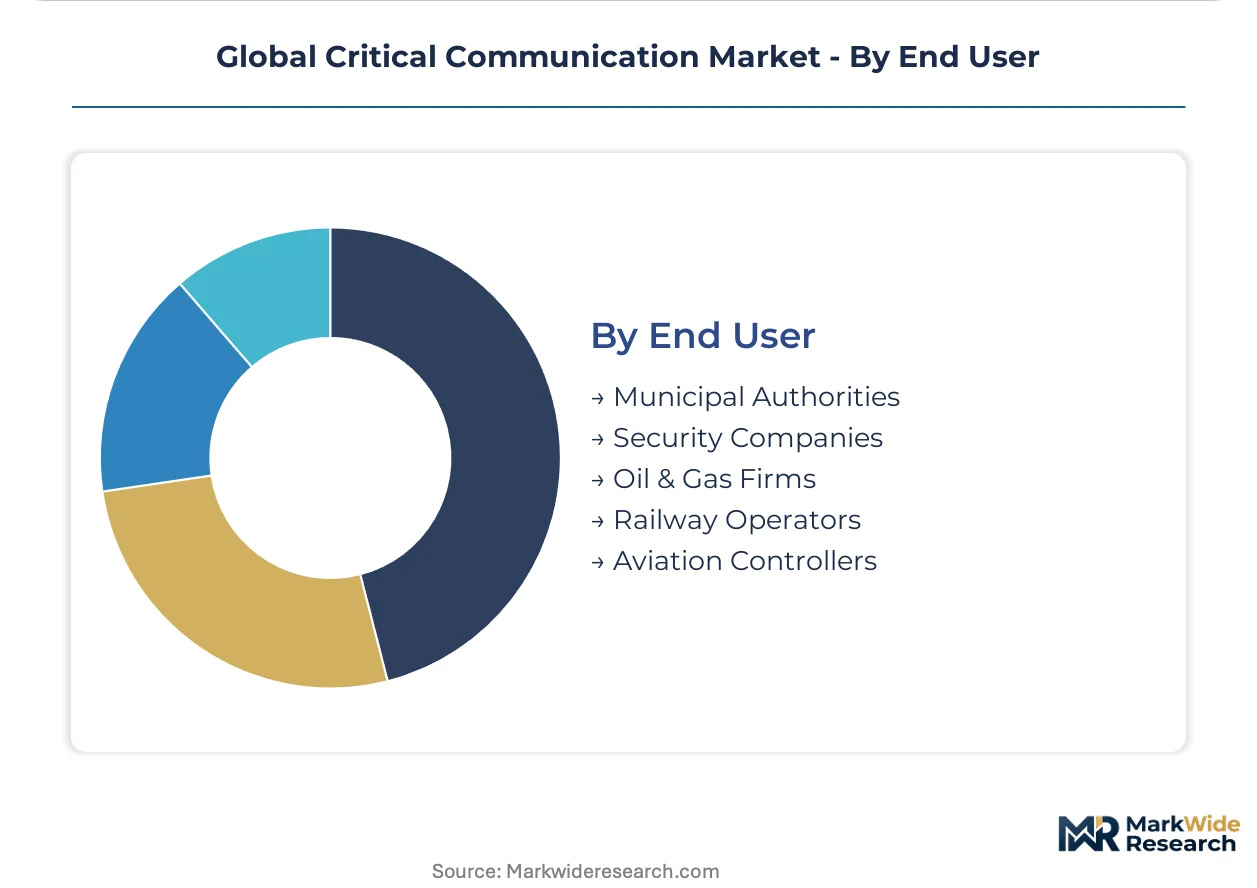
| Segmentation | Product Type: Land Mobile Radios, Push-to-Talk Over Cellular, Dispatch Consoles, Base Stations Technology: Terrestrial Trunked Radio, Digital Mobile Radio, Long-Term Evolution, Satellite Communication Application: Emergency Services, Public Safety Agencies, Utilities Operators, Transportation Networks, Defense Forces End User: Municipal Authorities, Security Companies, Oil & Gas Firms, Railway Operators, Aviation Controllers |
| Companies Covered | L3Harris Technologies, Inc., Cisco Systems, Inc., Motorola Solutions Inc., General Dynamics Corporation, Thales S.A., Nokia Corporation, Huawei Technologies Co., Ltd., Honeywell International Inc., Ericsson AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Critical Communication Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of mission-critical voice reliability with commercial broadband data capabilities. This convergence is creating new hybrid device form factors, network architectures, and service delivery models that redefine emergency and operational response.
Mission-Critical Push-to-Talk over LTE is a standards-based capability delivering secure, low-latency group communication on broadband networks. Public safety agencies and transportation operators are adopting MCPTT solutions to enhance situational awareness. This standards-based approach is overtaking proprietary push-to-talk over cellular applications by providing superior quality of service, interoperability, and priority access on shared or dedicated networks.
Spectrum allocation policies, such as the re-evaluation of the 4.9 GHz band in the United States, are creating new deployment possibilities. This shift can enable more flexible models for public safety and critical infrastructure communication, moving beyond exclusive single-agency network control. Utilities and local governments are most affected, as they could gain access to licensed spectrum to build private LTE networks for grid modernization and smart city applications.
A transition from capital expenditure to operational expenditure models influences equipment and service acquisition. Agencies and enterprises are increasingly adopting "as-a-service" contracts, where network access, devices, and software are procured through recurring subscriptions rather than large, upfront hardware purchases. This demand-side shift is most visible in North America and Europe, often linked to public-private partnerships for nationwide public safety broadband networks.
Global Critical Communication Market Segmentation

The critical communication market's segmentation provides a detailed view of the diverse technologies and solutions adopted by various sectors. Understanding these distinct segments is crucial for market participants to identify specific demand drivers and strategic investment areas. Each category reflects unique operational needs and regulatory landscapes shaping procurement decisions.
Product Type:
The upgrade and replacement cycle in critical communication systems significantly influences demand for both established and next-generation product types.
- Land Mobile Radios:These are foundational voice communication devices operating on dedicated spectrum, offering high reliability for mission-critical operations. Public safety agencies in the United States maintain extensive fleets of LMRs for daily operations.
- Push-to-Talk Over Cellular:This product enables instant group communication over commercial or dedicated broadband networks, leveraging LTE capabilities for enhanced data features. Emergency services are increasingly adopting PTT over Cellular for improved situational awareness.
- Dispatch Consoles:These centralized control systems manage and coordinate communication across multiple radio channels and networks for operators.
- Base Stations:Fixed infrastructure components provide radio coverage and connectivity for land mobile radio and broadband critical communication networks.
Volume placements concentrate in Land Mobile Radios; the faster expansion belongs to Push-to-Talk Over Cellular.
Technology:
Application-specific requirements largely determine the selection of underlying communication technologies within the critical communication market.
- Terrestrial Trunked Radio:TETRA is a digital trunked radio standard providing secure voice and data services, widely adopted by public safety organizations in Europe. Regulatory bodies like ETSI define its interoperability standards.
- Long-Term Evolution:LTE technology offers high-speed data and voice capabilities over broadband networks, enabling real-time video and geographic information system mapping. Nationwide public safety broadband initiatives in the United States drive LTE adoption.
- Digital Mobile Radio:DMR is a digital radio standard offering enhanced voice quality and basic data features, serving commercial and enterprise users.
- Satellite Communication:This technology provides coverage in remote or disaster-stricken areas where terrestrial networks are unavailable, essential for defense forces.
The Terrestrial Trunked Radio segment maintains a significant installed base, while Long-Term Evolution technology is expanding most quickly.
Application:
Regulatory mandates and operational imperatives define critical communication system deployments across diverse applications.
- Emergency Services:This application encompasses fire, ambulance, and rescue operations, demanding fail-safe, real-time voice and data connectivity during critical incidents. Procurement focuses on interoperability and data-centric capabilities for first responders.
- Public Safety Agencies:These include law enforcement and homeland security, requiring secure and resilient communication for daily operations and large-scale emergencies. Government-led initiatives in the United States accelerate upgrades to broadband-based systems.
- Utilities Operators:Communication systems support smart grid management and remote monitoring for energy and water infrastructure.
- Transportation Networks:This segment includes railways and public transit, utilizing critical communication for operational control and safety.
- Defense Forces:Secure and robust communication is vital for military operations and national security, often requiring specialized high-assurance systems.
Emergency Services consistently generate the largest demand, with Public Safety Agencies gaining share fastest through broadband integration.
End User:
Procurement patterns among end users reflect varying budgets, infrastructure needs, and regulatory compliance obligations for critical communication systems.
- Municipal Authorities:Local governments procure critical communication systems for public safety, city services, and disaster response. Nationwide public safety networks provide funding for these upgrades.
- Railway Operators:These entities require highly reliable communication for train control, passenger information, and operational safety across extensive networks. Infrastructure modernization mandates drive investment in private LTE networks.
- Security Companies:Private security firms utilize critical communication for surveillance, patrol coordination, and incident management.
- Oil & Gas Firms:Communication systems support remote operations, safety protocols, and data transmission in challenging industrial environments.
- Aviation Controllers:Air traffic control relies on specialized critical communication for aircraft guidance and ensuring flight safety.
Municipal Authorities represent a substantial purchasing cohort, whereas Railway Operators are driving significant investment in specialized network solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its extensive public safety broadband initiatives, anchors the global demand for advanced critical communication systems. This market segment exhibits diverse regional growth patterns driven by varying regulatory landscapes and infrastructure modernization priorities. Governments worldwide prioritize secure and reliable connectivity for emergency services and critical infrastructure.
United States
Demand for critical communication systems in the United States stems from nationwide public safety broadband network initiatives. The First Responder Network Authority (FirstNet) provides dedicated funding and policy frameworks for upgrading legacy radio systems. Major metropolitan areas like New York City and Los Angeles actively integrate LTE-based communication for emergency services.
Germany
Germany's critical communication market benefits from stringent regulatory pressures to enhance transport safety and grid reliability. European Telecommunications Standards Institute (ETSI) standards define interoperability for technologies like TETRA, widely adopted by public safety. Cities such as Berlin and Munich focus on private LTE networks to support smart city applications and public transit.
China
China drives critical communication system adoption through infrastructure modernization mandates and national security priorities. The Ministry of Industry and Information Technology (MIIT) governs spectrum allocation, influencing the pace of private network deployments. Industrial hubs in the Yangtze River Delta and Pearl River Delta are investing in secure communication for manufacturing and port operations.
India
India's critical communication market sees demand from growing urban infrastructure and disaster recovery efforts. Regulatory bodies like TRAI influence spectrum availability for public safety and utility operators. Major cities like Mumbai and Delhi are exploring private LTE networks for smart grid management and emergency response.
Brazil
Brazil represents a significant market for critical communication due to its vast geography and public safety modernization plans. Government initiatives in Latin America are beginning to fund national disaster recovery and public safety communication networks. São Paulo and Rio de Janeiro are key centers for early adoption of advanced systems for emergency services.
Global Critical Communication Market Key Industry Players
Global majors compete with regional champions across technology innovation and system integration capabilities within the critical communication market. The market exhibits a tiered structure, with established players holding significant shares in legacy LMR systems while new entrants focus on LTE-based solutions. Strategic archetypes include integrated solution providers, specialized hardware manufacturers, and software-centric platform developers. Companies are actively pursuing strategic partnerships and portfolio diversification to address the evolving demand for broadband-based solutions and expand their geographic reach.
Within the integrated solution provider tier, Motorola Solutions Inc. exemplifies extensive capabilities in land mobile radios and public safety software platforms, reflecting its U.S. origins. Thales S.A. occupies a strong position by representing integrated systems for defense and transportation networks, showcasing its European roots and diverse portfolio. L3Harris Technologies, Inc., a U.S.-based entity, anchors the high-assurance segment, specializing in secure communications for government and military clients. These companies collectively navigate the architectural migration from narrowband voice systems to data-intensive broadband networks, impacting their product development cycles. Their competitive strategies involve balancing investment in legacy system maintenance against the strategic migration to next-generation broadband-based platforms.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| Cisco Systems, Inc. |
| Motorola Solutions Inc. |
| General Dynamics Corporation |
| Thales S.A. |
| Nokia Corporation |
| Huawei Technologies Co., Ltd. |
| Honeywell International Inc. |
| Ericsson AB |
Cost & Logistics Intelligence
Architectural migration from narrowband LMR systems to data-intensive broadband networks simultaneously reshapes cost economics and concentrates the supply of specialized LTE components. This technological shift impacts both hardware procurement and service delivery models.
Pricing Analysis
Warranty and service bundling significantly influence the total cost of ownership for critical communication systems, often differentiating offerings. Pricing models increasingly incorporate subscription-based "as-a-service" contracts for network access and software. Price differentiation stems from customization levels for specific agency requirements and the integration of advanced data features. Pricing pressure arises from the substantial capital expenditure required for new LTE network infrastructure. Municipal authorities exhibit the highest price sensitivity due to budgetary constraints, while defense forces prioritize high-assurance systems over cost.
Supply Chain Analysis
Dual-sourcing requirements for mission-critical components are becoming standard practice to mitigate supply risks. Geographic supply concentration for specialized hardware and semiconductors centers in the United States, Germany, and China. Raw material dependencies include advanced radio frequency integrated circuits and high-performance network processors. A structural supply chain risk is the potential for single-source vulnerabilities in highly specialized component categories. Downstream distribution typically runs through direct sales to large government entities and specialized system integrators for complex, large-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a supply-constrained growth story, with dedicated spectrum allocation and specialized hardware manufacturing serving as key bottlenecks influencing pricing and deployment pace.
For Market Incumbents: Acquire specialized software firms to enhance data integration capabilities across disparate public safety applications. Invest in research and development for hybrid LMR-LTE devices, creating a seamless migration path for agencies and countering emerging IP-based solution providers. Strengthen relationships with regulatory bodies like the FCC and ETSI to influence future spectrum allocation policies. Deepen integration with public safety software platforms to offer comprehensive, end-to-end solutions.
For New Entrants and Emerging Players: A price-point gap exists between premium, fully integrated solutions and more accessible broadband communication options. Target industrial applications such as mining, manufacturing, and port operations, which require private LTE networks for operational efficiency. Focus on delivering "as-a-service" models, offering flexible subscription-based access to MCPTT and data services. Penetrate emerging markets in Latin America and Southeast Asia by partnering with local infrastructure providers.
For Investors and Strategic Acquirers: Exit pathways concentrate in software-centric platform developers and specialized network integrators with strong intellectual property in secure broadband communication. The long-term viability of this market is strong, driven by continuous infrastructure modernization mandates and the operational imperative for data-centric capabilities. A significant signal to watch is the widespread adoption of mission-critical push-to-talk over LTE standards across public safety agencies.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch Hybrid LMR-LTE Devices | Enables phased technology migration for public safety agencies and transportation operators. |
| Integrate Public Safety Software Platforms | Enhances situational awareness for emergency services through unified data access. |
| Form Strategic Spectrum Partnerships | Secures dedicated network access for critical infrastructure and public safety deployments. |
| Acquire Specialized LTE/5G Firms | Expands broadband communication capabilities for government and enterprise clients. |
| Expand into Emerging Markets | Captures new revenue streams from national disaster recovery and public safety initiatives. |
Research Approach
Multi-period observation of public safety funding, regulatory changes, and technology adoption rates anchored the trend analysis, supplemented by interviews with key industry stakeholders. Primary research involved discussions with public safety officials, IT directors, network engineers, and regulatory body representatives. This qualitative input was triangulated with quantitative data from secondary sources, including FCC filings, MIIT reports, ETSI standards documents, and government procurement databases.
An input-output matrix framework was employed to model market dynamics across the analysis window. This framework integrated segmentation dimensions such as product type, technology, application, end user, and regional regulatory frameworks. Compound annual growth rates were derived through a combination of regression analysis and expert consensus, utilizing key forecast inputs like government spending on nationwide public safety networks and broadband infrastructure rollout plans.
Inputs from government reports and corporate financial disclosures were available through the study window; gaps in comprehensive global private LTE deployment statistics introduce uncertainty bands into specific regional forecasts. Forecasts reflect current assumptions regarding technological advancements and regulatory stability. A model refresh is warranted upon material change in spectrum allocation policies or major shifts in public safety funding models.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Video Managed Services Market
Communication Services
Web Conferencing Market
Communication Services
North America Postal Services Market
Communication Services
Voip Services Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Green Communication Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Cloud Communication Platform Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
Consumer Communication Services Market
Communication Services
Latin America Postal Service Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Managed Communication Services Market
Communication Services
Mobile Messaging Market
Communication Services
Walkie Talkie Market