
 Europe Contact Center As a Service (Ccaas) Market | 2026-2036
Europe Contact Center As a Service (Ccaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Contact Center As a Service (Ccaas) Market Analysis
Mid-market enterprises are unwinding their reliance on large enterprise contact center contracts and shifting toward flexible consumption models. Genesys leverages its AI-powered workforce optimization stack to capture this migration wave. NICE Ltd. anchors its European position through analytics-intensive compliance tools tailored to GDPR-sensitive workflows. Five9 Inc. competes on rapid deployment timelines that appeal to buyers replacing legacy Avaya estates.
Contact Center As a Service delivers cloud-hosted customer engagement infrastructure combining automatic call distribution, interactive voice response, and unified agent desktops accessible via standard web protocols. The architecture eliminates capital-intensive premise-based hardware while enabling real-time elasticity in agent capacity. Public cloud deployment leads European uptake due to hyperscaler resilience and API extensibility, though hybrid cloud configurations are gaining traction among BFSI end users bound by data sovereignty requirements. AI-powered technology segments attract disproportionate R&D investment as natural language processing and sentiment analysis reshape first-contact resolution benchmarks.
GDPR enforcement by national data protection authorities across France, Germany, and Italy shapes vendor qualification criteria and limits non-EU data residency options. The EU AI Act risk-classification framework imposes transparency obligations on automated decision-making in customer service channels, compelling providers to document algorithmic logic. Stakeholders must weigh sovereign cloud certifications against the interoperability cost of fragmented national compliance regimes.
Market Dynamics
European financial institutions are dismantling decades-old on-premises contact center estates as GDPR and the EU AI Act force data residency and algorithmic transparency mandates that cloud-native architectures alone can satisfy at scale.
Growth Catalysts
- EU AI Act compliance deadlines:Automated decision-making transparency requirements are compelling banks and insurers to migrate toward CCaaS platforms with built-in explainability documentation and audit trails.
- Agent attrition crisis:Contact center labor shortages across Germany, France, and the Netherlands are accelerating AI-powered workforce optimization adoption to reduce reliance on human agent scaling.
- Real-time elasticity demand:E-commerce and travel verticals require instantaneous capacity modulation during seasonal spikes, a capability premise-based hardware cannot deliver.
Market Restraints
- Hyperscaler concentration risk:Over-reliance on AWS, Microsoft Azure, and Google Cloud for European CCaaS infrastructure creates single-point-of-failure exposure and limited negotiation leverage for enterprise buyers.
- Legacy integration tax:Custom API development to connect cloud contact centers with entrenched CRM and core banking systems consumes 30-40% of typical deployment budgets.
- Fragmented sovereign cloud certifications:Divergent national data residency regimes across Germany, France, and Italy multiply compliance certification costs for vendors seeking multi-country coverage.
Strategic Opportunities
- Central and Eastern Europe greenfield:Poland, Czech Republic, and Romania present underpenetrated markets where cloud-first financial services entrants lack legacy estate drag.
- Conversational AI + biometric authentication fusion:Voice biometrics layered onto natural language processing workflows enables passwordless authentication that reduces fraud and average handle time simultaneously.
- Vertical-specific CCaaS templates:Pre-configured compliance modules for insurance claims handling and wealth management advisory workflows accelerate time-to-value for regulated sectors.
Industry Challenges
- Multilingual NLP model scarcity:High-quality sentiment analysis and intent recognition for Nordic languages, Polish, and regional Spanish dialects lags English, French, and German coverage.
- Cross-border data transfer uncertainty:Schrems II litigation and evolving EU-US Data Privacy Framework adequacy decisions create legal ambiguity for CCaaS providers routing traffic across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Contact Center As a Service (Ccaas) Market |
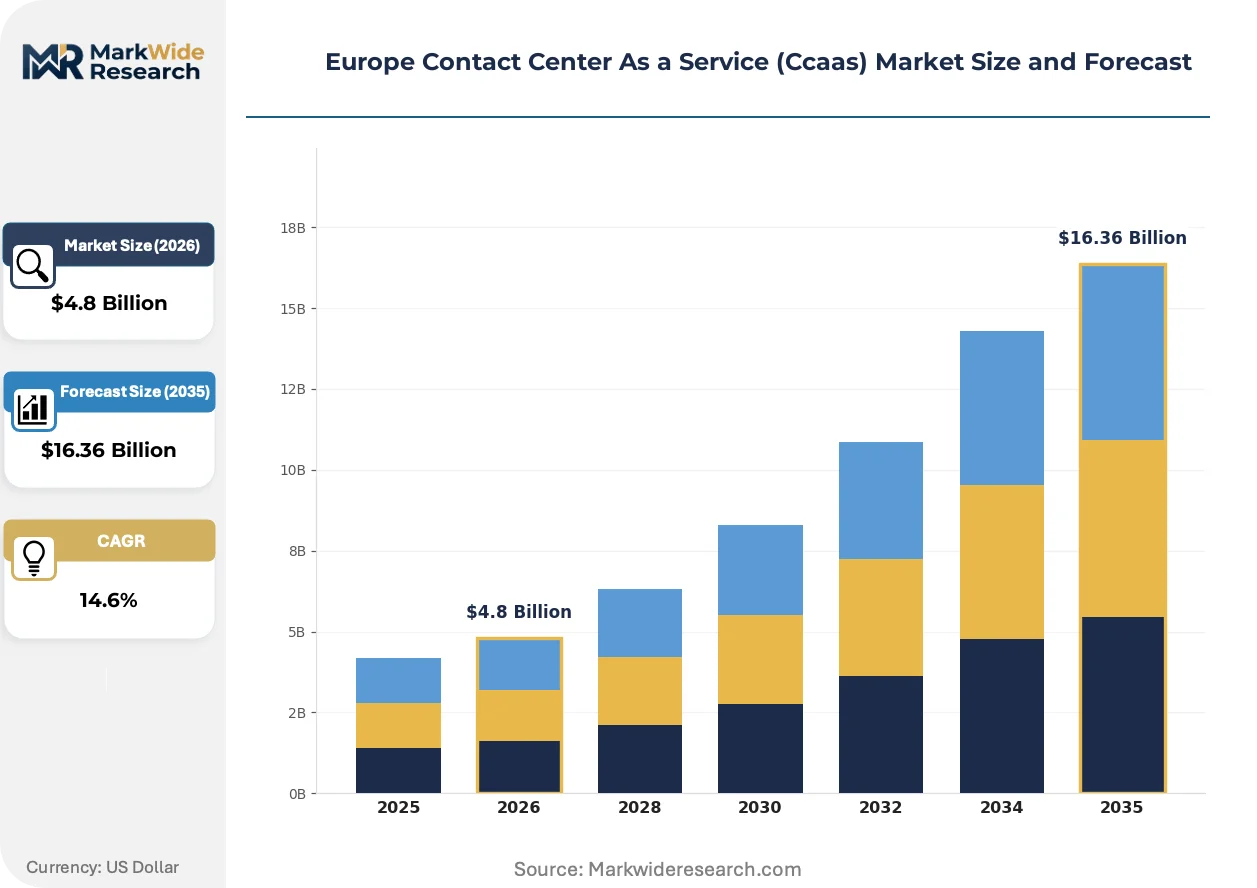
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Retail, Healthcare, BFSI, IT Services Technology: AI-Powered, Omnichannel, VoIP, Analytics Service Type: Inbound, Outbound, Blended, Support |
| Companies Covered | Genesys, NICE Ltd., Five9 Inc., Amazon Web Services Inc., 8x8 Inc., Avaya LLC, Cisco Systems Inc, Enghouse Interactive Inc., Atos SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Contact Center As a Service (Ccaas) Market Emerging Trajectories
Agent-facing AI copilots and real-time coaching engines are compressing training cycles and reshaping quality management from retrospective scoring to live intervention. Sovereign cloud deployments are fragmenting vendor architectures as national data localization requirements harden.
Large language model-powered agent assist tools are supplanting static knowledge bases and scripted response trees in tier-one customer interactions. Nordic banks and Dutch insurers are deploying these systems fastest, with live rollout timelines under 90 days becoming competitive table stakes. The technology is compressing first-contact resolution variance and reducing supervisor headcount ratios.
The EU AI Act's risk-classification framework mandates human oversight for high-risk automated customer service decisions, compelling CCaaS providers to engineer "human-in-the-loop" handoff protocols. Financial services workflows involving credit decisions or claims adjudication face the strictest transparency obligations. German and French regulators are already demanding algorithmic impact assessments as vendor qualification criteria.
Mid-market enterprises are abandoning multi-year enterprise contracts for consumption-based pricing with monthly minimums and burst allowances. Value-added resellers and systems integrators are capturing this migration by packaging CCaaS with adjacent workforce management and quality analytics. Benelux and Scandinavian markets show the fastest contract structure rotation.
Europe Contact Center As a Service (Ccaas) Market Segmentation
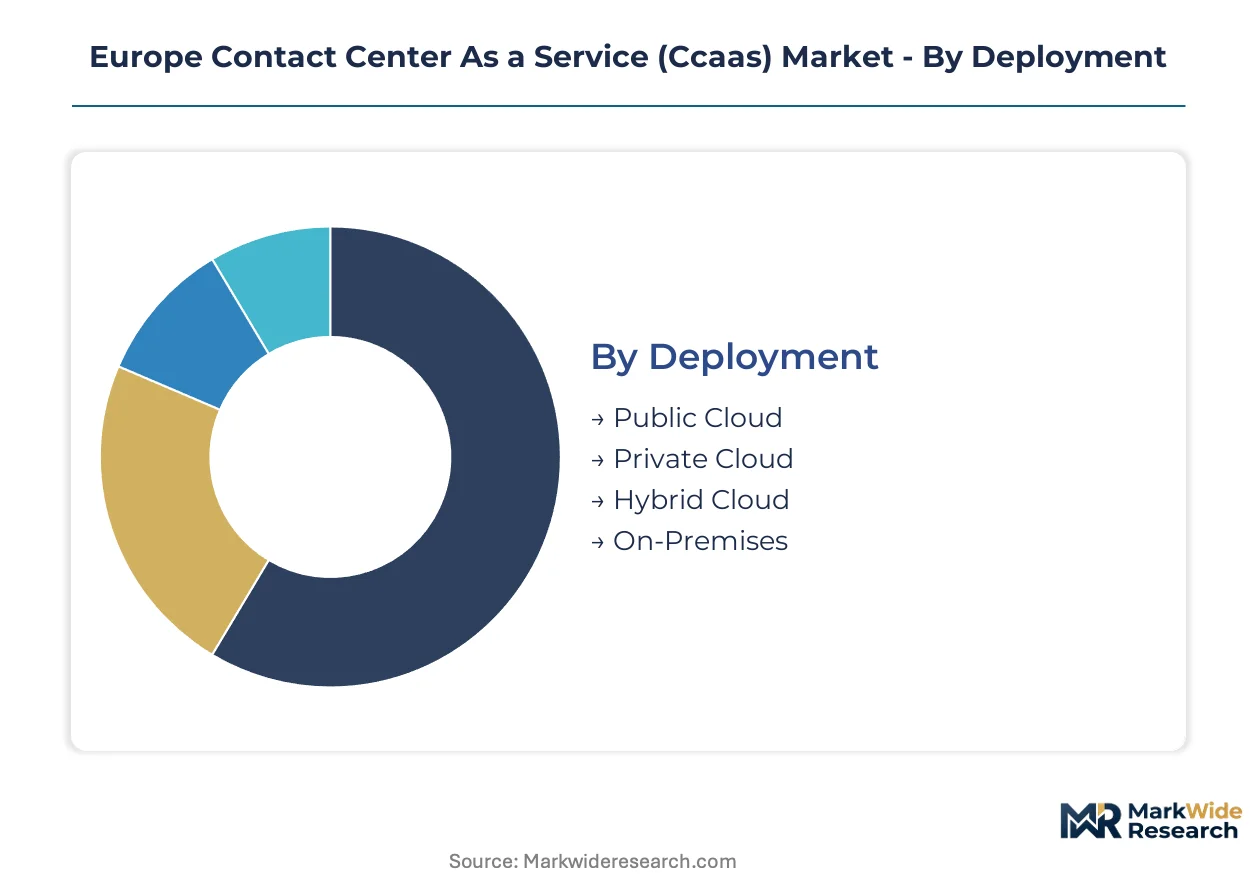
CCaaS purchasing patterns diverge sharply across deployment architectures and regulatory exposure levels. European buyers segment their procurement decisions around data sovereignty mandates, AI transparency obligations, and legacy system interdependencies.
Deployment:
Substitution pressure from sovereign cloud alternatives is reshaping how financial institutions evaluate infrastructure commitments.
- Public Cloud:Hyperscaler-hosted infrastructure delivers elastic compute and API extensibility through standard web protocols. German e-commerce platforms and Dutch travel operators concentrate demand here, driven by burst capacity requirements during seasonal volume spikes. GDPR compliance tools are increasingly bundled as native features.
- Hybrid Cloud:Split architectures route sensitive voice data through private nodes while leveraging public cloud for analytics workloads. French insurers and Italian banks favor this model to satisfy CNIL and Garante data localization rulings without sacrificing AI processing capabilities.
- Private Cloud:Single-tenant deployments on dedicated hardware meet strictest data residency requirements for wealth management advisory workflows.
- On-Premises:Legacy Avaya and Cisco estates persist in regulated sectors with multi-year amortization cycles remaining.
Public Cloud retains volume leadership; Hybrid Cloud holds the steepest expansion curve.
End User:
Margin structures vary dramatically by sector compliance burden and customer interaction complexity.
- BFSI:Banking, financial services, and insurance operations demand explainable AI documentation, biometric authentication layers, and audit-grade call recording retention. Frankfurt-based universal banks and Amsterdam insurers are migrating fastest to satisfy EU AI Act risk-classification mandates for credit decisions and claims adjudication.
- Healthcare:Patient engagement platforms require HIPAA-equivalent protections under national health data laws, with Nordic countries enforcing particularly stringent consent management protocols.
- Retail:Seasonal demand volatility drives preference for consumption-based pricing with burst allowances.
- IT Services:Technology providers white-label CCaaS infrastructure for downstream SME distribution.
BFSI commands the highest contract values; Retail is expanding most quickly.
Technology:
Supply concentration in large language model providers is concentrating vendor differentiation around implementation speed rather than core algorithm ownership.
- AI-Powered:Natural language processing engines, sentiment analysis modules, and real-time agent assist tools compress first-contact resolution variance. Nordic banks deploy these systems with sub-90-day rollout timelines now standard for competitive positioning.
- Omnichannel:Unified routing across voice, chat, email, and social channels eliminates channel silos that fragment customer journey visibility.
- VoIP:Session initiation protocol infrastructure remains foundational for voice connectivity.
- Analytics:Workforce optimization and quality management dashboards transform retrospective scoring into live intervention capabilities.
AI-Powered retains volume leadership; Omnichannel shows the steepest adoption acceleration.
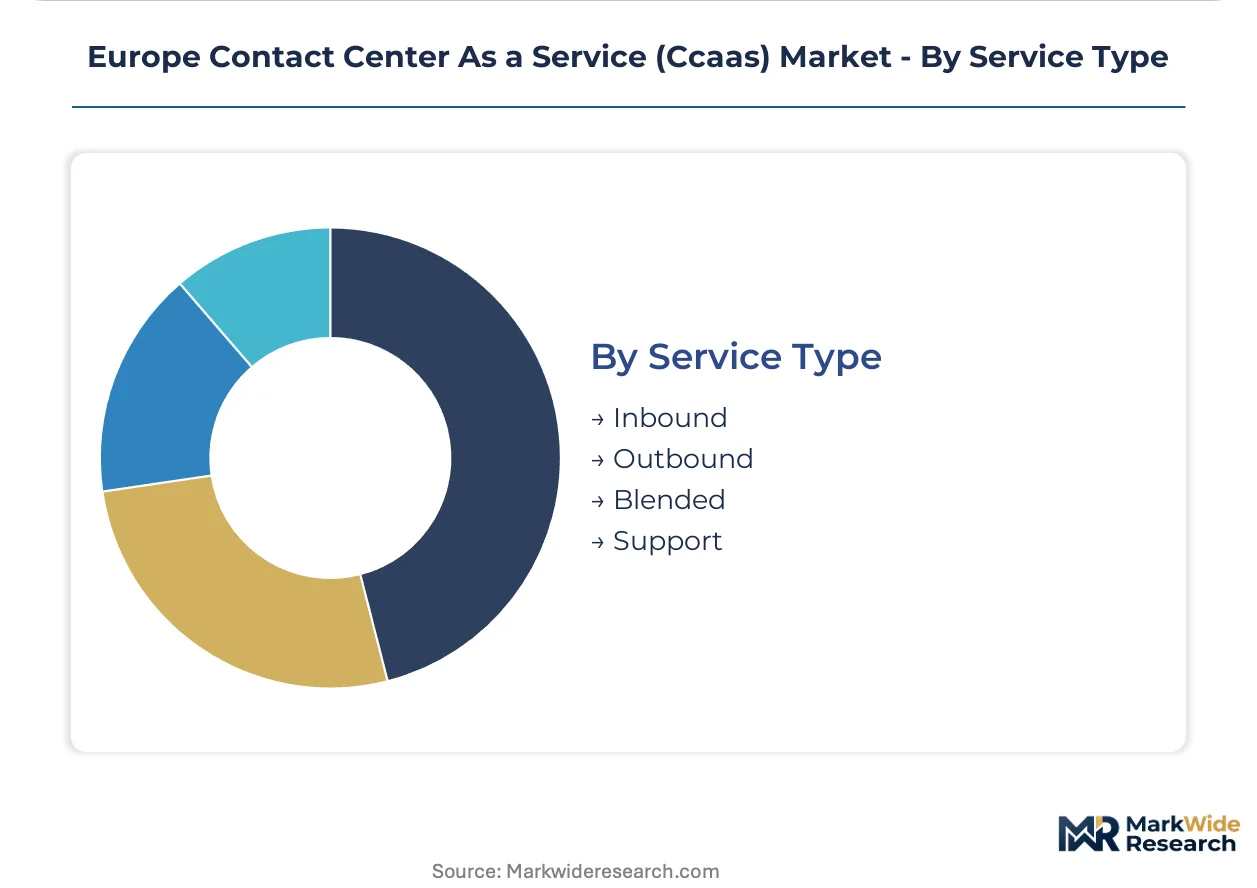
Service Type:
Application intensity determines pricing power and contract duration across interaction modalities.
- Inbound:Customer-initiated contact handling through IVR, ACD, and queue management systems. German automotive manufacturers and French telecom operators are upgrading these stacks to reduce abandonment rates during peak demand windows.
- Outbound:Proactive engagement campaigns for collections, appointment reminders, and sales outreach face tightening consent requirements under ePrivacy Directive implementations.
- Blended:Dynamic agent allocation between inbound and outbound queues maximizes utilization rates.
- Support:Technical helpdesk and post-sales service workflows integrate with CRM systems for case continuity.
Inbound retains volume leadership; Support is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German CCaaS vendors export sovereign-hosted platforms to Austrian and Swiss financial institutions seeking GDPR-compliant infrastructure without US hyperscaler exposure.
Germany
Frankfurt-based universal banks drive demand for data-resident customer engagement platforms with EU AI Act explainability documentation. BaFin supervisory guidance mandates algorithmic transparency for automated credit decisions. The Rhine-Main financial cluster anchors migration from legacy Avaya estates to cloud-native architectures.
France
Parisian insurers prioritize hybrid cloud configurations separating voice data from analytics workloads. CNIL rulings on international data transfers restrict non-EU hosting options for claims adjudication workflows. The La Défense business district concentrates procurement of biometric authentication layers.
United Kingdom
London fintechs consume burst-capacity CCaaS for seasonal customer acquisition spikes. FCA conduct rules shape audit-grade call recording retention requirements. The Canary Wharf-Financial District corridor leads European deployment of real-time agent assist tools.
Netherlands
Amsterdam insurers accelerate AI-powered workforce optimization to address agent attrition. Dutch Data Protection Authority enforcement on automated decision-making compels human-in-the-loop protocols. The Zuidas financial district pioneers sub-90-day conversational AI rollouts.
Italy
Milanese banks favor private cloud deployments for wealth management advisory workflows. Garante data localization rulings limit public cloud routing for sensitive voice interactions. The Porta Nuova business district drives demand for pre-configured compliance modules.
Europe Contact Center As a Service (Ccaas) Market Vendor Landscape
Player mix skews toward hyperscaler-backed platforms and specialized workforce optimization vendors. Market structure concentrates around three strategic tiers: cloud-native specialists, legacy infrastructure incumbents transitioning to subscription models, and telecommunications carriers white-labeling third-party stacks. Consolidation pressure intensifies as mid-market buyers abandon multi-year enterprise contracts. Dominant competitive moves include strategic partnerships with sovereign cloud providers and portfolio diversification into adjacent quality analytics.
Within the cloud-native specialist tier, Genesys and Five9 exemplify rapid-deployment positioning targeting legacy estate replacements. NICE Ltd. anchors the analytics-intensive compliance segment where GDPR-sensitive workflows demand audit-grade documentation. These three vendors occupy distinct competitive positions: Genesys leverages AI-powered workforce optimization, Five9 competes on deployment velocity, and NICE Ltd. embeds regulatory tooling into customer engagement infrastructure.
| Leading Market Players |
|---|
| Genesys |
| NICE Ltd. |
| Five9 Inc. |
| Amazon Web Services Inc. |
| 8x8 Inc. |
| Avaya LLC |
| Cisco Systems Inc |
| Enghouse Interactive Inc. |
| Atos SE |
| Others |
Supply Flow & Price Mechanics
Cloud-native CCaaS platforms displacing legacy on-premises Avaya and Cisco estates simultaneously redraw supply geography toward hyperscaler regions and compress pricing power for hardware-dependent vendors. This substitution dynamic concentrates infrastructure procurement decisions around AWS, Microsoft Azure, and Google Cloud regions while forcing premise-based providers into defensive bundling strategies.
Pricing Analysis
Next-generation AI-powered CCaaS platforms command premium positioning over prior-generation voice-only infrastructure and emerging consumption-based alternatives. Three-tier pricing structure across premium, standard, and economy levels differentiates by AI feature depth, GDPR certification grade, and burst capacity guarantees. Pricing pressure stems from mid-market buyers abandoning multi-year enterprise contracts for flexible monthly minimums with burst allowances. Retail and e-commerce verticals exhibit highest price sensitivity due to seasonal volume volatility, while BFSI institutions prioritize compliance-grade documentation over unit cost.
Supply Chain Analysis
Ireland and the Netherlands anchor European hyperscaler data center capacity for CCaaS infrastructure delivery, with Germany and France expanding sovereign cloud alternatives. Compute, storage, and specialized AI accelerator hardware draw from Taiwan, South Korea, and USA fabrication. Single-source vulnerability concentrates in NVIDIA GPU supply for real-time agent assist workloads. Distribution runs through direct vendor sales to enterprise buyers, supplemented by systems integrators and value-added resellers packaging adjacent workforce management tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European CCaaS competitive advantage increasingly hinges on scarce sovereign cloud engineering talent capable of threading multi-jurisdictional compliance architectures. Vendors lacking embedded GDPR and EU AI Act documentation capabilities face disqualification from financial services procurement shortlists.
For Market Incumbents: Shield installed base relationships by embedding algorithmic transparency documentation directly into platform roadmaps before EU AI Act enforcement hardens. Accelerate certification investment in German BSI and French SecNumCloud sovereign cloud standards to preempt challenger qualification. Vertical integration into biometric authentication layers defends margin position against modular competitors. For New Entrants and Emerging Players: CNIL and BSI certification fast-tracks unlock procurement access to French insurers and German universal banks locked out of non-EU-hosted alternatives. Central and Eastern European greenfield markets present underpenetrated white space where cloud-first financial services entrants lack legacy estate drag. Target Polish and Romanian banking licenses with rapid-deployment positioning emphasizing sub-90-day rollout timelines. For Investors and Strategic Acquirers: The market sits at a compliance-driven consolidation phase that favors analytics-intensive vendors with embedded regulatory tooling over pure-play infrastructure providers. Long-term viability centers on acquisition of workforce optimization specialists whose quality management dashboards transform retrospective scoring into live intervention capabilities. Monitor Schrems II litigation developments and evolving EU-US Data Privacy Framework adequacy decisions as inflection signals for cross-border data routing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | BSI and SecNumCloud credentials unlock German and French BFSI procurement pipelines restricted from hyperscaler-only alternatives. |
| Conversational AI Platform Integration | Large language model-powered agent assist tools compress first-contact resolution variance for Nordic banking deployments. |
| Biometric Authentication Partnership | Voice biometrics layered onto NLP workflows enables passwordless authentication reducing fraud and average handle time. |
| Vertical-Specific Template Development | Pre-configured compliance modules for insurance claims handling accelerate time-to-value for regulated sector buyers. |
| Central and Eastern European Expansion | Poland and Romania present underpenetrated markets where cloud-first financial services entrants lack legacy estate drag. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vendor financial disclosures, hyperscaler capex reports, and national data protection authority enforcement records. Interviews with contact center operations directors, IT procurement officers at European banks, compliance officers, systems integrators, and channel partners inform demand-side validation. Secondary sources include GDPR enforcement databases, EU AI Act implementation guidance, and cloud infrastructure deployment trackers. Bottom-up deployment sizing triangulates against top-down market aggregation.
Segmentation dimensions modeled span deployment architecture, end-user vertical, technology layer, and service type across the projection horizon. Deployment splits capture public, hybrid, private cloud, and on-premises persistence patterns. End-user segmentation distinguishes BFSI, healthcare, retail, and IT services demand profiles. Technology layers track AI-powered, omnichannel, VoIP, and analytics adoption curves. CAGRs derive from elasticity modeling of agent seat expansion, seasonal burst coefficients, and compliance-driven replacement cycles.
Decision-makers should treat outputs as directional under sustained EU AI Act implementation timelines and stable cross-border data transfer frameworks; material deviation in regulatory enforcement intensity or adequacy decision timing would warrant model refresh. Recalibration cycles align with material shifts in GDPR penalty patterns, sovereign cloud certification expansion, and hyperscaler regional capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Audio Conferencing Services Market
Communication Services
Cloud Communication Platform Market
Communication Services
India Communication Platform As a Service (Cpaas) Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Push-To-Talk Market
Communication Services
Pcaas Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Video Managed Services Market
Communication Services
In Flight Entertainment and Communication Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Walkie Talkie Market
Communication Services
Latin America Postal Service Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
Asia-Pacific Postal Services Market
Communication Services
North America Postal Services Market
Communication Services
High Performance Message Infrastructure Market