
 Managed Communication Services Market | 2026-2036
Managed Communication Services Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Communication Services Market Outlook
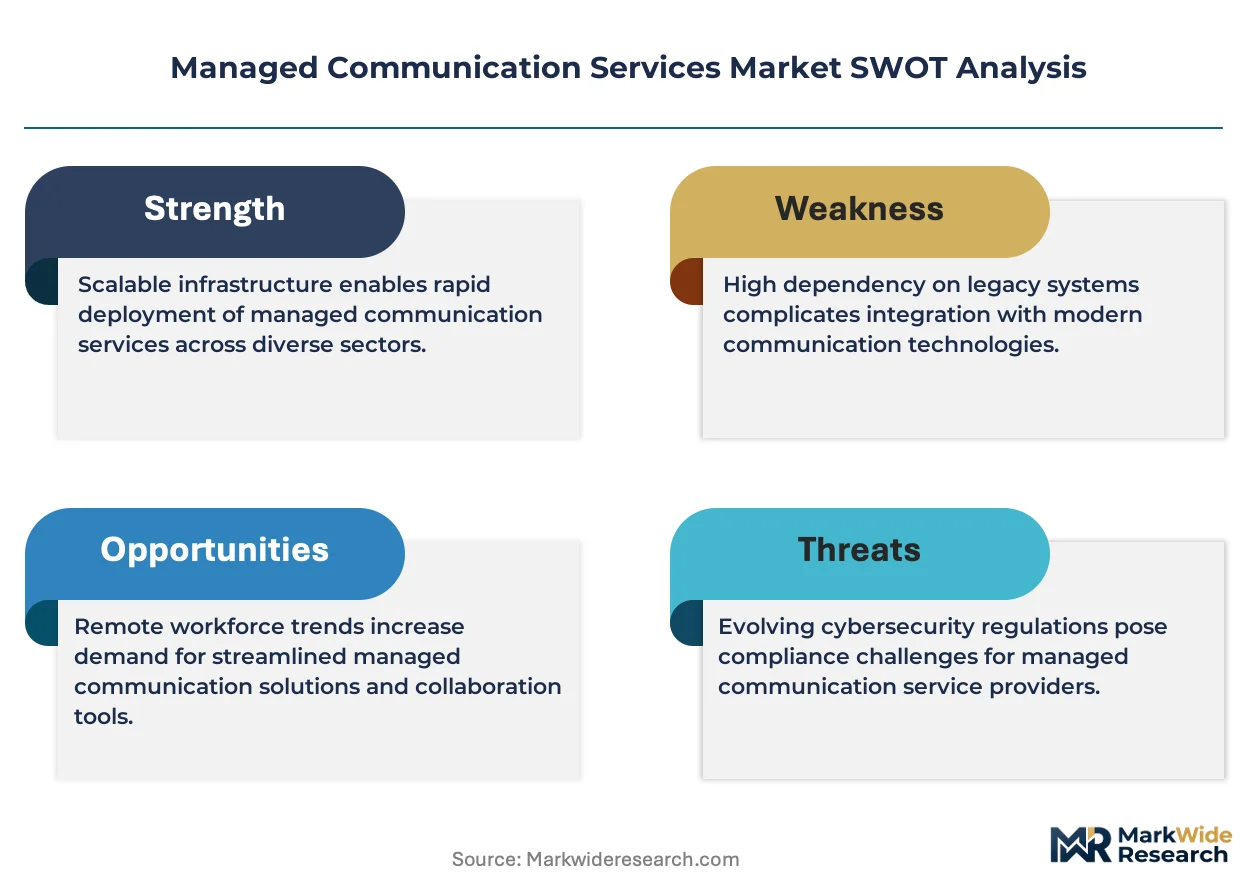
Subscription-based financing and operational leasing for communication infrastructure is tilting competitive dynamics toward asset-light providers that reduce upfront capital barriers for mid-market buyers. Cisco Systems leverages its global channel partner ecosystem to sustain hardware-software bundling across hybrid deployments. AT&T anchors its position through direct fiber ownership and managed network integration for large enterprises. Verizon Communications differentiates via verticalized security stacks embedded within its managed communication portfolios.
Managed Communication Services encompass the outsourced design, deployment, monitoring, and optimization of enterprise voice, video, messaging, and collaboration infrastructure, typically delivered through SLAs guaranteeing uptime thresholds above 99.9% and latency benchmarks critical for real-time applications. These services eliminate the need for in-house telephony expertise while ensuring interoperability across multi-vendor environments. Cloud-Based deployment now captures the dominant share of new engagements as enterprises retire legacy PBX systems, though Hybrid architectures retain margin concentration due to complexity premiums. Unified Communications represents the most mature service category with established pricing benchmarks, while Video Conferencing continues expanding fastest driven by distributed workforce normalization.
FCC net neutrality frameworks and HIPAA encryption mandates in the United States, alongside GDPR and the EU AI Act in Europe, collectively elevate compliance costs for self-managed communication stacks and redirect procurement toward certified managed service providers. ISO 27001 and SOC 2 Type II attestations have become baseline requirements for vendor qualification in regulated verticals. Stakeholders must evaluate provider resilience against evolving cross-border data localization rules and emerging encryption disclosure requirements.
Market Dynamics
Cloud migration is compressing deployment cycles for enterprise voice infrastructure while HIPAA encryption mandates and GDPR data localization rules force buyers toward certified managed service providers with pre-built compliance architectures.
Growth Catalysts
- HIPAA Encryption Mandates:US healthcare providers facing federal audit exposure are outsourcing secure messaging and telehealth infrastructure to managed providers with pre-validated compliance stacks, eliminating in-house cryptography expertise requirements.
- Industrial Cluster Concentration:Germany's Mittelstand manufacturing networks are consolidating communication spend with regional managed service specialists who bundle secure fiber access with unified collaboration platforms.
- AI-Enabled Quality Assurance:Real-time transcription and sentiment analysis tools embedded in managed contact center services are driving replacement of legacy PBX systems in financial services and insurance verticals.
Market Restraints
- Cross-Border Data Localization:EU AI Act and emerging national sovereignty rules in France, Germany, and Italy are fragmenting service architectures and forcing providers to maintain redundant in-country infrastructure.
- Specialized Engineering Talent Scarcity:SIP trunking, SBC configuration, and WebRTC optimization skills command premium compensation, constraining provider scaling velocity.
- Legacy System Entrenchment:Hybrid architectures retaining on-premises PBX elements for regulatory or latency reasons absorb disproportionate integration resources and compress service margins.
Strategic Opportunities
- Operational Leasing Models:Subscription-based financing for endpoints and infrastructure is unlocking mid-market segments previously excluded by upfront capital requirements.
- EU CSRD Alignment:Sustainability reporting mandates are creating demand for managed providers with carbon-accounted data center networks and renewable energy certificates.
- Edge Computing Convergence:Integration of 5G network slicing with managed UCaaS platforms is enabling sub-20ms latency guarantees for manufacturing and autonomous logistics applications.
Industry Challenges
- Multi-Vendor Interoperability Complexity:Enterprises running Cisco, Microsoft Teams, and Zoom simultaneously require managed providers to maintain certification across competing ecosystems.
- SOC 2 Type II Certification Timelines:Audit preparation cycles exceeding nine months delay market entry for new providers targeting financial services and healthcare verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Communication Services Market |
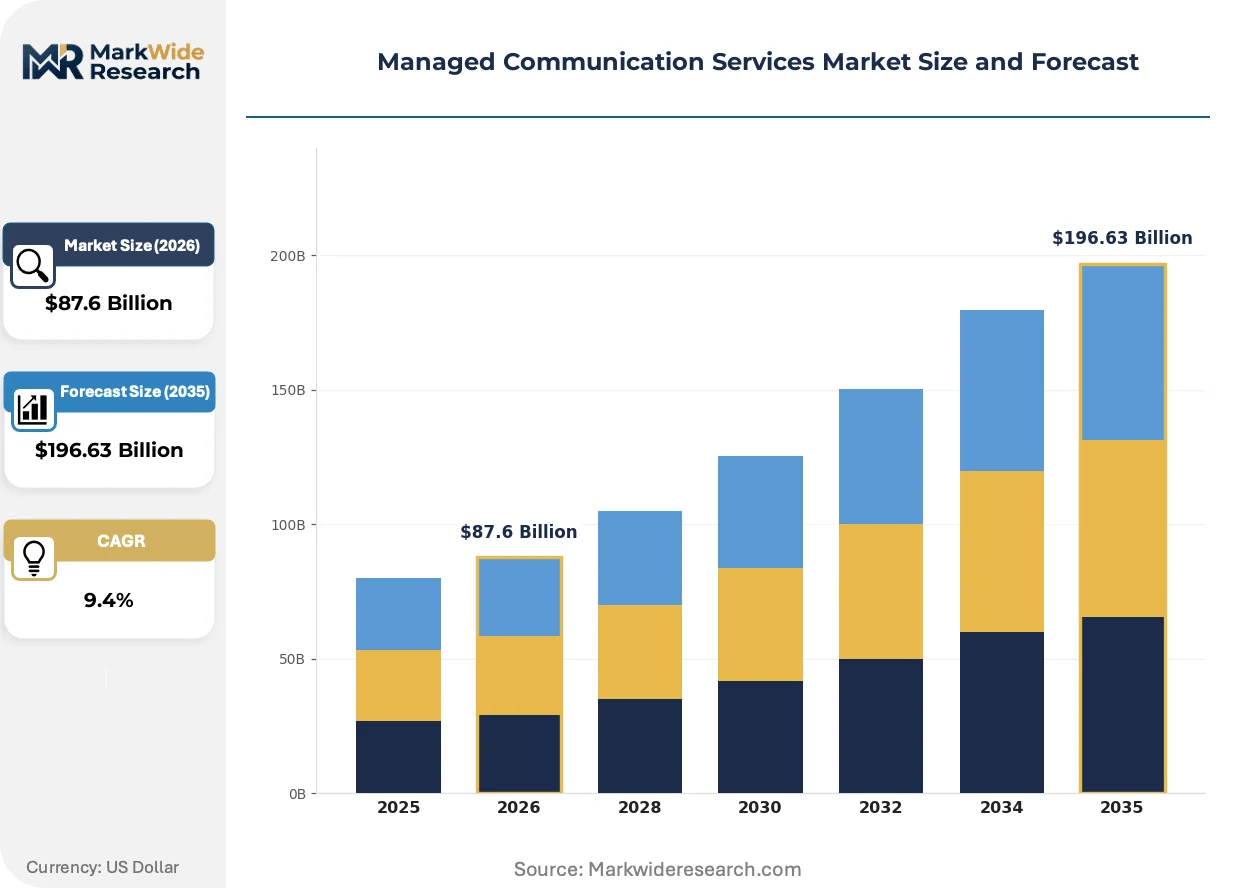
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Unified Communications, VoIP Services, Messaging Solutions, Video Conferencing Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Enterprise, SMB, Government, Non-Profit Industry Vertical: Healthcare, Education, Retail, Financial Services |
| Companies Covered | Cisco Systems, Inc., AT&T Inc., Verizon Communications Inc., NEC Corporation, Avaya Inc., RingCentral Inc., NTT DATA Group Corporation, Telefonaktiebolaget LM Ericsson, Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Communication Services Market Strategic Shifts
Artificial intelligence is embedding into every layer of managed communication infrastructure, from automated quality monitoring to predictive capacity planning, while regulatory fragmentation forces architectural specialization by geography.
WebRTC-based browser-native conferencing is rendering obsolete the traditional thick-client video applications that dominated enterprise deployments through 2022. Healthcare systems and professional services firms are adopting these zero-download platforms to eliminate endpoint management overhead. The shift is compressing vendor consolidation timelines as pure-play video specialists without browser-native architectures face technical obsolescence.
GDPR enforcement actions by CNIL in France and Hamburg's data protection authority are elevating data residency clauses to non-negotiable contract terms. German automotive suppliers and Dutch financial institutions now require managed providers to demonstrate physical server location with cryptographic attestation. This regulatory pressure is fragmenting pan-European service architectures and rewarding providers with dense in-country data center footprints.
Enterprise buyers are unbundling hardware procurement from managed service contracts, treating endpoints as separately financed assets while purchasing pure operational support. Mid-market manufacturing firms in the US Midwest and industrial regions of northern England are driving this separation, using equipment leasing specialists for phones and headsets while sourcing platform management from communication-focused providers. The bifurcation is compressing hardware margins and elevating service quality metrics as the primary competitive differentiator.
Managed Communication Services Market Segmentation
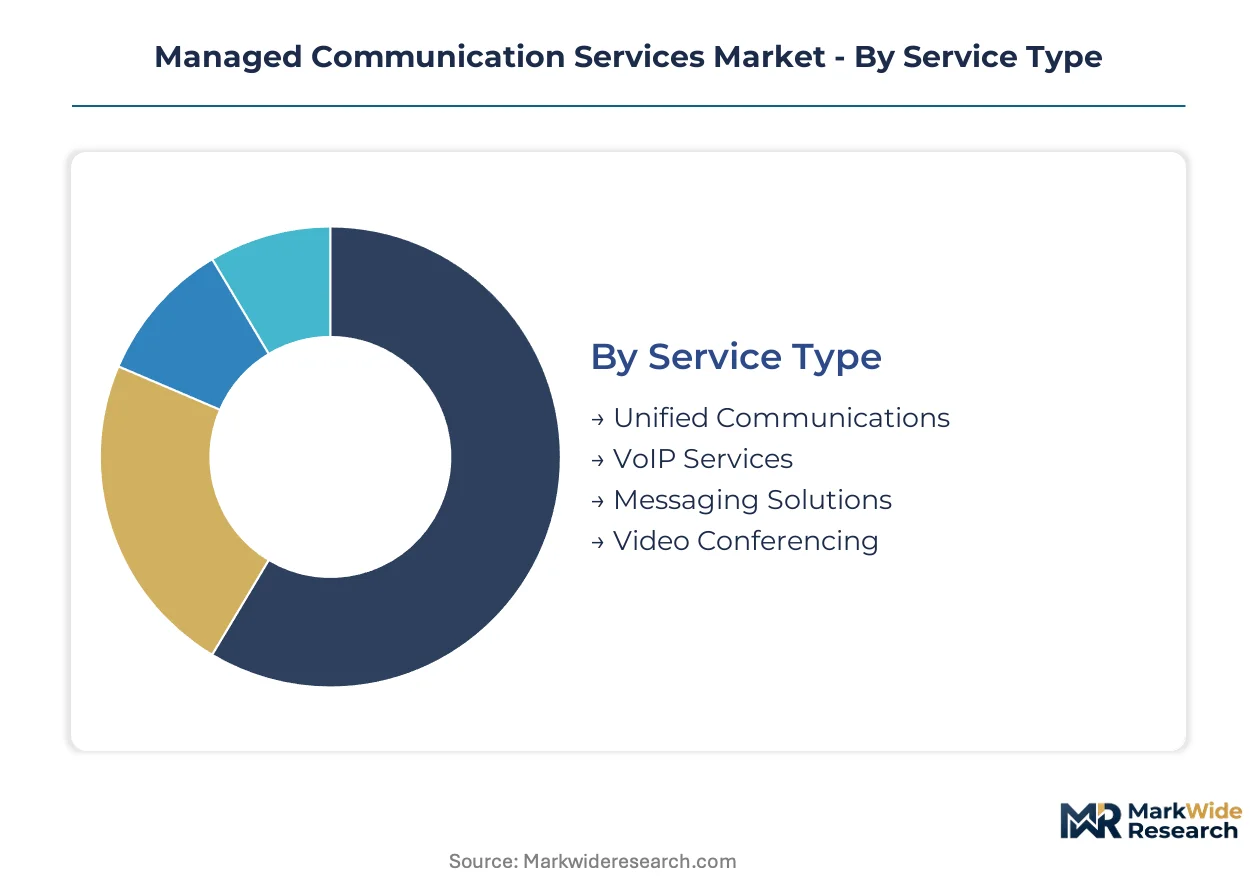
Segmentation in managed communication services reveals divergent procurement cycles across deployment architectures and end-user scale. Buyers cycle through endpoint refresh and platform migration at different velocities, creating portfolio complexity for providers managing multi-tenant infrastructure.
Service Type:
Replacement cycles vary dramatically across service categories, with video infrastructure turning over fastest as browser-native protocols displace legacy clients, while unified communications platforms exhibit slower migration patterns due to integration entrenchment.
- Unified Communications:Integrated voice, video, messaging, and collaboration platforms delivered through single-pane management consoles. Demand concentrates among German automotive suppliers and Dutch financial institutions requiring GDPR-compliant data residency with cryptographic attestation of server location.
- VoIP Services:Session Initiation Protocol trunking and cloud-based telephony replacing legacy PSTN connectivity. US healthcare providers facing HIPAA audit exposure are outsourcing secure voice infrastructure to eliminate in-house cryptography expertise requirements.
- Messaging Solutions:Secure enterprise messaging with end-to-end encryption and compliance archiving.
- Video Conferencing:WebRTC-based browser-native platforms eliminating endpoint management overhead.
Unified Communications dominates installed base. Video Conferencing is where expansion concentrates.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises builds from operational expenditure models, with hybrid architectures commanding complexity premiums while cloud deployments scale through volume efficiency.
- Cloud-Based:Fully hosted infrastructure with multi-tenant resource pooling and API-driven provisioning. Mid-market manufacturing firms across the US Midwest are driving unbundled procurement, treating endpoints as separately financed assets while purchasing pure operational support.
- Hybrid:Mixed on-premises and cloud infrastructure retaining PBX elements for regulatory or latency compliance. German Mittelstand manufacturing networks consolidate communication spend with regional specialists bundling secure fiber access with unified collaboration platforms.
- On-Premises:Self-managed infrastructure with dedicated hardware ownership.
- Managed Services:Comprehensive outsourcing encompassing design, deployment, and optimization with SLA guarantees above 99.9% uptime.
Cloud-Based deployment captures dominant new engagement share. Hybrid architectures retain margin concentration due to integration complexity.
End User:
Customer type determines contract structure and support intensity, with enterprise buyers demanding verticalized security stacks and SMB segments unlocking through subscription-based financing models.
- Enterprise:Large organizations with multi-site infrastructure requiring dedicated account management and custom integration. AT&T anchors positioning through direct fiber ownership and managed network integration, while Verizon differentiates via embedded security stacks.
- SMB:Small and medium businesses previously excluded by upfront capital barriers now accessing services through operational leasing and subscription financing.
- Government:Public sector entities with sovereign data requirements and classified communication needs.
- Non-Profit:Mission-driven organizations prioritizing cost efficiency over feature depth.
Enterprise accounts anchor provider revenue stability. SMB segments represent the steepest expansion trajectory as financing innovation unlocks access.
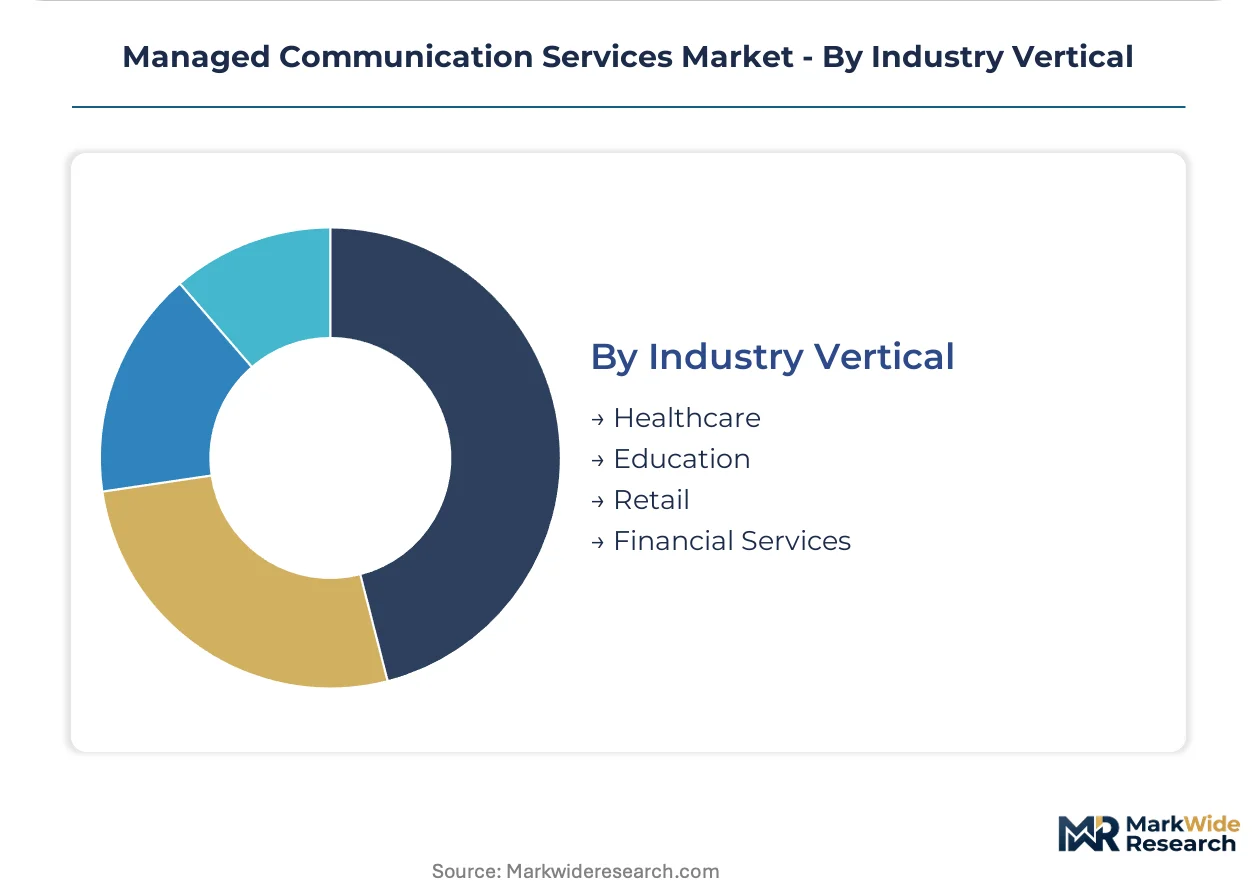
Industry Vertical:
Application-specific requirements drive vertical specialization, with regulated industries demanding pre-validated compliance architectures and commercial sectors prioritizing workforce collaboration functionality.
- Healthcare:HIPAA-mandated encryption and audit-ready infrastructure for telehealth and secure messaging. US providers facing federal audit exposure outsource to managed providers with pre-built compliance stacks.
- Financial Services:SOC 2 Type II attestation requirements and real-time quality assurance through AI-enabled transcription and sentiment analysis.
- Education:Scalable platforms supporting distributed learning with simplified endpoint management.
- Retail:Customer-facing communication integration with omnichannel service delivery.
Healthcare leads compliance-driven procurement. Financial Services is climbing the fastest through AI-enabled contact center replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC net neutrality enforcement and HIPAA encryption mandates in the United States, alongside GDPR and the EU AI Act in Europe, are redirecting procurement toward certified managed service providers with pre-built compliance architectures. German industrial clusters and US healthcare systems are accelerating cloud migration while demanding cryptographic attestation of data residency. Fragmented sovereignty rules are forcing redundant in-country infrastructure investments across major economies.
United States
Healthcare providers facing federal HIPAA audit exposure are outsourcing secure messaging and telehealth infrastructure to eliminate in-house cryptography expertise requirements. FCC frameworks govern net neutrality for managed network services. The US Midwest manufacturing belt is driving unbundled procurement patterns, treating endpoints as separately financed assets while sourcing pure operational support from communication specialists.
Germany
Mittelstand manufacturing networks are consolidating communication spend with regional managed service specialists who bundle secure fiber access with unified collaboration platforms. The EU AI Act and GDPR data localization rules enforce strict cross-border data governance. Industrial clusters in Baden-Württemberg and Bavaria prioritize outsourced communication infrastructure with certified ISO 27001 and SOC 2 Type II attestations.
United Kingdom
Financial services firms are adopting AI-enabled quality assurance through real-time transcription and sentiment analysis tools embedded in managed contact center services. GDPR compliance requirements align with post-Brexit data protection frameworks. London's fintech concentration is demanding sub-20ms latency guarantees through 5G network slicing integration with managed UCaaS platforms.
Japan
Enterprise buyers are retiring legacy PBX systems in favor of cloud-based unified communications with multi-tenant resource pooling and API-driven provisioning. METI industrial policy supports digital transformation of communication infrastructure. Manufacturing hubs in the Chubu region around Nagoya are implementing hybrid architectures retaining on-premises elements for regulatory compliance.
France
CNIL enforcement actions are elevating data residency clauses to non-negotiable contract terms for managed communication services. GDPR physical server location requirements now demand cryptographic attestation. Automotive suppliers in the Île-de-France region require providers to demonstrate in-country data center footprints with carbon-accounted networks and renewable energy certificates.
Managed Communication Services Market Competitive Environment
On the supply side, the industry is consolidating around telecommunications incumbents with direct infrastructure ownership, global technology vendors with channel partner ecosystems, and cloud-native specialists with subscription-based financing models. Three strategic archetypes dominate: fiber-owning carriers anchoring large enterprise accounts, hardware-software bundlers sustaining hybrid deployment margins, and asset-light providers unlocking mid-market segments through operational leasing. Competitive intensity centers on verticalized security stack differentiation and geographic compliance certification velocity.
Within the telecommunications carrier tier, AT&T anchors positioning through direct fiber ownership and managed network integration for enterprise accounts, while Verizon occupies a differentiated position via embedded security stacks within managed communication portfolios. Cisco Systems exemplifies the hardware-software bundler archetype, leveraging global channel partnerships to sustain hybrid deployment economics across multi-vendor environments. These three entities represent the dominant competitive vectors shaping procurement patterns in regulated verticals.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| AT&T Inc. |
| Verizon Communications Inc. |
| NEC Corporation |
| Avaya Inc. |
| RingCentral Inc. |
| NTT DATA Group Corporation |
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Others |
Value Chain & Pricing Dynamics
Transatlantic fiber cable routes between the United States and Germany carry the bulk of managed communication service provisioning costs, concentrating pricing power among carriers with direct infrastructure ownership while forcing asset-light providers toward subscription financing models that absorb freight and latency premium differentials.
Pricing Analysis
Certification level creates the primary spread between premium and standard service tiers, with ISO 27001 and SOC 2 Type II attestation commanding substantial premiums in healthcare and financial services verticals. Three-tier pricing structure across premium, standard, and economy levels dominates contract structures, though cost compression in the economy tier is intensifying because WebRTC commoditization eliminates endpoint management overhead. Mid-market manufacturing firms in the US Midwest exhibit highest price sensitivity, while German Mittelstand networks prioritize certified data residency over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for endpoint hardware and data center equipment, forcing providers toward diversified sourcing. Component manufacturing concentrates in Taiwan for semiconductors, China for optical networking gear, and Germany for precision industrial communication systems. Raw material dependencies include rare earth elements for fiber amplifiers, silicon photonics chips, and lithium for backup power systems. Distribution runs through carrier-direct channels for enterprise accounts and channel partner ecosystems for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed communication services constitute a defensive-moat market where regulatory certification entrenchment creates switching costs that lock enterprise buyers into validated provider relationships, with HIPAA and GDPR compliance architecture serving as the primary structural barrier to displacement.
For Market Incumbents: Build switching-cost moats through embedded compliance architecture that integrates HIPAA encryption stacks and GDPR data residency attestation directly into client operational workflows. Deepen fiber ownership in Germany's industrial clusters to defend against regional specialist encroachment. Acquire AI-enabled quality assurance capabilities to preempt contact center replacement cycles in financial services. For New Entrants and Emerging Players: France's CNIL enforcement gap in carbon-accounted data center networks offers immediate white-space opportunity for providers with renewable energy certificates and cryptographic server location proof. Target mid-market manufacturing firms in northern England with unbundled procurement models separating endpoint financing from operational support. Enter through operational leasing partnerships with equipment financing specialists to bypass capital barrier exclusion. For Investors and Strategic Acquirers: Carve-out targets emerge from telecommunications incumbents divesting non-core managed service units to focus on core infrastructure ownership. Long-term viability rests on regulatory certification velocity rather than technology differentiation, favoring providers with established audit relationships over pure-play innovators. Watch AI-enabled contact center replacement rates in insurance verticals as inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Acceleration | ISO 27001 and SOC 2 Type II pre-validation unlocks healthcare and financial services procurement cycles. |
| Edge Computing Infrastructure Deployment | 5G network slicing integration with UCaaS platforms enables sub-20ms latency guarantees for manufacturing. |
| Carbon-Accounted Data Center Expansion | EU CSRD alignment with renewable energy certificates captures sustainability-mandated procurement in France. |
| AI-Enabled Contact Center Integration | Real-time transcription and sentiment analysis tools drive legacy PBX replacement in insurance verticals. |
| Operational Leasing Partnership | Subscription financing models unlock mid-market segments previously excluded by upfront capital barriers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs at German automotive suppliers, IT procurement officers at US healthcare systems, channel partners in the Cisco ecosystem, and integration specialists managing multi-vendor Microsoft Teams and Zoom environments. Secondary validation drew from SEC filings of telecommunications carriers, hyperscaler capex disclosures, GDPR enforcement actions by CNIL and Hamburg data protection authorities, and FCC net neutrality frameworks. Bottom-up and top-down triangulation cross-checked service provider capacity announcements against enterprise buyer procurement pipeline data.
Calibration against historical adoption curves for cloud-based unified communications and hybrid architecture migrations shaped the analytical framework across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user scale, industry vertical compliance requirements, and geographic data residency clusters. CAGRs were derived from fitted growth curves adjusted for regulatory enforcement timing and technology substitution rates, with WebRTC displacement timelines and AI contact center replacement cycles serving as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud entrants or sovereign infrastructure nationalization would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Industrial Communication Market
Communication Services
Latin America Postal Service Market
Communication Services
Speech to Speech Translation Market
Communication Services
North America Postal Services Market
Communication Services
Mobile Messaging Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Global Passenger Information System Market
Communication Services
Meeting Solutions Market
Communication Services
In Flight Entertainment and Communication Market
Communication Services
Dispatch Console Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Consumer Communication Services Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Voice Commerce Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Cloud Communication Platform Market