
 Direct-To-Home (DTH) Satellite TV Services Market | 2026-2036
Direct-To-Home (DTH) Satellite TV Services Market Size, Share, and Industry Trends Forecast 2026-2036
Direct-To-Home (DTH) Satellite TV Services Market Outlook
Middle East orbital slot expansion is narrowing the availability of premium Ku-band capacity for DTH operators across the region. DIRECTV leverages its extensive satellite fleet to sustain coverage density across the Americas. Dish Network anchors rural subscriber retention through proprietary set-top box integration and bundled broadband offerings. Sky competes aggressively on premium sports content licensing to differentiate its European satellite portfolio.
Direct-To-Home (DTH) Satellite TV Services deliver television programming via geostationary satellites directly to individual subscriber premises using parabolic antennas typically measuring 60-90 centimeters in diameter, with signals encoded through DVB-S2 modulation standards enabling spectral efficiency above 4 bits per second per Hertz. The primary commercial purpose centers on distributing linear broadcast channels and on-demand content to households beyond reliable terrestrial cable or fiber infrastructure. High Definition service tiers currently generate the majority of revenue across residential customer segments, while Ultra High Definition remains concentrated among premium subscribers seeking enhanced resolution for live sports and cinematic programming. IP-Based Delivery technology is expanding fastest as operators integrate hybrid satellite-broadband architectures to support interactive and streaming functionalities without abandoning core broadcast reliability.
The FCC governs orbital debris mitigation and spectrum allocation for US-based DTH operators, while the EU's Audiovisual Media Services Directive shapes content quotas and advertising standards across European satellite markets. Brazil's ANATEL enforces set-top box interoperability mandates that influence hardware procurement cycles for regional operators. Stakeholders must monitor evolving spectrum reallocation debates between satellite broadcasters and terrestrial 5G interests as these determine long-term transponder viability and capital deployment priorities.
Market Dynamics
Spectrum reallocation debates between satellite broadcasters and terrestrial 5G interests are compressing long-term transponder viability and forcing capital deployment toward hybrid architectures.
Growth Catalysts
- India's TRAI packaging mandates:Pricing transparency rules are expanding subscriber access across rural residential segments as operators simplify tariff structures.
- DVB-S2X encoding:Advanced modulation standards are unlocking spectral efficiency gains above 5 bits per second per Hertz for Ultra High Definition distribution.
- Brazil-Mexico sports demand:Premium live content consumption is accelerating transponder capacity upgrades across Latin American orbital positions.
Market Restraints
- Ku-band scarcity:Middle East orbital slot expansion is narrowing premium capacity availability for established DTH operators.
- 5G terrestrial encroachment:C-band reallocation proceedings in multiple jurisdictions are threatening legacy broadcast spectrum assignments.
- Fiber backhaul gaps:Rural broadband infrastructure deficits limit hybrid satellite-IP service quality in emerging economies.
Strategic Opportunities
- Sub-Saharan Africa:Underpenetrated markets beyond reliable terrestrial infrastructure present greenfield subscriber acquisition potential.
- Connected set-top convergence:Integration of streaming applications with broadcast receivers is opening new revenue streams from advertising and data analytics.
- EU Green Deal alignment:Energy efficiency mandates for consumer electronics are creating competitive differentiation for low-power receiver designs.
Industry Challenges
- RF engineering talent:Specialized satellite communications expertise shortages are delaying network optimization and new service rollouts.
- Legacy MPEG-2 migration:Decommissioning outdated encoding infrastructure requires coordinated subscriber equipment replacement programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct-To-Home (DTH) Satellite TV Services Market |
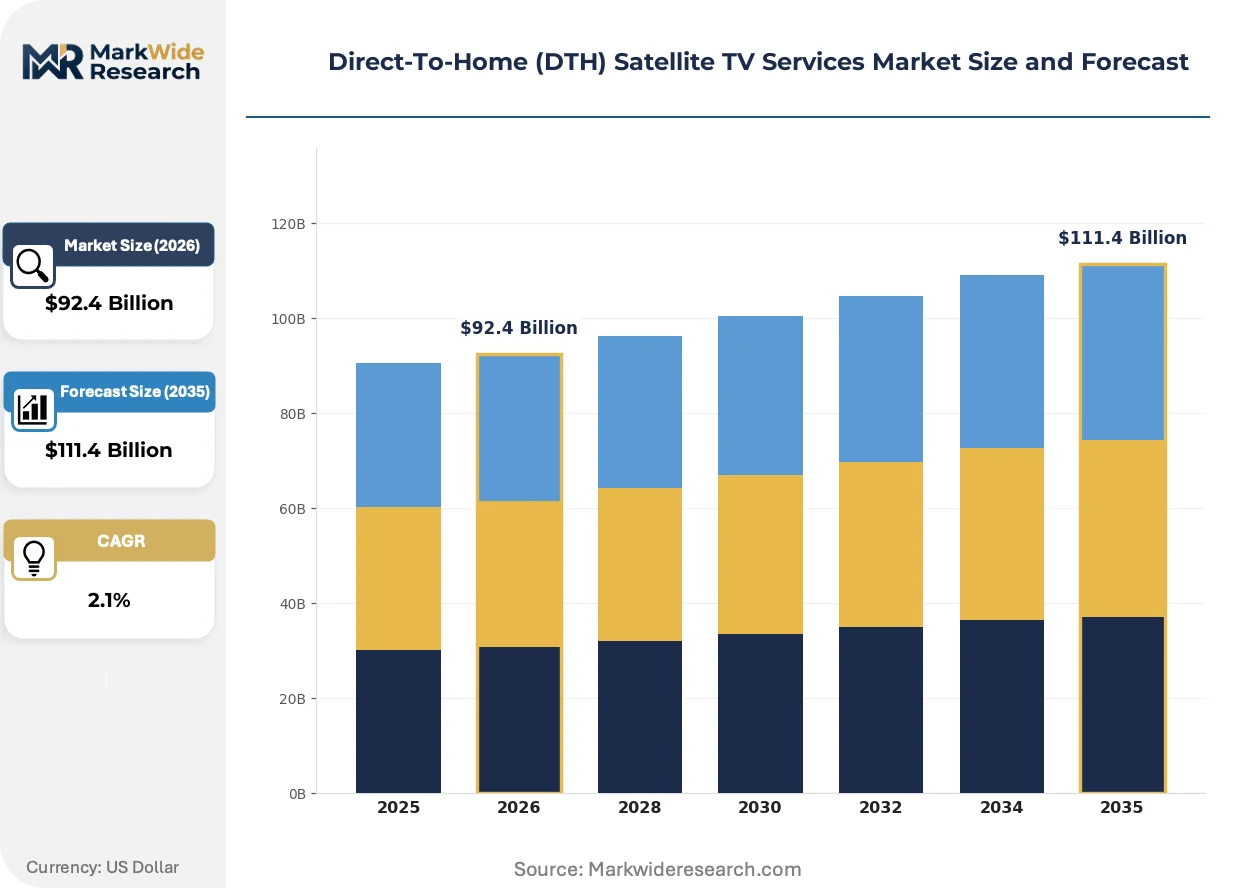
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $111.4 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Definition, High Definition, Ultra High Definition, 3D Content Technology: Broadcast Satellite, IP-Based Delivery, Hybrid Satellite, DVB-S2 Customer Type: Residential, Commercial, Hospitality, Institutional Distribution Channel: Direct Sales, Online Platforms, Retail Outlets, Subscription Packages |
| Companies Covered | Sling TV, Hulu + Live TV, DIRECTV, Philo, FuboTV, Dish Network, YouTube TV, Sky, AT&T, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct-To-Home (DTH) Satellite TV Services Market Strategic Shifts
Hybrid satellite-broadband architectures are redefining service delivery models as operators balance broadcast reliability with interactive functionality demands.
HbbTV 2.0 specification deployment is enabling broadcast-broadband convergence through standardized application environments. European operators are integrating these capabilities across premium tier deployments. Linear broadcast infrastructure is rendering obsolete standalone IP-only delivery strategies for mass-market television distribution.
ANATEL's set-top box interoperability mandates in Brazil are forcing hardware procurement standardization across regional supply chains. Manufacturers must certify devices against unified technical specifications. Smaller operators lacking procurement scale face compressed margin structures as equipment costs homogenize.
Rural subscriber retention strategies now emphasize bundled broadband rather than standalone video pricing. Dish Network and regional competitors are restructuring service tiers around connectivity convergence. Latin American markets exhibit the most pronounced shift toward integrated communications packages.
Direct-To-Home (DTH) Satellite TV Services Market Segmentation
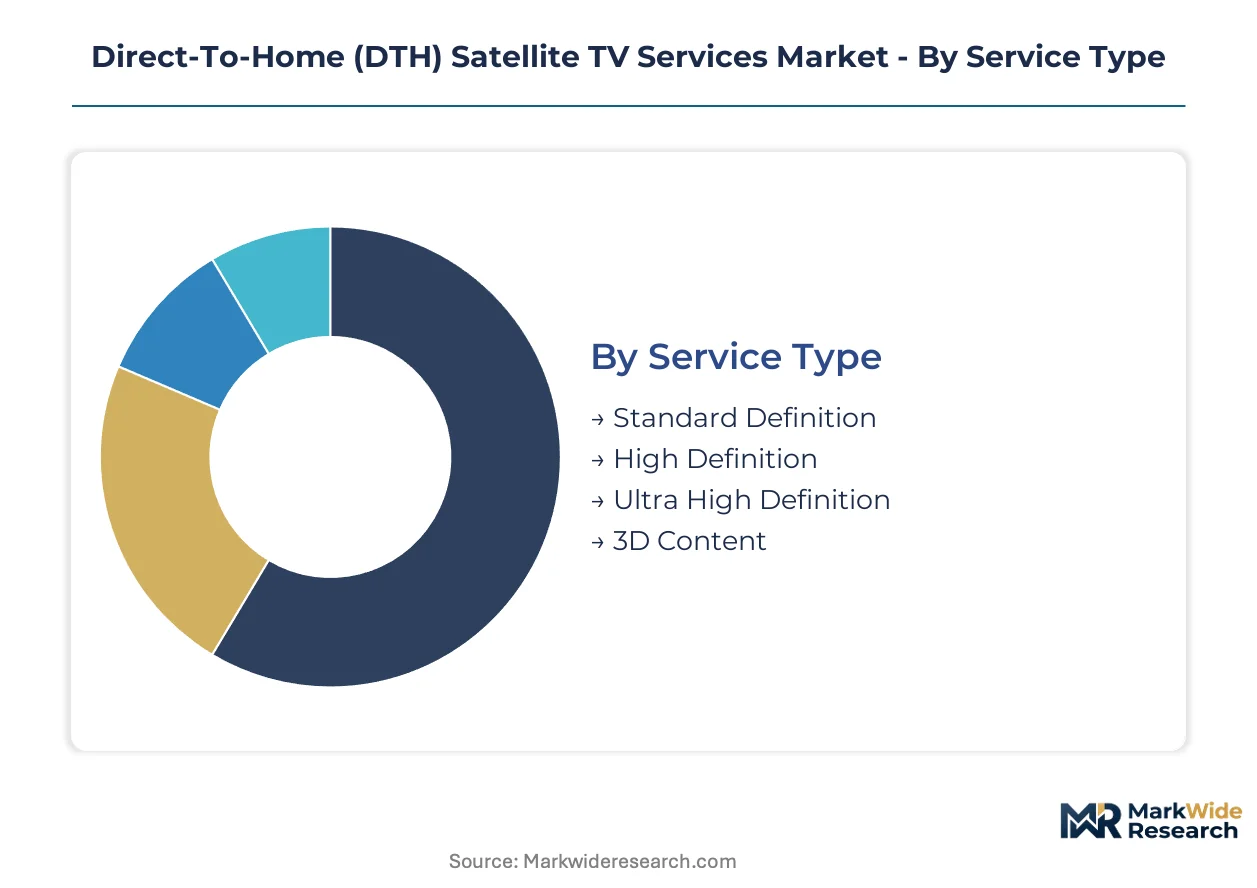
DTH operators structure service portfolios around resolution tiers, delivery architectures, and subscriber density patterns. Segmentation discipline determines capital allocation across transponder capacity, encoding infrastructure, and customer acquisition channels.
Service Type:
Resolution tiers exhibit starkly different replacement cycles, with Ultra High Definition turning over every 3-4 years as display technology advances while Standard Definition enters terminal decline.
- High Definition:DVB-S2 modulation at 1080i or 1080p resolution currently generates the majority of residential revenue across mature markets. Demand concentrates in Brazil and Mexico where sports broadcasters prioritize bandwidth-efficient premium tier distribution.
- Ultra High Definition:4K resolution at 2160p with High Dynamic Range requires HEVC encoding and expanded transponder capacity. Latin American operators lead deployment as live sports consumption drives subscriber willingness to pay premium tariffs.
- Standard Definition:Legacy 576i/480i resolution persists in price-sensitive rural segments across India and sub-Saharan Africa.
- 3D Content:Stereoscopic programming remains confined to niche cinematic and sports applications with limited broadcaster commitment.
High Definition anchors the volume base while Ultra High Definition gains share at the steepest rate.
Technology:
Cost tier structures separate broadcast-only deployments from hybrid architectures requiring broadband backhaul investment.
- IP-Based Delivery:Streaming-over-satellite architectures integrate multicast IP with conditional access systems. European operators deploy HbbTV 2.0 specifications to enable broadcast-broadband convergence for interactive services.
- Hybrid Satellite:Combined satellite downlink with terrestrial return path supports video-on-demand and interactive applications. Dish Network leverages this architecture for rural broadband bundling in the United States.
- Broadcast Satellite:Traditional unidirectional DVB-S2 transmission remains dominant in emerging markets with limited fiber infrastructure.
- DVB-S2:The foundational modulation standard enables spectral efficiency above 4 bits per second per Hertz across legacy receiver populations.
Broadcast Satellite carries the installed base while IP-Based Delivery climbs the fastest as operators retrofit hybrid capabilities.
Customer Type:
Application concentration varies sharply, with Residential subscribers demanding linear channel stability while Commercial segments prioritize customizable content packages.
- Residential:Individual household subscriptions drive volume economics across all geographies. India's TRAI packaging mandates are expanding rural access through simplified tariff structures.
- Hospitality:Hotels and resorts require centralized headend systems with room-specific control interfaces. Latin American tourism corridors generate concentrated demand for multi-language premium sports tiers.
- Commercial:Bars, restaurants, and public venues need public performance licensing and scalable screen configurations.
- Institutional:Educational and government facilities prioritize cost-controlled basic tier access with limited premium content requirements.
Residential anchors subscriber volume while Hospitality expands most quickly as tourism infrastructure recovers across priority markets.
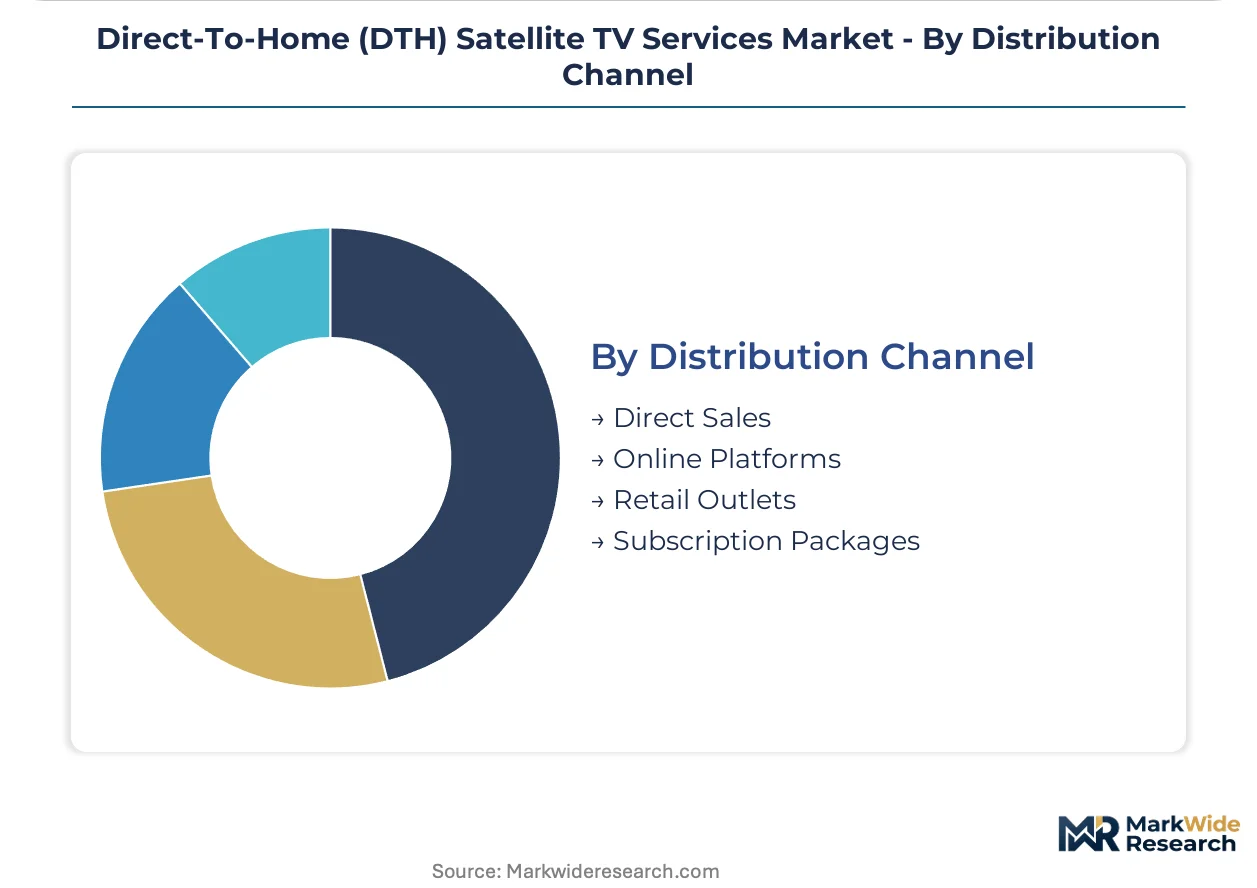
Distribution Channel:
Customer acquisition economics favor direct digital engagement over physical retail presence in markets with mature broadband penetration.
- Subscription Packages:Bundled channel tiers with annual commitments generate predictable recurring revenue and reduce churn. Brazilian operators structure these around regional sports rights concentration.
- Online Platforms:Digital self-service activation and device provisioning reduce subscriber acquisition costs. Indian operators leverage these for rural market expansion beyond traditional retail reach.
- Direct Sales:Field technician installation ensures proper antenna alignment and conditional access activation.
- Retail Outlets:Electronics stores and dedicated service centers support hardware replacement and account management in markets with lower digital literacy.
Subscription Packages dominate revenue contribution while Online Platforms gain share at the steepest rate as operators digitize customer journeys.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orbital slot allocation and spectrum licensing frameworks concentrate DTH infrastructure investment in markets with mature broadcast regulation and underserved terrestrial alternatives. Transponder capacity deployment follows subscriber density patterns across rural-urban divides.
United States
Rural broadband gaps sustain demand for hybrid satellite-IP service bundles. The FCC enforces orbital debris mitigation standards that shape fleet replacement cycles. Dish Network anchors subscriber retention through proprietary set-top integration in Midwest and Mountain West markets.
Brazil
Live sports consumption drives Ultra High Definition capacity upgrades across premium tiers. ANATEL mandates set-top box interoperability that standardizes hardware procurement for regional operators. São Paulo anchors pay-TV subscriber concentration while northern states expand rural access.
India
TRAI packaging transparency rules simplify tariff structures for price-sensitive rural households. The regulator's interoperability mandates accelerate set-top replacement programs. Maharashtra and Gujarat lead subscriber density as broadcasters deploy DVB-S2X encoding for spectral efficiency gains.
Germany
EU Green Deal energy efficiency standards differentiate low-power receiver designs in retail channels. The Audiovisual Media Services Directive shapes content quotas for satellite distribution. Bavaria and North Rhine-Westphalia concentrate headend infrastructure for Central European beam coverage.
Mexico
Regional sports rights concentration structures premium tier pricing for Latin American beam capacity. The national telecommunications regulator enforces must-carry obligations for public service channels. Mexico City Metro anchors subscriber volume while Yucatán Peninsula tourism corridors drive hospitality segment demand.
Direct-To-Home (DTH) Satellite TV Services Market Competitive Environment
Legacy satellite fleet operators and streaming-integrated platforms split the market along infrastructure ownership lines. Consolidation characterizes mature markets where orbital slot scarcity limits new entrant viability. Three archetypes dominate: transponder-heavy incumbents with captive satellite capacity, broadband-anchored challengers bundling connectivity, and IP-native services leveraging third-party distribution. Capacity expansion and strategic content licensing constitute the primary competitive vectors as operators defend subscriber bases against terrestrial alternatives.
Among transponder-heavy incumbents, DIRECTV and Dish Network occupy positions defined by captive orbital infrastructure and rural market penetration. Sky exemplifies the premium content licensing archetype through European sports portfolio concentration. These three operators anchor strategic positioning across Americas and European markets without identical service architectures.
| Leading Market Players |
|---|
| Sling TV |
| Hulu + Live TV |
| DIRECTV |
| Philo |
| FuboTV |
| Dish Network |
| YouTube TV |
| Sky |
| AT&T |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Ku-band transponder leasing from Middle East orbital slots compresses pricing tier spreads while forcing supply chain restructuring toward hybrid IP architectures. This chokepoint simultaneously elevates premium tier tariffs for Ultra High Definition capacity and accelerates equipment procurement cycles as operators seek spectral efficiency gains.
Pricing Analysis
India's TRAI packaging mandates dictate the pricing tier structure across emerging market deployments, mandating transparency that collapses opaque bundling practices. Three-tier pricing structure across premium, standard, and economy levels separates Ultra High Definition sports tiers from High Definition base packages and residual Standard Definition rural offerings. Cost compression in economy tiers is intensifying because of set-top box interoperability mandates forcing hardware standardization. Rural residential segments exhibit highest price sensitivity while hospitality buyers in Latin American tourism corridors absorb premium tariffs without volume negotiation.
Supply Chain Analysis
Extended payment terms from satellite manufacturers to launch service providers now stretch across 18-24 month deployment cycles, restructuring working capital requirements for fleet operators. Transponder manufacturing concentrates in the United States, France, and Japan, while set-top box assembly feeds from China, Vietnam, and Mexico. Component sourcing draws from gallium nitride amplifier substrates, high-efficiency solar cells, and DVB-S2X chipset fabrication. Single-source vulnerability in solid-state power amplifier supply creates fleet replacement scheduling risk. Distribution runs through direct operator procurement for transponder capacity and tiered electronics distributors for consumer premises equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rural broadband penetration gaps across sub-Saharan Africa and South Asia represent early-cycle expansion tailwinds, as terrestrial infrastructure deficits sustain satellite-dependent subscriber acquisition well beyond the analysis window.
For Market Incumbents: Entrench orbital slot control through accelerated fleet replacement programs ahead of 5G spectrum reallocation deadlines. Lock in long-term transponder leasing structures with emerging market broadcasters to preempt IP-native streaming challengers. Prioritize backward integration into encoding infrastructure to capture DVB-S2X efficiency gains as a margin defense against hybrid broadband competitors. For New Entrants and Emerging Players: Mid-market hospitality installations in Southeast Asian tourism corridors represent the most penetrable entry point, as legacy operators underinvest in multi-language premium sports tier localization. Sub-Saharan African residential markets beyond fiber backhaul reach offer greenfield subscriber bases with limited incumbent saturation. Pursue white-label set-top manufacturing partnerships to bypass ANATEL-style interoperability certification barriers and accelerate time-to-market. For Investors and Strategic Acquirers: C-band reallocation proceedings across multiple jurisdictions reshape the acquisition landscape, elevating stranded asset risk for transponder-heavy operators while rewarding hybrid IP-architecture holdings. Five-to-ten year viability favors targets with demonstrated HbbTV 2.0 deployment capabilities and proven rural broadband bundling economics. Monitor FCC orbital debris mitigation enforcement intensity as the critical signal for fleet replacement capex inflection and incumbent balance sheet stress.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Satellite-Broadband Architecture Deployment | Dish Network's rural bundling model demonstrates subscriber retention gains from connectivity convergence. |
| DVB-S2X Encoding Infrastructure Upgrade | Spectral efficiency above 5 bits per second per Hertz unlocks Ultra High Definition capacity without transponder expansion. |
| Connected Set-Top Platform Integration | HbbTV 2.0 specification adoption enables advertising and data analytics revenue streams beyond subscription tariffs. |
| Orbital Slot Capacity Expansion | Middle East Ku-band scarcity elevates premium positioning for operators with secured geostationary real estate. |
| Rural Market Direct Digital Distribution | India's online platform activation models reduce subscriber acquisition costs beyond traditional retail infrastructure. |
Study Parameters
A standing panel of satellite fleet operations executives, broadcast technology procurement directors, regulatory affairs specialists at TRAI and ANATEL, and rural market distribution heads provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against FCC spectrum allocation filings, Eutelsat and Intelsat capacity disclosure documents, ITU orbital registry databases, and DVB technical specification releases. Bottom-up subscriber and transponder utilization estimates triangulated against top-down market value reconstructions.
Scenario-bracketing framed analytical approach across the projection horizon, with conservative and expansion cases bound by 5G reallocation timing uncertainty and hybrid adoption elasticity. Segmentation dimensions modeled encompass resolution tier migration patterns, delivery architecture evolution from broadcast-only to IP-integrated, customer type concentration shifts, and regional regulatory cluster differentiation. CAGRs derived from fitted adoption curves against historical DVB standard transition precedents, with transponder capacity utilization rates and set-top replacement cycles as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in emerging market currency stability, rural disposable income trajectories, or launch cost inflation would shift the trajectory. Forecasts reflect documented assumptions regarding spectrum policy continuity and encoding standard adoption timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
High Performance Message Infrastructure Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Outbound Telemarketing Market
Communication Services
Mobile Messaging Market
Communication Services
Postal Services Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Voice Commerce Market
Communication Services
Meeting Solutions Market
Communication Services
Dispatch Console Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Broadcasting Solutions Market
Communication Services
Global Passenger Information System Market
Communication Services
Pcaas Market
Communication Services
Industrial Communication Market
Communication Services
Walkie Talkie Market
Communication Services
Global Critical Communication Market