
 Pcaas Market | 2026-2036
Pcaas Market Size, Share, and Industry Trends Forecast 2026-2036
Pcaas Market Outlook
Software-defined feature licensing is rebalancing what hardware OEMs monetize across the contract term. HP Inc. leverages its endpoint security stack to differentiate multi-year PCaaS bundles. Dell Technologies Inc. anchors enterprise deployments with integrated asset recovery and carbon reporting services.
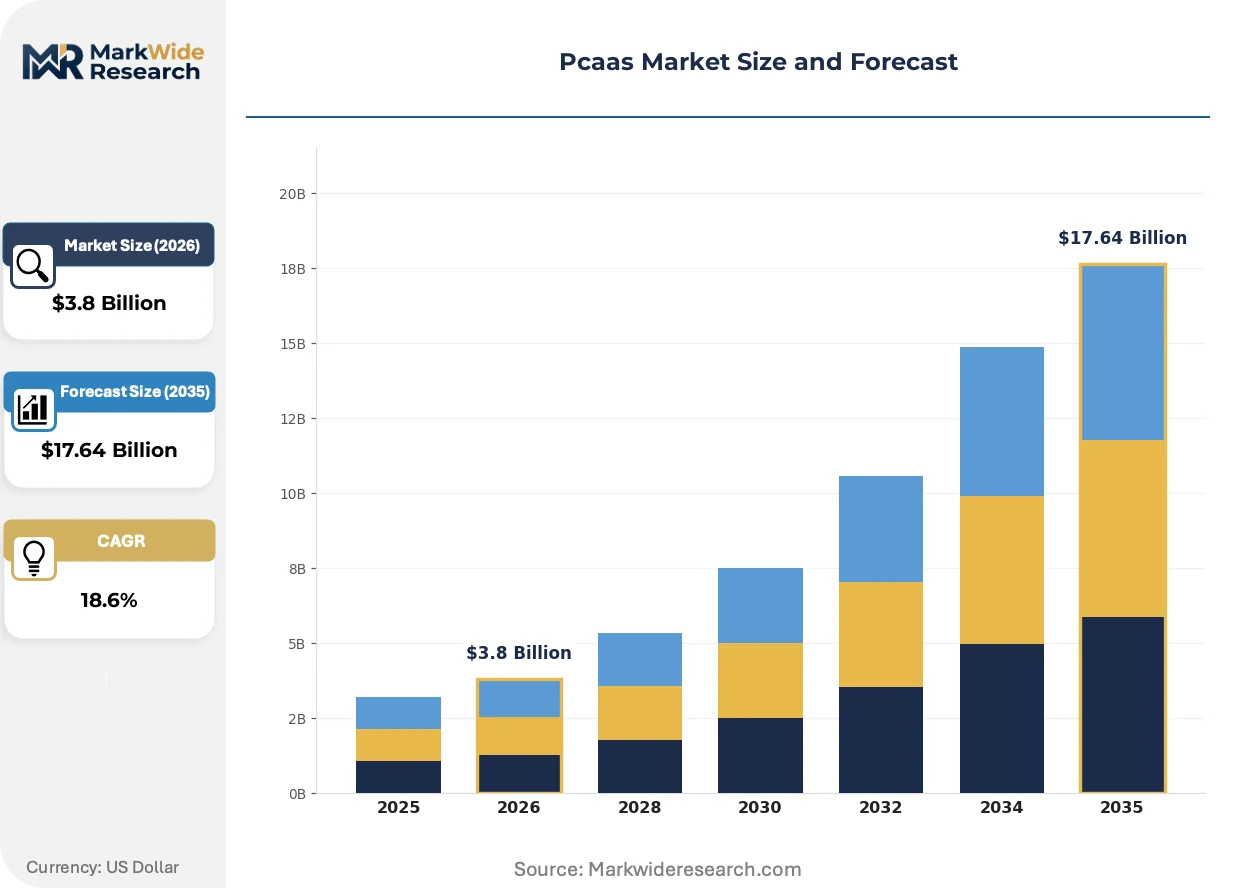
PC as a Service (PCaaS) delivers compute hardware through subscription contracts bundling procurement, deployment, support, and end-of-life recovery, typically spanning 24-to-60 month terms with per-seat monthly pricing. The model shifts balance-sheet ownership from buyer to vendor while embedding remote monitoring and predictive failure management. Managed Services within the Service Type dimension commands the dominant margin pool due to recurring revenue stickiness and lower customer acquisition costs versus Professional Services engagements. Hybrid Cloud deployment configurations are expanding fastest as regulated industries require on-premise data residency for sensitive workloads while leveraging cloud-based management planes.
FDA cybersecurity guidance for networked medical devices, HIPAA administrative safeguards, and the EU AI Act's risk classification system shape product roadmaps and liability structures for PCaaS providers serving healthcare and public-sector end users. The SEC's climate disclosure rules and CSRD reporting obligations in Europe further compel vendors to embed Scope 3 emissions tracking into device lifecycle services. Stakeholders must evaluate whether their current PCaaS contracts capture sufficient telemetry for emerging regulatory attestation requirements.
Market Dynamics
Enterprise IT departments are shifting capital expenditure to operational expenditure models under pressure from cloud-first mandates, fundamentally restructuring how compute hardware is procured, managed, and retired across distributed workforces.
Growth Catalysts
- EU NIS2 Directive:The cybersecurity framework mandates managed endpoint services for critical infrastructure operators, accelerating compliance-driven procurement of standardized device lifecycle management.
- Hybrid Cloud deployment:Regulated industries require on-premise data residency for sensitive workloads while leveraging cloud-based management planes, expanding configuration flexibility.
- United States demand concentration:Distributed workforces across healthcare, financial services, and public sector require scalable PCaaS standardization at enterprise scale.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fabrication dominance creates vulnerability in processor and memory availability for multi-year fleet contracts.
- CSRD reporting friction:The EU's Corporate Sustainability Reporting Directive imposes granular Scope 3 emissions tracking requirements that strain vendor data collection infrastructure.
- Residual value volatility:Secondary market pricing for enterprise laptops fluctuates with component obsolescence cycles, compressing contract profitability margins.
Strategic Opportunities
- Germany manufacturing vertical:Industrial automation and automotive suppliers present underpenetrated demand for ruggedized device-as-a-service with predictive maintenance integration.
- SEC climate disclosure alignment:US-listed enterprises require embedded carbon accounting in vendor contracts, creating differentiation for providers with verified lifecycle emissions data.
- Zero Trust architecture convergence:Integration of hardware security modules with identity management platforms enables premium positioning in federal and healthcare procurement.
Industry Challenges
- FDA 510(k) cybersecurity documentation:Medical device manufacturers face extended validation timelines when networked endpoints require premarket clearance for software update mechanisms.
- Legacy asset data migration:Enterprises with heterogeneous device estates struggle to consolidate telemetry from disparate endpoint management tools into unified PCaaS dashboards.
- Certified technician scarcity:Multi-vendor hardware support requires CompTIA A+ and vendor-specific credentials that lag market expansion in secondary metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pcaas Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Service Type: Managed Services, Professional Services, Consulting Services, Custom Solutions End User: Small Businesses, Enterprises, Government Agencies, Educational Institutions Technology: Machine Learning, Artificial Intelligence, Data Analytics, Automation |
| Companies Covered | HP Inc., Dell Technologies Inc., Lenovo Group Ltd, Microsoft Corporation, SHI International Corp., CompuCom Systems Inc., Cisco Systems, Inc., Fujitsu Limited, Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pcaas Market Strategic Shifts
Software-defined feature licensing is rebalancing what hardware OEMs monetize across contract terms, embedding security and management capabilities as subscription-tier differentiators rather than perpetual add-ons.
Predictive failure analytics is absorbing telemetry from thermal sensors, solid-state drive wear indicators, and battery cycle counts to trigger proactive device replacement before productivity disruption. Healthcare systems and financial trading floors with zero-tolerance downtime requirements are adopting this capability fastest. The technology is absorbing margin from traditional break-fix support contracts into higher-value managed service tiers.
The EU AI Act's risk classification system imposes conformity assessment obligations on PCaaS providers serving high-risk public-sector applications, including biometric authentication and automated decision-support tools. Vendors must maintain technical documentation and human oversight protocols that extend contract governance frameworks. Healthcare delivery organizations across Germany and France are restructuring procurement specifications to preempt compliance gaps.
Consolidated vendor selection is displacing multi-source hardware strategies as enterprises prioritize single-accountability for security patches, carbon reporting, and end-of-life recovery. Large pharmaceutical and professional services firms are compressing supplier panels from five-plus vendors to two preferred partners. This concentration is most visible in the United States, where procurement teams negotiate master service agreements spanning 50,000-plus seats with integrated ESG attestation requirements.
Pcaas Market Segmentation
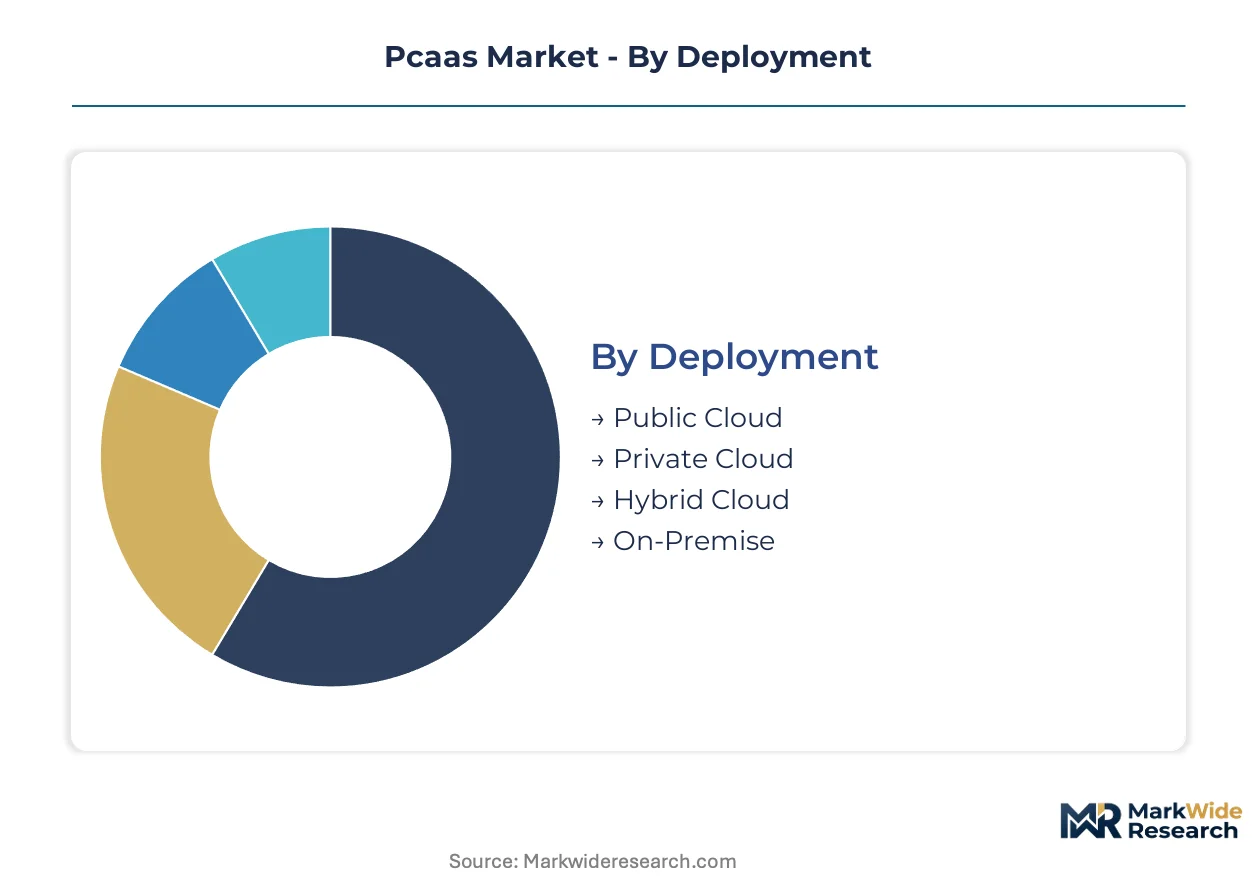
PCaaS procurement patterns diverge sharply across deployment architectures, service tiers, and end-user scale requirements. Understanding these fault lines reveals where vendors capture recurring revenue versus one-time engagements, and which technology integrations command premium positioning.
Deployment:
Technical architecture determines data residency capabilities, latency profiles, and compliance scope for regulated workloads.
- Public Cloud:Multi-tenant infrastructure delivers lowest per-seat operational overhead with centralized patch management and zero on-site hardware. Financial services firms in the United States and Germany favor this model for non-sensitive workstation fleets where speed of provisioning outweighs custody concerns.
- Hybrid Cloud:Split-stack configurations anchor sensitive processing on-premise while management planes operate from vendor cloud environments. Healthcare delivery organizations across Germany and France are expanding this architecture fastest under EU AI Act conformity pressures.
- Private Cloud:Single-tenant dedicated infrastructure serves defense contractors and classified research facilities requiring air-gapped endpoint management.
- On-Premise:Fully localized control satisfies national data sovereignty mandates in Japan and select Middle Eastern jurisdictions.
Public Cloud leads on scale; Hybrid Cloud leads on momentum.
Service Type:
Margin concentration tracks contract duration and integration depth rather than transactional volume.
- Managed Services:Bundled endpoint monitoring, security patching, and lifecycle refresh under 24-to-60 month terms generate the stickiest revenue streams. Enterprises with 10,000-plus seat deployments in the United States negotiate these contracts with embedded ESG attestation requirements.
- Professional Services:Project-based migration, deployment, and training engagements carry higher customer acquisition costs and renewal uncertainty.
- Consulting Services:Advisory work on fleet optimization and compliance readiness typically precedes larger managed service conversions.
- Custom Solutions:Bespoke integrations with legacy identity management or ERP systems command premium day rates but resist standardization.
Managed Services dominates recurring value; Custom Solutions captures the steepest expansion trajectory in specialized verticals.
End User:
Procurement sophistication and contract negotiation leverage scale inversely with organizational size.
- Enterprises:Multi-national corporations with distributed workforces drive standardization mandates and consolidated vendor panels. Master service agreements spanning 50,000-plus seats with integrated carbon reporting are now standard in United States pharmaceutical and professional services sectors.
- Government Agencies:Federal and state entities impose Zero Trust architecture requirements and FedRAMP authorization burdens that filter vendor eligibility.
- Small Businesses:Price-sensitive buyers with limited IT staff favor pre-configured bundles with minimal customization options.
- Educational Institutions:Seasonal enrollment cycles and grant-funded refresh programs create lumpy demand patterns with extended procurement timelines.
Enterprises anchor contract value; Government Agencies are gaining share fastest through cybersecurity mandate compliance.
Technology:
Intelligent automation layers differentiate commodity hardware subscriptions from premium service tiers.
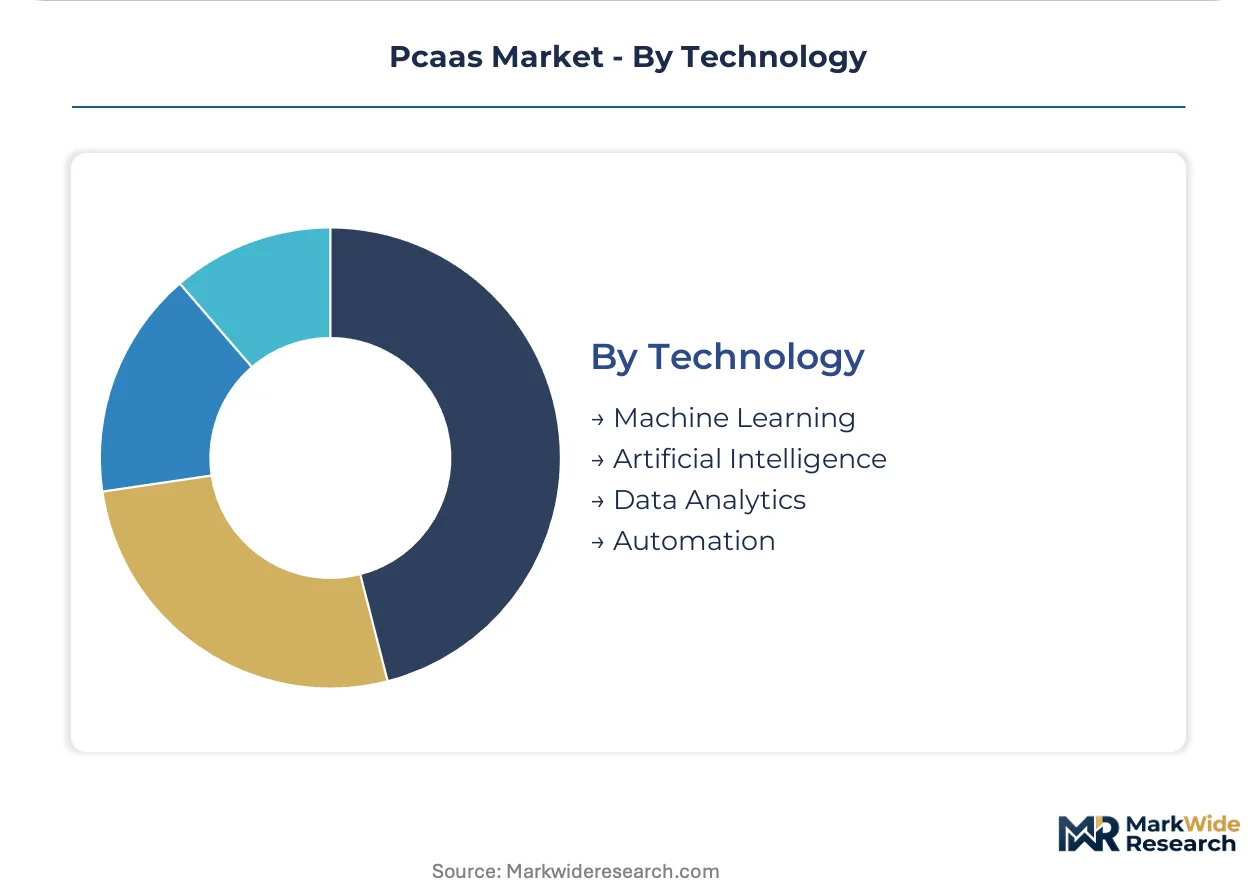
- Machine Learning:Predictive failure models absorbing thermal sensor and SSD wear telemetry trigger proactive replacement before productivity disruption. Healthcare systems and financial trading floors with zero-tolerance downtime requirements adopt this capability fastest.
- Automation:Zero-touch provisioning and policy enforcement reduce deployment labor costs and human configuration errors at enterprise scale.
- Artificial Intelligence:Biometric authentication and automated decision-support tools face heightened conformity assessment obligations under EU AI Act risk classifications.
- Data Analytics:Fleet-wide performance dashboards and carbon accounting telemetry satisfy emerging SEC climate disclosure and CSRD reporting requirements.
Machine Learning leads on commercial traction; Data Analytics is climbing the fastest as regulatory disclosure mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping PCaaS procurement as enterprises migrate contracts toward jurisdictions with clearer cybersecurity liability frameworks and lower compliance friction. Vendors are restructuring service delivery architectures to capture this geographic differentiation.
United States
Federal Zero Trust mandates and SEC climate disclosure rules are consolidating demand around providers with FedRAMP authorization and embedded carbon accounting. Healthcare systems in the Boston-Cambridge cluster are adopting predictive failure analytics fastest, driven by FDA cybersecurity guidance for networked medical devices.
Germany
Industrial automation suppliers in Bavaria and Baden-Württemberg are expanding ruggedized device-as-a-service contracts with predictive maintenance integration. The EU NIS2 Directive and CSRD reporting obligations are filtering vendor eligibility, favoring providers with verified Scope 3 emissions tracking and technical documentation protocols.
Japan
National data sovereignty mandates are preserving on-premise deployment dominance for defense contractors and classified research facilities in the Tokyo-Yokohama corridor. METI standards for endpoint security are accelerating procurement of hardware-integrated identity management platforms across financial services.
United Kingdom
Professional services firms in London are compressing supplier panels from five-plus vendors to two preferred partners with integrated ESG attestation. The UK National Cyber Security Centre guidance is aligning procurement specifications with EU AI Act conformity frameworks ahead of formal regulatory divergence.
France
Healthcare delivery organizations in the Île-de-France region are restructuring procurement specifications to preempt EU AI Act compliance gaps for biometric authentication and automated decision-support tools. CNIL data protection requirements are reinforcing hybrid cloud configurations with on-premise data residency for sensitive workloads.
Pcaas Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with hardware OEMs anchoring enterprise deployments and systems integrators capturing professional services margin. The vendor base concentrates around three strategic archetypes: full-stack OEMs bundling security and lifecycle services, IT distributors layering managed services atop hardware logistics, and consulting firms converting advisory engagements into multi-year managed contracts. Competitive moves center on portfolio diversification into carbon reporting telemetry and strategic partnerships with identity management platforms.
Within the full-stack OEM tier, HP Inc. and Dell Technologies Inc. exemplify the integrated hardware-security-carbon reporting positioning that dominates United States pharmaceutical and professional services procurement. Lenovo Group Ltd. occupies a distinct position bridging enterprise scale with price-accessible configurations for mid-market consolidation. Fujitsu Limited anchors the Japan-market on-premise deployment segment where national data sovereignty mandates preserve single-tenant infrastructure demand.
| Leading Market Players |
|---|
| HP Inc. |
| Dell Technologies Inc. |
| Lenovo Group Ltd |
| Microsoft Corporation |
| SHI International Corp. |
| CompuCom Systems Inc. |
| Cisco Systems, Inc. |
| Fujitsu Limited |
| Capgemini |
| Others |
Value Chain & Pricing Dynamics
Captive integration into endpoint security stacks and carbon accounting telemetry anchors vendor pricing power while compressing distributor margins across multi-year fleet contracts. HP Inc. and Dell Technologies Inc. leverage in-house development of predictive analytics layers to justify premium service tiers, whereas IT distributors without captive software capabilities compete on hardware logistics efficiency alone.
Pricing Analysis
Distributor margin compression defines the channel economics, with direct-to-enterprise contracts capturing 15-20 point spreads that previously flowed through hardware resellers. Three-tier pricing structure across premium, standard, and economy levels stratifies by security certification depth and ESG attestation granularity, with FedRAMP-authorized bundles commanding substantial premiums. Cost compression in mid-market segments intensifies as Lenovo Group Ltd. and contract manufacturers introduce price-accessible configurations with stripped-down management layers. Small businesses exhibit highest price sensitivity, while pharmaceutical and financial services enterprises prioritize integrated carbon reporting over per-seat cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from United States federal contractors and German automotive suppliers mandate qualified secondary suppliers for processor and memory components, extending procurement timelines. Taiwan and South Korea fabrication dominance creates structural vulnerability in CPU and SSD availability, with enterprise fleet contracts exposed to single-source concentration in advanced node semiconductors. Supply chain risk centers on tariff exposure for China-assembled devices serving North American healthcare and public sector accounts. Distribution runs through direct vendor sales organizations for enterprise deployments above 10,000 seats, while mid-market and small business segments rely on IT distributors and channel partners for hardware logistics and initial configuration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in PCaaS rests on predictive failure analytics and embedded carbon telemetry shifting contract value from commodity hardware to recurring software-defined services. Automation of deployment and lifecycle management compresses delivery costs while enabling premium positioning.
For Market Incumbents: Hedge against residual value volatility by shortening refresh cycles and embedding secondary market remarketing into contract terms. Consolidate supplier panels from five-plus vendors to two preferred partners to capture scale economics in security patch management and ESG reporting. Backward integration into endpoint security software development defends margin position against pure-play managed service entrants. For New Entrants and Emerging Players: Systems integrators lacking captive hardware manufacturing represent the most penetrable channel partner type for white-label PCaaS bundling. Target German industrial automation suppliers and Japan defense contractors with ruggedized device-as-a-service configurations requiring predictive maintenance integration. Lead generation through compliance advisory engagements on EU AI Act and NIS2 Directive readiness converts into multi-year managed service contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale managed service providers lack FedRAMP authorization or verified Scope 3 emissions tracking infrastructure. Acquisition targets with established healthcare system relationships and FDA 510(k) cybersecurity documentation capabilities offer strongest five-to-ten year viability. Watch for inflection when SEC climate disclosure enforcement accelerates vendor differentiation around embedded carbon accounting.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Platform Development | HP Inc. and Dell Technologies Inc. absorb break-fix margin into higher-value managed service tiers through proactive failure management. |
| FedRAMP Authorization Investment | Compliance with federal Zero Trust mandates filters vendor eligibility for United States public sector contracts exceeding 50,000 seats. |
| Carbon Accounting Telemetry Integration | Verified Scope 3 emissions tracking satisfies SEC climate disclosure and CSRD reporting requirements for pharmaceutical procurement. |
| Healthcare System Partnership Expansion | FDA cybersecurity guidance for networked medical devices drives adoption of predictive failure analytics in Boston-Cambridge hospital clusters. |
| Industrial Automation Vertical Penetration | German automotive suppliers in Bavaria expand ruggedized device-as-a-service contracts with predictive maintenance integration. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with IT procurement officers, endpoint security architects, fleet operations managers, and channel sales directors with secondary validation. Primary sources included CTOs at pharmaceutical and financial services enterprises, GPO contracts managers at healthcare delivery organizations, and distribution executives at IT logistics providers. Secondary data sources encompassed SEC climate disclosure filings, FedRAMP authorization databases, EU NIS2 Directive implementation guidance, and CSRD technical standards documentation. Bottom-up seat deployment estimates triangulated against top-down vendor revenue attribution across service type and deployment architecture segments.
Segment-weighting approaches modeled deployment configurations, service tiers, end-user scale categories, and intelligent automation technology layers throughout the forecast period. CAGRs derived from historical contract value trajectories, seat expansion patterns at enterprise accounts, and regulatory mandate adoption curves across United States, Germany, and Japan markets. Forecast inputs incorporated cloud-first mandate penetration rates, Zero Trust architecture deployment timelines, and EU AI Act conformity assessment obligations for biometric authentication and automated decision-support tools.
Revisions become necessary when semiconductor supply disruptions, regulatory enforcement acceleration, or enterprise procurement consolidation patterns materialize outside baseline assumptions. Deviation in residual value recovery rates for enterprise laptop secondary markets would shift contract profitability and vendor pricing power materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Green Communication Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Push-To-Talk Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Asia-Pacific Postal Services Market
Communication Services
Speech to Speech Translation Market
Communication Services
Video Managed Services Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Cloud Communication Platform Market
Communication Services
Walkie Talkie Market
Communication Services
Mobile Messaging Market
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Web Conferencing Market
Communication Services
Global Communications Interface Market
Communication Services
Rich Communications Suite Services and Subscribers Market