
 Enterprise Communication Infrastructure Market | 2026-2036
Enterprise Communication Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Communication Infrastructure Market Foresight
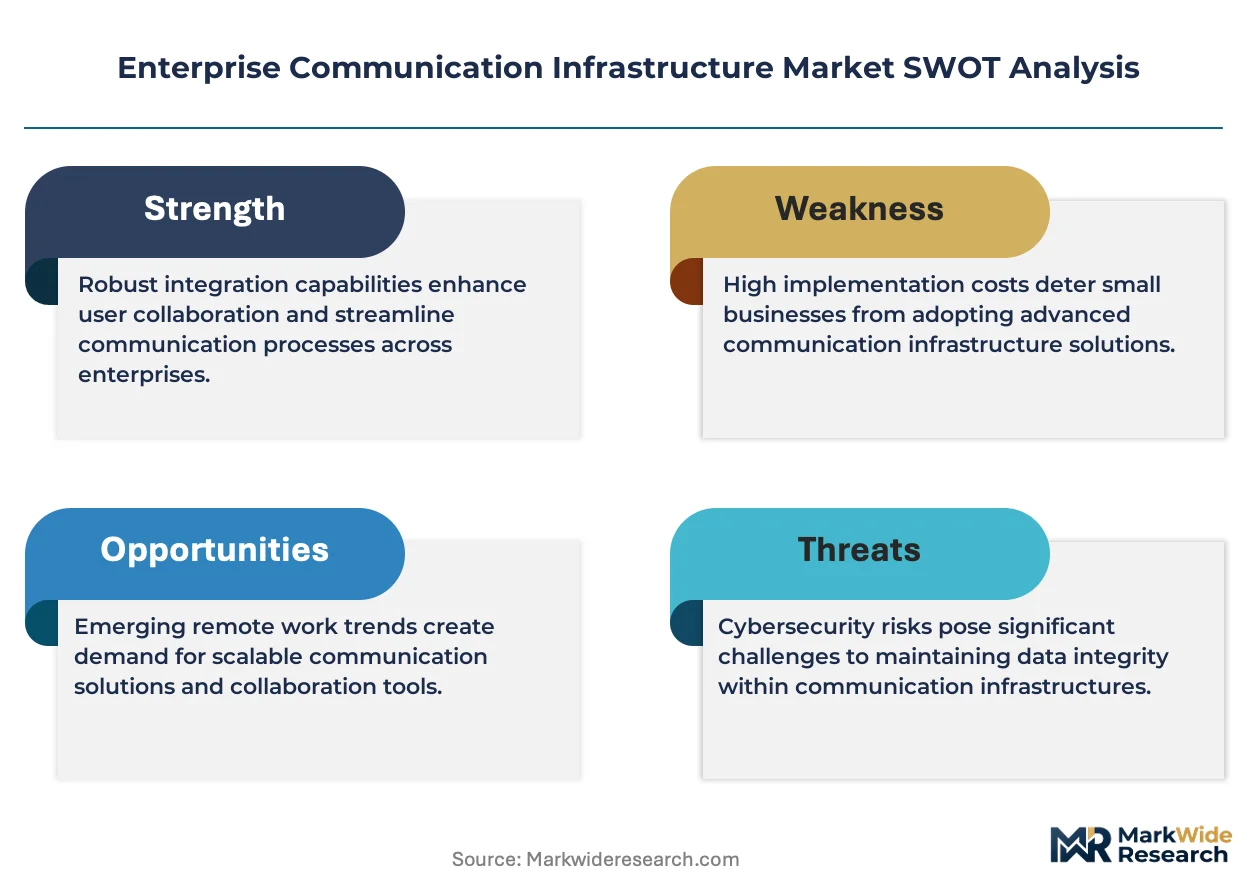
The EU AI Act is recalibrating vendor compliance costs across Europe, forcing smaller providers to absorb certification overhead or exit the market. Cisco Systems Inc. leverages its global channel network to distribute certified hardware at scale. NEC Corporation anchors its competitive position through deep vertical integration into private 5G campus networks. Microsoft Corporation differentiates via native AI embedding across Teams and Azure Communication Services.
Enterprise communication infrastructure encompasses the hardware, software, and network systems enabling real-time voice, video, and data exchange across organizations, typically requiring sub-150 millisecond latency for VoIP and 99.999% uptime SLAs for mission-critical operations. Cloud-based deployment models are capturing the fastest expansion as enterprises shed capital-intensive on-premises maintenance, while hybrid architectures retain dominance among regulated sectors requiring data sovereignty controls. Unified communications platforms command the deepest margin pools by bundling voice, messaging, and video into sticky subscription ecosystems.
The Federal Communications Commission shapes US market access through E-Rate funding rules for educational institutions and net neutrality frameworks affecting traffic prioritization. The European Telecommunications Standards Institute and Germany's Federal Network Agency jointly enforce interoperability mandates and PSTN transition timelines. Japan's Ministry of Internal Affairs and Communications sets spectrum allocation policies for enterprise 5G private networks. Stakeholders must weigh sovereign cloud requirements against the operational agility of hyperscaler partnerships when architecting next-generation communication stacks.
Market Dynamics
The PSTN switch-off deadlines across Europe are forcing enterprises to abandon circuit-switched voice infrastructure, compressing replacement cycles and redistributing vendor market positions toward cloud-native platforms.
Growth Catalysts
- EU AI Act Compliance Mandates:Financial services firms in Germany and France must deploy certified AI-enabled contact center platforms by statutory deadlines, accelerating replacement of legacy systems.
- Hybrid Work Infrastructure:Enterprise mandates for location-flexible collaboration are expanding unified communications deployments across professional services and technology sectors.
- Private 5G Campus Networks:Manufacturing and logistics facilities are integrating dedicated spectrum deployments to achieve sub-50 millisecond latency for mission-critical voice and video.
Market Restraints
- Semiconductor Supply Concentration:Enterprise voice gateway and session border controller production depends on concentrated advanced node fabrication in Taiwan and South Korea.
- EU AI Act Certification Costs:Smaller communication platform providers face prohibitive compliance overhead for high-risk AI system classification, forcing market exits.
- Copper Infrastructure Stranded Assets:Enterprises with extensive on-premises PBX depreciation schedules face accelerated write-downs as PSTN termination dates approach.
Strategic Opportunities
- India Enterprise Modernization:TRAI's cloud telephony liberalization and the country's PLI scheme for telecom equipment create entry points for hosted communication providers.
- Healthcare Secure Messaging:HIPAA-compliant unified communications integration with electronic health record systems represents underpenetrated demand in US ambulatory care networks.
- Edge-AI Voice Analytics:Convergence of on-device natural language processing with enterprise telephony infrastructure enables real-time compliance monitoring without cloud data egress.
Industry Challenges
- Legacy TDM-to-IP Migration:Enterprises with embedded ISDN PRI circuits and analog fax dependencies face complex interworking requirements during infrastructure transitions.
- Multi-Cloud Orchestration Talent:Shortage of engineers certified across Microsoft Teams, Cisco Webex, and Zoom Phone administration platforms constrains enterprise deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Communication Infrastructure Market |
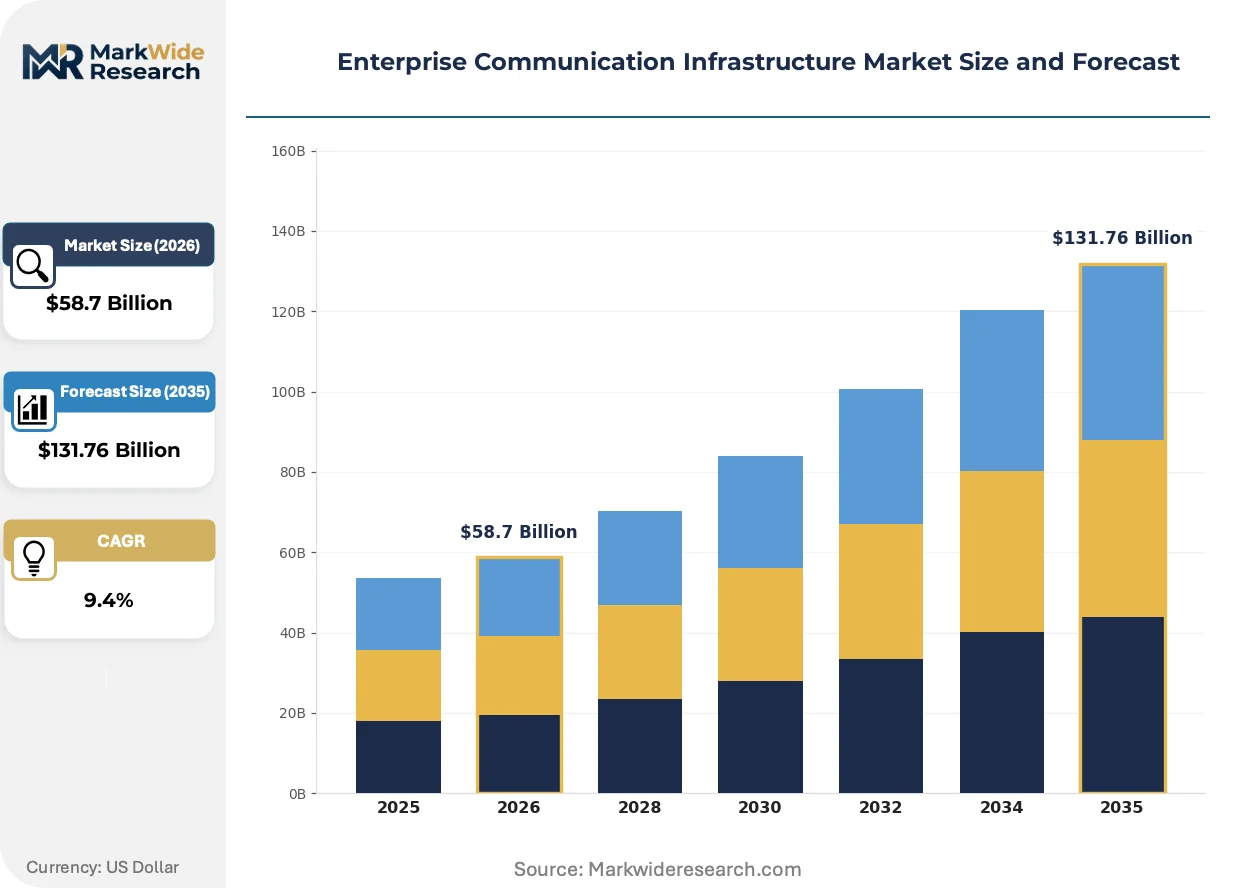
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: VoIP, Unified Communications, Video Conferencing, Instant Messaging Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: SMBs, Enterprises, Government Agencies, Educational Institutions Service Type: Support Services, Consulting, Integration Services, Training |
| Companies Covered | AT&T Corporation, DXC Technology, Cisco Systems Inc., NEC Corporation, Verizon Communications, Microsoft Corporation, Avaya Inc., Mitel Networks Corporation, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Communication Infrastructure Market Shifts & Advancements
Artificial intelligence is embedding into voice infrastructure at the codec, routing, and analytics layers simultaneously, compressing the traditional separation between transport and application intelligence.
AI-powered noise suppression and bandwidth adaptation is integrating directly into enterprise endpoints and session border controllers. Financial trading floors and healthcare consultation rooms are adopting these capabilities fastest. The technology is integrating real-time audio optimization with quality-of-service policy enforcement, collapsing the distinction between network and application management functions.
Germany's Federal Network Agency has mandated interoperability testing for all IP-based emergency calling infrastructure ahead of PSTN switch-off. Equipment vendors must certify gateway devices against BNetzA technical specifications before network deployment authorization. German healthcare and public safety verticals are accelerating procurement timelines to secure compliant infrastructure before statutory deadlines.
Enterprise buyers are consolidating communication spend under platform-native ecosystem contracts rather than best-of-breed point solutions. Value-added resellers and systems integrators are losing standalone voice margins to direct hyperscaler relationships. This concentration is most visible in US and UK financial services, where procurement teams are bundling Teams Phone or Zoom Phone with existing productivity suite entitlements.
Enterprise Communication Infrastructure Market Segmentation
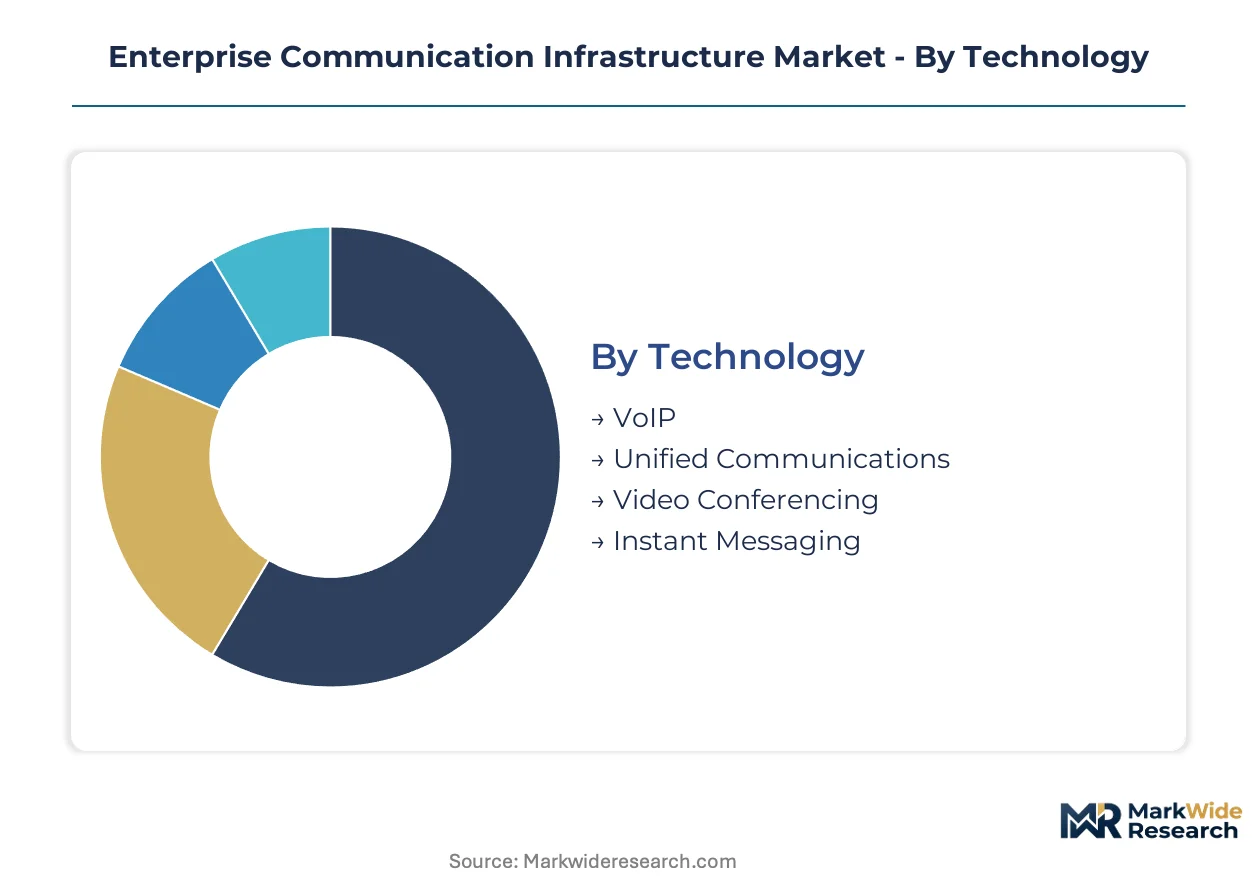
Enterprise communication infrastructure segments diverge sharply by integration depth, with embedded systems demanding tighter latency guarantees than standalone deployments. Procurement teams weight total cost of ownership against migration complexity when mapping technology choices to organizational scale.
Technology:
Integration depth separates standalone transport layers from application-embedded intelligence, with unified communications collapsing multiple modalities into single-stack architectures.
- VoIP:Packet-switched voice transmission over IP networks with codec negotiation and quality-of-service tagging. Manufacturing facilities in Germany prioritize VoIP gateway certification ahead of PSTN switch-off deadlines imposed by the Federal Network Agency.
- Unified Communications:Converged platform bundling voice, messaging, video, and presence into subscription ecosystems. Financial services firms in France and Germany accelerate replacement cycles to meet EU AI Act compliance mandates for certified contact center platforms.
- Video Conferencing:Real-time audiovisual collaboration with endpoint hardware and cloud bridging infrastructure.
- Instant Messaging:Persistent chat with file sharing and threaded conversation archiving for compliance.
VoIP leads volumes today; unified communications is gaining share fastest.
Deployment Model:
Cost tier stratification drives procurement patterns, with capital expenditure constraints favoring operational expenditure models in mid-market segments.
- Cloud-Based:Multi-tenant SaaS delivery eliminating on-premises hardware ownership and maintenance overhead. Professional services firms across the US and UK consolidate spend under platform-native ecosystem contracts with direct hyperscaler relationships.
- Hybrid:Split architecture preserving data sovereignty for regulated workloads while offloading burst capacity. Healthcare networks in Germany retain on-premises session border controllers for emergency calling compliance while routing routine traffic to cloud infrastructure.
- On-Premises:Dedicated hardware and software with full administrative control over security policies.
- Managed Services:Outsourced operations with service-level agreements covering uptime and response times.
Hybrid deployments dominate regulated verticals today; cloud-based models are expanding most quickly in technology and professional services sectors.
End User:
Application requirements scale with organizational complexity, with government and healthcare buyers imposing certification and interoperability mandates absent in commercial segments.
- Enterprises:Large organizations with multi-site deployments and dedicated IT operations teams. German healthcare and public safety verticals accelerate procurement timelines to secure IP-based emergency calling infrastructure before statutory deadlines.
- SMBs:Small and medium businesses with limited technical staff favoring turnkey solutions.
- Government Agencies:Public sector entities with sovereign cloud requirements and classified data handling protocols.
- Educational Institutions:Schools and universities leveraging E-Rate funding rules in the US for infrastructure modernization.
Enterprises command the deepest procurement budgets today; educational institutions are climbing the fastest as federal funding programs expand eligible technology categories.
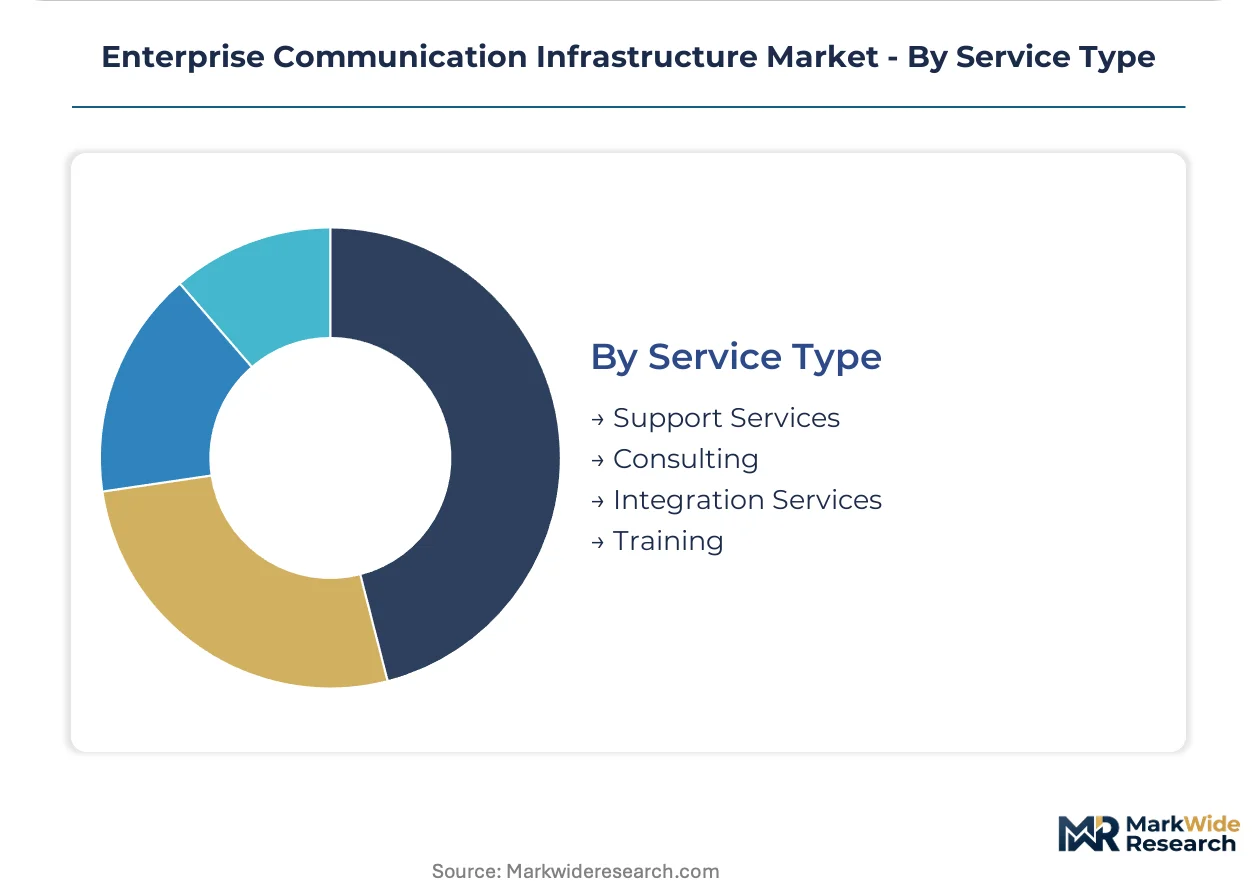
Service Type:
Margin concentration follows technical complexity, with integration services capturing premium pricing for legacy-to-IP migration projects.
- Integration Services:System interconnection and workflow automation across disparate communication platforms. Enterprises with embedded ISDN PRI circuits and analog fax dependencies engage specialized engineers for complex TDM-to-IP transitions.
- Consulting:Strategic advisory on architecture selection and vendor evaluation.
- Support Services:Ongoing technical assistance and break-fix coverage.
- Training:Administrator certification and end-user adoption programs.
Integration services lead service revenue today; consulting is gaining share fastest as PSTN switch-off deadlines compress replacement decision timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise communication infrastructure talent concentrates in Germany's Ruhr industrial corridor, the US San Francisco Bay Area, and India's Bengaluru technology cluster. These concentrations anchor procurement decision-making for cloud migration and compliance-critical deployments.
Germany
Manufacturing conglomerates in Stuttgart and Munich drive demand for private 5G campus networks with sub-50 millisecond latency guarantees. The Federal Network Agency enforces BNetzA technical specifications for IP-based emergency calling ahead of PSTN switch-off deadlines. Bavaria's healthcare networks accelerate procurement of compliant session border controllers for hospital systems.
United States
Financial services firms in Manhattan and professional services clusters in Chicago expand unified communications deployments under hybrid work mandates. The FCC shapes market access through E-Rate funding rules for educational institutions and net neutrality frameworks affecting traffic prioritization. Silicon Valley technology campuses pilot edge-AI voice analytics for real-time compliance monitoring.
India
IT services exporters in Bengaluru and Hyderabad modernize legacy contact center infrastructure for global enterprise clients. TRAI's cloud telephony liberalization and the PLI scheme for telecom equipment create entry points for hosted communication providers. Maharashtra's banking sector in Mumbai adopts certified AI-enabled platforms for customer service automation.
Japan
Automotive manufacturers in Toyota City and electronics assemblers in Osaka integrate dedicated spectrum for mission-critical voice and video. The Ministry of Internal Affairs and Communications sets spectrum allocation policies for enterprise 5G private networks. Nagoya's industrial corridor deploys low-latency communication stacks for smart factory coordination.
United Kingdom
Professional services firms in London consolidate communication spend under platform-native ecosystem contracts with direct hyperscaler relationships. Ofcom regulates PSTN transition timelines and interoperability standards for business voice services. The Cambridge technology cluster experiments with on-device natural language processing for secure enterprise telephony.
Enterprise Communication Infrastructure Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment models and compliance tiers. The vendor base stratifies into three tiers: hyperscalers with native productivity suite integration, established networking hardware incumbents with channel scale, and vertical specialists targeting regulated verticals. Dominant competitive moves include M&A to acquire cloud-native software assets and strategic partnerships to embed AI capabilities into existing hardware footprints.
Within the hyperscaler tier, Microsoft Corporation exemplifies platform-native ecosystem bundling, while Cisco Systems Inc. anchors the networking hardware incumbent archetype through global channel distribution. NEC Corporation occupies a position among vertical specialists with deep integration into private 5G campus deployments. These three represent contrasting strategic postures: software-first subscription models, hardware-scale certification advantages, and sector-specific compliance expertise.
| Leading Market Players |
|---|
| AT&T Corporation |
| DXC Technology |
| Cisco Systems Inc. |
| NEC Corporation |
| Verizon Communications |
| Microsoft Corporation |
| Avaya Inc. |
| Mitel Networks Corporation |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Cloud-native codec optimization is collapsing the traditional separation between hardware and software cost structures, simultaneously compressing endpoint manufacturing economics and concentrating procurement leverage among hyperscaler direct-contract buyers.
Pricing Analysis
Bundled subscription ecosystems now command premium positioning over unbundled point solutions across enterprise segments. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service bundling. Pricing pressure stems from hyperscaler platform-native contracts absorbing standalone voice margins. Mid-market professional services firms exhibit highest price sensitivity, while regulated healthcare and financial services buyers prioritize compliance-grade premiums over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced node semiconductor fabrication powering enterprise voice gateways and session border controllers. Production draws from concentrated foundry capacity for SoC chipsets, DSP components, and power management ICs. Tariff exposure on networking hardware imports from China creates downstream cost volatility. Distribution runs through authorized value-added reseller networks and direct hyperscaler channels serving enterprise procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as PSTN switch-off mandates force predictable replacement cycles across European installed bases.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Accelerate BNetzA and EU AI Act compliance timelines ahead of statutory deadlines to strand non-compliant competitor inventories. Anchor channel control through exclusive distribution agreements with German systems integrators serving healthcare and public safety verticals. For New Entrants and Emerging Players: TRAI cloud telephony liberalization in India opens a window for hosted communication providers to capture IT services exporter modernization demand. Target Maharashtra banking sector contact center automation as the most penetrable segment. Pursue white-label platform partnerships with domestic telecom equipment distributors lacking native software development capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among vertical specialists with private 5G campus network integration expertise. Five-to-ten year viability favors acquisition targets possessing sovereign cloud certifications and sector-specific compliance track records. Monitor German Federal Network Agency procurement authorization timelines as the critical inflection signal for infrastructure replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native AI embedding across Teams and Azure Communication Services collapses standalone voice margins. |
| Certification Investment | BNetzA technical specifications for IP-based emergency calling create compliance moats before PSTN switch-off. |
| Strategic Partnership | Channel alliances with German systems integrators anchor distribution for healthcare and public safety verticals. |
| Geographic Expansion | India's PLI scheme for telecom equipment and TRAI liberalization create entry points for hosted providers. |
| Acquisition of Specialist Firm | Vertical specialists with private 5G campus expertise command scarcity premiums in manufacturing automation. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down vendor shipment tracking forms the analytical core. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners combine with secondary validation from SEC filings, hyperscaler capex disclosures, E-Rate funding databases, and TRAI regulatory notifications. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map deployment model, organization size, vertical, and integration complexity against regional adoption patterns across the analysis window. CAGRs derive from segment-level replacement cycle analysis and compliance mandate timing. Forecast inputs incorporate PSTN switch-off deadlines, EU AI Act certification timelines, and private 5G spectrum allocation policies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or accelerated regulatory deadline shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Postal Services Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Global Call Center Platform Market
Communication Services
North America Postal Services Market
Communication Services
Video Conferencing Market
Communication Services
Walkie Talkie Market
Communication Services
Speech to Speech Translation Market
Communication Services
Cloud Communication Platform Market
Communication Services
Global Communications Interface Market
Communication Services
Outbound Telemarketing Market
Communication Services
Voip Services Market
Communication Services
In Flight Entertainment and Communication Market
Communication Services
Web Conferencing Market
Communication Services
Meeting Solutions Market
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Rich Communications Suite Services and Subscribers Market