
 North America Postal Services Market | 2026-2036
North America Postal Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Postal Services Market Analytics
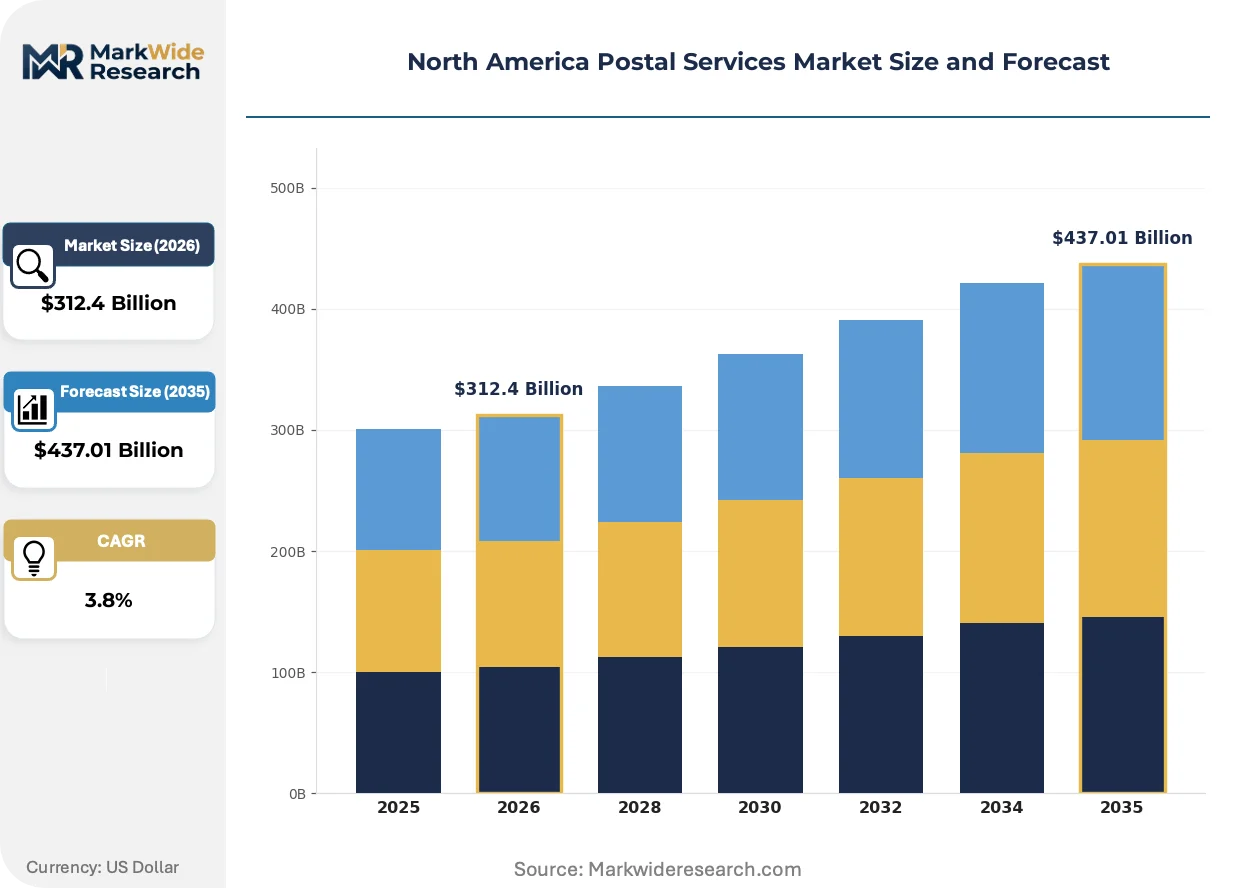
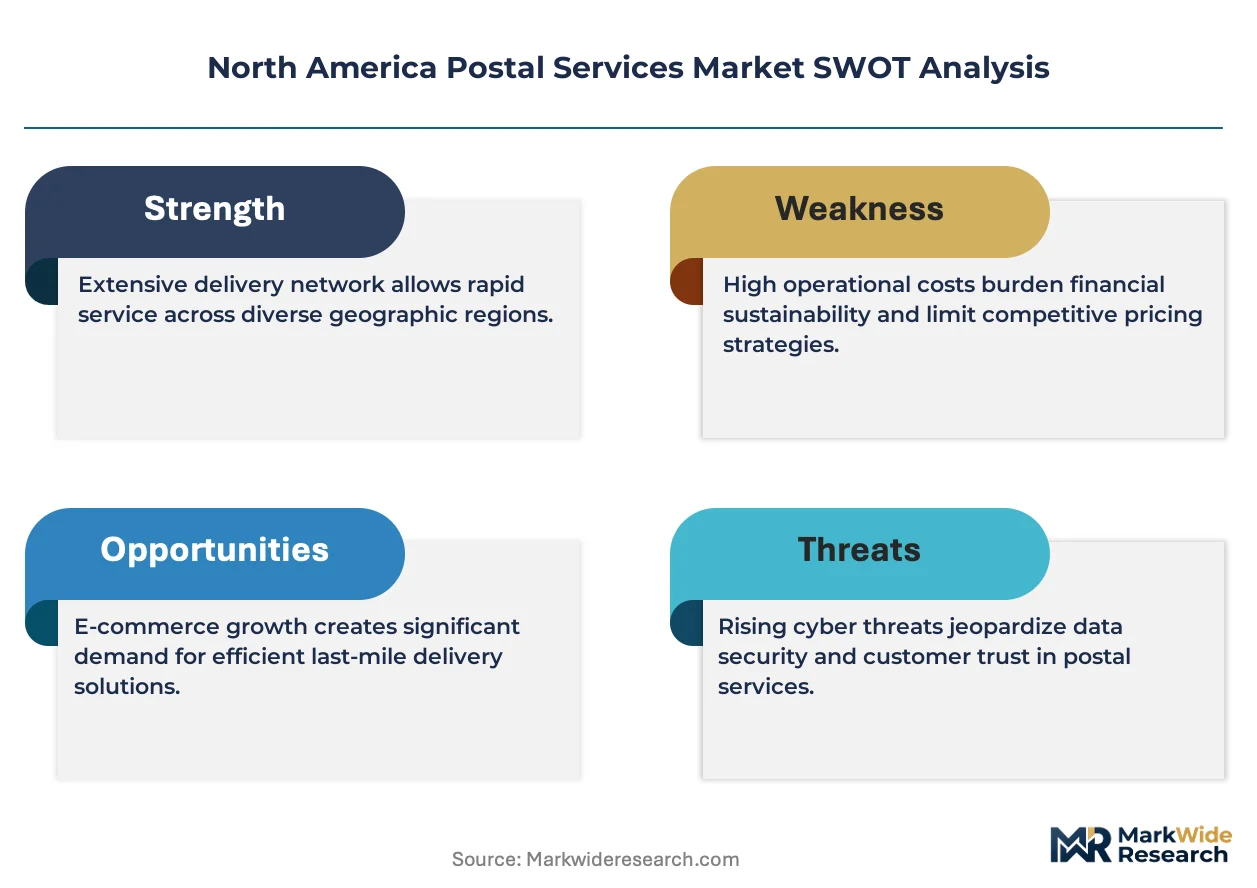
E-commerce buyer consolidation is restructuring contract negotiations across the North America Postal Services Market. Large online retailers now command volume-based pricing that reshapes carrier economics. United Parcel Service anchors its network through integrated ground and air operations spanning the United States, Canada, and Mexico. FedEx Corporation competes through time-definite express services and specialized healthcare logistics infrastructure. United States Postal Service leverages its statutory monopoly on mailbox access and last-mile coverage in rural and suburban territories.
Postal services encompass the collection, processing, transportation, and delivery of letters, parcels, and documents through physical infrastructure networks operating at defined service standards. These systems rely on automated sorting facilities, barcode tracking protocols, and route-optimization algorithms to achieve delivery commitments across diverse geographic densities. Express Mail commands premium pricing for time-sensitive shipments, while Standard Mail retains volume leadership in bulk commercial correspondence. Same-Day Delivery represents the fastest-expanding delivery mode, though margin pools remain thin due to labor intensity and fleet requirements. E-commerce Businesses generate the dominant share of parcel volume growth, pulling investment toward sortation automation and urban micro-fulfillment nodes.
The United States Postal Service operates under congressional oversight and Postal Regulatory Commission rate-setting authority, while Canada Post Corporation functions under the Canada Post Corporation Act with federal mandate obligations. Mexico's postal regulator oversees Correos de Mexico under communications ministry supervision, with cross-border customs protocols shaped by USMCA trade provisions. Stakeholders must monitor how postal reform legislation, emissions regulations, and labor classification rulings alter cost structures and competitive boundaries across the three-country postal landscape.
Market Dynamics
E-commerce volume concentration among a handful of mega-retailers is compressing carrier margins and forcing network reconfiguration across the United States, Canada, and Mexico. Parcel density in urban corridors now dictates sortation facility placement more than traditional population coverage models.
Growth Catalysts
- USMCA customs modernization:Simplified cross-border documentation protocols are accelerating parcel flows between the United States and Mexico, reducing clearance friction for express shipments.
- Last-mile robotics deployment:Autonomous mobile robots in urban distribution hubs are compressing sortation cycle times for same-day delivery commitments in dense metropolitan zones.
- Rural broadband expansion:Enhanced digital connectivity in underserved territories is enabling address verification and delivery scheduling tools that reduce failed delivery rates.
Market Restraints
- Fleet electrification capex burden:Battery-electric delivery vehicle procurement requirements under California CARB rules and similar state mandates are straining capital allocation for route density optimization.
- Last-mile labor classification uncertainty:Independent contractor reclassification litigation in multiple U.S. jurisdictions is creating payroll cost volatility and insurance exposure for gig-dependent delivery networks.
- Address database fragmentation:Inconsistent rural addressing standards between U.S. ZIP code systems, Canadian postal codes, and Mexican codigo postal formats complicate cross-border routing algorithms.
Strategic Opportunities
- Mexico e-commerce penetration gap:Underdeveloped parcel locker infrastructure in Mexican metropolitan areas offers first-mover positioning for automated pickup networks serving unbanked populations.
- Healthcare cold-chain convergence:Temperature-controlled parcel protocols developed for pharmaceutical distribution are transferable to premium perishable e-commerce verticals requiring validated thermal packaging.
- Carbon disclosure alignment:Scope 3 emissions tracking mandates under proposed SEC climate rules and existing TCFD-aligned Canadian securities guidance are creating demand for carrier-provided shipment-level carbon accounting tools.
Industry Challenges
- Sortation technician scarcity:Maintenance expertise for high-speed optical character recognition and dimensioning equipment outpaces vocational training pipeline capacity in Midwest and Southwest U.S. hub markets.
- Legacy manifest system integration:Proprietary electronic data interchange protocols from dominant e-commerce platforms require costly middleware development for tier-two regional carriers to maintain API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Postal Services Market |
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $437.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: First-Class Mail, Priority Mail, Express Mail, Standard Mail Delivery Mode: Overnight Delivery, Same-Day Delivery, Scheduled Delivery, International Delivery End User: Residential Customers, E-commerce Businesses, Government Agencies, Retail Stores Packaging Type: Envelopes, Boxes, Padded Mailers, Custom Packaging |
| Companies Covered | FedEx Corporation, Purolator Inc., United States Postal Service (USPS), OnTrac Logistics, Correos de Mexico, Canada Post Corporation, Deutsche Post DHL Group, Amazon Logistics, United Parcel Service (UPS), Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Postal Services Market Evolving Landscape
Digital freight matching and dynamic route optimization are collapsing traditional static delivery schedules. Network operators now compete on algorithmic dispatch precision rather than fixed-route density alone.
Computer vision-based parcel dimensioning is automating manifest accuracy verification at induction points. E-commerce fulfillment centers are deploying these systems to eliminate manual cube measurement and reduce revenue leakage from misclassified shipments. The technology is automating dimensional weight audit processes that previously required physical re-weigh stations.
The USPS Reform Act's pricing flexibility provisions and Postal Regulatory Commission rate authority adjustments are enabling competitive parcel rate structures previously constrained by universal service obligations. These regulatory modifications permit negotiated service agreements with high-volume shippers that approximate commercial carrier contract terms. Rural delivery frequency mandates remain the primary constraint on full pricing parity with private operators.
Subscription-based delivery consolidation is displacing per-transaction shipping decisions among mid-market e-commerce merchants. Merchants are bundling fulfillment commitments across quarterly periods rather than negotiating spot rates per shipment. This pattern concentrates most visibly among direct-to-consumer apparel and home goods sellers operating in the Northeast and Pacific Coast corridors.
North America Postal Services Market Segmentation
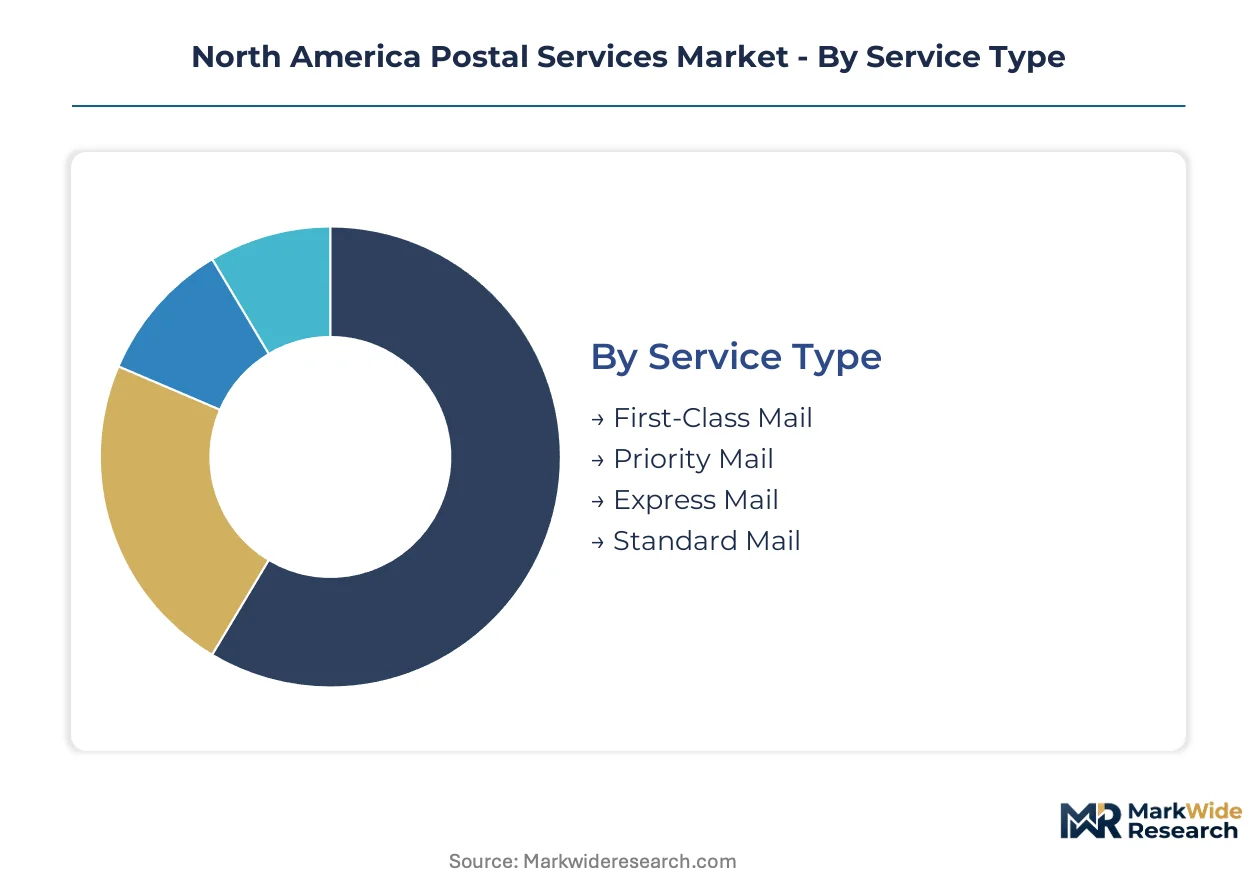
Postal service segmentation reveals how carriers allocate capital across divergent margin profiles. Volume-heavy segments demand automation investment, while premium tiers require reliability infrastructure and specialized handling protocols.
Service Type:
The volume versus premium split defines carrier network design, with bulk correspondence lanes running parallel to time-definite express corridors.
- First-Class Mail:Envelopes and lightweight correspondence move through automated flat sorting machines with optical character recognition addressing. Residential letter volume concentrates in suburban ZIP codes, though USPS statutory obligations prevent selective service withdrawal from low-density routes.
- Express Mail:Time-definite delivery commitments with money-back guarantees require dedicated air freight contracts and priority sortation queues. E-commerce Businesses in the Northeast and Pacific Coast corridors generate dominant demand for next-day residential delivery.
- Priority Mail:Two-to-three-day delivery windows for parcels under 70 pounds utilize ground networks with zone-based pricing. Regional carriers compete aggressively on cubic rate structures for this mid-tier segment.
- Standard Mail:Bulk commercial correspondence and marketing materials move at deferred service standards with deep volume discounts. Catalog retailers and political mailers represent core demand concentrations.
Mature deployment sits with Standard Mail. Newer deployment is concentrated in Express Mail.
Delivery Mode:
Speed-based differentiation creates four operational regimes, each with distinct fleet and labor configurations.
- Same-Day Delivery:Urban courier networks with dynamic dispatch algorithms serve metropolitan zones under 25-mile radii. E-commerce Businesses in Chicago, Los Angeles, and Toronto drive capacity expansion, though labor intensity compresses margins.
- Overnight Delivery:Air freight integration with morning sortation guarantees 10:30 AM delivery commitments. Healthcare specimen transport and legal document filing generate premium pricing tolerance.
- Scheduled Delivery:Predictable day-definite windows allow route optimization and density maximization. Subscription box merchants and parts distributors favor this cost-controlled mode.
- International Delivery:Customs brokerage integration and terminal dues negotiations shape cross-border economics. USMCA corridor volumes between the United States and Mexico are climbing the fastest.
Mature deployment sits with Scheduled Delivery. Newer deployment is concentrated in Same-Day Delivery.
End User:
Customer type determines contract structure, from individual postage purchases to enterprise negotiated service agreements.
- E-commerce Businesses:Volume-based pricing tiers with API-integrated manifesting dominate parcel growth. Mega-retailers command dedicated sortation capacity in Memphis, Louisville, and Indianapolis hub markets.
- Residential Customers:Individual shippers with sporadic demand patterns pay retail rates at post office counters or carrier retail locations. Rural address verification challenges elevate delivery failure costs.
- Government Agencies:Federal procurement vehicles and interagency mail protocols require certified tracking and chain-of-c custody documentation. USPS retains statutory preference for official correspondence.
- Retail Stores:Brick-and-mortar merchants utilize postal services for returns processing and inventory replenishment. Buy-online-pickup-in-store fulfillment creates hybrid delivery requirements.
Mature deployment sits with Residential Customers. Newer deployment is concentrated in E-commerce Businesses.
Packaging Type:
Dimensional weight pricing and automated handling compatibility shape packaging selection across shipper segments.
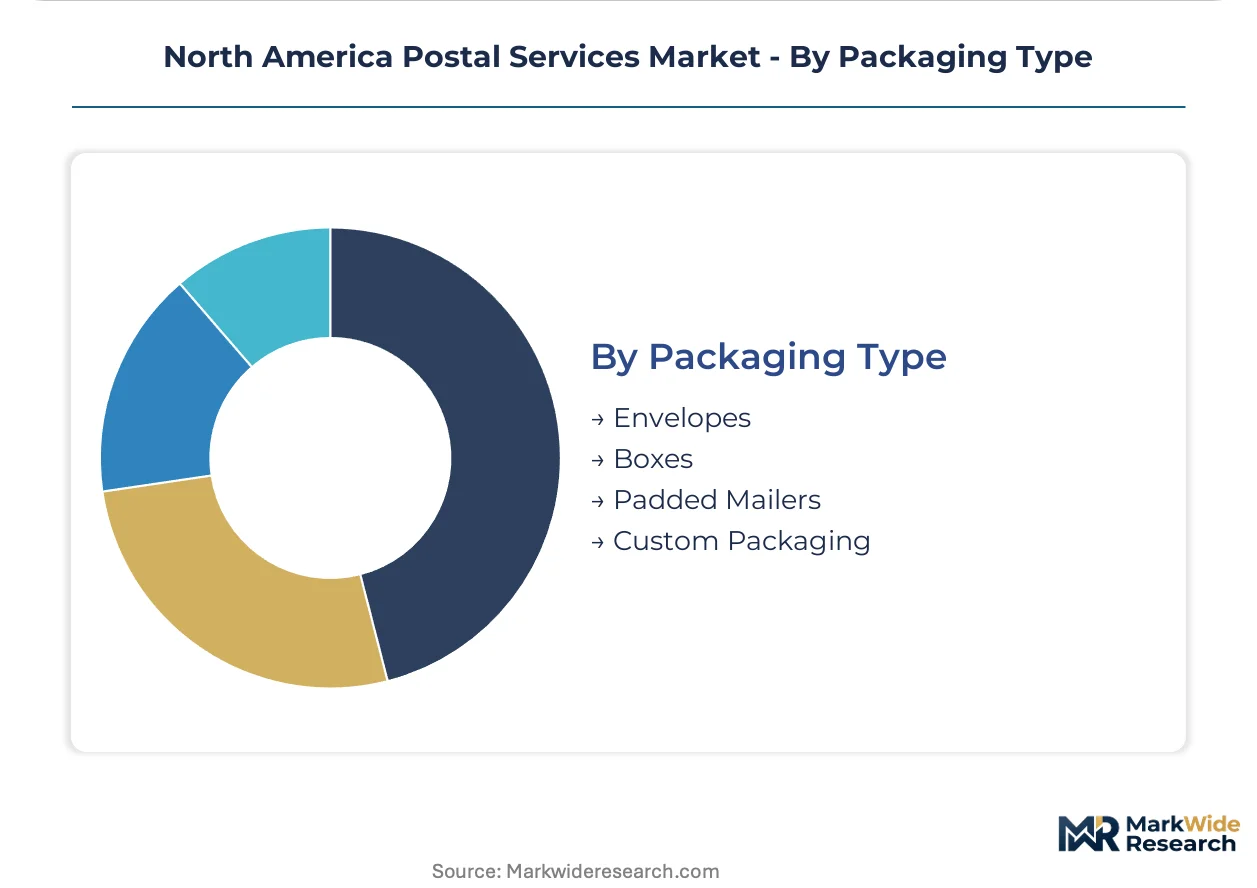
- Boxes:Corrugated containers dominate parcel volume with automated dimensioning systems verifying cube measurements at induction. E-commerce fulfillment centers in Texas and Ohio deploy computer vision to eliminate revenue leakage from misclassified shipments.
- Envelopes:Lightweight flat mailpieces move through high-speed letter sorting infrastructure with barcode tracking. Financial services and insurance sectors generate recurring statement mailing volumes.
- Padded Mailers:Poly-bubble and paper-padded alternatives protect goods while minimizing dimensional weight charges. Apparel and accessory merchants favor this format for soft goods.
- Custom Packaging:Branded unboxing experiences with inserts and protective structures require manual handling exceptions. Premium cosmetics and electronics verticals absorb higher per-unit costs.
Mature deployment sits with Envelopes. Newer deployment is concentrated in Boxes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum refining clusters along the Gulf Coast anchor North American logistics infrastructure. Dense pipeline networks and intermodal terminals concentrate parcel sortation capacity within 500-mile radii of Houston and New Orleans. This feedstock proximity shapes carrier hub placement and last-mile density economics across the continent.
United States
Cross-border e-commerce volumes from Mexico and Canada drive capacity investments at Memphis and Louisville air hubs. The Postal Regulatory Commission exercises rate-setting authority over USPS parcel pricing under statutory reform provisions. Chicago's intermodal terminals host automated sortation facilities serving Midwest manufacturing corridors with dense B2B parcel flows.
Canada
Rural address verification challenges in Prairie Provinces elevate delivery failure costs for remote resource extraction sites. Health Canada and the PMRA oversee pharmaceutical shipment protocols that converge with postal cold-chain standards. Toronto's Pearson Airport corridor anchors express freight consolidation for trans-Pacific e-commerce fulfillment.
Mexico
Manufacturing maquiladoras in Nuevo León and Baja California generate industrial parcel density along the USMCA corridor. The communications ministry supervises Correos de México under federal mandate obligations with evolving universal service requirements. Mexico City metro area parcel locker penetration remains underdeveloped relative to e-commerce growth rates.
North America Postal Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue gig-economy last-mile models and automated locker networks. The North America Postal Services Market structures around three distinct player tiers: integrated express carriers with dedicated air fleets, statutory postal operators with mailbox monopolies, and platform-integrated logistics arms of major retailers. Competitive dynamics center on negotiated service agreement pricing and sortation automation capex cycles. Dominant moves include hub capacity expansion near e-commerce fulfillment clusters and strategic partnerships for rural last-mile coverage.
Within the integrated carrier tier, United Parcel Service and FedEx Corporation exemplify network-scale operators with multi-modal infrastructure spanning the continent. Canada Post Corporation occupies a statutory position under federal mandate obligations. Among platform-integrated entrants, Amazon Logistics represents the retail-captive logistics archetype with dedicated sortation investments.
| Leading Market Players |
|---|
| FedEx Corporation |
| Purolator Inc. |
| United States Postal Service (USPS) |
| OnTrac Logistics |
| Correos de Mexico |
| Canada Post Corporation |
| Deutsche Post DHL Group |
| Amazon Logistics |
| United Parcel Service (UPS) |
| Others |
Value Network & Pricing Analysis
Automated sortation equipment deployment across Memphis, Louisville, and Indianapolis hubs is simultaneously compressing unit processing costs and concentrating carrier bargaining power with high-volume e-commerce shippers. This capital-intensive transition rewards network density and marginalizes regional operators lacking scale to amortize robotics investments.
Pricing Analysis
Guaranteed delivery windows and API-integrated tracking separate bundled premium tiers from unbundled economy alternatives. Pricing stratifies across express, priority, and standard tiers with differentiation driven by delivery speed commitments and dimensional weight accuracy. Cost compression in standard parcel services is intensifying because mega-retailers command volume-based negotiated service agreements. Small and mid-market merchants exhibit highest price sensitivity, while healthcare and legal sectors absorb premium rates for time-definite reliability.
Supply Chain Analysis
Direct-to-retail fulfillment channels handle hyperscale buyer demand through dedicated sortation capacity reserved at primary hubs. Equipment manufacturing concentrates in Germany, Japan, and the United States for optical character recognition and dimensioning systems. Lithium-ion battery cells, aluminum vehicle bodies, and semiconductor components for routing algorithms constitute critical input dependencies. Single-source vulnerability for high-speed sorting machinery creates procurement risk. Distribution runs through hub-and-spoke networks with final-mile density determining last-leg economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive air freight and sortation robotics is accelerating as carriers seek upstream control over capacity constraints and downstream control over delivery scheduling.
For Market Incumbents: To counter Amazon Logistics' dedicated fulfillment infrastructure, United Parcel Service and FedEx Corporation should deepen backward integration into air cargo capacity at Memphis and Louisville while securing exclusive sortation partnerships with high-frequency e-commerce merchants. Postal Regulatory Commission rate flexibility permits competitive parcel pricing that narrows private carrier advantages.
For New Entrants and Emerging Players: Begin with parcel locker deployment in Mexican metropolitan areas where Correos de México infrastructure lags e-commerce penetration. Automated pickup networks serving unbanked populations in Mexico City and Guadalajara represent accessible white space. Partner with convenience retail chains for locker placement density.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated carriers seeking last-mile robotics capabilities and healthcare cold-chain certifications. Five-to-ten-year viability favors operators with demonstrated API integration with dominant e-commerce platforms. Monitor USPS Reform Act implementation pace as inflection signal for competitive pricing parity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hub Capacity Expansion | Memphis and Louisville air hub investments anchor time-definite express commitments for healthcare and legal sectors. |
| Last-Mile Robotics Deployment | Autonomous mobile robots in Chicago and Los Angeles distribution centers compress same-day delivery cycle times. |
| Healthcare Cold-Chain Certification | Temperature-controlled protocols validated by FDA and Health Canada open pharmaceutical and perishable verticals. |
| Parcel Locker Network Buildout | Mexico City automated pickup infrastructure addresses unbanked population access gaps left by Correos de México. |
| Carbon Accounting Tool Development | Shipment-level emissions tracking aligns with SEC climate disclosure rules and TCFD-aligned Canadian securities guidance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this North America Postal Services Market analysis. Primary interviews with parcel operations directors, e-commerce logistics managers, Postal Regulatory Commission policy staff, and sortation equipment procurement leads combined with USPS financial disclosures, Canada Post annual reports, USMCA customs modernization documentation, and carrier negotiated service agreement filings. Bottom-up volume modeling and top-down macroeconomic triangulation validated segment-level outputs.
Reconciliation of shipment volume databases with carrier capacity disclosures and e-commerce fulfillment center expansion permits informed projection construction across the analysis window. Segmentation dimensions modeled include service type, delivery mode, end user category, and packaging format alongside hub-specific capacity utilization rates. CAGRs derived from historical volume trajectories adjusted for regulatory rate authority modifications and fleet electrification capex cycles. Cross-border parcel flow data and rural delivery frequency mandates informed corridor-specific growth assumptions.
Underlying measurement precision varies by segment; express mail and e-commerce business volumes carry tighter precision than standard mail and residential customer segments due to manifest system granularity. Forecasts reflect assumptions regarding labor classification litigation outcomes, battery-electric vehicle procurement timelines, and USMCA customs protocol adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Managed Communication Services Market
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Green Communication Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Pcaas Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Meeting Solutions Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Global Communications Interface Market
Communication Services
Outbound Telemarketing Market
Communication Services
India Communication Platform As a Service (Cpaas) Market
Communication Services
Global Call Center Platform Market
Communication Services
Broadcasting Solutions Market
Communication Services
Speech to Speech Translation Market
Communication Services
Video Managed Services Market
Communication Services
Video Conferencing Market