
 Contact Center As a Service (Ccaas) Market | 2026-2036
Contact Center As a Service (Ccaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Center As a Service (Ccaas) Market Analysis
Subscription-based consumption and usage-based leasing is tilting competitive entry toward asset-light challengers. Five9, Inc. leverages its cloud-native architecture to serve mid-market accounts without heavy infrastructure commitments. Cisco Systems, Inc. anchors enterprise trust through deep security certifications and on-premises migration pathways. Genesys sustains differentiation with AI workforce management layered across hybrid deployment modes.
Contact Center As a Service (CCaaS) denotes cloud-delivered software platforms that ingest voice, digital messaging, and video interactions through APIs, orchestrating agent desktops, workforce optimization, and real-time analytics from vendor-managed data centers. These systems eliminate capital expenditure on private branch exchanges while enabling elastic scaling during demand surges. Cloud-Based Services within the service type dimension carry the broadest margin pools as vendors bundle professional services atop recurring subscriptions. Public Cloud deployments lead volume but Hybrid Cloud configurations are expanding fastest among regulated end users in banking and healthcare that must segment data residency. Omnichannel Platforms across the technology dimension are absorbing disproportionate R&D investment as buyers consolidate previously siloed chat, voice, and social channels.
The Federal Communications Commission (FCC) shapes US demand through robocall mitigation mandates and call authentication protocols that CCaaS providers must embed. The European Union's GDPR and forthcoming AI Act compel vendors to engineer consent management and algorithmic transparency directly into routing engines. Stakeholders must monitor whether compliance tooling becomes a bundled standard or a premium-priced module that restructures vendor selection criteria.
Market Dynamics
Cloud-native architectures are compressing infrastructure barriers, enabling asset-light entrants to challenge established vendors while regulatory mandates across multiple jurisdictions force compliance investments into core routing engines.
Growth Catalysts
- EU AI Act algorithmic transparency:Mandates for documented decision-making in automated call routing are accelerating vendor R&D into explainable AI layers, creating competitive differentiation for early adopters.
- Automotive exporter demand:German industrial manufacturers require multilingual omnichannel support at scale, pulling specialized CCaaS configurations into high-complexity deployments.
- Robocall mitigation protocols:FCC authentication mandates in the United States are embedding trust frameworks directly into platform architectures, expanding addressable market for compliant providers.
Market Restraints
- Data residency segmentation costs:Hybrid cloud configurations required by banking and healthcare end-users impose redundant infrastructure overhead, compressing margins for vendors serving regulated verticals.
- Telecom carrier concentration:Voice termination and SIP trunking supply concentrates among tier-1 network operators in North America, exposing buyers to upstream pricing leverage.
- Legacy PBX substitution lag:On-premises hardware depreciation cycles and sunk capital in private branch exchanges delay cloud migration timelines for mid-market accounts.
Strategic Opportunities
- Usage-based leasing expansion:Consumption models that align costs with interaction volumes are opening mid-market segments previously blocked by subscription minimums.
- Workforce optimization convergence:Integration of AI-driven scheduling with real-time sentiment analysis creates bundled value propositions distinct from point solutions.
- API-first platform architectures:Modular integration with CRM and ERP systems enables vertical-specific configurations without custom development cycles.
Industry Challenges
- Agent desktop integration complexity:Unifying siloed chat, voice, and social channels into single-pane workflows demands extensive professional services engagement, elongating deployment timelines.
- Multilingual support engineering:Real-time translation and cultural localization at scale requires continuous model training and region-specific compliance validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Center As a Service (Ccaas) Market |
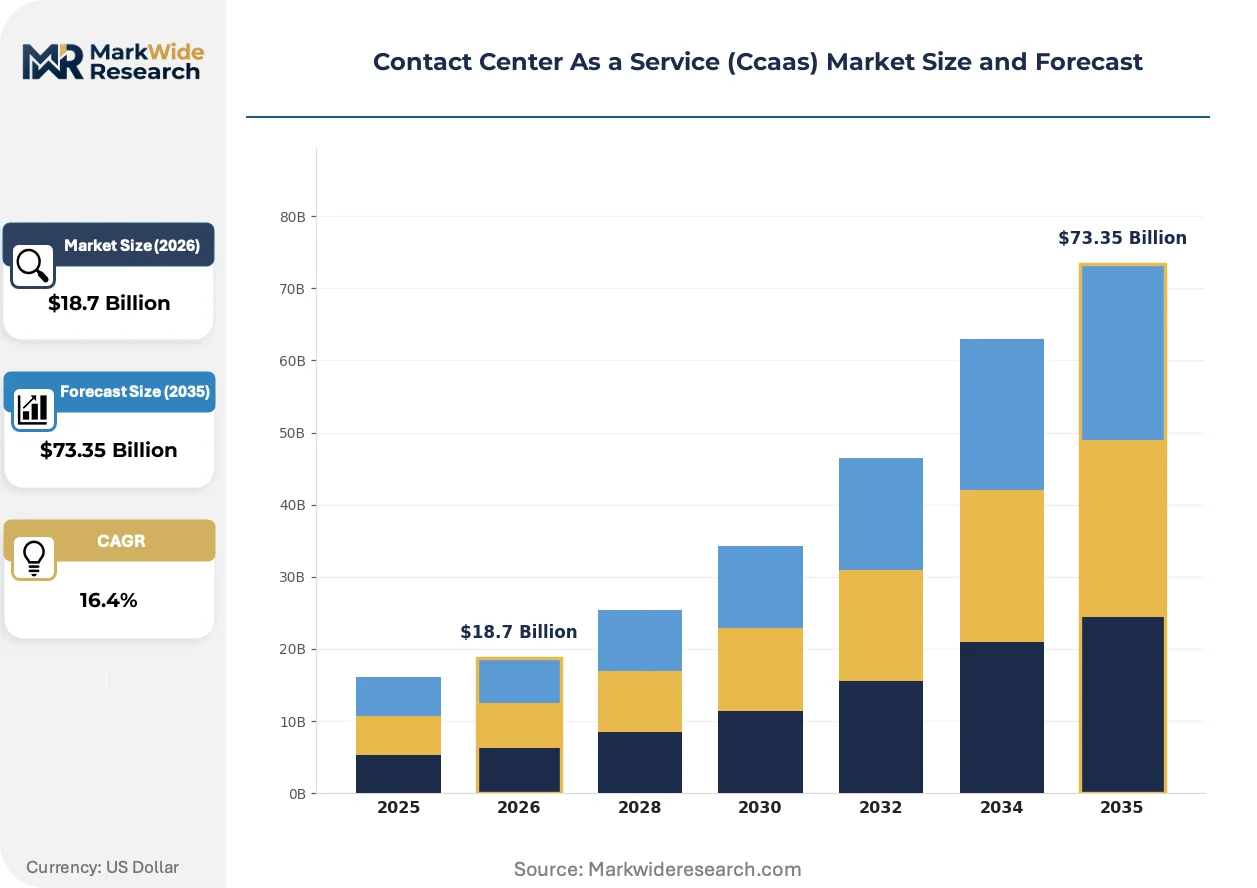
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Self-Service Solutions, Blended Services, Cloud-Based Services Deployment: Private Cloud, Public Cloud, Hybrid Cloud, On-Premises End User: Retail, Banking, Telecommunications, Healthcare Technology: AI Chatbots, VoIP Solutions, CRM Integration, Omnichannel Platforms |
| Companies Covered | Five9, Inc., Genesys, NICE CXone, Talkdesk, 8x8, Inc., RingCentral, Avaya, Inc., Cisco Systems, Inc., Enghouse Interactive Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Center As a Service (Ccaas) Market Emerging Trajectories
Artificial intelligence is restructuring how customer interactions are processed, routed, and analyzed, with vendor investment concentrating on predictive capabilities that anticipate demand surges before they materialize.
Natural language processing is migrating from post-call transcription to real-time sentiment analysis and next-best-action recommendation engines. Retail chains and healthcare providers are deploying these capabilities within eighteen-month refresh cycles. The shift is compressing competitive advantage timelines for vendors lacking native AI infrastructure.
The EU AI Act is mandating algorithmic audit trails for automated decision systems used in customer routing. Vendors must engineer consent management and explainability layers directly into platform cores. Banking and insurance end-users in Germany and France are prioritizing providers with pre-built compliance modules.
Enterprise buying committees are consolidating vendor relationships, favoring platforms that bundle workforce optimization with omnichannel orchestration. Systems integrators and direct sales channels are displacing pure self-serve adoption for deployments exceeding five hundred seats. This concentration is most pronounced in United States healthcare and financial services verticals.
Contact Center As a Service (Ccaas) Market Segmentation
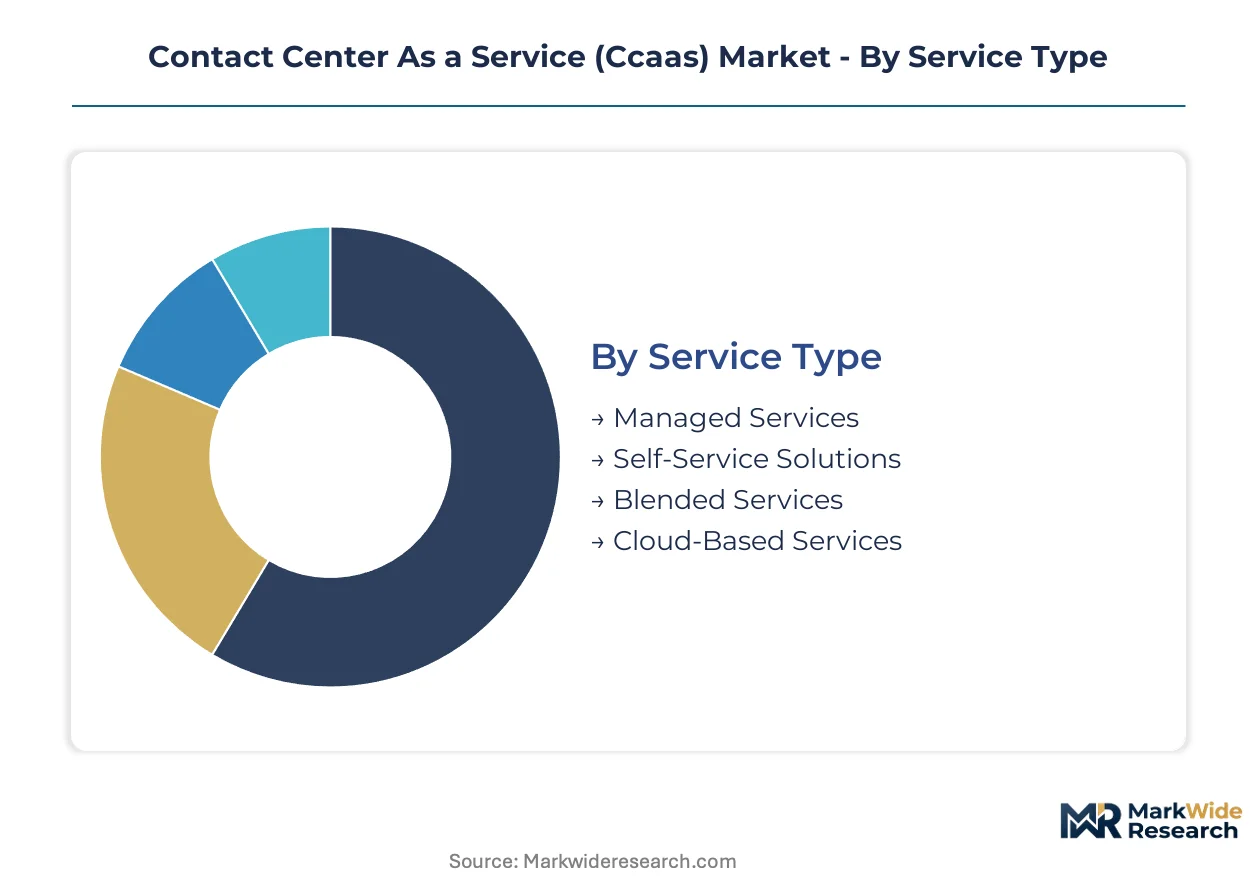
CCaaS procurement patterns diverge sharply across service delivery models, infrastructure configurations, and technology stacks. Buyers segment their vendor selection based on regulatory exposure, interaction complexity, and existing IT estate constraints.
Service Type:
Mature subscription bundles dominate enterprise accounts while emerging consumption models unlock mid-market penetration.
- Cloud-Based Services:Vendor-managed infrastructure delivers elastic capacity through API-orchestrated voice, messaging, and video channels. German automotive exporters and North American retail chains are consolidating procurement here to eliminate PBX capital expenditure while scaling multilingual support during seasonal demand surges.
- Managed Services:Third-party operation of routing engines, agent desktops, and workforce optimization offloads operational complexity to specialized providers. Banking and healthcare end-users in regulated jurisdictions favor this model to satisfy data residency requirements without building internal cloud competencies.
- Self-Service Solutions:Interactive voice response and conversational AI interfaces deflect routine inquiries from live agents.
- Blended Services:Hybrid human-agent and automated touchpoint orchestration balances cost efficiency with escalation pathways.
Cloud-Based Services retains volume leadership; Self-Service Solutions holds the steepest expansion curve.
Deployment:
Cost tier stratification separates commodity public cloud from premium hybrid configurations serving regulated verticals.
- Hybrid Cloud:Segmented infrastructure splits interaction routing between vendor-managed and client-controlled environments. Banking and healthcare buyers mandate this architecture to isolate personally identifiable information within jurisdictional boundaries while leveraging cloud elasticity for non-sensitive workloads.
- Public Cloud:Multi-tenant platforms deliver the lowest per-seat economics through shared infrastructure pools. Mid-market retail and telecommunications providers standardize here, accepting vendor-determined data residency in exchange for rapid deployment and minimal IT overhead.
- Private Cloud:Single-tenant deployments dedicate physical infrastructure to individual clients.
- On-Premises:Legacy PBX and contact center hardware persists in accounts with depreciated capital assets and conservative risk profiles.
Public Cloud dominates seat volume; Hybrid Cloud is climbing the fastest as regulatory pressure intensifies.
End User:
Application complexity varies dramatically across verticals, with interaction volume, compliance burden, and channel diversity shaping platform requirements.
- Banking:Fraud prevention, identity verification, and PCI-DSS compliance mandate encrypted recording, biometric authentication, and immutable audit trails. EU AI Act transparency requirements are accelerating explainable AI adoption for automated credit and service decisions.
- Healthcare:HIPAA obligations in the United States and GDPR health data provisions in Europe require consent-managed routing and restricted agent access to protected information. Telehealth expansion is pulling video interaction capabilities into core platform evaluations.
- Retail:Seasonal demand volatility and omnichannel purchase journeys prioritize elastic scaling and unified cart history across chat, voice, and social touchpoints.
- Telecommunications:High-volume technical support and subscriber retention programs demand workforce optimization integrated with network operations data.
Banking commands the highest per-seat pricing; Healthcare is gaining share fastest as telehealth interaction volumes compound.
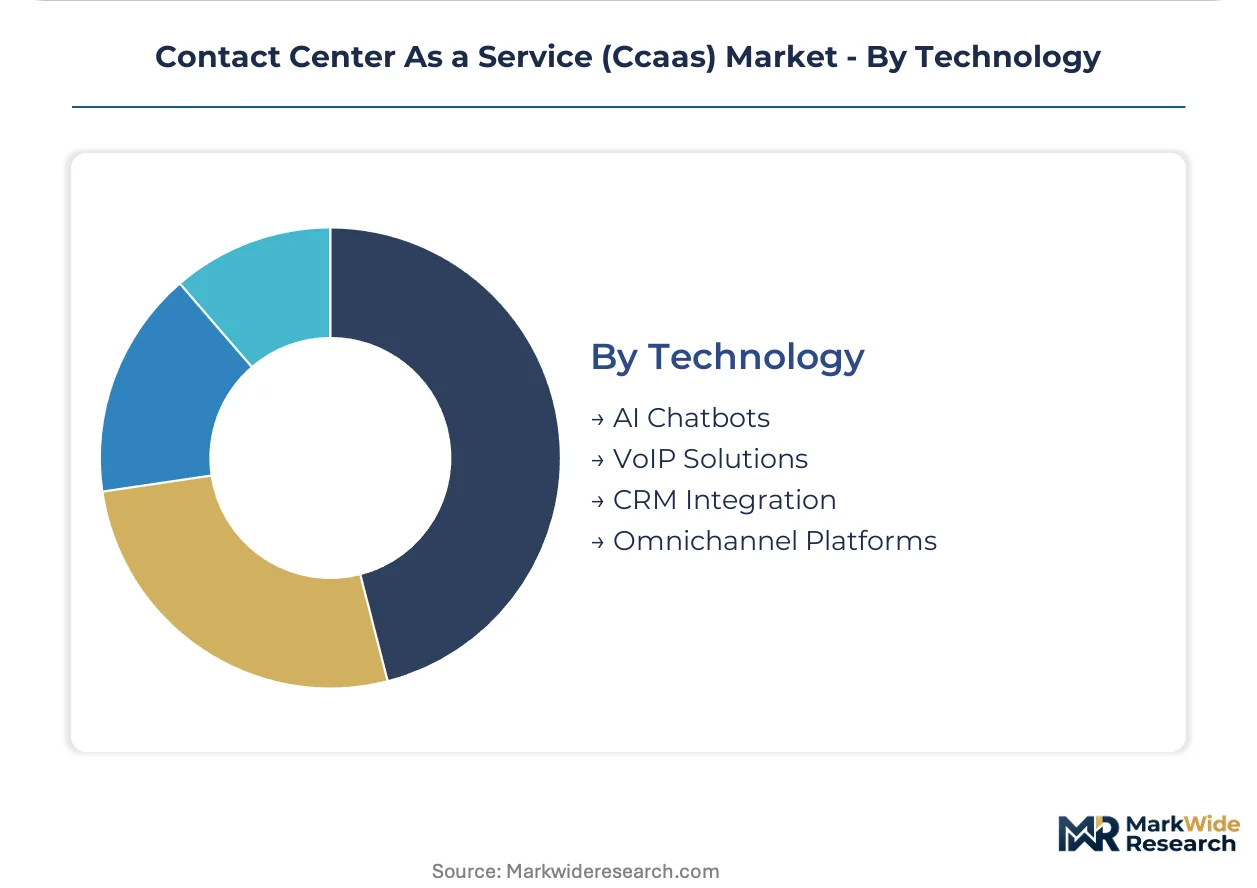
Technology:
Customer type stratification separates integrated platform buyers from point-solution adopters seeking modular augmentation.
- Omnichannel Platforms:Unified orchestration of voice, digital messaging, video, and social channels through single-pane agent desktops. Enterprise buying committees in United States healthcare and financial services are consolidating vendor relationships around these bundles, displacing best-of-breed point solutions.
- AI Chatbots:Natural language processing engines handle intent classification, entity extraction, and conversational flow management. Retail chains are deploying these capabilities within compressed refresh cycles to deflect routine inquiries and compress average handle times.
- CRM Integration:Pre-built connectors to Salesforce, Microsoft Dynamics, and vertical-specific customer data platforms.
- VoIP Solutions:SIP trunking and WebRTC voice delivery replace traditional telephony infrastructure.
Omnichannel Platforms retain the largest deal sizes; AI Chatbots show the steepest expansion trajectory as real-time sentiment analysis matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act is accelerating vendor investment in explainable AI routing engines across European banking and insurance sectors. FCC robocall mitigation mandates in the United States are embedding authentication protocols directly into platform architectures. German automotive exporters are pulling specialized multilingual configurations into high-complexity deployments.
United States
Retail chains are expanding CCaaS deployments to unify customer touchpoints across seasonal demand surges. The FCC mandates STIR/SHAKEN call authentication protocols that providers must embed to maintain carrier interoperability. Silicon Valley and Seattle technology clusters host cloud-native vendors serving mid-market accounts without heavy infrastructure commitments.
Germany
Automotive and industrial exporters require multilingual omnichannel support at scale for complex B2B service interactions. The EU AI Act compels vendors to document algorithmic decision-making in automated call routing systems. Stuttgart and Munich manufacturing corridors are consolidating procurement around hybrid cloud configurations to satisfy data residency requirements.
United Kingdom
Financial services firms in London are prioritizing platforms with pre-built GDPR compliance modules for consent-managed routing. The Financial Conduct Authority scrutinizes outsourcing arrangements for cloud-delivered customer contact operations. The London-Reading technology corridor concentrates vendor development centers serving European multilingual requirements.
France
Banking and insurance end-users in Paris are demanding explainable AI layers for automated credit and service decisions under EU AI Act transparency requirements. CNIL enforcement of GDPR health data provisions shapes platform selection for healthcare providers. The Paris-Saclay cluster hosts AI workforce optimization R&D serving continental European deployments.
Japan
Telecommunications providers and electronics manufacturers are consolidating vendor relationships around platforms bundling workforce optimization with omnichannel orchestration. METI guidance on cloud security certifications influences procurement criteria for regulated verticals. Tokyo and Osaka metropolitan areas concentrate enterprise buying committees evaluating hybrid deployment modes.
Contact Center As a Service (Ccaas) Market Vendor Landscape
Channel-controlling players compete with product-specialist players across deployment modes and vertical applications. The vendor base organizes into three tiers: cloud-native challengers serving mid-market accounts without infrastructure commitments, legacy incumbents anchoring enterprise trust through security certifications, and platform consolidators bundling workforce optimization with routing engines. Dominant competitive moves include M&A to absorb AI workforce management capabilities and strategic partnerships with systems integrators for large-seat deployments.
Within the cloud-native tier, Five9, Inc. and Talkdesk exemplify asset-light architectures that compress infrastructure barriers for expanding mid-market penetration. Cisco Systems, Inc. occupies a position among security-focused incumbents leveraging deep certifications and on-premises migration pathways to anchor regulated vertical relationships. Genesys sits within the platform consolidation archetype, sustaining differentiation through AI workforce management layered across hybrid deployment modes serving complex multinational requirements.
| Leading Market Players |
|---|
| Five9, Inc. |
| Genesys |
| NICE CXone |
| Talkdesk |
| 8x8, Inc. |
| RingCentral |
| Avaya, Inc. |
| Cisco Systems, Inc. |
| Enghouse Interactive Inc. |
| Others |
Supply Flow & Price Mechanics
Silicon Valley cloud infrastructure clusters concentrate hyperscaler capacity that feeds directly into CCaaS vendor cost structures, translating compute density into pricing leverage for enterprise buyers negotiating multi-year commitments. Tier-1 network operators in North America maintain upstream control over voice termination and SIP trunking supply, embedding carrier interoperability costs into platform economics that compress margins for mid-market deployments.
Pricing Analysis
Certification level creates the primary spread across CCaaS tiers, with SOC 2 Type II and ISO 27001 compliance commanding premium positioning over uncertified alternatives. Subscription-based SaaS models dominate, though usage-based consumption is gaining traction among seasonal retail operators. Price differentiation rests on vertical integration depth and after-sales professional services bundling. Cost compression in the mid-market tier is intensifying because asset-light challengers eliminate infrastructure overhead. Healthcare and banking buyers demonstrate lowest price sensitivity due to compliance mandates, while telecommunications providers negotiate aggressively on per-seat economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from tier-1 cloud infrastructure providers anchor vendor working capital structures. Geographic supply concentrates in the United States, Ireland, and Germany for data center capacity, with Singapore and Japan serving Asia-Pacific demand. Raw material dependencies include specialized GPUs for AI inference, submarine fiber cables for latency-sensitive voice, and certified hardware for regulated deployments. Single-source vulnerability in GPU supply chains from NVIDIA concentration poses structural risk. Distribution runs through direct enterprise sales teams, systems integrators, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CCaaS penetration remains in early-cycle expansion as hybrid workforce normalization sustains cloud migration tailwinds across mid-market accounts previously blocked by capital expenditure barriers.
For Market Incumbents: Insulate enterprise relationships by accelerating AI workforce management R&D and embedding EU AI Act compliance modules directly into routing engines. Vertical integration into specialized data residency infrastructure for banking and healthcare verticals defends against asset-light challengers. Channel control through systems integrator exclusivity agreements protects large-seat deployment pipelines. For New Entrants and Emerging Players: Pursue white-space penetration in German automotive exporter segments requiring multilingual omnichannel configurations underserved by generic platforms. Target mid-market retail chains in North America with consumption-based pricing that eliminates subscription minimums. API-first go-to-market positioning enables rapid CRM integration without custom development cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform consolidators bundling workforce optimization with omnichannel orchestration over point-solution specialists. Long-term viability hinges on AI-native infrastructure and hybrid deployment flexibility across regulated jurisdictions. Acquisition target archetype: cloud-native challengers with pre-built compliance modules for EU AI Act and GDPR. The signal to watch is consolidation velocity among buying committees exceeding five hundred seats.| Strategic Initiative | Industry Significance |
|---|---|
| AI Workforce Management Integration | Combines predictive scheduling with real-time sentiment analysis for bundled value propositions. |
| Hybrid Cloud Certification Investment | Enables banking and healthcare data residency compliance without sacrificing elastic scaling. |
| API-First Platform Architecture | Accelerates vertical-specific configurations through modular CRM and ERP connectors. |
| EU AI Act Compliance Module Development | Engineers explainable AI layers and algorithmic audit trails into core routing engines. |
| Systems Integrator Partnership Expansion | Captures large-seat deployments displacing pure self-serve adoption in enterprise accounts. |
Methodological Framework
A standing panel of contact center operations directors, CIOs at retail and healthcare enterprises, cloud procurement officers, and systems integrator practice leads provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against SEC filings of public CCaaS vendors, hyperscaler capex disclosures, FCC robocall mitigation orders, and EU regulatory documentation. Bottom-up seat deployment estimates triangulated against top-down vendor revenue segmentation across service type, deployment mode, and end-user vertical.
Scenario-bracketing framed demand projections across the modeling period, with sensitivity analysis on regulatory adoption timelines and migration lag from legacy PBX estates. Segmentation dimensions modeled include service delivery model, infrastructure configuration, organization size tier, integration complexity, and regional regulatory cluster. CAGRs derived from fitted growth curves anchored to disclosed vendor growth rates and end-user procurement cycle surveys. Forecast inputs incorporated EU AI Act implementation pace and FCC authentication mandate compliance deadlines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by cloud-native challengers or accelerated legacy substitution would shift outcomes. Macroeconomic contraction affecting enterprise software budgets, regulatory delay in EU AI Act enforcement, or breakthroughs in on-premises AI inference could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Voip Services Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
Broadcasting Solutions Market
Communication Services
Global Critical Communication Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Push-To-Talk Market
Communication Services
Mobile Messaging Market
Communication Services
Video Managed Services Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Voice Commerce Market
Communication Services
Asia-Pacific Postal Services Market
Communication Services
Postal Services Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Pcaas Market