
 Green Communication Market | 2026-2036
Green Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Green Communication Market Foresight
Enterprise procurement of communication infrastructure is tilting toward energy-certified equipment as sustainability metrics enter vendor scorecards. Nokia Oyj leverages its Bell Labs research engine to develop liquid-cooled base stations that slash thermal overhead. Telefónica SA anchors its network modernization in renewable-powered data centers across Iberia and Latin America. Cisco Systems Inc competes through modular hardware designs that extend equipment lifecycles and reduce e-waste volumes.
Green communication encompasses low-energy protocols, recyclable hardware materials, and carbon-neutral data transmission architectures engineered to minimize electromagnetic footprint and operational power draw. Systems typically incorporate sleep-mode algorithms, ambient-powered sensors, and biodegradable circuit substrates to achieve Energy Star and TCO certifications while maintaining latency thresholds under 10 milliseconds for real-time applications. Cloud computing infrastructure captures the largest margin pool as hyperscalers negotiate renewable energy contracts for server farms, while 5G radio access networks represent the fastest-expanding segment due to massive MIMO antenna deployments requiring targeted efficiency gains. Collaboration software trails in revenue contribution but shows structural promise as vendors embed carbon accounting dashboards into subscription tiers.
The EU Green Deal and REACH chemical standards constrain hardware material choices across European supply chains, while the EPA Energy Star program and FCC equipment authorization rules shape product qualification pathways in the United States. India's BIS energy efficiency labeling and the PLI scheme for telecom manufacturing redirect domestic production toward compliant, export-ready gear. Stakeholders must track evolving carbon border adjustment mechanisms and renewable energy certificate requirements as these frameworks increasingly determine market access eligibility and procurement qualification criteria.
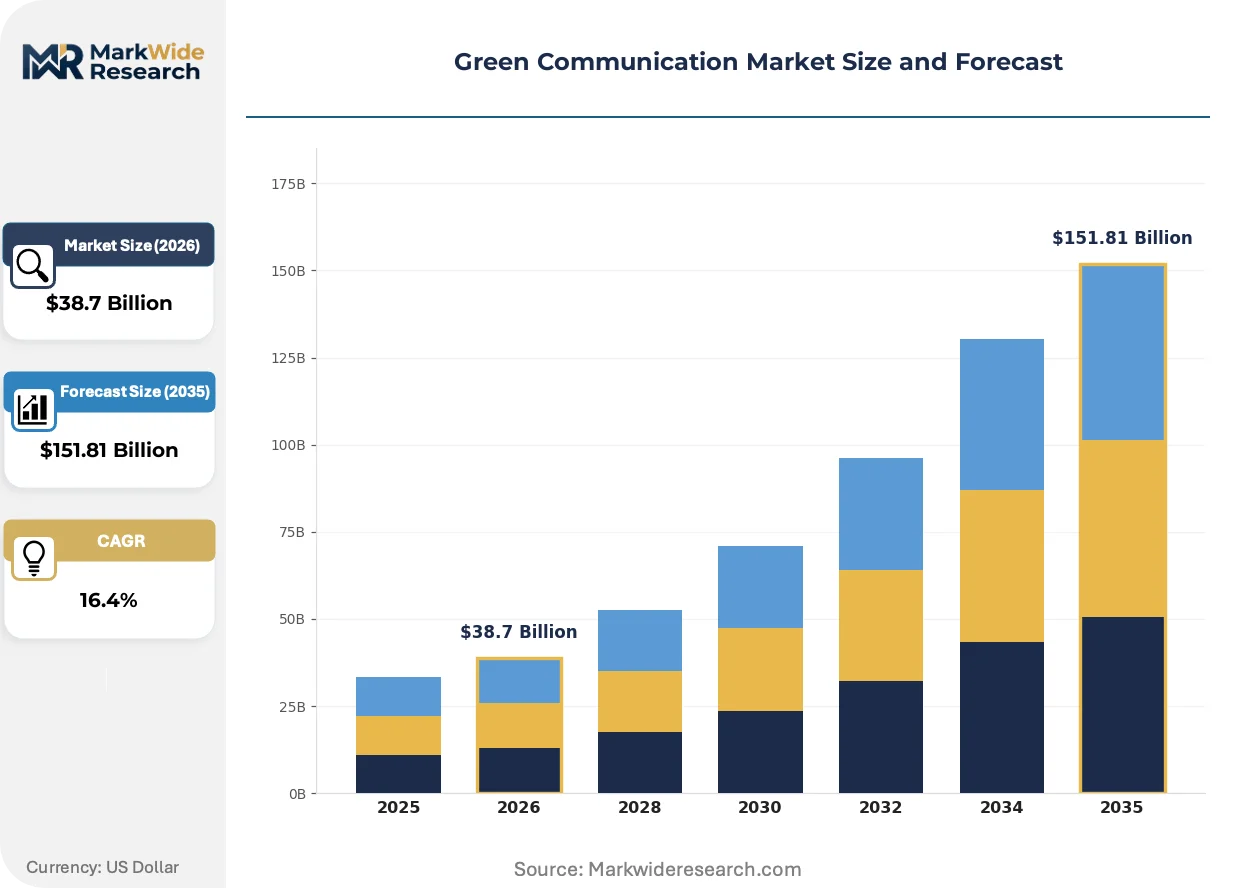
Market Dynamics
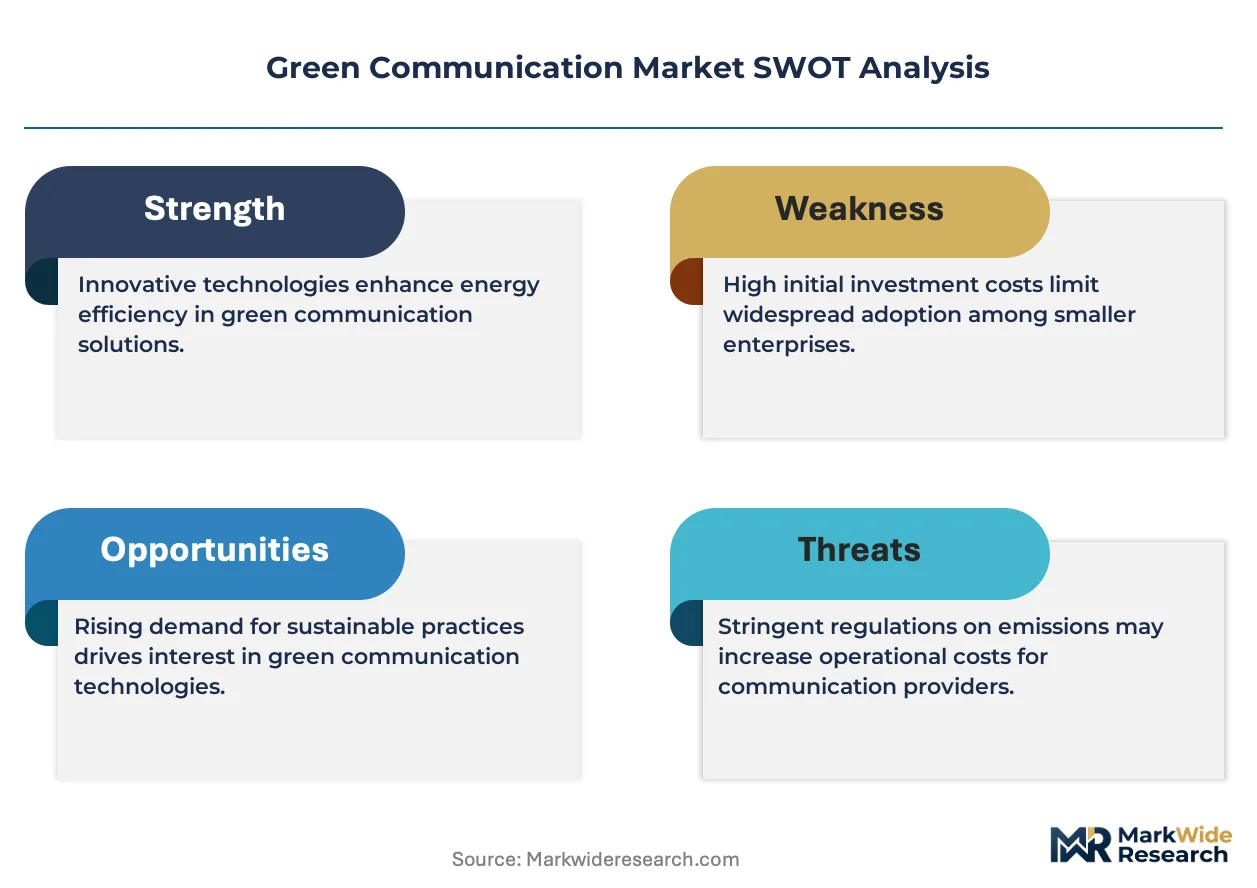
Carrier capex cycles are compressing as energy costs claim 20-40% of network operating budgets, forcing equipment vendors to embed power efficiency as a primary design constraint rather than an afterthought.
Growth Catalysts
- EU Green Deal carbon mandates:The framework's 2030 net-zero targets for telecom infrastructure accelerate hardware refresh timelines across member states. Operators face penalties for non-compliance.
- Hyperscale data center buildouts:Cloud providers in Virginia, Frankfurt, and Singapore negotiate renewable power purchase agreements that cascade efficiency requirements down the supply chain.
- Massive MIMO antenna densification:5G small cell deployments multiply power draw per square kilometer, creating urgent demand for sleep-mode algorithms and ambient-powered edge nodes.
Market Restraints
- Rare earth supply concentration:Neodymium and dysprosium for high-efficiency magnets concentrate in Chinese processing facilities, exposing equipment makers to input volatility and export restriction risk.
- REACH chemical compliance costs:The EU's substance restrictions force reformulation of flame-retardant circuit substrates, adding 12-18 months to product qualification timelines.
- Copper-aluminum substitution limits:Thermal conductivity constraints prevent full displacement of copper in high-frequency RF components, capping potential material cost reductions.
Strategic Opportunities
- India PLI scheme for telecom manufacturing:Production-linked incentives redirect assembly capacity toward export-ready, BIS-certified green equipment for African and Southeast Asian markets.
- AI-driven network optimization:Machine learning traffic prediction converges with liquid cooling systems to enable dynamic power scaling in urban base station clusters.
- Carbon accounting software integration:Real-time emissions dashboards embedded in enterprise collaboration subscriptions create recurring revenue streams distinct from hardware margins.
Industry Challenges
- Thermal engineering talent scarcity:Liquid cooling system design requires specialized fluid dynamics expertise concentrated in automotive and aerospace sectors, not traditional telecom hiring pools.
- Multi-vendor interoperability testing:Sleep-mode algorithms from different base station OEMs create handoff failures during low-traffic periods, demanding costly system integration labor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Communication Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IP Telephony, Video Conferencing, Unified Messaging, Collaboration Software Technology: VoIP, Wireless Networks, Cloud Computing, 5G End User: Corporate Sector, Government Agencies, Educational Institutions, NGOs Application: Remote Working, Smart Cities, Sustainable Development, Eco-Friendly Transport |
| Companies Covered | Telefónica SA, Turkcell, Nokia Oyj, SAP SE, NatWest Group, Telefonaktiebolaget LM Ericsson, Telefônica Brasil SA, Cellnex Telecom SA, Cisco Systems Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Communication Market Shifts & Advancements
Silicon photonics and advanced thermal architectures are rewriting the power-performance tradeoff in high-throughput communication systems, compressing legacy copper-based designs into niche applications.
Silicon photonic transceivers convert electrical signals to optical pulses within the chip package, eliminating discrete laser assemblies. Hyperscalers in Oregon and Dublin deploy these modules at 800G speeds for intra-data center links. The technology is collapsing the cost floor for terabit-scale interconnects, pressuring commodity copper cable vendors toward obsolescence in high-bandwidth applications.
REACH chemical standards now restrict halogenated flame retardants in printed circuit boards across EU supply chains. Manufacturers must qualify phosphorus-based alternatives that meet UL 94 V-0 ratings without bromine content. German industrial buyers retrofitting factory automation networks face 18-month recertification delays, accelerating preference for pre-compliant Asian component suppliers.
Enterprise buyers now embed carbon intensity metrics into vendor scorecards alongside latency and uptime guarantees. Procurement teams in Frankfurt and Amsterdam weight Scope 3 emissions data at 15-25% of total evaluation criteria. This behavioral shift favors modular hardware designs with documented end-of-life recycling pathways, disadvantaging sealed-unit competitors with opaque material chains.
Green Communication Market Segmentation
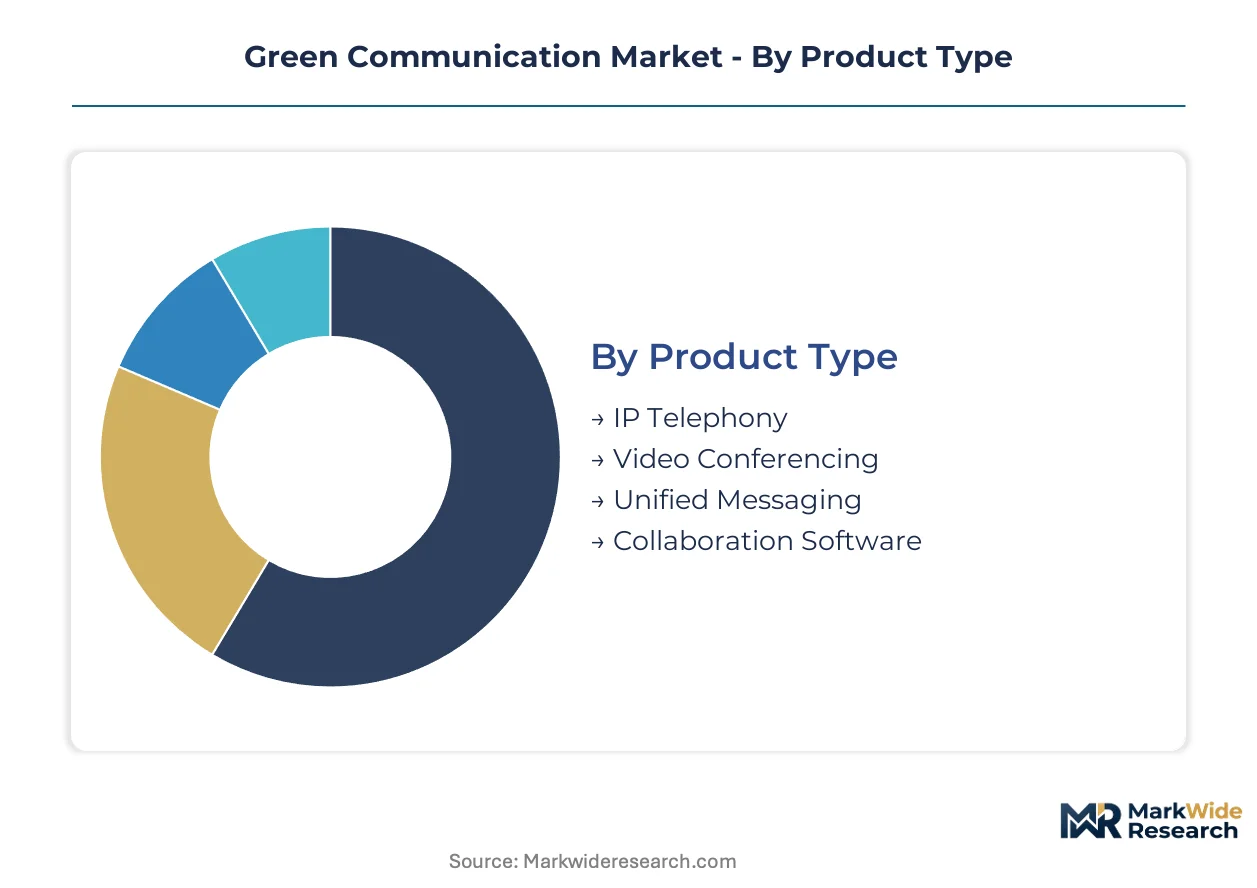
Segmentation in green communication reveals how sustainability mandates reshape procurement patterns across hardware, software, and service layers. Vendors must align product roadmaps with divergent energy efficiency requirements spanning enterprise collaboration tools and carrier-grade infrastructure.
Product Type:
Cost tier differentiation separates capital-intensive hardware deployments from recurring software subscriptions with embedded carbon tracking.
- IP Telephony:Session Initiation Protocol (SIP) trunking and Power over Ethernet (PoE) handsets reduce per-port energy draw below 3 watts in sleep mode. German industrial buyers prioritize Energy Star-certified desk phones with documented end-of-life recycling pathways.
- Video Conferencing:Hardware codecs with AI-driven background suppression and automatic framing cut bandwidth consumption by 40-60% versus legacy H.264 implementations. Corporate procurement teams in Frankfurt and Amsterdam weight Scope 3 emissions data at 15-25% of vendor scorecards.
- Unified Messaging:Cloud-native architectures consolidate voicemail, email, and fax into single-tenant or multi-tenant platforms with renewable-powered data centers.
- Collaboration Software:SaaS platforms embed real-time carbon accounting dashboards into subscription tiers, creating recurring revenue distinct from hardware margins.
IP Telephony holds installed capacity. Collaboration Software is rotating up the share rankings.
Technology:
Application maturity varies sharply, with legacy voice protocols giving way to packet-switched and cellular architectures engineered for power efficiency.
- VoIP:G.729 and Opus codecs compress voice streams to 8-32 kbps, slashing transport energy versus circuit-switched PSTN. Rural broadband extension programs in India leverage VoIP for low-power village connectivity.
- Wireless Networks:Wi-Fi 6E and 7 introduce target wake time (TWT) scheduling that extends IoT sensor battery life to 5-10 years. Smart city deployments in Singapore and Barcelona prioritize mesh networks with solar-powered edge nodes.
- Cloud Computing:Hyperscale data centers in Virginia, Frankfurt, and Singapore negotiate renewable power purchase agreements that cascade efficiency requirements through server, storage, and networking tiers.
- 5G:Massive MIMO antenna densification multiplies power draw per square kilometer, creating urgent demand for sleep-mode algorithms and liquid-cooled base stations.
Cloud Computing dominates current infrastructure spend. 5G is expanding most quickly as carriers modernize radio access networks.
End User:
Customer type determines procurement sophistication, from standardized government tenders to bespoke NGO sustainability mandates.
- Corporate Sector:Fortune 500 procurement teams mandate ISO 14001-certified vendors with verified Scope 1-3 emissions disclosure. ESG-linked financing accelerates refresh cycles for energy-efficient unified communication systems.
- Government Agencies:EU member state public tenders embed EU Green Deal compliance as mandatory technical criteria, disqualifying non-conforming bidders. National net-zero targets for telecom infrastructure accelerate hardware replacement timelines.
- Educational Institutions:University procurement prioritates TCO-certified endpoints with modular designs extending equipment lifecycles.
- NGOs:Development organizations specify biodegradable circuit substrates and conflict-free mineral sourcing for field-deployed communication kits.
Corporate Sector commands premium pricing. Government Agencies are climbing the fastest on policy-mandated refresh cycles.
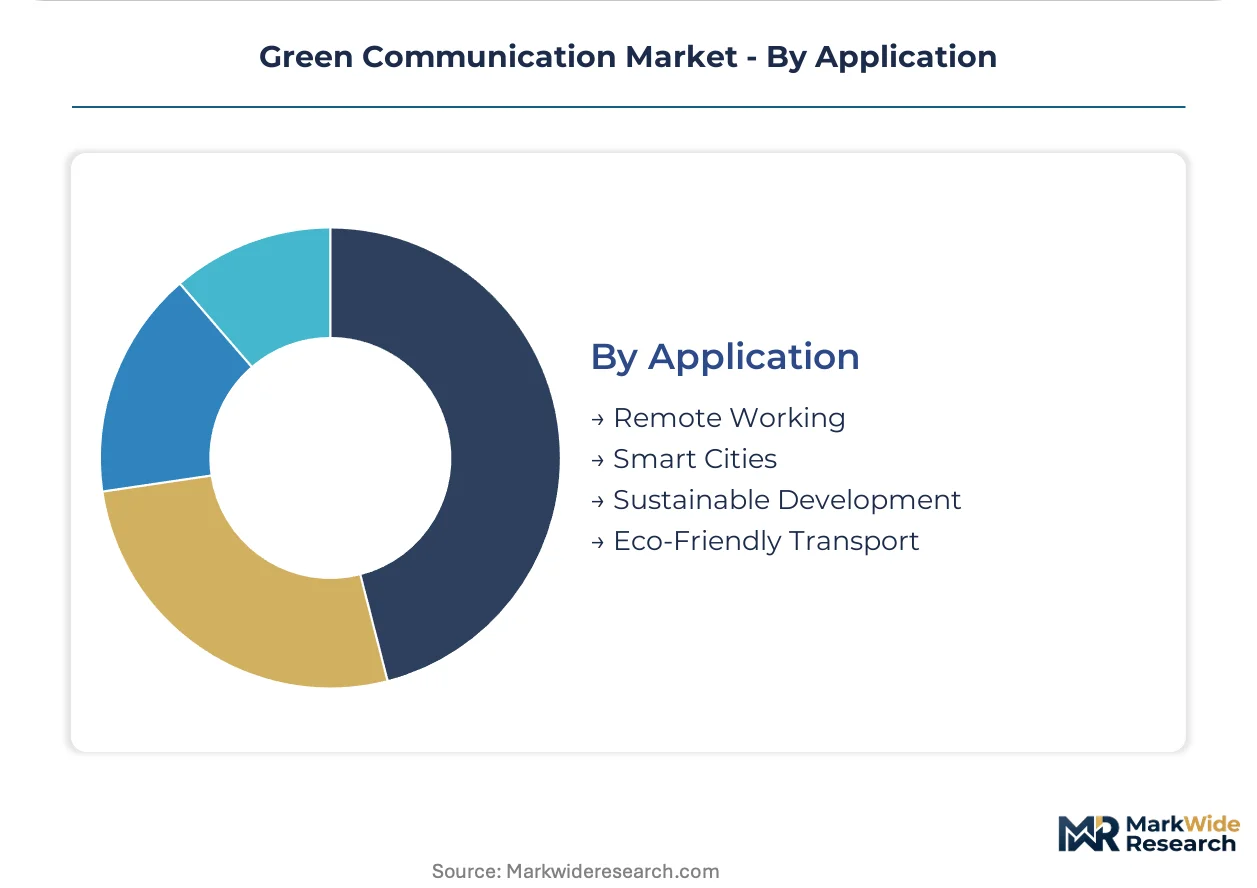
Application:
Volume concentration tracks urbanization patterns and remote work permanence across post-pandemic labor markets.
- Remote Working:Distributed workforce models sustain demand for low-latency home office equipment with sub-10 millisecond response thresholds. Enterprise buyers in Amsterdam and London retrofit residential broadband with business-grade QoS.
- Smart Cities:Integrated traffic, lighting, and public safety networks require ambient-powered sensors with sleep-mode algorithms. Barcelona and Singapore deploy city-wide IoT backbones with renewable-powered edge computing.
- Sustainable Development:Off-grid communication infrastructure serves rural electrification programs with solar-powered base stations and satellite backhaul.
- Eco-Friendly Transport:Vehicle-to-everything (V2X) protocols enable traffic optimization and platooning for electric bus and rail fleets.
Remote Working absorbed pandemic-era investment. Smart Cities is gaining share fastest on infrastructure stimulus allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's 2030 net-zero targets for telecom infrastructure accelerate equipment refresh cycles across member states. India's PLI scheme redirects manufacturing capacity toward export-ready green gear. Singapore and Barcelona anchor smart city deployments with renewable-powered edge computing clusters.
Germany
Industrial buyers in the Ruhr Valley and Bavaria retrofit factory automation networks with low-power unified communication systems. The national net-zero mandates for telecom infrastructure compress hardware replacement timelines. Berlin-based procurement teams weight Scope 3 emissions data at 15-25% of vendor scorecards.
United States
Hyperscalers in Virginia and Oregon negotiate renewable power purchase agreements that cascade efficiency requirements through server and networking tiers. The EPA Energy Star program and FCC equipment authorization rules shape product qualification pathways. Corporate procurement teams in Seattle and Austin mandate ISO 14001-certified vendors with verified emissions disclosure.
India
Rural broadband extension programs leverage VoIP for low-power village connectivity across Maharashtra and Gujarat. The BIS energy efficiency labeling scheme and PLI scheme for telecom manufacturing redirect domestic production toward compliant, export-ready gear. Bangalore anchors smart city deployments with solar-powered edge nodes.
Singapore
Smart city deployments prioritize mesh networks with solar-powered edge nodes and ambient-powered sensors. The national regulator shapes procurement standards for renewable-powered data centers. Enterprise buyers retrofit residential broadband with business-grade QoS across the city-state's financial district.
Spain
Network modernization programs anchor renewable-powered data centers across Iberia. The EU Green Deal compliance requirements accelerate hardware refresh timelines for Telefónica SA's infrastructure. Barcelona deploys city-wide IoT backbones with renewable-powered edge computing for integrated traffic and public safety networks.
Green Communication Market Competitive Landscape
On the supply side, the industry is consolidating around integrated infrastructure vendors with captive R&D engines and modular hardware portfolios. Tiered competition separates hyperscale cloud providers, telecom equipment OEMs, and enterprise software vendors with embedded carbon tracking. Dominant competitive moves include strategic partnerships for renewable energy procurement and portfolio diversification into AI-driven network optimization tools.
Within the telecom equipment tier, Nokia Oyj and Telefónica SA exemplify the integrated infrastructure archetype, while Cisco Systems Inc occupies a position bridging enterprise networking with modular sustainability designs. These entities represent the supply-side concentration where energy efficiency R&D and renewable-powered deployment capabilities determine vendor selection outcomes.
| Leading Market Players |
|---|
| Telefónica SA |
| Turkcell |
| Nokia Oyj |
| SAP SE |
| NatWest Group |
| Telefonaktiebolaget LM Ericsson |
| Telefônica Brasil SA |
| Cellnex Telecom SA |
| Cisco Systems Inc |
| Others |
Supply & Pricing Matrix
Rare earth processing concentration in Chinese facilities for neodymium and dysprosium feeds directly into margin compression for European base station manufacturers competing on liquid-cooled designs. Equipment vendors face asymmetric pricing power as raw material volatility cascades through tiered hardware procurement contracts.
Pricing Analysis
Volume-discount tiering structures separate hyperscale cloud procurement from mid-market enterprise deployments. Three-tier pricing stratifies across Energy Star-certified premium hardware, standard modular equipment, and economy-grade refurbished gear. Cost compression in the mid-tier intensifies as Indian PLI-subsidized manufacturers enter European supply chains. Corporate buyers with ESG-linked financing exhibit lowest price sensitivity, while educational institutions and rural broadband programs anchor the economy tier.
Supply Chain Analysis
Tariff exposure between Chinese rare earth processors and European equipment fabricators dominates supply chain risk assessment for green communication hardware. Manufacturing draws from China for magnet assemblies, Germany for precision thermal components, and Taiwan for silicon photonic transceivers. Copper and phosphorus-based flame retardant dependencies create single-source vulnerability during REACH recertification cycles. Distribution runs through carrier-direct procurement channels for telecom infrastructure and value-added resellers for enterprise collaboration software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green communication sits in early-cycle expansion as EU Green Deal enforcement accelerates hardware replacement timelines across member state telecom infrastructure. Massive MIMO densification and liquid cooling adoption represent underpenetrated technology transitions with decade-long runway.
For Market Incumbents: Pre-empt silicon photonic module integration by securing captive supply agreements with optical component specialists before cost curves collapse copper interconnect margins. Accelerate liquid cooling R&D hiring from automotive thermal engineering pools to address talent scarcity constraining base station deployment timelines. Defend position against modular Asian competitors by embedding carbon accounting software into recurring subscription tiers. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized manufacturing ecosystem for export-ready green equipment serving African and Southeast Asian markets. Target smart city edge computing deployments in Singapore and Barcelona where ambient-powered sensor networks require specialized low-power protocol expertise. Lead with AI-driven network optimization tools as a service layer above commodity hardware procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native collaboration software as SaaS delivery models displace on-premise infrastructure deployment. Long-term viability favors platforms with embedded carbon tracking capabilities and renewable energy contract portfolios. Monitor hyperscaler renewable power purchase agreement volumes as the signal to watch for infrastructure demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling System Deployment | Nokia Oyj and Telefónica SA anchor thermal efficiency gains in urban base station clusters. |
| Silicon Photonic Module Integration | Hyperscalers in Oregon and Dublin compress interconnect costs at 800G speeds. |
| Carbon Accounting Software Embedding | SaaS vendors create recurring revenue distinct from hardware margin pools. |
| REACH-Compliant Material Qualification | German industrial buyers accelerate preference for pre-certified Asian suppliers. |
| Renewable Power Purchase Agreements | Cloud providers in Virginia and Frankfurt cascade efficiency requirements through supply chains. |
Research Methodology
Desk research of carrier capex disclosures, hyperscaler sustainability reports, and EU regulatory filings preceded structured interviews with telecom infrastructure procurement directors, thermal engineering leads at equipment OEMs, and enterprise IT sustainability officers. Secondary validation drew from EPA Energy Star certification databases, BIS energy efficiency registries, and PLI scheme beneficiary disclosures. Bottom-up equipment shipment estimates triangulated against top-down carrier infrastructure spending forecasts.
Assumptions held fixed include EU Green Deal enforcement timelines and rare earth supply concentration patterns, while renewable energy cost curves and AI optimization adoption rates were varied across sensitivity scenarios. Segmentation dimensions modeled span product type, technology protocol, end-user sophistication, and application environment. CAGRs were derived from equipment refresh cycle compression analysis and hyperscale data center buildout trajectories. Inputs included liquid cooling penetration rates and phosphorus-based flame retardant qualification timelines.
Sensitivities concentrate around REACH regulatory expansion, Chinese export restriction enforcement, and thermal engineering talent migration patterns. Forecasts reflect documented assumptions regarding carrier energy cost thresholds and enterprise ESG procurement weighting. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Outbound Telemarketing Market
Communication Services
Dispatch Console Market
Communication Services
Video Managed Services Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Voice Commerce Market
Communication Services
Managed Communication Services Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Global Call Center Platform Market
Communication Services
Audio Conferencing Services Market
Communication Services
North America Postal Services Market
Communication Services
Video Conferencing Market
Communication Services
Meeting Solutions Market
Communication Services
Web Conferencing Market
Communication Services
Industrial Communication Market
Communication Services
India Communication Platform As a Service (Cpaas) Market