
 Voip Services Market | 2026-2036
Voip Services Market Size, Share, and Industry Trends Forecast 2026-2036
Voip Services Market Outlook
Cloud infrastructure providers across North America are recalibrating network capacity to absorb surging VoIP traffic volumes. Microsoft Corporation leverages its Teams ecosystem to anchor enterprise voice workloads within existing productivity suites. Cisco Systems, Inc. competes through specialized hardware-software integration that sustains on-premises loyalty among security-sensitive buyers. Zoom Video Communications, Inc. dominates the mid-market segment with simplified deployment that reduces IT overhead.
VoIP services transmit voice communications as packetized data over IP networks using codecs such as G.711 and Opus at bit rates ranging from 6.6 kbps to 64 kbps, replacing circuit-switched telephony with session initiation protocol signaling for call setup and teardown. Hosted VoIP leads service type adoption as organizations outsource infrastructure maintenance to cloud operators, while mobile VoIP grows fastest among field-service and logistics workforces requiring seamless handoff between cellular and Wi-Fi transport. The subscription pricing model captures recurring revenue from SMEs seeking predictable operational expenditure, whereas freemium tiers function as conversion funnels for individual and micro-business acquisition.
The FCC enforces STIR/SHAKEN authentication frameworks to combat illegal robocalling, compelling carriers to implement digital certificate verification that raises compliance costs for smaller resellers. The EU AI Act and GDPR jointly constrain automated call analytics and voice data retention practices, shaping product architecture for European deployments. Enterprises must monitor regulatory divergence between jurisdictions when architecting cross-border voice infrastructure and selecting vendor compliance certifications.
Market Dynamics
The VoIP services market is undergoing structural compression as FCC-mandated STIR/SHAKEN authentication forces carriers to rebuild signaling infrastructure, while enterprise buyers simultaneously collapse voice, video, and messaging into unified communications platforms.
Growth Catalysts
- STIR/SHAKEN Mandate:The FCC's caller ID authentication framework compels service providers to upgrade digital certificate verification systems, creating replacement demand across the carrier ecosystem.
- Hybrid Work Normalization:Enterprise contact centers in the United States sustain unified communications spending as distributed workforces require seamless voice integration with collaboration tools.
- Opus Codec Adoption:Low-bitrate audio compression at 6.6-64 kbps enables high-fidelity voice transmission over constrained cellular and Wi-Fi networks for field-service applications.
Market Restraints
- Compliance Cost Concentration:Smaller resellers face disproportionate burden from STIR/SHAKEN certificate infrastructure, accelerating consolidation toward scaled cloud operators.
- Legacy PBX Stranded Assets:On-premises hardware depreciation timelines misalign with SaaS migration cycles, delaying full cloud transitions in regulated industries.
- EU Regulatory Friction:The AI Act and GDPR jointly constrain automated call analytics and voice data retention, fragmenting product architecture for European deployments.
Strategic Opportunities
- Mobile VoIP Expansion:Logistics and field-service workforces in Germany and France demand seamless handoff between cellular and Wi-Fi transport for fleet dispatch applications.
- Freemium Conversion Funnels:Micro-business acquisition through zero-cost tiers creates addressable base for premium feature upsell in price-sensitive segments.
- API-First Voice Embedding:Convergence of WebRTC with CRM platforms enables contextual call intelligence inside Salesforce and HubSpot workflows.
Industry Challenges
- SIP Trunk Certification Delays:Enterprise IT teams face extended validation cycles for session border controller interoperability with existing firewall architectures.
- Voice Security Talent Scarcity:Shortage of engineers proficient in both real-time transport protocol hardening and TLS certificate management slows secure deployment timelines.
- Cross-Border Compliance Complexity:Divergent data localization requirements between the United States and European Union force redundant infrastructure provisioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voip Services Market |
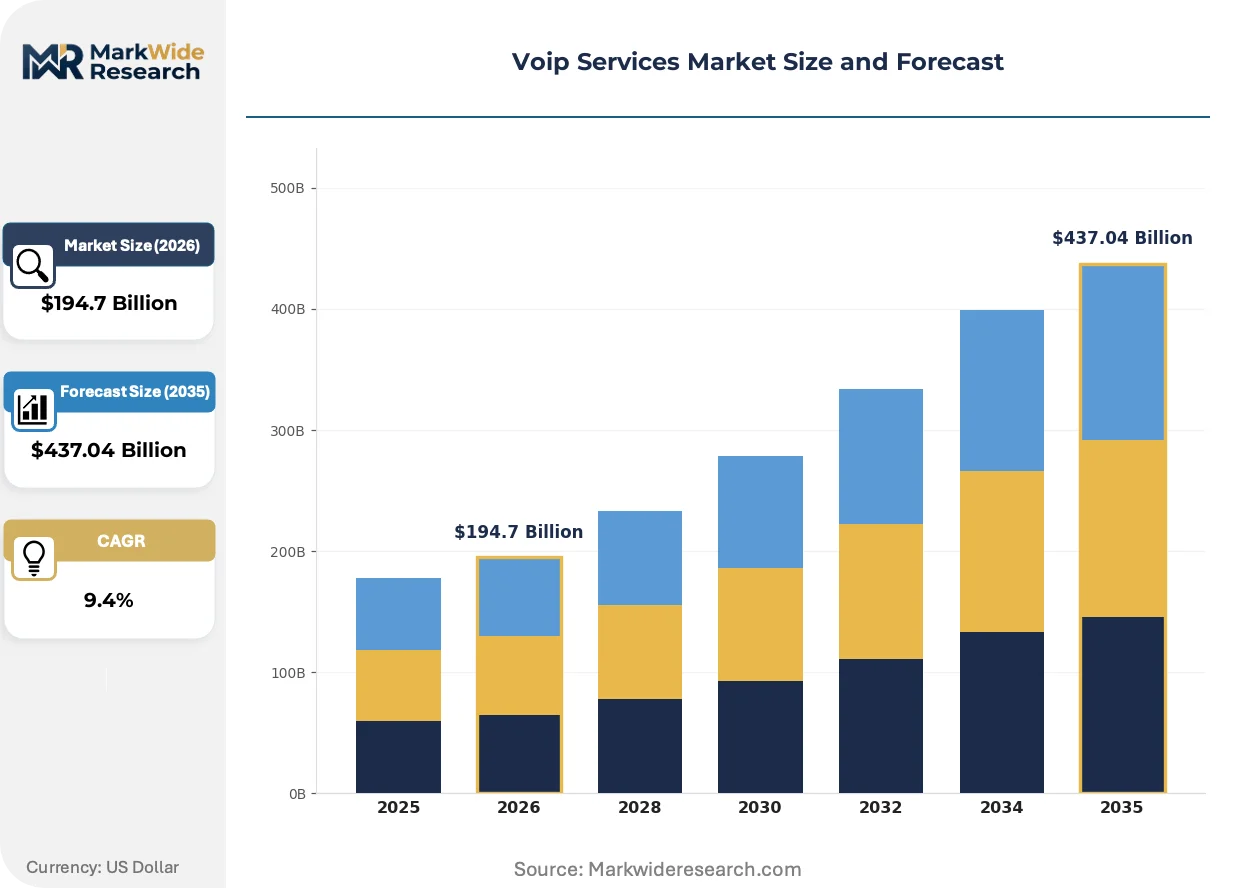
| Market Size in 2026 | $194.7 Billion |
| Market Size in 2035 | $437.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hosted VoIP, On-Premises VoIP, Mobile VoIP, Hybrid VoIP Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: SMEs, Large Enterprises, Government, Individuals Pricing Model: Subscription, Pay-As-You-Go, One-Time Fee, Freemium |
| Companies Covered | RingCentral, Inc., Cisco Systems, Inc., Microsoft Corporation, Vonage Holdings Corp., Nextiva, 8x8, Inc., Dialpad, Inc., Zoom Video Communications, Inc., GoTo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voip Services Market Strategic Shifts
Artificial intelligence is restructuring how voice traffic is processed, authenticated, and monetized across carrier and enterprise environments. Three convergent developments are compressing competitive timelines and redefining service boundaries.
AI-powered noise suppression and real-time transcription is absorbing quality assurance and compliance monitoring functions previously handled by discrete hardware appliances. Financial services contact centers in the United States are deploying these capabilities at scale, eliminating dedicated recording infrastructure while compressing vendor relationships into platform consolidators.
The EU AI Act's risk classification framework for biometric voice analysis is forcing European carriers to segment product roadmaps between high-risk and limited-risk use cases. Automated sentiment scoring now requires explicit consent architectures and algorithmic audit trails, compelling architecture changes for multilingual deployments in France and Germany.
Consumption patterns among mid-market buyers are fragmenting traditional seat-based licensing into metered usage models aligned with actual call volumes. Channel partners in the United Kingdom are replacing perpetual licenses with consumption-based billing, while value-added resellers unbundle implementation services from recurring software fees.
Voip Services Market Segmentation
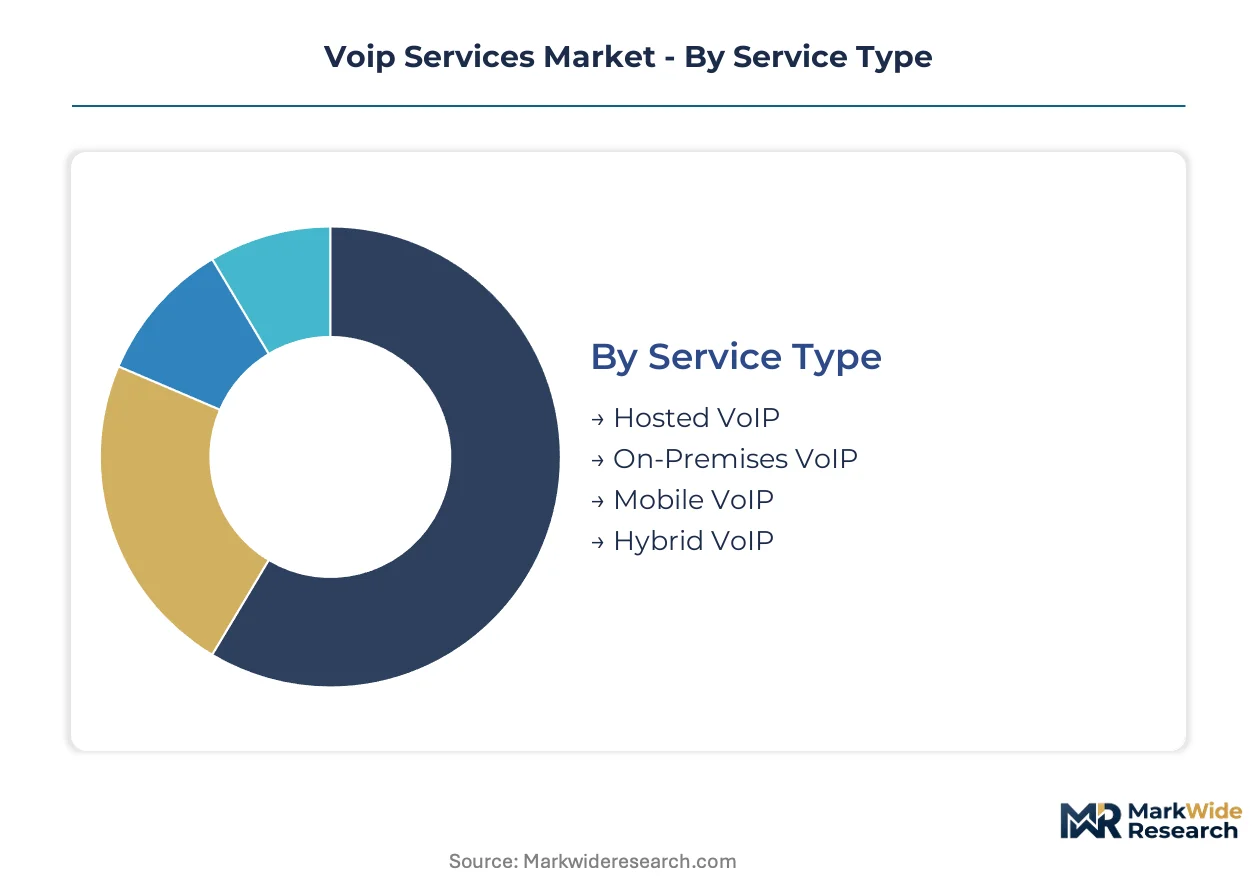
VoIP market segmentation reveals how infrastructure ownership preferences split between outsourced cloud delivery and retained control over voice systems. Deployment choices directly determine compliance burden, capital intensity, and integration depth with adjacent collaboration platforms.
Service Type:
Standalone voice systems dominate legacy replacement cycles, while embedded communications within productivity suites reshape new procurement patterns.
- Hosted VoIP:Cloud operators manage session border controllers, media gateways, and codec transcoding infrastructure at their facilities. Enterprise contact centers in the United States favor this model to eliminate datacenter footprint while meeting FCC STIR/SHAKEN certificate requirements through carrier-managed attestation.
- On-Premises VoIP:Organizations retain physical control over IP-PBX hardware, session initiation protocol trunking, and local survivability during WAN outages. Financial services and defense contractors in regulated sectors sustain this segment despite higher total cost of ownership to preserve call metadata sovereignty.
- Mobile VoIP:Applications leverage cellular data or Wi-Fi transport using Opus codec compression for field-service dispatch and logistics fleet coordination.
- Hybrid VoIP:Architectures split control plane functions between cloud-hosted management and on-premises media processing to balance operational flexibility with latency-sensitive use cases.
Volume placements concentrate in Hosted VoIP; the faster expansion belongs to Mobile VoIP.
Deployment Model:
Cost tiering separates hyperscale consumption from dedicated infrastructure with premium security isolation.
- Public Cloud:Shared multi-tenant infrastructure delivers per-seat pricing with automatic software updates and geographic redundancy. Mid-market enterprises across price-sensitive segments default to this model for predictable operational expenditure without capital commitment.
- Private Cloud:Single-tenant virtualized environments provide dedicated compute and storage resources with customizable security policies. Healthcare providers and government agencies mandate this tier to satisfy HIPAA and FedRAMP control requirements for voice data residency.
- Hybrid Cloud:Burst capacity from public infrastructure supplements private cloud base capacity during seasonal contact center volume spikes.
- On-Premises:Bare-metal deployment within customer-controlled facilities persists where air-gapped networks or sub-50ms latency thresholds apply.
Customer concentration clusters in Public Cloud; Private Cloud captures the steepest expansion trajectory among compliance-driven buyers.
End User:
Customer type determines feature complexity tolerance and sales channel economics.
- SMEs:Organizations with under 500 employees prioritize rapid deployment and minimal IT overhead through standardized service bundles. Channel partners in the United Kingdom and Germany target this segment with consumption-based billing that replaces perpetual licensing.
- Large Enterprises:Global organizations require multi-region redundancy, custom integration with legacy CRM systems, and dedicated technical account management. These buyers negotiate enterprise agreements with API rate limits and committed use discounts spanning three-to-five year terms.
- Government:Public sector procurement mandates FedRAMP, StateRAMP, or equivalent certifications with domestic data processing requirements.
- Individuals:Consumers and freelancers activate free or low-cost tiers for personal communications and micro-business presence.
Revenue scale favors Large Enterprises; SME segment gains share fastest through freemium conversion funnels.
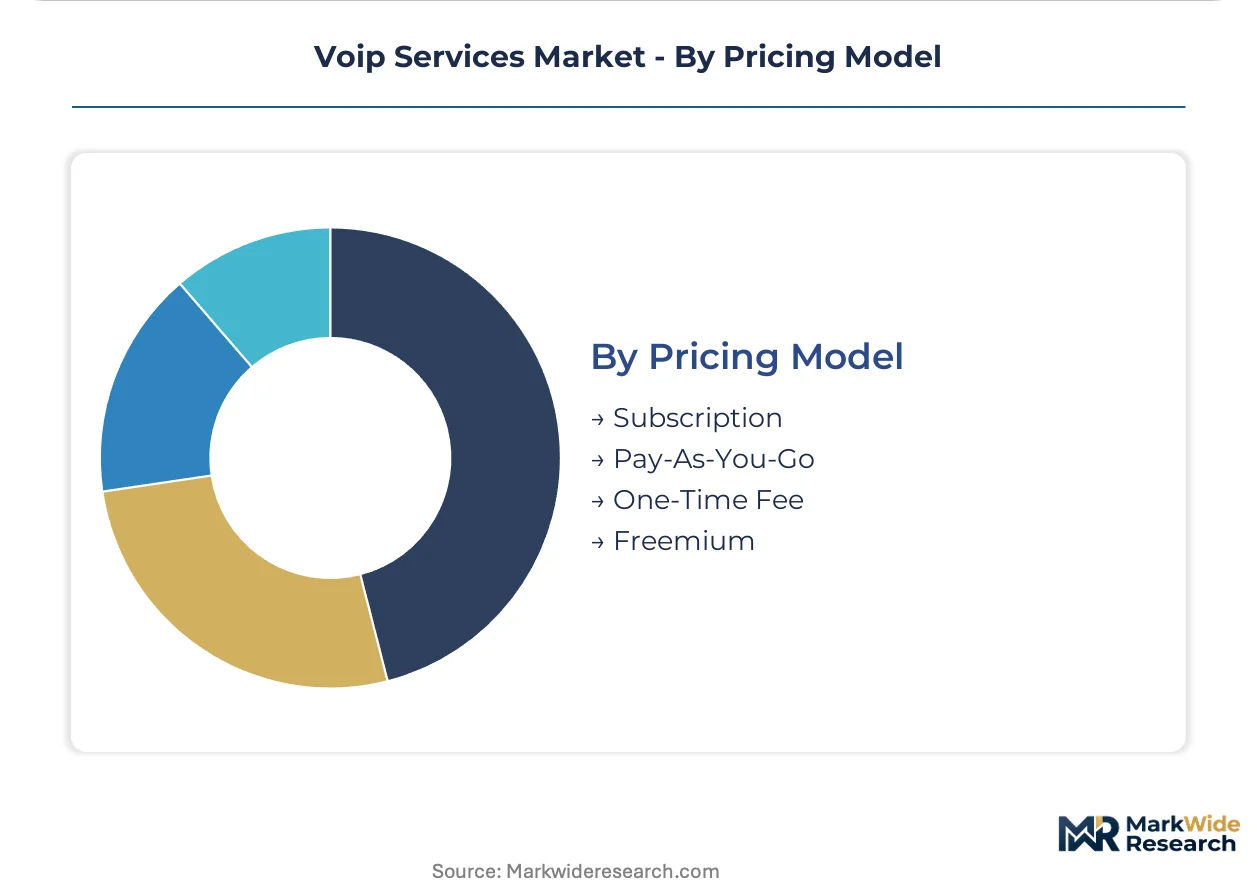
Pricing Model:
Margin structure varies dramatically between recurring subscription streams and transactional usage patterns.
- Subscription:Fixed monthly fees per user or line provide predictable cash flows and simplified budgeting for finance departments. This model dominates enterprise procurement with annual prepay discounts and automatic renewal clauses.
- Pay-As-You-Go:Metered billing against actual minutes, messages, or API calls aligns costs with seasonal demand fluctuations. Seasonal retail operations and campaign-driven political organizations prefer this structure to avoid stranded capacity during low-activity periods.
- One-Time Fee:Perpetual licenses for on-premises software with separate maintenance agreements persist among organizations with capital budget cycles and depreciation requirements.
- Freemium:Zero-cost entry tiers with feature-gated upgrades acquire individual users and micro-businesses for subsequent premium conversion.
Revenue concentration sits with Subscription; Pay-As-You-Go climbs fastest among digitally native organizations with variable demand profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadband fiber deployments in South Korea and Japan anchor VoIP infrastructure density across the Asia-Pacific corridor. Carrier-grade signaling investments concentrate where government mandates accelerate legacy network retirement.
United States
Enterprise contact centers in Texas and Florida drive hosted VoIP replacement cycles as hybrid work policies sustain unified communications spending. The FCC's STIR/SHAKEN mandate compels carriers to implement digital certificate verification for caller ID authentication. Dallas-Fort Worth clusters host major cloud infrastructure facilities processing voice workloads for Fortune 500 headquarters.
Germany
Logistics and field-service workforces in Bavaria and North Rhine-Westphalia demand mobile VoIP with seamless cellular-Wi-Fi handoff for fleet dispatch applications. The EU AI Act constrains automated call analytics and biometric voice analysis, forcing architecture segmentation for high-risk use cases. Munich anchors enterprise voice integration projects within manufacturing supply chain operations.
United Kingdom
Mid-market buyers in London and the Southeast fragment traditional seat-based licensing into metered usage models aligned with actual call volumes. GDPR retention requirements shape voice data storage practices for financial services contact centers. Channel partners in the Thames Valley replace perpetual licenses with consumption-based billing structures.
Japan
Financial institutions in Tokyo and Osaka deploy AI-powered noise suppression and real-time transcription at scale, eliminating dedicated recording infrastructure. METI guidelines influence enterprise migration timelines from legacy PBX systems to cloud-hosted alternatives. The Kanto region concentrates vendor technical support centers for regional language deployment.
India
IT services exporters in Bengaluru and Hyderabad embed VoIP APIs within CRM platforms for contextual call intelligence in offshore delivery operations. TRAI regulations govern interconnection charges and quality-of-service standards for IP-based voice services. The Delhi-NCR corridor hosts hyperscale data centers provisioning voice infrastructure for SME segments.
Voip Services Market Competitive Environment
Global majors compete with regional champions across deployment model specialization, with platform consolidators absorbing point-solution vendors at the mid-market tier. Market structure tilts toward hyperscale cloud operators that bundle voice with productivity suites, while specialized carriers retain security-sensitive accounts. Three archetypes dominate: integrated collaboration platforms, carrier-grade infrastructure providers, and API-first communication embedders. Consolidation accelerates through strategic partnerships between hardware manufacturers and software platforms, alongside geographic expansion into compliance-heavy European jurisdictions.
Within the integrated platform tier, Microsoft Corporation and Cisco Systems, Inc. exemplify divergent approaches to enterprise voice retention—one anchoring workloads within existing productivity ecosystems, the other sustaining on-premises loyalty through hardware-software binding. Zoom Video Communications, Inc. occupies a position in the mid-market simplification segment where reduced IT overhead drives procurement decisions. These three entities represent the competitive tension between cloud-native delivery and hybrid architectures that persists across North American and European deployments.
| Leading Market Players |
|---|
| RingCentral, Inc. |
| Cisco Systems, Inc. |
| Microsoft Corporation |
| Vonage Holdings Corp. |
| Nextiva |
| 8x8, Inc. |
| Dialpad, Inc. |
| Zoom Video Communications, Inc. |
| GoTo |
| Others |
Value Chain & Pricing Dynamics
Session border controller engineering talent clusters in Bangalore and Hyderabad create labor-cost differentials that widen spreads between premium managed-service tiers and economy self-service offerings. Indian development centers feed cloud-native VoIP platforms with compressed engineering costs, while North American technical account management commands premium pricing for enterprise-grade SLAs.
Pricing Analysis
Warranty and service-bundling arrangements separate premium managed offerings from unbundled infrastructure-only tiers. Subscription-based SaaS pricing dominates enterprise procurement, with differentiation driven by FCC STIR/SHAKEN compliance certification and geographic redundancy guarantees. Cost compression in mid-market segments intensifies as freemium conversion funnels absorb price-sensitive SME buyers, while financial services and government segments exhibit lowest price sensitivity due to FedRAMP and data sovereignty requirements.
Supply Chain Analysis
Codec licensing and session border controller silicon draw from concentrated pools of intellectual property holders in the United States, Taiwan, and Israel. Specialized DSP components, TLS certificate infrastructure, and carrier-grade signaling hardware constitute critical input dependencies. Single-source vulnerability around STIR/SHAKEN certificate authorities creates systemic compliance risk. Distribution runs through hyperscale cloud operators and specialized carrier resellers with regional interconnection agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VoIP services market is consolidating into a vertical-integration race where control over session border controller hardware and certificate authority relationships determines margin capture. Players are pursuing downstream control over enterprise customer relationships to reduce channel dependency.
For Market Incumbents: Lock in enterprise relationships through FedRAMP and StateRAMP certification investments that create switching costs for government and healthcare buyers. Deepen API integration with Salesforce and HubSpot workflows to embed voice services within existing operational toolchains, defending against modular competitors. For New Entrants and Emerging Players: The price-point gap between Cisco's premium hardware-integrated tiers and Zoom's mid-market simplification creates white-space for API-first communication embedders targeting logistics and field-service applications in Germany and France. Target mobile VoIP segments with Opus-optimized fleet dispatch solutions and consumption-based billing that avoids perpetual license friction. For Investors and Strategic Acquirers: Re-rating potential sits with private cloud specialists given EU AI Act compliance requirements that fragment product roadmaps and favor single-tenant architectures. Long-term viability favors carriers with in-house certificate authority relationships and domestic data center footprints. Watch STIR/SHAKEN enforcement intensity as an inflection indicator for reseller consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| STIR/SHAKEN Infrastructure Buildout | FCC-mandated certificate verification systems compel carrier ecosystem replacement cycles. |
| API-First Voice Embedding | WebRTC convergence with CRM platforms enables contextual call intelligence inside enterprise workflows. |
| Private Cloud Certification Investment | FedRAMP and HIPAA compliance unlocks healthcare and government procurement channels. |
| Mobile VoIP Fleet Solutions | Opus codec optimization for cellular-Wi-Fi handoff captures logistics and field-service demand. |
| Consumption-Based Billing Transition | Metered usage models align costs with seasonal demand for price-sensitive mid-market buyers. |
Study Parameters
SEC 10-K filings, FCC enforcement action records, and hyperscaler capex disclosures formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with CTOs at enterprise contact centers, IT procurement officers, carrier network engineers, and channel partners validated deployment model preferences and pricing elasticity. Bottom-up triangulation across service type, deployment model, and end-user segmentation converged with top-down macroeconomic anchoring.
Bottom-up modeling aggregated individual segment trajectories while top-down validation checked aggregate consistency against broadband infrastructure investment patterns and regulatory mandate timelines. Segmentation dimensions included service type, deployment model, organization size, vertical industry, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and net new adoption curves across the projection horizon, with Opus codec penetration and STIR/SHAKEN compliance deadlines serving as industry-specific forecast inputs.
Inputs from carrier regulatory filings and enterprise software procurement databases were available through the study window; gaps in real-time pricing transparency for private cloud deployments introduce uncertainty bands around mid-market segment splits. Forecasts reflect documented assumptions about hybrid work persistence and FCC enforcement intensity. Regulatory divergence between United States and European Union jurisdictions, alongside voice security talent scarcity, warrants ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Consumer Communication Services Market
Communication Services
Global Critical Communication Market
Communication Services
India Communication Platform As a Service (Cpaas) Market
Communication Services
Postal Services Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Message Handling Systems Market
Communication Services
Outbound Telemarketing Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
North America Postal Services Market
Communication Services
Meeting Solutions Market
Communication Services
Industrial Communication Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Push-To-Talk Market
Communication Services
Web Conferencing Market
Communication Services
Fixed Business Voice Platforms and Services Market