
 Broadcasting Solutions Market | 2026-2036
Broadcasting Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Broadcasting Solutions Market Intelligence
Broadcast engineering talent scarcity is bifurcating the market into vendors that build integrated platforms versus those that sell modular components. Cisco Systems Inc. leverages its networking heritage to dominate IP-based broadcast infrastructure. Ericsson anchors large-scale terrestrial and satellite deployments across Nordic and Asian telecom partnerships. Grass Valley specializes in camera and production switcher ecosystems that sustain loyalty among tier-one sports networks.
Broadcasting solutions encompass hardware, software, and services that acquire, process, distribute, and deliver audio-video content across terrestrial, satellite, cable, and IP networks, typically operating within 3G-SDI to 12G-SDI signal ranges or uncompressed IP streams exceeding 25 Gbps for 4K workflows. The primary purpose is ensuring reliable, low-latency content delivery to mass audiences with guaranteed quality-of-service metrics. Playout automation and streaming platforms capture disproportionate R&D investment as broadcasters abandon tape-based and manual scheduling for software-defined channels. Encoding and decoding solutions face margin compression from commoditized H.264/H.265 silicon, while media asset management retains pricing power through AI-driven metadata extraction and rights-management integration.
The FCC governs spectrum allocation and station licensing in the United States, directly shaping replacement demand as repacking forces transmitter upgrades. ETSI and the EU Electronic Communications Code harmonize technical standards across member states, easing cross-border content distribution but mandating accessibility and emergency-alert compliance. Japan's Ministry of Internal Affairs and Communications drives 8K terrestrial test broadcasts through ISDB-S3 specifications. Stakeholders must monitor whether ATSC 3.0 deployment momentum in the United States and comparable next-generation standards elsewhere translate into sustained capital expenditure or deferred replacement cycles.
Market Dynamics
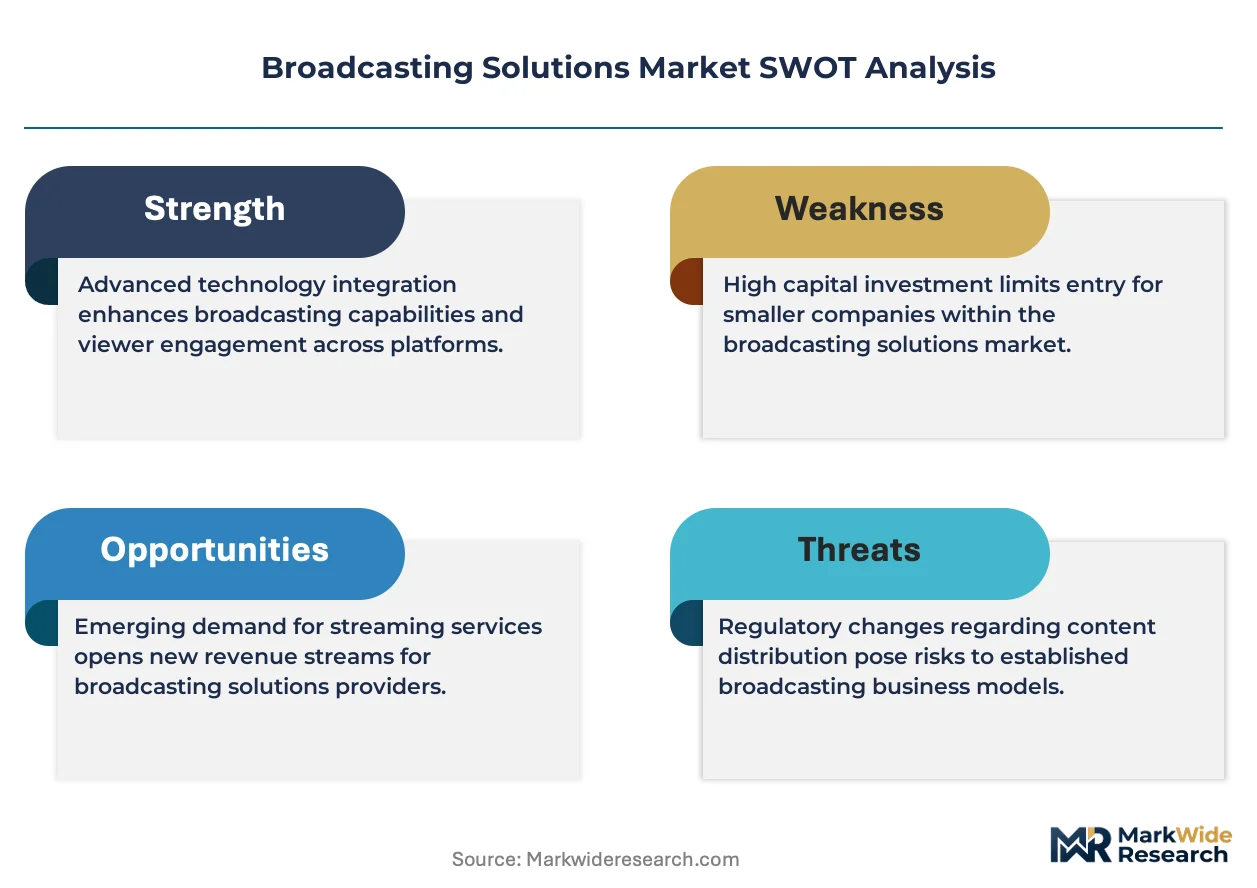
IP-based broadcast workflows are restructuring capital allocation across terrestrial, satellite, and cable operators, forcing simultaneous investment in software-defined infrastructure and spectrum reallocation compliance.
Growth Catalysts
- ATSC 3.0 deployment mandates:The FCC's spectrum repacking timeline compels US broadcasters to replace transmitters with NextGen TV-compatible hardware, creating replacement demand independent of organic growth cycles.
- Live sports streaming investment:Dedicated streaming platforms and sports networks are commissioning redundant transmission paths and remote production kits to guarantee failover during high-value events.
- AI-driven metadata extraction:Media asset management vendors embed machine learning for automated content tagging, accelerating archive monetization and rights-tracking efficiency.
Market Restraints
- Specialized engineering talent scarcity:The convergence of broadcast engineering and IT networking skills has created a labor gap that extends deployment timelines and inflates implementation costs.
- Commoditized encoding silicon:H.264 and H.265 chipsets from Asian semiconductor foundries have collapsed hardware margins in compression equipment, pressuring pure-play encoder vendors.
- Legacy SDI infrastructure lock-in:Major sports networks and national broadcasters face sunk-cost constraints that delay IP migration despite superior total cost of ownership.
Strategic Opportunities
- Remote production adoption in tier-two sports:Regional leagues and collegiate athletics in the United States are adopting at-home production models to reduce travel costs and crew footprints.
- Cloud-native playout for FAST channels:Free ad-supported streaming television platforms require software-defined channel origination that scales without hardware provisioning.
- 8K terrestrial test infrastructure in Japan:ISDB-S3 specification trials create early-mover equipment demand for cameras, switchers, and transmission systems ahead of wider deployment.
Industry Challenges
- Hybrid SDI-IP workflow complexity:Broadcast engineers must maintain signal integrity across asynchronous timing domains while training operations staff on unfamiliar network protocols.
- Interoperability certification delays:Vendors face extended testing cycles against SMPTE ST 2110 and NMOS specifications before achieving customer acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broadcasting Solutions Market |
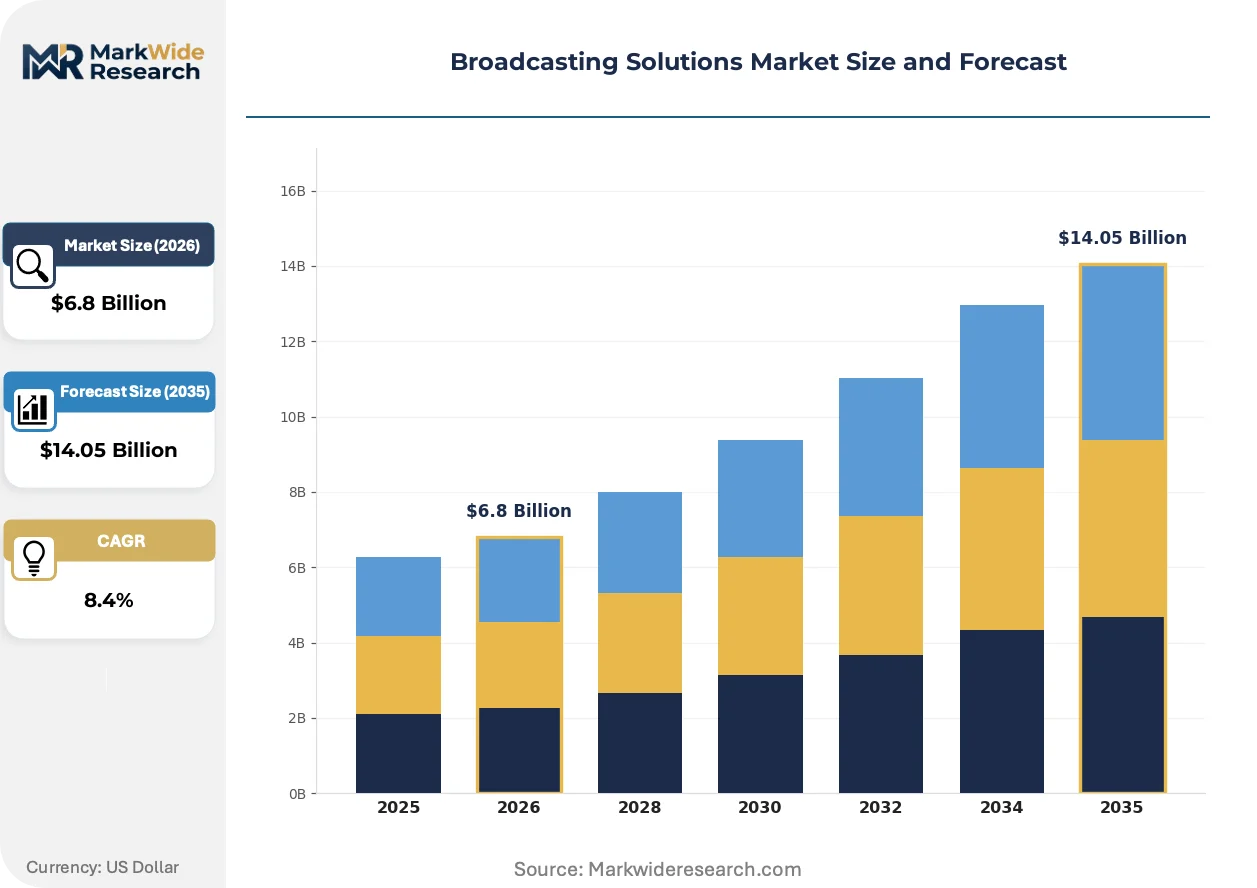
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Content Management System, Playout Automation, Signal Processing, Encoding & Decoding, Media Asset Management, Streaming Platform Technology: Satellite Broadcasting, IPTV, Digital Video Broadcasting, Over-the-Top, Terrestrial, Cable Use Case: Live Event Transmission, News Distribution, Sports Broadcasting, Educational Content Delivery, Entertainment Broadcasting, Corporate Communications End User: Broadcast Stations, Media Agencies, Telecommunication Providers, Government Agencies, Sports Networks, Production Houses |
| Companies Covered | Cisco Systems Inc., Ericsson, CommScope, Rohde & Schwarz, Harmonic Inc., EVS Broadcast Equipment, Grass Valley, Evertz Microsystems, Imagine Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broadcasting Solutions Market Strategic Shifts & Innovations
Software-defined architectures are collapsing traditional hardware procurement cycles while regulatory mandates force synchronized infrastructure replacement across multiple geographies.
Uncompressed IP transport using SMPTE ST 2110 is supplanting baseband SDI routing in major broadcast facilities. Tier-one sports networks and national public broadcasters in Germany and Japan are completing facility-wide conversions. This transition is compressing capital expenditure timelines from seven-year refresh cycles to three-year phased migrations as operational technology and information technology budgets merge.
ETSI harmonization under the EU Electronic Communications Code is standardizing technical requirements for cross-border content distribution. Broadcasters operating across Germany, France, and Nordic markets benefit from unified accessibility and emergency-alert compliance frameworks. Equipment vendors are consolidating product SKUs to serve this harmonized regulatory environment rather than maintaining country-specific variants.
Subscription-based service models for playout automation and media asset management are displacing perpetual license purchases. Regional broadcasters and emerging FAST channel operators in the United States favor operational expenditure structures that scale with channel count. This preference shift favors vendors with mature SaaS platforms over traditional hardware-centric suppliers.
Broadcasting Solutions Market Segmentation
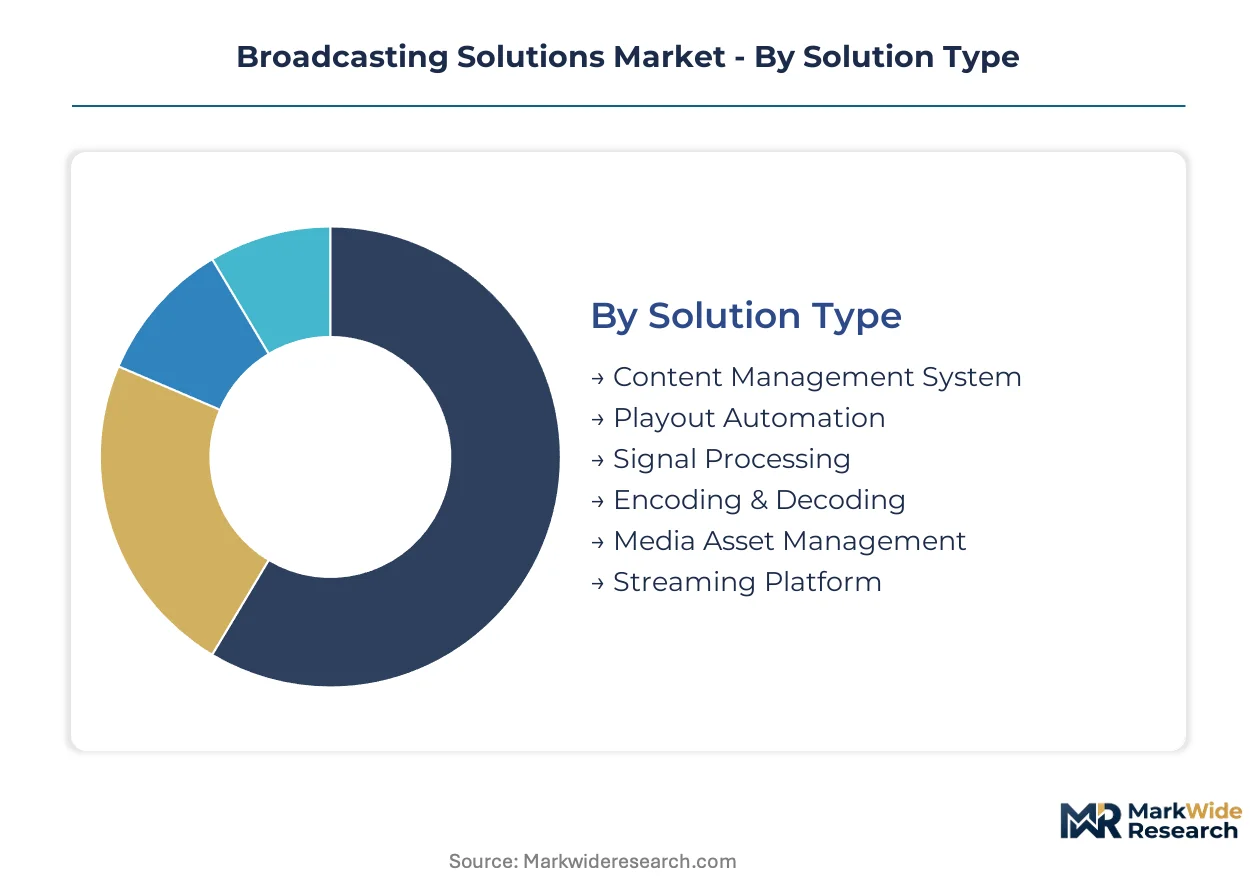
Broadcasting solutions fragment across four distinct axes that reshape procurement priorities. Solution type determines whether vendors capture recurring software revenue or one-time hardware sales. Technology and use-case splits reveal where infrastructure investment concentrates amid the IP transition.
Solution Type:
Margin pools concentrate in software layers that command recurring revenue, while hardware components face commoditization pressure from semiconductor foundries.
- Playout Automation:Software-defined channel origination systems replace tape-based scheduling with frame-accurate automated sequencing. Tier-two sports networks and FAST channel operators in the United States favor subscription models that scale with channel count rather than capital-intensive hardware procurement.
- Media Asset Management:AI-driven metadata extraction platforms automate content tagging and rights-tracking across petabyte-scale archives. National public broadcasters in Germany and Japan pay premium pricing for machine learning integration that accelerates archive monetization.
- Content Management System:Web-based editorial workflows unify scriptwriting, rundown management, and social media publishing.
- Signal Processing:Baseband-to-IP conversion equipment bridges SDI and SMPTE ST 2110 timing domains.
- Encoding & Decoding:H.264 and H.265 silicon from Asian foundries has collapsed hardware margins in compression equipment.
- Streaming Platform:Origin servers and content delivery orchestration for direct-to-consumer services.
The dominant share belongs to Playout Automation, while Media Asset Management is closing the gap fastest.
Technology:
Capital deployment splits between legacy infrastructure maintenance and next-generation IP network buildouts.
- Over-the-Top:Internet-delivered video bypasses traditional distribution gatekeepers using adaptive bitrate streaming protocols. Dedicated sports streaming platforms in the United States commission redundant transmission paths and remote production kits to guarantee failover during high-value live events.
- IPTV:Managed IP networks deliver broadcast-quality video with guaranteed quality-of-service metrics. Telecommunication providers in Germany bundle IPTV with broadband subscriptions, driving set-top box and middleware investment.
- Satellite Broadcasting:Geostationary and low-earth-orbit constellations serve remote regions and maritime applications.
- Digital Video Broadcasting:DVB-T2 and DVB-S2 standards dominate European terrestrial and satellite distribution.
- Terrestrial:ATSC 3.0 deployment in the United States and ISDB-S3 trials in Japan compel transmitter upgrades.
- Cable:DOCSIS 3.1 and 4.0 upgrades sustain hybrid fiber-coaxial networks.
Over-the-Top commands the largest investment flow, with IPTV expanding most quickly in bundled telecom offerings.
Use Case:
Revenue concentration tracks live content value, with sports commanding premium infrastructure redundancy.
- Sports Broadcasting:Multi-camera live production with instant replay, graphics insertion, and redundant transmission paths. Professional leagues and collegiate athletics in the United States adopt at-home production models to reduce travel costs and crew footprints while maintaining broadcast quality.
- Live Event Transmission:Single-occasion coverage of concerts, ceremonies, and breaking news requiring rapid deployment kits. Production houses in Japan deploy 8K-capable camera chains and switchers for ISDB-S3 specification trials ahead of wider terrestrial deployment.
- News Distribution:Continuous operation with breaking-news interrupt capabilities.
- Educational Content Delivery:Scheduled instructional programming with accessibility compliance requirements.
- Entertainment Broadcasting:Scripted and unscripted content with post-production workflows.
- Corporate Communications:Internal video distribution and executive broadcast capabilities.
Sports Broadcasting holds the dominant share, while Live Event Transmission gains share fastest through remote production adoption.
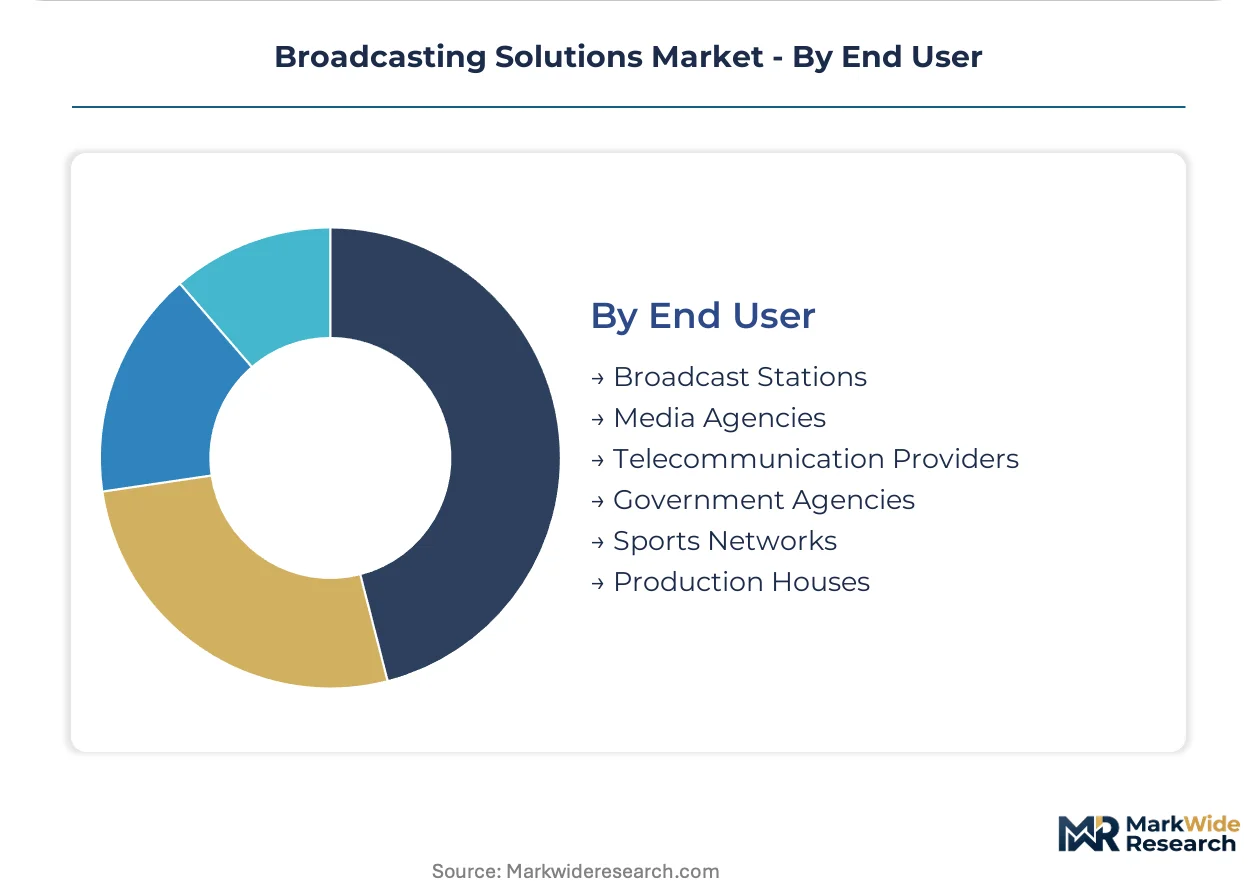
End User:
Procurement authority separates capital-intensive facility owners from service-based operators.
- Broadcast Stations:Licensed terrestrial transmitters with FCC-mandated spectrum repacking obligations. Network-affiliated stations in the United States must replace transmitters with NextGen TV-compatible hardware on accelerated timelines independent of organic growth cycles.
- Sports Networks:Dedicated channels with specialized production requirements and redundant infrastructure. ESPN and regional sports networks maintain loyalty to camera and production switcher ecosystems that sustain vendor relationships across refresh cycles.
- Media Agencies:Content aggregation and distribution intermediaries.
- Telecommunication Providers:IPTV and streaming infrastructure operators.
- Government Agencies:Public safety and emergency alert distribution systems.
- Production Houses:Freelance and contract production services.
Broadcast Stations dominate procurement volume, though Sports Networks show the steepest expansion trajectory through dedicated streaming investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC governs spectrum allocation and station licensing in the United States, directly shaping replacement demand as repacking forces transmitter upgrades across the dominant geography. ETSI and the EU Electronic Communications Code harmonize technical standards across member states. Japan's Ministry of Internal Affairs and Communications drives 8K terrestrial test broadcasts through ISDB-S3 specifications.
United States
Network-affiliated stations must replace transmitters with NextGen TV-compatible hardware on accelerated timelines independent of organic growth cycles. The FCC's spectrum repacking timeline compels broadcaster infrastructure investment. Major sports networks in Los Angeles and New York maintain loyalty to camera and production switcher ecosystems that sustain vendor relationships.
Germany
Telecommunication providers bundle IPTV with broadband subscriptions, driving set-top box and middleware investment. ETSI harmonization under the EU Electronic Communications Code standardizes technical requirements for cross-border content distribution. National public broadcasters in Berlin and Munich pay premium pricing for machine learning integration that accelerates archive monetization.
Japan
Production houses deploy 8K-capable camera chains and switchers for ISDB-S3 specification trials ahead of wider terrestrial deployment. The Ministry of Internal Affairs and Communications drives 8K terrestrial test broadcasts through ISDB-S3 specifications. Broadcasting equipment clusters in Tokyo and Osaka concentrate facility-wide conversions to uncompressed IP transport using SMPTE ST 2110.
United Kingdom
Regional broadcasters favor operational expenditure structures that scale with channel count for playout automation and media asset management. Ofcom regulates spectrum allocation and broadcasting standards across terrestrial and satellite platforms. Production facilities in London and Manchester complete phased migrations from baseband SDI routing to software-defined infrastructure.
South Korea
Telecommunication providers invest in IPTV and streaming infrastructure as part of bundled service offerings. The Korea Communications Commission oversees broadcasting standards and network infrastructure requirements. Technology clusters in Seoul and Busan concentrate R&D investment in encoding and decoding solutions alongside media asset management platforms.
Broadcasting Solutions Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the broadcasting solutions market. Tier-one sports networks and national broadcasters sustain long-term vendor relationships across refresh cycles. The competitive landscape fragments across networking heritage players, broadcast-native equipment specialists, and telecom-anchored infrastructure providers. Dominant competitive moves include strategic partnerships for IP workflow integration and portfolio diversification into software-defined service models.
Within the networking-heritage tier, Cisco Systems Inc. occupies a position exemplifying convergence between broadcast engineering and IT infrastructure. Ericsson anchors large-scale terrestrial and satellite deployments through Nordic and Asian telecom partnerships. Grass Valley sits within the broadcast-native specialist tier, representing sustained loyalty among tier-one sports networks for camera and production switcher ecosystems.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Ericsson |
| CommScope |
| Rohde & Schwarz |
| Harmonic Inc. |
| EVS Broadcast Equipment |
| Grass Valley |
| Evertz Microsystems |
| Imagine Communications |
| Others |
Cost & Logistics Intelligence
Semiconductor foundry scale economies in Taiwan and South Korea compress encoding hardware price floors while concentrating supply leverage among three dominant chip fabricators. This concentration simultaneously enables subscription-based software pricing power for IP workflow vendors and squeezes margins for commoditized compression equipment manufacturers.
Pricing Analysis
Long-term service contracts dominate procurement for playout automation and media asset management, with tier-two broadcasters favoring SaaS structures that scale with channel count over perpetual licenses. Price differentiation rests on AI integration depth and SMPTE ST 2110 certification tier, with premium tiers commanding substantial uplifts for uncompressed IP capability. Pricing pressure intensifies in encoding hardware as Asian foundry output saturates H.264/H.265 silicon markets. Sports networks exhibit lowest price sensitivity due to failover redundancy requirements, while regional broadcast stations face acute budget constraints from FCC-mandated transmitter replacements.
Supply Chain Analysis
Strategic stockpiling of FPGA and broadcast-grade memory components characterizes vendor inventory strategy, buffering against foundry allocation volatility and extended lead times for specialized silicon. Supply concentration centers on Taiwan, South Korea, and Japan for advanced semiconductors, with China dominating passive component and PCB fabrication. The chain draws from germanium substrates, gallium arsenide wafers, and precision timing oscillators as critical inputs. Single-source vulnerability in 12G-SDI and 25G Ethernet PHY chipsets poses structural risk. Distribution runs through authorized broadcast equipment resellers and direct OEM relationships with national broadcasters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across SDI-IP transition stages creates specialized vendor niches as broadcasters phase infrastructure replacement over disparate timelines. The shift from capital-intensive hardware to recurring software revenue models rewards platform consolidation plays.
For Market Incumbents: Shield installed-base relationships by embedding professional services around SMPTE ST 2110 migration complexity, countering modular component vendors that undercut on hardware margin. Deepen backward integration into FPGA firmware development to escape commoditized encoding silicon dependency. Prioritize certification investment for NMOS interoperability to extend testing-cycle advantages against emerging competitors. For New Entrants and Emerging Players: Differentiate on cloud-native playout architectures purpose-built for FAST channel operators seeking operational expenditure flexibility without hardware provisioning overhead. Target collegiate athletics and regional sports leagues in the United States for at-home production kits, a white-space segment underserved by tier-one camera ecosystem vendors. Pursue partnership-led go-to-market strategies with telecom providers bundling IPTV infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among media asset management vendors with AI-driven metadata extraction capabilities, where archive monetization efficiency sustains pricing power. Long-term viability over the projection horizon favors software-defined platform plays over hardware-centric legacy suppliers. Monitor ATSC 3.0 deployment momentum as inflection indicator for sustained capital expenditure versus deferred replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified SMPTE ST 2110 and SDI workflow management reduces operational complexity for hybrid facilities. |
| Strategic Partnership | Telecom bundling agreements in Germany and South Korea accelerate IPTV middleware penetration. |
| Acquisition of Specialist Firm | Machine learning talent acquisition strengthens AI metadata extraction capabilities for archive monetization. |
| Geographic Expansion | Early presence in Japan's ISDB-S3 trial infrastructure secures 8K equipment relationships ahead of wider deployment. |
| Product Launch | Subscription-based channel origination targets FAST operator demand for scalable operational expenditure models. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FCC filings, ETSI standards documentation, and broadcaster capital expenditure disclosures. Interviews with broadcast engineering directors, IP network architects, sports network procurement leads, and media asset management vendors informed demand-side validation. Secondary sources include SMPTE technical specifications, Ministry of Internal Affairs and Communications 8K trial reports, and equipment vendor SEC filings. Bottom-up channel checks and top-down market sizing triangulate volume and value estimates.
Segmentation dimensions modeled encompass solution type, technology protocol, use-case vertical, and end-user procurement authority across the projection horizon. CAGRs derive from installed-base replacement cycles, regulatory mandate timelines, and streaming platform investment trajectories. Forecast inputs incorporate FCC spectrum repacking schedules, ISDB-S3 specification readiness, and FAST channel proliferation rates.
The analysis sits within stated boundaries; outcomes outside ATSC 3.0 deployment adherence, IP talent availability, and semiconductor supply stability would require recalibration. Forecasts reflect documented assumptions regarding broadcaster budget allocation between regulatory compliance and organic modernization. Revision becomes warranted when hybrid SDI-IP transition timelines extend beyond operational technology and information technology budget convergence thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Walkie Talkie Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Global Critical Communication Market
Communication Services
Managed Communication Services Market
Communication Services
North America Postal Services Market
Communication Services
Video Conferencing Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Latin America Postal Service Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Push-To-Talk Market
Communication Services
Global Passenger Information System Market
Communication Services
Message Handling Systems Market
Communication Services
Green Communication Market
Communication Services
Speech to Speech Translation Market
Communication Services
Voip Services Market
Communication Services
Video Managed Services Market