
 Brazil Optical Transceiver Market | 2026-2036
Brazil Optical Transceiver Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Optical Transceiver Market Insights
Silicon photonics is decoupling Brazil's optical transceiver economics from traditional indium phosphide substrates. Cisco Systems leverages its domestic channel partnerships to anchor enterprise router-to-transceiver bundling. Huawei Technologies competes aggressively on price-performance for 100G and 400G modules sold to Brazilian carriers.
An optical transceiver converts electrical signals to optical signals and vice versa, typically operating at wavelengths between 850 nanometers and 1625 nanometers with power consumption thresholds below 15 watts per module. QSFP form factors dominate data center interconnects where density and thermal efficiency determine rack economics, while telecommunications deployments favor CFP modules for coherent long-haul transmission. Cloud providers represent the fastest-growing end user category as hyperscalers build presence in Campinas and Barueri.
ANATEL mandates type approval and electromagnetic compatibility certification for all optical equipment deployed in Brazilian networks, creating a compliance gateway that filters import channels. The country's national broadband plan and PLI-style incentives for local electronics manufacturing are reshaping procurement patterns toward domestically assembled modules. Stakeholders must monitor whether ANATEL tightens local content requirements before committing to import-dependent supply structures.
Market Dynamics
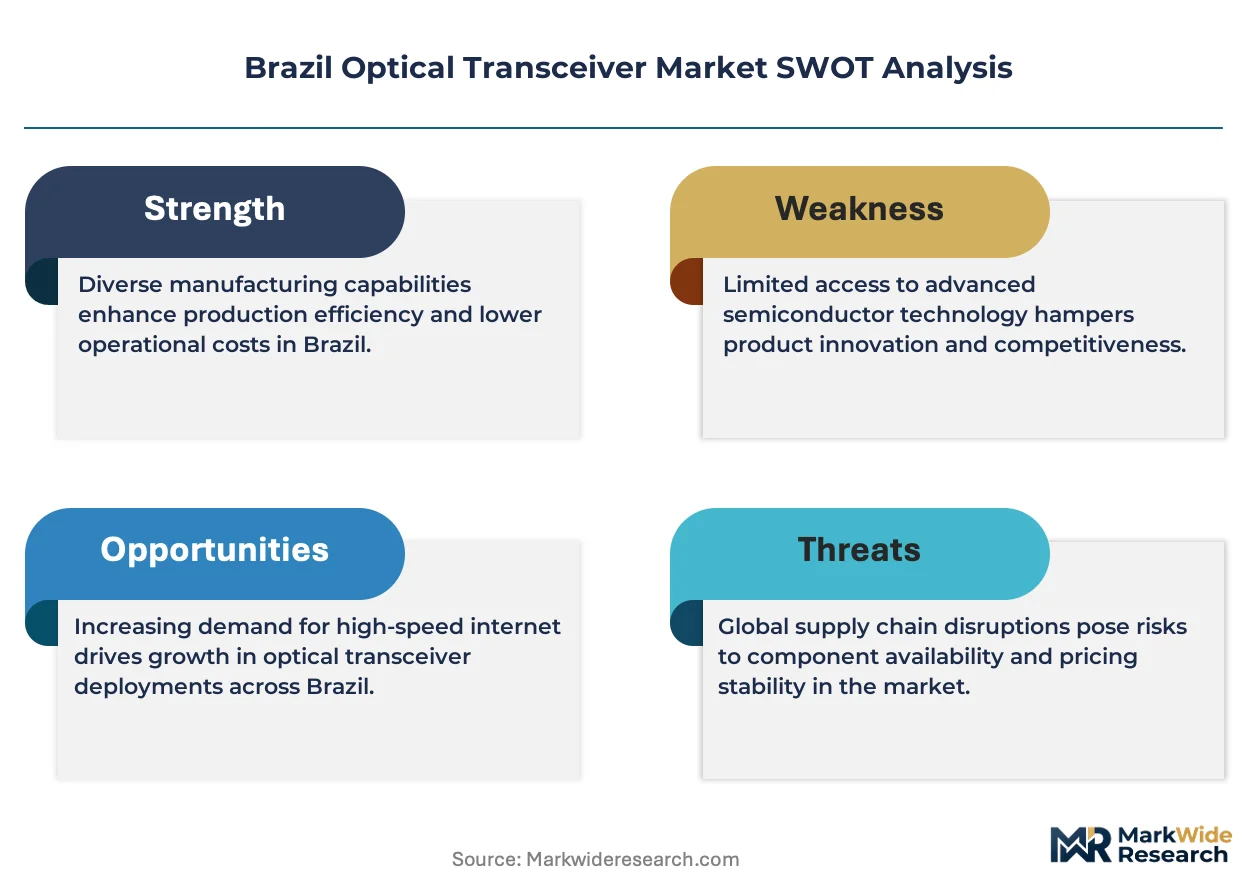
Silicon photonics is compressing module costs while ANATEL's local content mandates force supply chain reconfiguration, creating tension between import dependency and domestic assembly economics across Brazilian optical networks.
Growth Catalysts
- ANATEL Broadband Targets:The national broadband plan mandates fiber-to-the-home expansion, accelerating last-mile deployments in underserved municipalities and driving module procurement volumes.
- Hyperscaler Data Center Buildouts:Cloud operators in Campinas and Barueri are constructing facilities requiring 400G and 800G interconnects, creating concentrated demand for high-density transceiver form factors.
- Submarine Cable Landings:New cable systems terminating in Fortaleza and Santos are upgrading backhaul capacity, necessitating coherent optical modules for terrestrial extensions into São Paulo's financial corridor.
Market Restraints
- Indium Phosphide Supply Concentration:High-performance laser chip fabrication concentrates in East Asian foundries, exposing Brazilian assemblers to geopolitical supply disruptions and extended lead times.
- ANATEL Certification Friction:Type approval and electromagnetic compatibility testing creates 4-6 month import gateways, delaying deployment schedules for time-sensitive network upgrades.
- Copper DAC Substitution:Short-reach data center interconnects below 7 meters increasingly adopt passive copper cables, displacing optical transceivers in low-latency trading and storage applications.
Strategic Opportunities
- Northern Corridor Expansion:Manaus and Belém represent underpenetrated fiber markets where ANATEL's universalization fund subsidizes infrastructure buildouts for first-mile optical equipment.
- Silicon Photonics-Coherent Convergence:Integration of DSP silicon with photonic integrated circuits enables 800G ZR modules for metro networks, collapsing the cost gap between data center and telecom optics.
- PLI-Style Assembly Incentives:Brazil's local electronics manufacturing incentives create margin advantages for domestically assembled QSFP modules versus fully imported alternatives.
Industry Challenges
- Optical Packaging Engineering Gap:Domestic workforce scarcity in fiber alignment and hermetic sealing processes limits yield rates for complex coherent modules assembled in Brazilian facilities.
- Legacy SONET/SDH Integration:Incumbent carriers maintain TDM infrastructure requiring protocol translation gateways, complicating transceiver interoperability testing and extending deployment timelines.
- QSFP Thermal Design Complexity:15-watt power envelopes in high-density switches demand advanced heat dissipation engineering that exceeds local thermal simulation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Optical Transceiver Market |
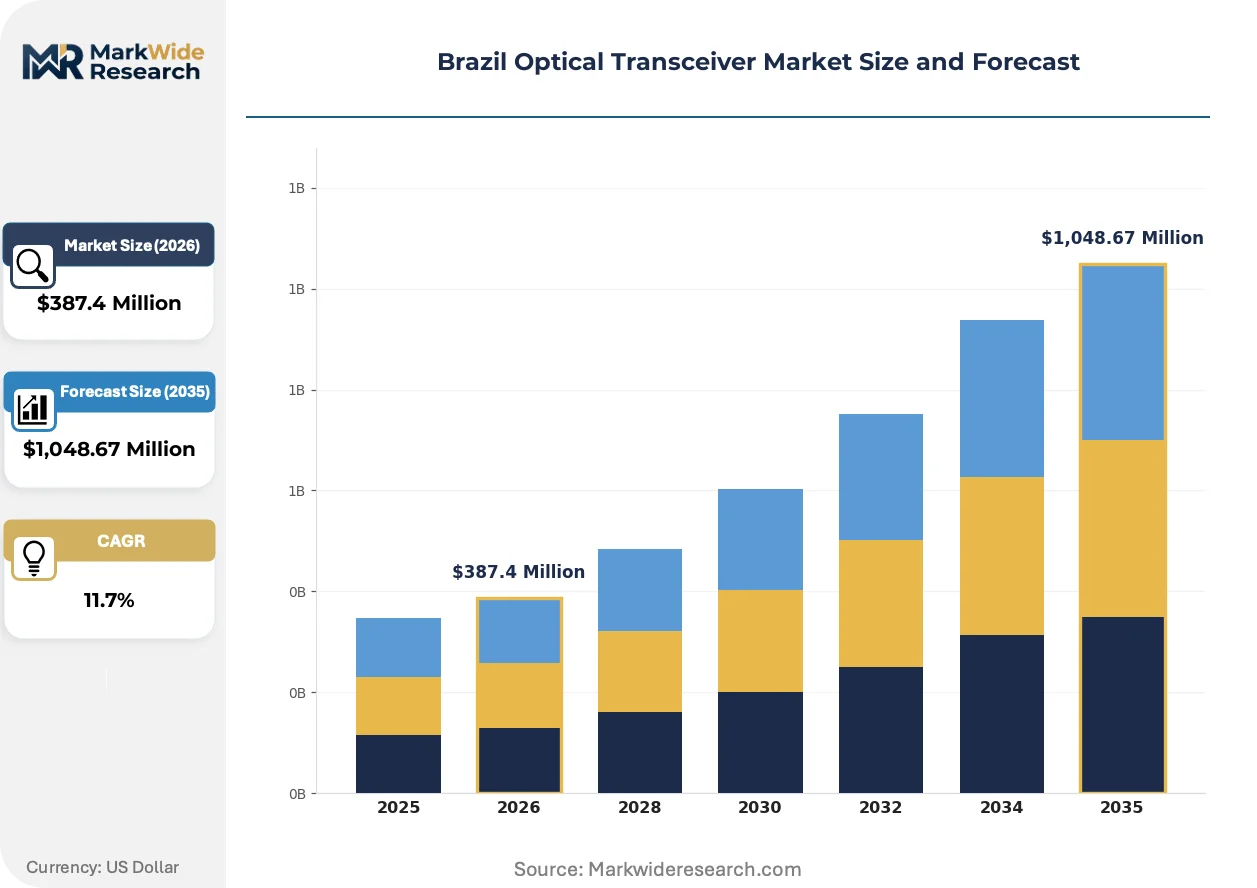
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $1,048.67 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 25G, 40G, 100G, 400G Technology: SFP, QSFP, CFP, ZR End User: Telecommunications, Data Centers, Enterprises, Cloud Providers Deployment: On-Premises, Cloud-Based, Hybrid, Others |
| Companies Covered | Cisco Systems, Huawei Technologies, Coherent Corp., Lumentum Holdings, Broadcom, Hewlett Packard Enterprise, Arista Networks, Accelink Technologies, Padtec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Optical Transceiver Market Trends and Innovations
Optical transceiver evolution in Brazil centers on form factor densification, regulatory localization mandates, and procurement model restructuring as network operators balance performance requirements against domestic content compliance.
Silicon photonics platforms integrate CMOS electronics with optical components on single substrates, enabling 800G transmission at power budgets below 12 watts. Data center operators in São Paulo's financial district are deploying these modules aggressively for spine-leaf architectures. This convergence is unifying previously separate supply chains for telecom and enterprise optics, collapsing vendor qualification overhead and compressing procurement cycles.
ANATEL's updated electromagnetic compatibility certification framework now mandates in-country testing for all optical equipment, eliminating reliance on foreign laboratory reports. This regulatory shift forces module suppliers to establish Brazilian testing partnerships or local assembly facilities. Telecommunications deployments face the steepest compliance burden, as coherent long-haul modules require extended environmental stress validation.
Hyperscalers are consolidating transceiver procurement through direct manufacturer relationships, bypassing traditional distribution channels. This channel disintermediation concentrates volume with qualified vendors capable of ANATEL compliance and local logistics. The shift is most pronounced in Campinas and Barueri, where cloud operators negotiate multi-year supply agreements with silicon photonics specialists.
Brazil Optical Transceiver Market Segmentation
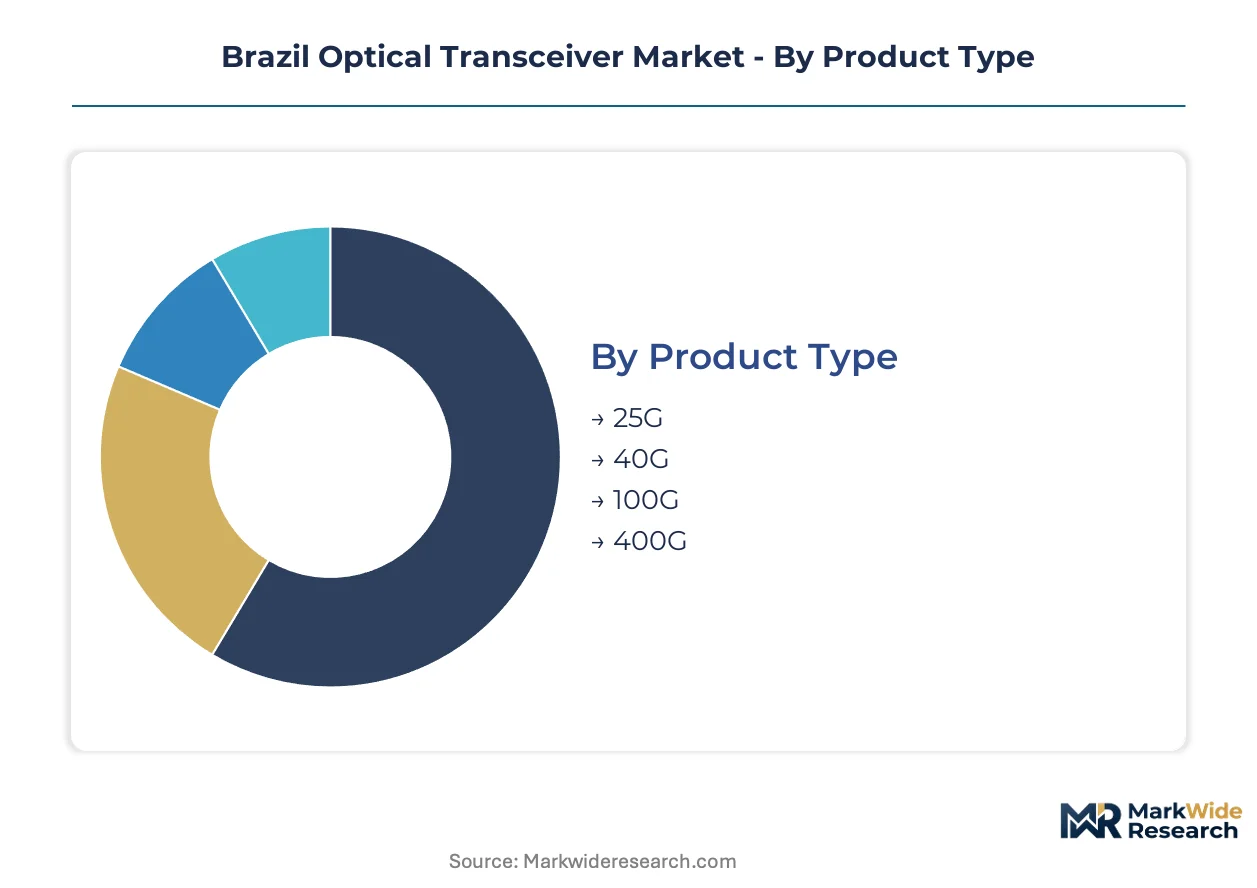
Brazil's optical transceiver segmentation reflects competing pressures between hyperscaler density requirements and ANATEL's localization mandates. Procurement patterns diverge sharply across form factors and end-user categories as supply chains reconfigure for domestic assembly economics.
Product Type:
Supply concentration in high-speed laser fabrication concentrates procurement leverage among carriers deploying coherent transmission.
- 25G:Legacy enterprise and mobile backhaul applications dominate this specification, particularly in São Paulo's financial district where protocol translation gateways bridge TDM infrastructure. Municipal fiber deployments in Belo Horizonte and Curitiba absorb residual volumes as ANATEL universalization funds subsidize first-mile connectivity.
- 40G:Transitional deployments in regional carrier networks face displacement pressure from 100G price compression. Rio de Janeiro's incumbent operators maintain limited procurement for metro ring upgrades where capital constraints delay full infrastructure refresh cycles.
- 100G:Campus interconnects and distributed data center fabrics in Barueri drive steady demand for this mid-tier specification. Cisco's domestic bundling strategies anchor enterprise router deployments requiring backward-compatible optical interfaces.
- 400G:Hyperscaler spine-leaf architectures in Campinas concentrate demand for this high-density form factor. Silicon photonics integration enables power budgets below 12 watts per module, collapsing thermal constraints that previously limited rack density.
Today's leader: 100G. Tomorrow's challenger: 400G.
Technology:
Form factor selection determines thermal engineering requirements and regulatory compliance pathways across Brazilian network deployments.
- SFP:Compact pluggable interfaces serve enterprise edge applications and legacy equipment retrofits. São Paulo's financial institutions deploy SFP modules for building-to-building connectivity within trading districts.
- QSFP:Quad-lane density dominates data center interconnects where rack space economics override per-port cost considerations. Cloud operators in Campinas negotiate direct manufacturer relationships bypassing traditional distribution channels for this form factor.
- CFP:Coherent long-haul modules face the steepest ANATEL certification burden due to extended environmental stress validation requirements. Submarine cable landing stations in Fortaleza and Santos deploy CFP modules for terrestrial backhaul extensions.
- ZR:Pluggable coherent optics enable 800G metro transmission without dedicated transponder hardware. Silicon photonics-coherent convergence collapses cost gaps between data center and telecom optics in this emerging category.
QSFP commands current procurement volumes. ZR gains share fastest among coherent alternatives.
End User:
Customer concentration shapes margin structures and channel strategies across the Brazilian optical value chain.
- Telecommunications:Incumbent carriers in Rio de Janeiro and São Paulo maintain SONET/SDH infrastructure requiring protocol translation gateways. ANATEL certification friction extends deployment timelines for coherent module upgrades.
- Data Centers:Colocation facilities in Barueri and Campinas absorb high-density QSFP volumes for spine-leaf architectures. Thermal design complexity at 15-watt power envelopes exceeds local simulation capabilities.
- Enterprises:São Paulo's financial district drives demand for low-latency interconnects where copper DAC substitution displaces optical solutions below 7 meters.
- Cloud Providers:Hyperscalers consolidate procurement through multi-year supply agreements with silicon photonics specialists. This segment climbs the fastest as AWS, Microsoft, and Google expand presence in southeastern Brazil.
Telecommunications anchors revenue. Cloud providers expand most quickly.
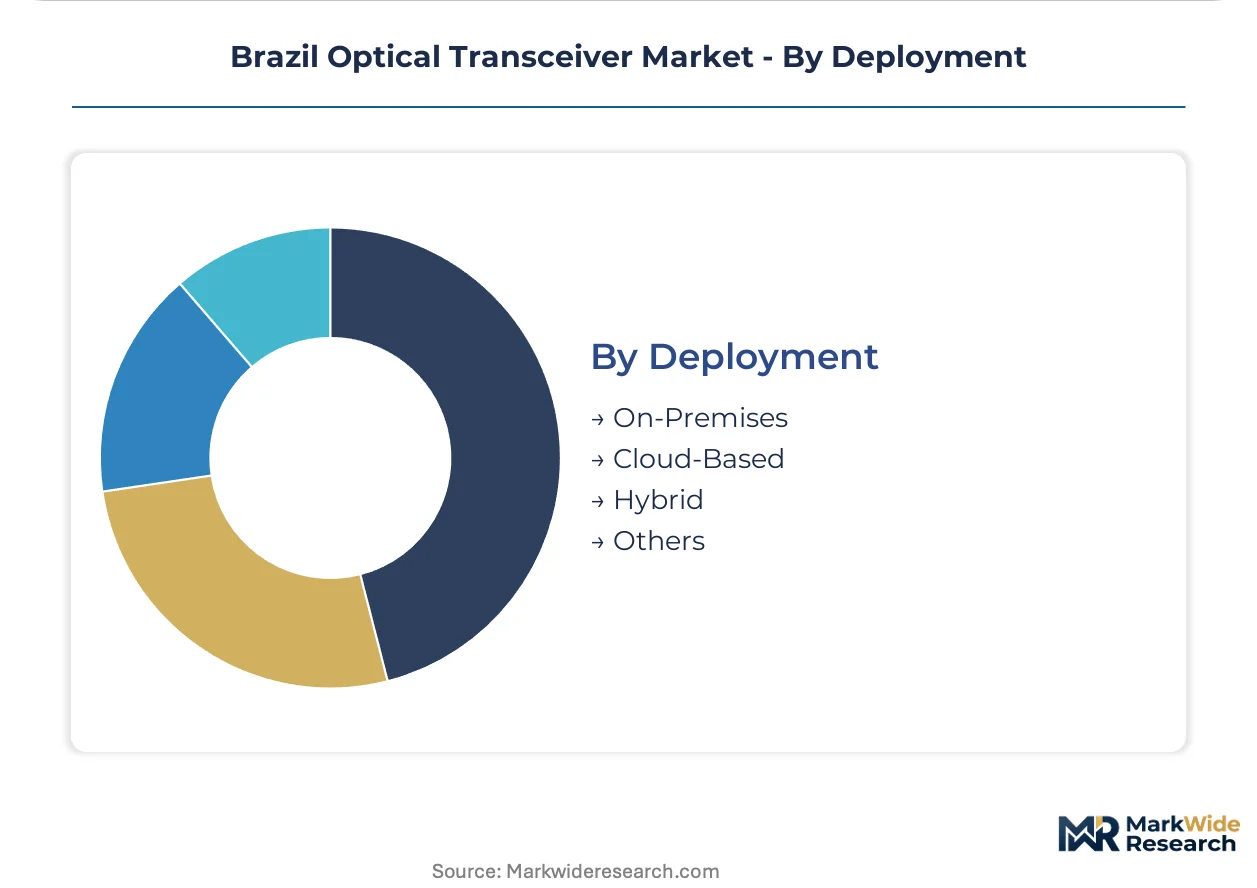
Deployment:
Infrastructure location determines latency requirements and regulatory jurisdiction for optical equipment procurement.
- On-Premises:Enterprise data centers in São Paulo's financial corridor maintain captive optical infrastructure for compliance-sensitive workloads. Trading venues require sub-microsecond latency that constrains cloud migration.
- Cloud-Based:Hyperscaler facilities in Campinas and Barueri deploy 400G and 800G interconnects at scale. ANATEL's data localization considerations influence supplier selection for these deployments.
- Hybrid:Financial institutions partition workloads across private infrastructure and cloud resources, creating heterogeneous optical requirements. Protocol interoperability testing extends procurement cycles.
- Others:Edge computing nodes and 5G radio access networks represent emerging deployment categories with unstandardized optical specifications.
Cloud-based deployments lead capital allocation. Hybrid architectures gain complexity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's financial corridor anchors Brazil's optical transceiver demand, with hyperscaler clusters in Campinas and Barueri driving form factor densification. ANATEL's broadband mandates reshape procurement geography across southeastern industrial zones.
São Paulo
Data center buildouts in Campinas and Barueri absorb 400G and 800G QSFP volumes for spine-leaf architectures. ANATEL's electromagnetic compatibility certification requires in-country testing, forcing suppliers to establish local partnerships. The financial district's trading venues demand sub-microsecond latency, constraining cloud migration and sustaining captive optical infrastructure.
Rio de Janeiro
Incumbent carriers maintain SONET/SDH infrastructure requiring protocol translation gateways for coherent module upgrades. ANATEL's type approval process creates 4-6 month import gateways, delaying deployment schedules. Metro ring networks in the metropolitan area face capital constraints that slow full infrastructure refresh cycles.
Minas Gerais
Belo Horizonte's municipal fiber deployments absorb residual 25G volumes as ANATEL universalization funds subsidize first-mile connectivity. The state's industrial automation sector generates enterprise demand for compact SFP interfaces. Regional carrier networks here lag southeastern counterparts in high-speed module adoption.
Ceará
Submarine cable landing stations in Fortaleza deploy CFP coherent modules for terrestrial backhaul extensions into São Paulo. ANATEL's certification friction hits longest-haul equipment hardest due to extended environmental stress validation. The northern corridor remains underpenetrated relative to southeastern infrastructure density.
Paraná
Curitiba's enterprise clusters sustain mid-tier 100G procurement for campus interconnect applications. PLI-style assembly incentives create margin advantages for domestically assembled modules versus imported alternatives. The state's manufacturing base supports optical packaging operations with varying yield rates.
Brazil Optical Transceiver Market Competitive Landscape
Global majors compete with regional champions across certification compliance and domestic assembly economics. Market structure consolidates around three tiers: silicon photonics specialists, coherent long-haul vendors, and enterprise bundling platforms. Two strategic archetypes dominate: hyperscale-direct suppliers bypassing distribution channels, and ANATEL-certified assemblers capturing local content premiums. Competitive moves center on Brazilian testing partnerships and PLI-qualifying assembly facilities.
Among the named players, Cisco Systems and Huawei Technologies exemplify divergent market approaches. Cisco leverages domestic channel partnerships to anchor enterprise router-to-transceiver bundling in São Paulo's financial district. Huawei competes aggressively on price-performance for 100G and 400G modules sold to Brazilian carriers. Coherent Corp. occupies a position within the long-haul specialist tier, its name signaling focus on submarine cable and metro applications. These three represent distinct strategic postures: bundling integration, carrier price competition, and coherent transmission specialization.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Coherent Corp. |
| Lumentum Holdings |
| Broadcom |
| Hewlett Packard Enterprise |
| Arista Networks |
| Accelink Technologies |
| Padtec |
| Others |
Pricing and Supply Chain Analysis
Silicon photonics integration is simultaneously collapsing module cost structures and redrawing supplier power dynamics across Brazilian optical networks. This manufacturing transition enables 800G transmission at sub-12-watt power budgets, compressing the historical premium commanded by indium phosphide-based coherent modules while concentrating procurement leverage among CMOS-capable foundries.
Pricing Analysis
Input-cost pass-through from indium phosphide laser chips anchors pricing stratification across performance tiers. Three-tier pricing separates ANATEL-certified coherent modules from standard QSFP data center units from economy-grade SFP enterprise interfaces, with certification grade and volume scale as primary differentiation drivers. Cost compression in 400G silicon photonics variants is intensifying because hyperscalers negotiate multi-year direct manufacturer agreements. Cloud providers exhibit lowest price sensitivity, while municipal fiber operators absorbing ANATEL universalization subsidies face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements from hyperscalers and Tier-1 carriers mandate multi-supplier qualification for critical laser components, forcing procurement teams to maintain parallel relationships with East Asian and domestic assembly partners. Optical component fabrication concentrates in Taiwan, China, and South Korea, with Brazilian facilities dependent on imported photonic integrated circuits, DSP silicon, and hermetic packaging materials. Single-source vulnerability in indium phosphide laser chip supply creates exposure to geopolitical disruption and extended qualification cycles. Distribution runs through ANATEL-certified assemblers capturing local content premiums, bypassing traditional import channels for enterprise and telecom deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through silicon photonics cost-down trajectories and premium-tier 800G ZR module adoption, as ANATEL localization mandates create pricing power for compliant domestic assemblers.
For Market Incumbents: Anticipate displacement pressure from copper DAC substitution below 7 meters by accelerating coherent-to-pluggable convergence in metro applications. Defensive moves require deepening backward integration into silicon photonics design partnerships and expanding ANATEL-certified testing capacity in São Paulo state. Channel control through router-transceiver bundling anchors enterprise retention against Huawei's carrier price aggression. For New Entrants and Emerging Players: Silicon photonics specialization offers entry leverage into hyperscaler direct procurement channels bypassing traditional distribution. White-space targets concentrate in northern corridor fiber deployments subsidized by ANATEL universalization funds, where first-mile 25G module demand exceeds qualified domestic supply. Go-to-market positioning through PLI-qualifying assembly partnerships captures margin advantages versus fully imported alternatives. For Investors and Strategic Acquirers: Valuations sit cheapest among optical packaging engineering specialists with ANATEL certification infrastructure and latent coherent module assembly capability. Long-term viability over the projection horizon hinges on convergence between data center and telecom optics supply chains. The signal to watch is ANATEL tightening local content thresholds, which would re-rate compliant assemblers against import-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Certification Partnership | Establishes in-country testing capability eliminating 4-6 month import gateways for coherent modules. |
| Silicon Photonics Design Integration | Enables 800G ZR module production collapsing cost gaps between data center and telecom optics. |
| PLI-Qualifying Assembly Facility | Captures local content premiums through domestically assembled QSFP modules versus imported alternatives. |
| Hyperscaler Direct Supply Agreement | Bypasses distribution channel disintermediation consolidating volume with Campinas and Barueri cloud operators. |
| Northern Corridor Distribution Expansion | Positions first-mile optical equipment for Manaus and Belém fiber markets under ANATEL universalization subsidies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center procurement officers, carrier network engineers, ANATEL certification specialists, optical component distributors, and silicon photonics R&D directors with secondary validation. Sources included ANATEL equipment approval databases, submarine cable landing station capacity disclosures, hyperscaler capex filings, and customs import records for optical equipment. Bottom-up module shipment estimates triangulated against top-down infrastructure investment flows.
Segment-weighting approaches distributed volume and value across form factor categories, data rate specifications, end-user verticals, and regional deployment clusters throughout the forecast period. CAGRs derived from infrastructure buildout timelines, ANATEL broadband target trajectories, and hyperscaler facility expansion announcements. Industry-specific inputs incorporated thermal design constraints at 15-watt power envelopes, electromagnetic compatibility certification friction, and PLI incentive qualification thresholds.
The model holds under stable ANATEL regulatory frameworks and continued hyperscaler facility investment in southeastern Brazil; deviation in local content mandate tightening or East Asian supply disruption would shift the outlook materially. Forecasts reflect assumptions regarding silicon photonics yield improvement and coherent module domestic assembly capability development. Specific risk factors include indium phosphide foundry concentration, copper DAC substitution acceleration, and legacy SONET/SDH infrastructure persistence extending procurement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Asia-Pacific Data Virtualization Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Computer Servers Market
Data Center and Networking
Data Center Services Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Mobile Data Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
Nosql Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Automotive Data Management Market