
 Postal Services Market | 2026-2036
Postal Services Market Size, Share, and Industry Trends Forecast 2026-2036
Postal Services Market Outlook
The capital-intensity divergence between integrated logistics giants and regional postal operators is collapsing as automation requirements reshape minimum viable scale. USPS sustains unmatched last-mile coverage through its statutory universal service obligation and physical address network. DHL dominates transcontinental express corridors with controlled air freight capacity and customs brokerage integration. FedEx differentiates through time-definite international shipping and specialized healthcare logistics infrastructure.
Postal services encompass the collection, processing, transportation, and delivery of letters, parcels, and documents through physical infrastructure networks operating with defined service level agreements and tracking capabilities. The sector functions as critical economic infrastructure, enabling commercial exchange, government communication, and consumer fulfillment through standardized addressing systems and regulated delivery performance. Express services and package delivery command the strongest margin pools as e-commerce volume shifts consumer expectations toward speed and visibility. Standard mail retains structural importance for government agencies and bulk corporate communications despite secular volume decline. Same-day delivery represents the fastest-growing delivery mode, though ground transportation still carries the majority of unit economics.
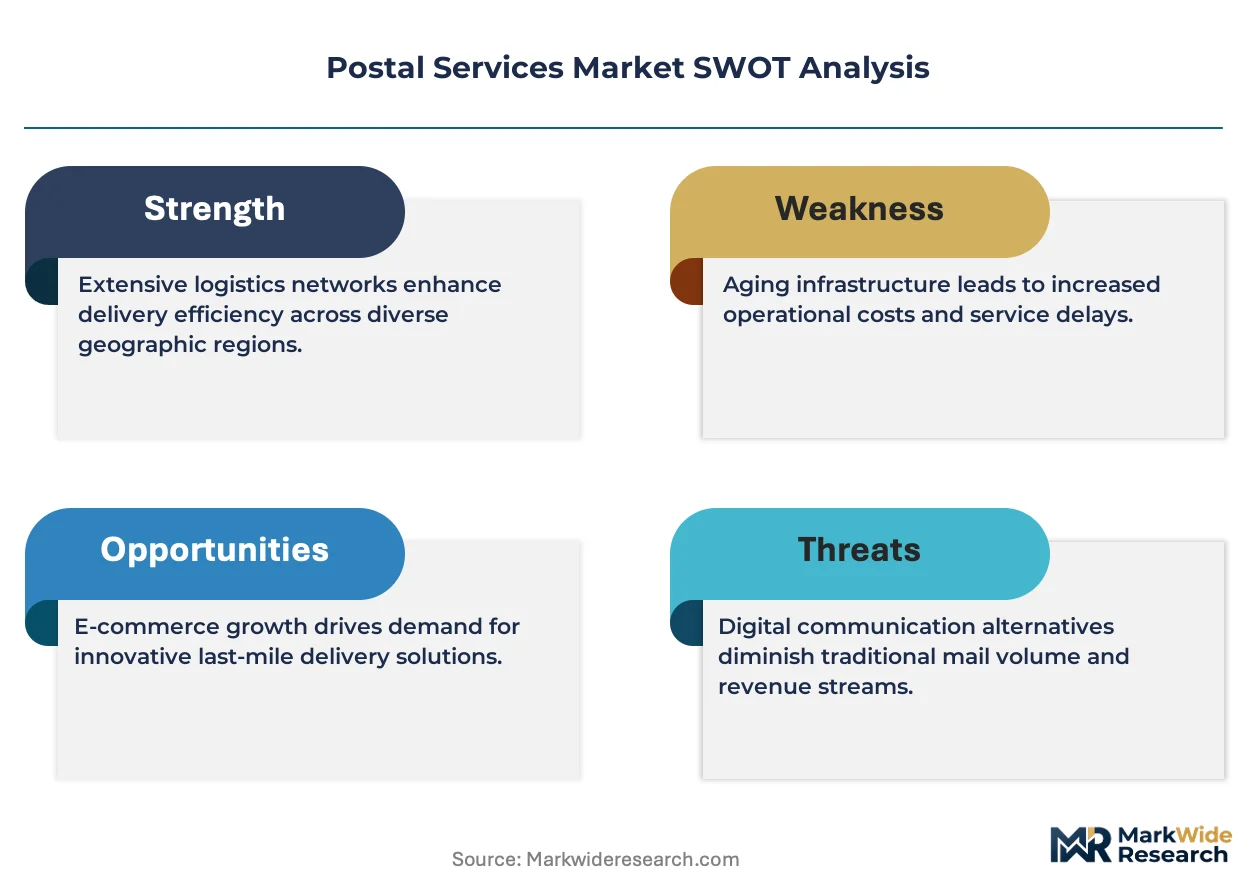
Universal service obligations enforced by national regulators in the United States, Germany, and Canada mandate minimum delivery standards and geographic coverage that shape operator cost structures and pricing authority. The EU Green Deal and national emissions frameworks are accelerating fleet electrification mandates that redirect capital toward battery-electric vehicles and alternative fuel infrastructure. Stakeholders must monitor how postal operators balance legacy mail infrastructure maintenance against parcel automation investments while regulatory compliance costs escalate.
Market Dynamics
The EU Green Deal's emissions mandates are forcing capital reallocation from legacy mail infrastructure toward electrified parcel networks and automated sorting systems.
Growth Catalysts
- E-commerce fulfillment density:Omnichannel retail is expanding parcel volume through centralized distribution hubs in Germany and the Netherlands, pulling automated last-mile investment.
- REACH-compliant fleet standards:European emissions frameworks are accelerating battery-electric vehicle deployment across national postal fleets, creating equipment refresh cycles.
- Healthcare cold chain expansion:Temperature-controlled pharmaceutical logistics is opening specialized express corridors between manufacturing clusters and hospital networks.
Market Restraints
- Lithium supply concentration:Battery raw material sourcing from concentrated mining jurisdictions is elevating fleet electrification costs and delivery timelines.
- Universal service obligations:Statutory coverage mandates in the United States, Germany, and Canada lock capital into low-margin rural delivery infrastructure.
- Digital substitution:Electronic billing and government communication platforms are compressing standard mail volumes in corporate and public sectors.
Strategic Opportunities
- Reverse logistics integration:E-commerce return flows are creating secondary revenue streams through consolidated collection networks and refurbishment partnerships.
- Customs brokerage automation:AI-driven clearance systems are reducing cross-border friction for small-parcel shippers in transcontinental corridors.
- Urban micro-fulfillment:Dark store networks in dense European city centers are enabling sub-two-hour delivery windows through bicycle and electric van fleets.
Industry Challenges
- Sorting automation talent:Robotics maintenance and warehouse management system integration require skilled technicians that national operators struggle to recruit at scale.
- Legacy IT modernization:Decades-old tracking and billing platforms resist API-based integration with e-commerce marketplace systems, delaying real-time visibility deployment.
- Electrification capex timing:Battery-electric vehicle procurement must synchronize with depot charging infrastructure buildout, straining capital allocation discipline.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postal Services Market |
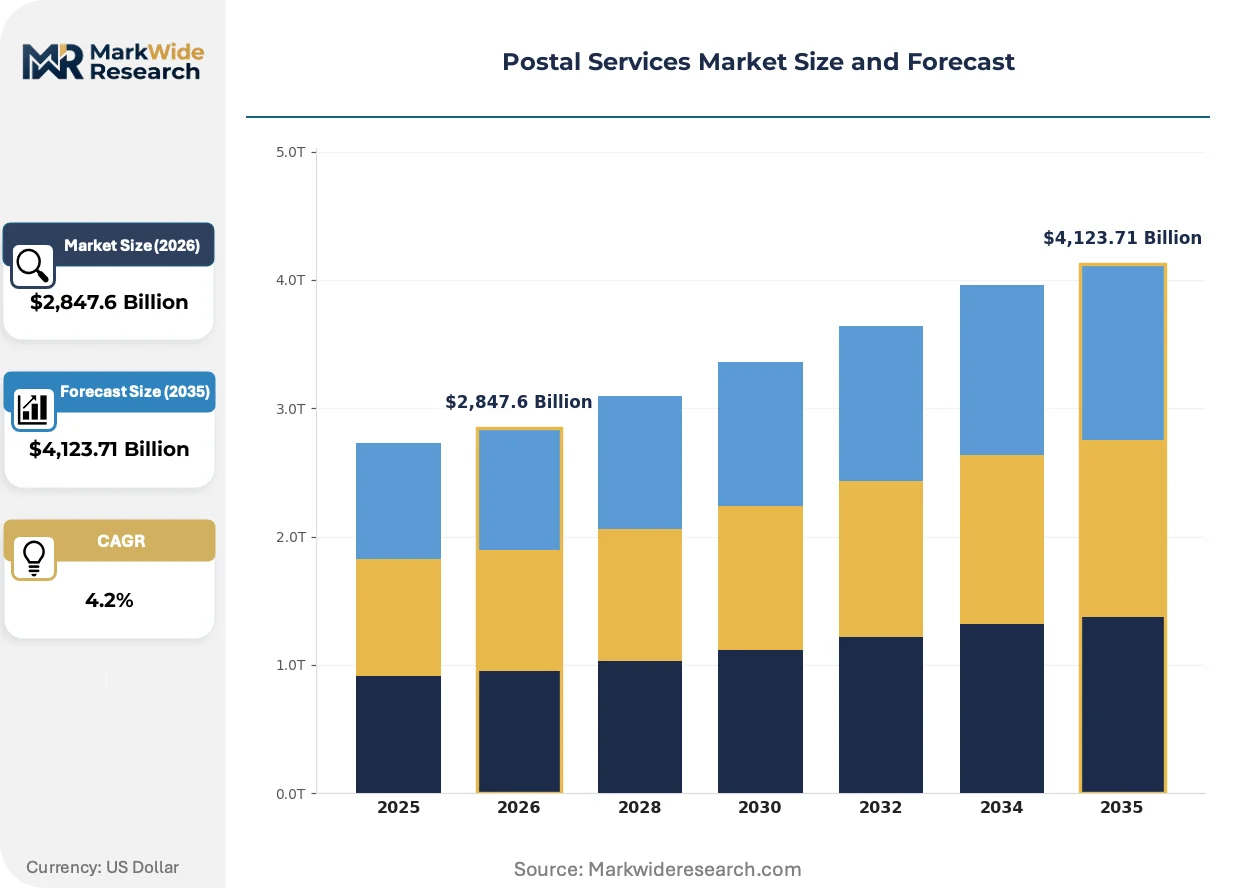
| Market Size in 2026 | $2,847.6 Billion |
| Market Size in 2035 | $4,123.71 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Mail, Express Services, Package Delivery, Bulk Mailing End User: Households, E-Commerce Companies, Government Agencies, Corporations Delivery Mode: Ground Transportation, Air Freight, Same-Day Delivery, International Shipping Packaging Type: Envelope, Box, Poly Mailer, Secure Packaging |
| Companies Covered | DHL, Canada Post Corporation, USPS, Purolator, Correos de Mexico, UPS, Amazon Logistics, OnTrac/LaserShip, FedEx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postal Services Market Strategic Shifts
Operational technology investments are bifurcating the sector between automated parcel hubs and declining letter processing infrastructure, with regulatory emissions mandates accelerating the capital shift.
Robotic sortation systems are decomposing traditional manual hub operations through AI-driven package singulation and dynamic routing algorithms. E-commerce fulfillment centers in Germany and the Netherlands are deploying these systems at scale, compressing unit processing costs and enabling same-day service windows that manual operations cannot match.
The EU Green Deal's fleet electrification timeline is mandating battery-electric vehicle procurement across national postal operators by 2030. This policy is redirecting maintenance capital toward charging infrastructure and grid integration, with German and French operators front-loading investment to secure vehicle allocation from constrained OEM production lines.
Buyer procurement patterns are consolidating shipping volume through platform-integrated rate APIs rather than negotiated annual contracts. Mid-market e-commerce sellers are shifting toward real-time carrier selection based on cost and speed algorithms, with this behavior most visible in the United Kingdom and Nordic markets where marketplace penetration is highest.
Postal Services Market Segmentation
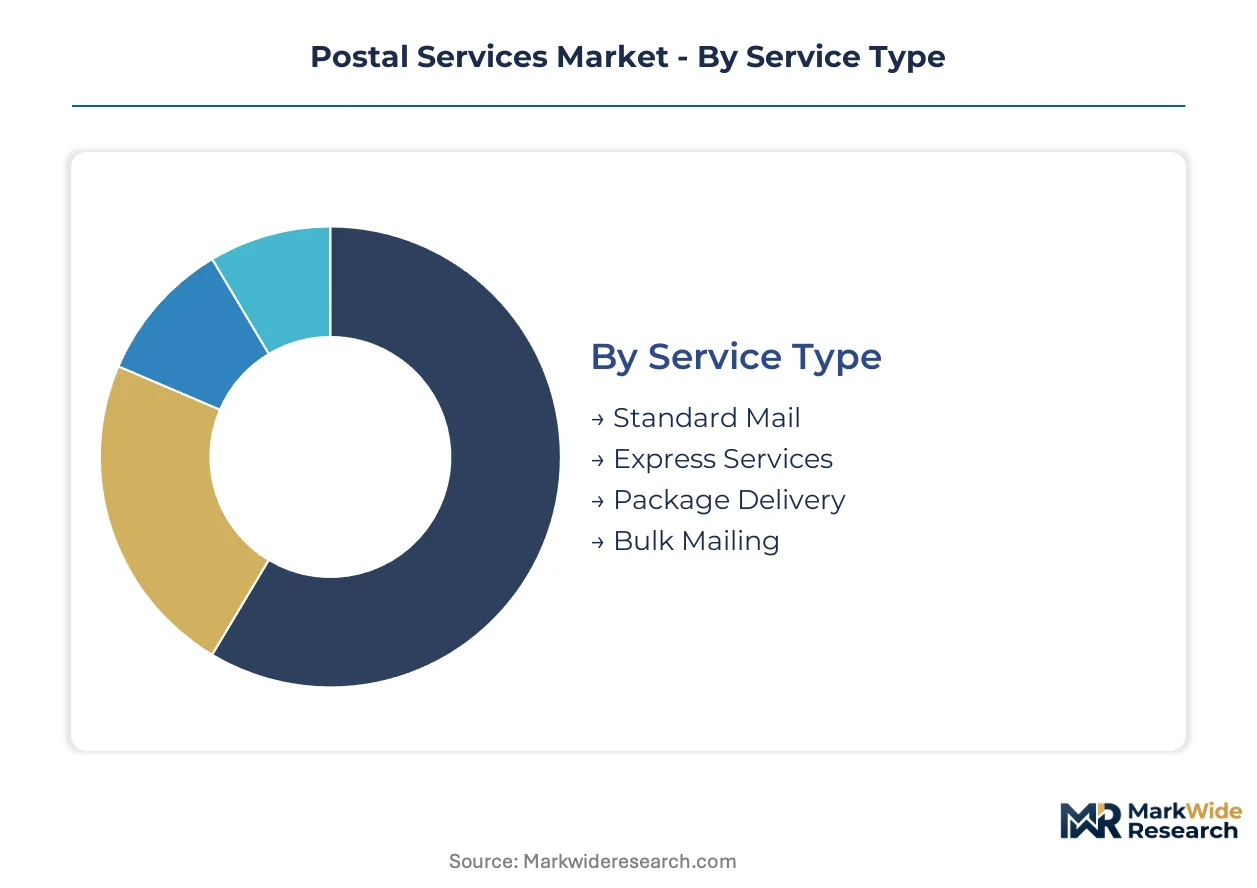
Postal service segmentation reveals how capital allocation and margin capture diverge across service tiers and customer types. Understanding these divisions exposes where automation investments concentrate and which delivery modes face regulatory pressure.
Service Type:
Channel flow varies sharply by service tier, with express and parcel services commanding premium infrastructure while standard mail subsidizes universal coverage obligations.
- Express Services:Time-definite delivery with guaranteed transit windows and end-to-end tracking. Demand concentrates in healthcare corridors and high-value manufacturing clusters where FDA and EMA compliance requirements mandate temperature monitoring and chain-of-custody documentation.
- Package Delivery:Non-expedited parcel handling with standardized transit commitments and scan-based visibility. E-commerce fulfillment networks in Germany and the Netherlands drive volume concentration, pulling automated sortation investment away from legacy mail facilities.
- Standard Mail:First-class and marketing correspondence with baseline delivery standards. Government benefit disbursements and bulk corporate communications sustain volume despite digital substitution pressure.
- Bulk Mailing:Consolidated letter and flat processing for high-volume senders with presort discounts. Catalog retailers and political campaigns remain core constituencies in the United States and Canada.
By volume, standard mail leads. By growth pace, package delivery is ahead.
End User:
Customer type determines pricing power and service customization depth, with enterprise accounts driving API integration and households receiving standardized offerings.
- E-Commerce Companies:Omnichannel retailers and marketplace sellers with high parcel volume and return-flow requirements. These customers negotiate dynamic rate APIs and consolidated billing across multiple origin points.
- Corporations:B2B shippers with contractual volume commitments and specialized handling needs for documents, samples, and replacement parts. Procurement teams prioritize customs brokerage integration for transcontinental lanes.
- Government Agencies:Statutory mailers with universal service obligations and regulated pricing. Tax authorities, licensing bodies, and election administrators depend on physical delivery for legal notification requirements.
- Households:Individual consumers with sporadic shipping needs and high price sensitivity. Residential delivery density shapes last-mile cost structures, particularly in rural United States and Canadian postal codes.
Revenue contribution tilts toward e-commerce companies. Margin expansion potential sits with corporate accounts.
Delivery Mode:
Transport modality selection reflects speed-cost tradeoffs and infrastructure availability, with ground networks absorbing volume growth while air freight retains premium positioning.
- Ground Transportation:Road and rail-based parcel movement with flexible routing and lower unit economics. European operators deploy battery-electric vans under EU Green Deal mandates, with German and French fleets leading electrification timelines.
- Same-Day Delivery:Sub-24-hour fulfillment through urban micro-fulfillment networks and gig-economy couriers. Dark stores in London, Paris, and Berlin enable sub-two-hour windows for grocery and fashion verticals.
- Air Freight:Controlled capacity express corridors with dedicated freighter and belly-hold integration. Pharmaceutical cold chain expansion drives specialized temperature-controlled lift between manufacturing clusters and hospital networks.
- International Shipping:Cross-border parcel and document handling with customs clearance integration. AI-driven brokerage systems reduce friction for small-parcel shippers in United Kingdom and Nordic markets with high marketplace penetration.
Ground transportation carries the volume base. Same-day delivery is climbing the fastest.
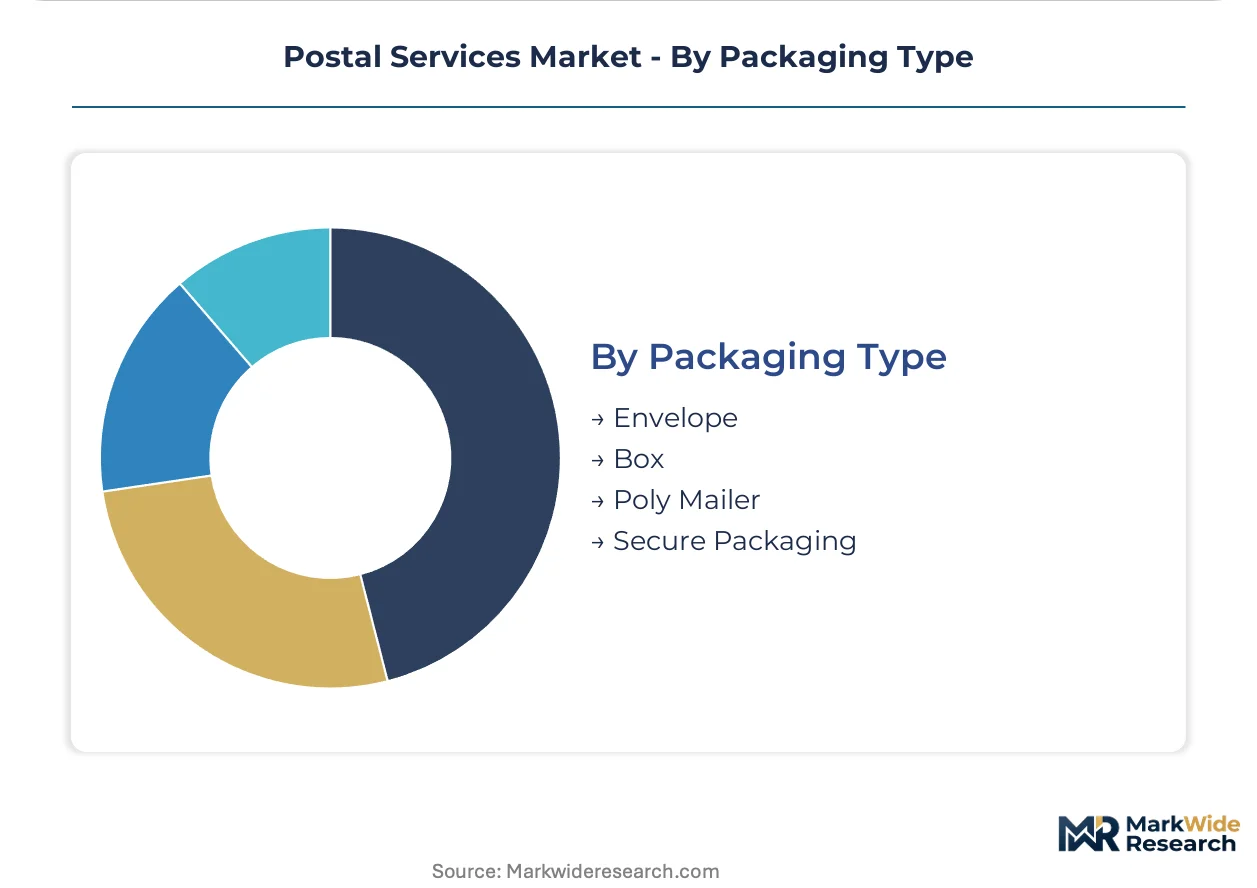
Packaging Type:
Material specifications align with content protection requirements and automated handling compatibility, driving standardization in high-volume channels.
- Box:Rigid corrugated containers for fragile and high-value goods with dimensional weight pricing. E-commerce fulfillment centers optimize box size algorithms to minimize void fill and shipping cost.
- Poly Mailer:Lightweight polyethylene envelopes for soft goods and apparel with moisture resistance. Fast fashion retailers in the United Kingdom and Germany favor this format for cost and sustainability profile.
- Envelope:Paper-based flat mailers for documents and lightweight correspondence. Standardized dimensions enable high-speed automated processing in legacy mail facilities.
- Secure Packaging:Tamper-evident and serialized containers for pharmaceuticals, jewelry, and confidential documents. FDA and DEA requirements mandate specific closure and tracking protocols for controlled substances.
Box usage dominates parcel volume. Poly mailer adoption is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in Canada by a substantial margin, driven by denser parcel networks and lower universal service cost burdens. Regulatory divergence between EU emissions mandates and North American compliance timelines widens this gap further.
United States
E-commerce fulfillment density and healthcare cold chain expansion drive volume concentration in the Southeast and Pacific Northwest. The FAA regulates drone delivery trials while the EPA enforces fleet emissions standards under the Clean Air Act. Amazon Logistics operates automated sortation hubs in Phoenix and Atlanta, compressing delivery windows for Prime subscribers.
Germany
Omnichannel retail penetration and automotive parts logistics sustain parcel growth in the Rhine-Ruhr corridor. The EU Green Deal mandates battery-electric vehicle procurement by 2030, with KBA overseeing type approval for commercial fleets. DHL operates Europe's densest last-mile network from Leipzig and Frankfurt hubs, setting continental operational benchmarks.
United Kingdom
Marketplace seller consolidation and gig-economy delivery integration reshape London's urban logistics. Ofcom regulates universal service obligations while the Competition and Markets Authority reviews carrier pricing. Dark store networks in Greater Manchester and Birmingham enable sub-two-hour fulfillment windows for grocery verticals.
Canada
Rural delivery obligations and cross-border e-commerce returns sustain volume despite low population density. Health Canada regulates pharmaceutical shipping standards while the CRTC oversees postal service pricing. Purolator and Canada Post Corporation maintain intermodal hubs in Mississauga and Vancouver to serve the Toronto-Montreal corridor.
France
Luxury goods export logistics and nuclear pharmaceutical shipments concentrate demand around Paris and Lyon. ANSM enforces cold chain compliance for biologics while the EU Green Deal accelerates La Poste's fleet electrification. Automated sorting facilities in Roissy and Bordeaux handle transcontinental express corridors to African francophone markets.
Postal Services Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the postal services sector. Integrated logistics giants control air freight capacity and customs automation, while national postal operators retain last-mile density through statutory universal service networks. Three archetypes dominate: transcontinental express carriers with controlled lift capacity, e-commerce platform logistics arms with captive volume, and state-affiliated postal operators with rural coverage mandates. Competitive moves concentrate on fleet electrification timing and automated sortation hub deployment.
Among North American integrated carriers, UPS and FedEx occupy positions as scale-driven express specialists with time-definite international portfolios. USPS anchors the universal service tier with unmatched physical address coverage. DHL represents the transcontinental archetype with controlled air freight corridors and customs brokerage integration across European and Asian markets.
| Leading Market Players |
|---|
| DHL |
| Canada Post Corporation |
| USPS |
| Purolator |
| Correos de Mexico |
| UPS |
| Amazon Logistics |
| OnTrac/LaserShip |
| FedEx |
| Others |
Value Chain & Pricing Dynamics
Battery-electric vehicle substitution for diesel delivery fleets simultaneously redraws procurement geography toward East Asian cell manufacturing and compresses total cost of ownership economics for national postal operators under EU Green Deal timelines.
Pricing Analysis
The customization-premium spread separates configured-to-order express corridors from standard parcel services, with time-definite healthcare logistics commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade for temperature-controlled shipments and volume scale for e-commerce platform integrations. Cost compression in standard mail is intensifying because digital billing platforms erode letter volume. E-commerce companies exhibit the highest price sensitivity due to algorithmic carrier selection, while pharmaceutical manufacturers accept premium positioning for compliance-guaranteed cold chain custody.
Supply Chain Analysis
Inventory lead times for battery-electric commercial vehicles now stretch eighteen to thirty-six months as OEM production lines allocate capacity toward passenger car segments. Geographic supply concentration centers on China, South Korea, and Japan for lithium-ion cell manufacturing, with cathode active material processing anchored in Indonesia and the Democratic Republic of Congo. Raw material dependencies include lithium carbonate, nickel sulfate, and cobalt hydroxide. Single-source vulnerability in cathode precursor supply creates concentration risk. Distribution runs through national postal fleet procurement offices and integrated logistics lessors with depot charging infrastructure partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Postal services sit at a high-growth disruption inflection where EU Green Deal fleet electrification mandates force simultaneous capital reallocation toward battery supply chains and automated sortation infrastructure.
For Market Incumbents: Secure lithium supply offtake agreements with diversified mining jurisdictions to de-risk cell procurement concentration. Anchor automated sortation hub deployment in Rhine-Ruhr and Southeast US e-commerce corridors to defend parcel volume capture against platform logistics arms. Vertical integration into depot charging infrastructure reduces third-party dependency.
For New Entrants and Emerging Players: Anchor in urban micro-fulfillment networks for same-day grocery and fashion verticals where incumbent last-mile density offers limited advantage. Target gig-economy courier aggregation platforms in London and Paris as the most penetrable segment. Pursue API-first rate marketplace positioning to bypass negotiated contract barriers.
For Investors and Strategic Acquirers: The market sits at a capital-intensity escalation phase that favors integrated operators with captive air freight capacity and customs automation depth. Long-term viability hinges on electrification execution discipline and robotics talent retention. Acquisition target archetype: regional parcel specialists with dense urban last-mile networks and underinvested electrification pipelines. Signal to watch: battery-electric vehicle allocation priority from constrained OEM production lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Secures battery-electric vehicle allocation from OEMs under EU Green Deal procurement timelines. |
| Automated Sortation Hub Deployment | Compresses unit processing costs in Germany and Netherlands e-commerce fulfillment corridors. |
| Customs Brokerage Automation | Reduces cross-border friction for small-parcel shippers in UK and Nordic marketplace channels. |
| Reverse Logistics Integration | Captures secondary revenue from e-commerce return flows through consolidated collection networks. |
| Healthcare Cold Chain Certification | Opens FDA and EMA-compliant express corridors between pharmaceutical manufacturing clusters. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EU regulatory databases, and customs trade records to validate market sizing assumptions. Primary interviews engaged postal operations executives, e-commerce logistics procurement leads, fleet electrification specialists, and pharmaceutical distribution managers. Secondary validation drew from EPA emissions disclosures, KBA type approval registers, and IATA cargo traffic data. Bottom-up volume builds triangulated against top-down macroeconomic elasticity models.
Segmentation dimensions modeled include service tier, end-user archetype, delivery modality, and packaging format across the projection horizon. Express and parcel volume trajectories derived from e-commerce penetration elasticity and omnichannel fulfillment density indicators. Standard mail decline rates calibrated against digital substitution indices from government communication platform adoption. CAGRs reflect compound annual progression across the modeling period without year-specific anchoring.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and lithium supply chain expansion; material deviation in battery raw material availability or emissions mandate delay would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Managed Communication Services Market
Communication Services
Cloud Communication Platform Market
Communication Services
Message Handling Systems Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Global Call Center Platform Market
Communication Services
Meeting Solutions Market
Communication Services
Walkie Talkie Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
Web Conferencing Market
Communication Services
In Flight Entertainment and Communication Market
Communication Services
Asia-Pacific Postal Services Market
Communication Services
Consumer Communication Services Market
Communication Services
Global Passenger Information System Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Latin America Postal Service Market