
 Commonwealth of Independent States (CIS) Building and Construction Sheets Market | 2026-2036
Commonwealth of Independent States (CIS) Building and Construction Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Commonwealth of Independent States (CIS) Building and Construction Sheets Market Outlook
Prefabricated panel systems is tilting procurement patterns across the CIS construction sector toward standardized sheet dimensions and factory-controlled quality. NLMK leverages its integrated steel-to-sheets production footprint to dominate metal-based construction panel supply across Russia and neighboring republics. Plyterra Group anchors the engineered wood segment through specialized plywood manufacturing scaled for modular housing projects. SafPlast Innovative competes in plastic construction sheets by extending its extrusion capabilities into weather-resistant cladding grades.
Building and construction sheets encompass flat, rigid or semi-rigid materials manufactured in standardized thicknesses typically ranging from 3 mm to 40 mm, engineered for structural sheathing, interior finishing, or protective surfacing in built environments. These products serve primarily as substrate layers, facade elements, or formwork surfaces across residential, commercial, and infrastructure applications. Plywood and OSB command the largest share of wood-based demand, with OSB gaining ground in residential wall sheathing as builders prioritize cost-engineered alternatives to solid timber. Metal sheets sustain premium positioning in commercial and infrastructure segments where load-bearing capacity and fire resistance carry specification weight. Plastic sheets, distributed through wholesale channels, occupy growing share in moisture-exposed applications such as bathroom cladding and agricultural construction.
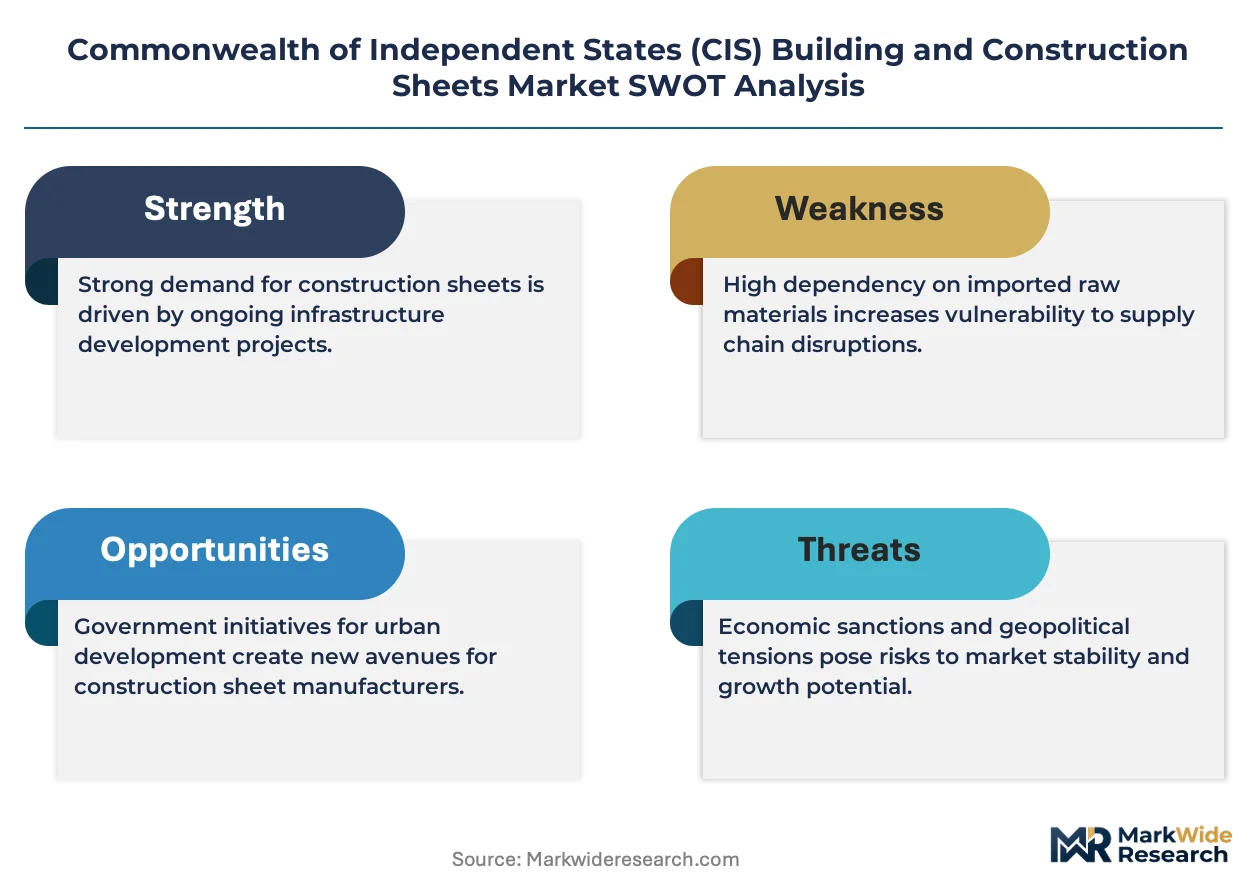
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) enforces GOST construction standards that mandate fire-retardant certification for sheet materials in multi-story residential buildings, directly filtering which products qualify for state-funded housing programs. Belarus's Ministry of Architecture and Construction maintains parallel technical codes that align with Eurasian Economic Union harmonization efforts, creating cross-border compliance obligations for sheet suppliers operating across the customs union. Kazakhstan's Committee for Technical Regulation and Metrology enforces construction material safety protocols that increasingly reference EU REACH substance restrictions, particularly for formaldehyde emissions in MDF and chipboard. Stakeholders must monitor how EAEU technical regulation convergence proceeds against national carve-outs for domestic sheet producers.
Market Dynamics
Russia's updated fire-safety technical regulations are forcing sheet manufacturers to reconfigure product portfolios toward certified grades, while prefabricated construction methods concentrate demand around standardized dimensions that favor factory-controlled quality over site-cut variability.
Growth Catalysts
- EAEU Harmonization:Belarus's Ministry of Architecture and Construction maintains technical codes aligned with Eurasian Economic Union standards, creating cross-border compliance pathways that reduce friction for sheet suppliers operating across the customs union.
- Modular Housing:Residential developers in Moscow's Central Federal District are specifying engineered wood panels for wall sheathing systems, compressing construction timelines and reducing on-site labor requirements.
- Formaldehyde Restrictions:Kazakhstan's Committee for Technical Regulation and Metrology enforces emission protocols referencing EU REACH substance limits, pulling MDF and chipboard manufacturers toward low-emission resin formulations.
Market Restraints
- Input Cost Volatility:Urea-formaldehyde resin prices fluctuate with natural gas feedstock costs, compressing margins for particleboard producers dependent on thermosetting adhesives.
- Supply Concentration:Metal sheet production clusters in Russia's Lipetsk and Magnitogorsk regions, creating geographic vulnerability to logistics disruptions affecting commercial construction timelines.
- Substitution Pressure:Cross-laminated timber is displacing traditional plywood in mid-rise residential frames, eroding volume for conventional sheet grades in multi-story applications.
Strategic Opportunities
- Agricultural Construction:Plastic cladding sheets for livestock housing and greenhouse structures remain underpenetrated across Kazakhstan's rural districts, where weather-resistant alternatives to metal siding command premium positioning.
- Digital Specification Tools:Building information modeling platforms are enabling architects to pre-validate sheet material fire ratings against Rosstandart GOST databases, accelerating procurement cycles for certified products.
- Urban Renewal Mandates:Moscow's renovation programs for Soviet-era housing stock are specifying fire-retardant OSB for interior partition systems, creating dedicated demand channels outside new-build construction.
Industry Challenges
- Certification Timeline Compression:Rosstandart's updated fire-safety testing protocols require extended laboratory validation periods, delaying product launches for manufacturers introducing modified resin formulations.
- Skills Shortage in Quality Assurance:Factory-level technicians capable of operating automated pressing equipment for engineered wood panels remain scarce across Russia's Volga Federal District production bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commonwealth of Independent States (CIS) Building and Construction Sheets Market |
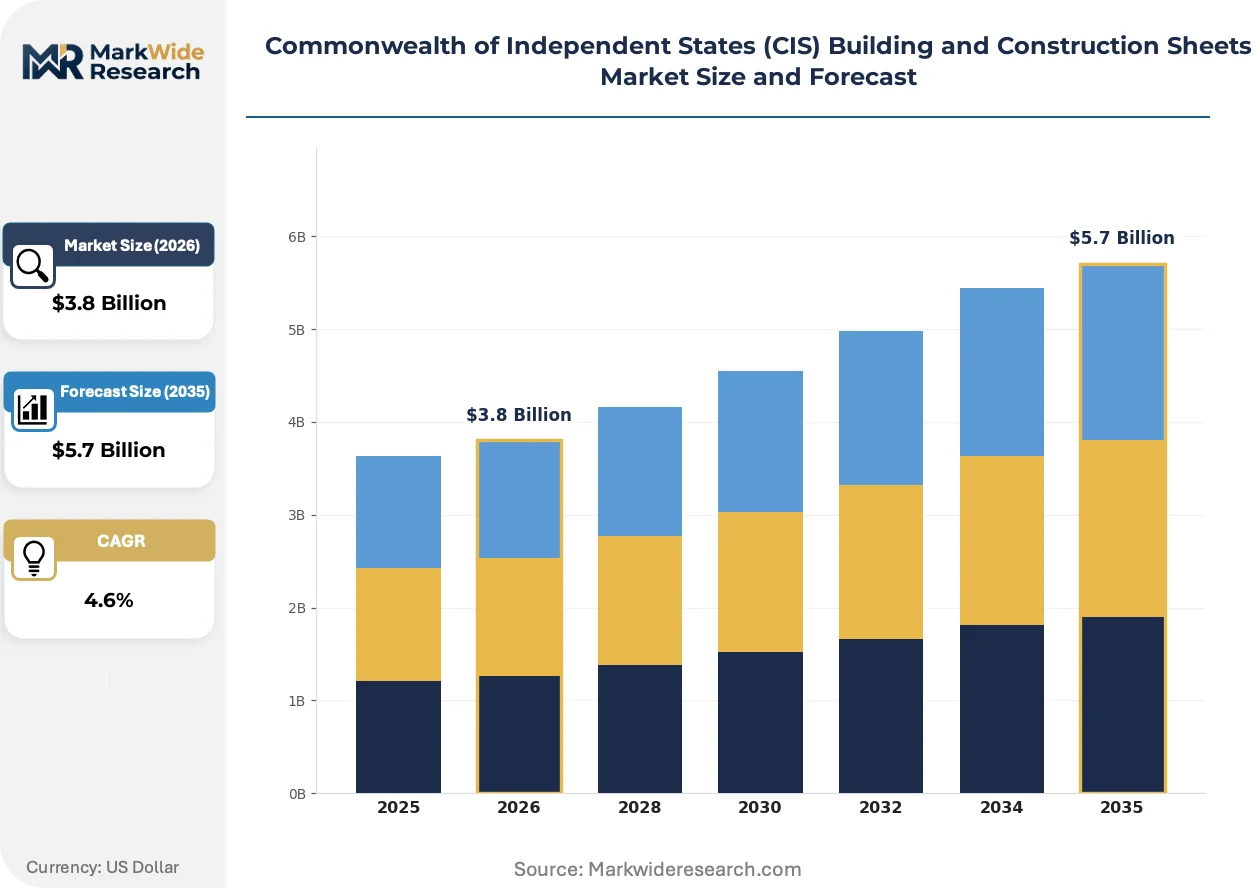
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, OSB, MDF, Chipboard Application: Residential, Commercial, Industrial, Infrastructure Material: Wood, Plastic, Metal, Composite Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | SafPlast Innovative, NLMK, Sumitomo Corporation, Plastmass Group, Prominvest, Ug Oil Plast, Armastek Group, Plyterra Group, Stymex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commonwealth of Independent States (CIS) Building and Construction Sheets Market Strategic Shifts
Digital specification workflows and material traceability systems are compressing the distance between sheet manufacturers and project engineers, enabling real-time compliance verification against evolving EAEU technical regulations.
Building information modeling software is virtualizing the pre-construction validation process for sheet material selection. Russian architectural firms are embedding GOST fire-rating databases directly into BIM platforms, collapsing the specification cycle from weeks to days. This compression is virtualizing traditional distributor roles as engineers source certified sheets through direct manufacturer portals.
Rosstandart's phased implementation of stricter GOST R 53292 fire-safety standards for multi-story residential applications is disqualifying uncertified particleboard from state-funded housing programs. Manufacturers are retrofitting production lines with intumescent coating capabilities to maintain eligibility. The regulatory pressure falls heaviest on medium-density fiberboard grades used in interior finishing systems across Moscow's municipal construction pipeline.
Developer procurement teams are consolidating sheet purchasing through integrated supply contracts that bundle structural sheathing, finishing panels, and protective membranes under single-source agreements. Wholesale distributors in Russia's Northwest Federal District are losing specification influence as direct manufacturer relationships capture volume from fragmented reseller networks. This consolidation is most visible in St. Petersburg's residential tower projects, where general contractors negotiate annual frame agreements with engineered wood producers.
Commonwealth of Independent States (CIS) Building and Construction Sheets Market Segmentation
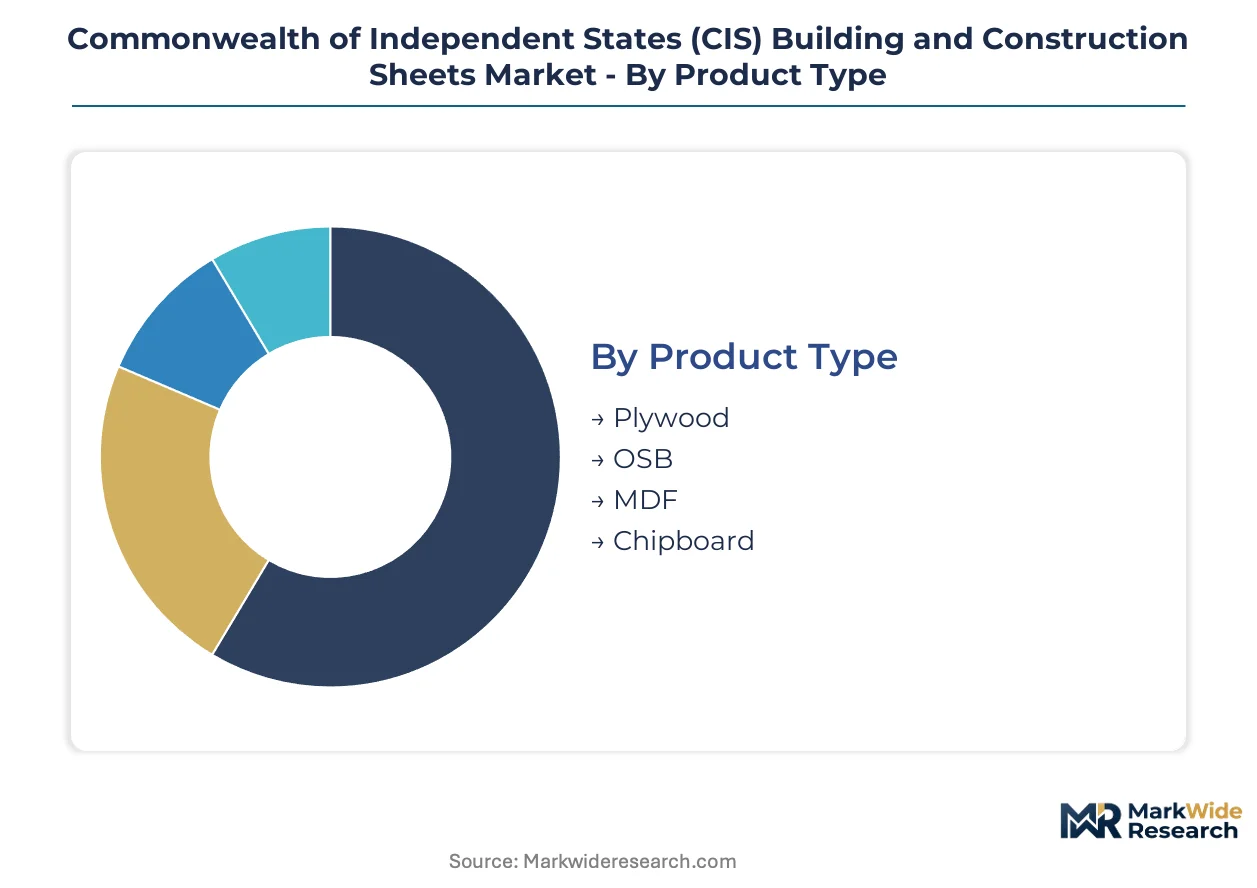
Segmentation in the CIS building and construction sheets market reveals how procurement cycles, certification requirements, and end-use specifications reshape competitive positioning across product categories. Understanding these divisions exposes where volume concentrates and where margins compress under regulatory pressure.
Product Type:
Plywood and OSB turn inventory fastest through Moscow's residential pipeline, while MDF and chipboard face extended certification timelines that slow stock rotation.
- Plywood:Cross-laminated veneer sheets bonded with phenolic or urea-formaldehyde resins deliver structural integrity for concrete formwork and wall sheathing. Russia's Central Federal District absorbs the bulk of volumes as Moscow developers prioritize certified grades for high-rise frames under Rosstandart fire-safety protocols.
- OSB:Oriented strand board compresses wood flakes in cross-directional layers with waterproof wax binders, creating cost-engineered alternatives to solid timber. Belarusian modular housing factories are specifying OSB for prefabricated wall systems, compressing construction timelines while meeting EAEU harmonized standards.
- MDF:Medium-density fiberboard manufacturers face Kazakhstan's formaldehyde emission limits referencing EU REACH substance restrictions.
- Chipboard:Particleboard grades serve interior finishing systems where cost sensitivity outweighs structural load requirements.
Plywood anchors the volume base while OSB gains share at the steepest rate.
Application:
Cost tiers separate specification authority, with infrastructure and commercial projects commanding premium-certified grades while residential developers optimize around standardized dimensions.
- Residential:Multi-story apartment construction across Russia's urban centers consumes engineered wood panels for wall sheathing, flooring substrates, and interior partitions. Moscow's renovation programs for Soviet-era housing stock are creating dedicated demand channels for fire-retardant OSB outside new-build pipelines.
- Commercial:Office and retail developments specify metal-based construction sheets where load-bearing capacity and fire resistance carry specification weight in facade and roofing applications.
- Industrial:Factory construction and warehouse facilities prioritize moisture-resistant plastic cladding for agricultural and logistics structures.
- Infrastructure:Bridge decking, tunnel lining, and transportation facilities require specialized composite sheets meeting extended durability testing protocols.
Residential construction anchors the volume base while infrastructure applications expand most quickly under federal investment programs.
Material:
Supply concentration shapes margin structures, with metal production clustering in Russia's industrial regions while wood-based sheet manufacturing distributes across forest belt republics.
- Wood:Engineered panels from birch, pine, and spruce feed residential and light commercial construction across the customs union. Plyterra Group and similar producers scale output for modular housing projects in Belarus and Kazakhstan.
- Metal:Steel and aluminum sheets sustain premium positioning in commercial and infrastructure segments where Rosstandart GOST fire ratings mandate non-combustible materials.
- Plastic:PVC and polycarbonate extrusions penetrate moisture-exposed applications including bathroom cladding and agricultural greenhouse construction.
- Composite:Fiber-reinforced and engineered mineral boards serve niche specifications requiring combined structural and thermal performance.
Wood-based materials anchor the volume base while plastic sheets climb the fastest on agricultural construction demand.
Distribution Channel:
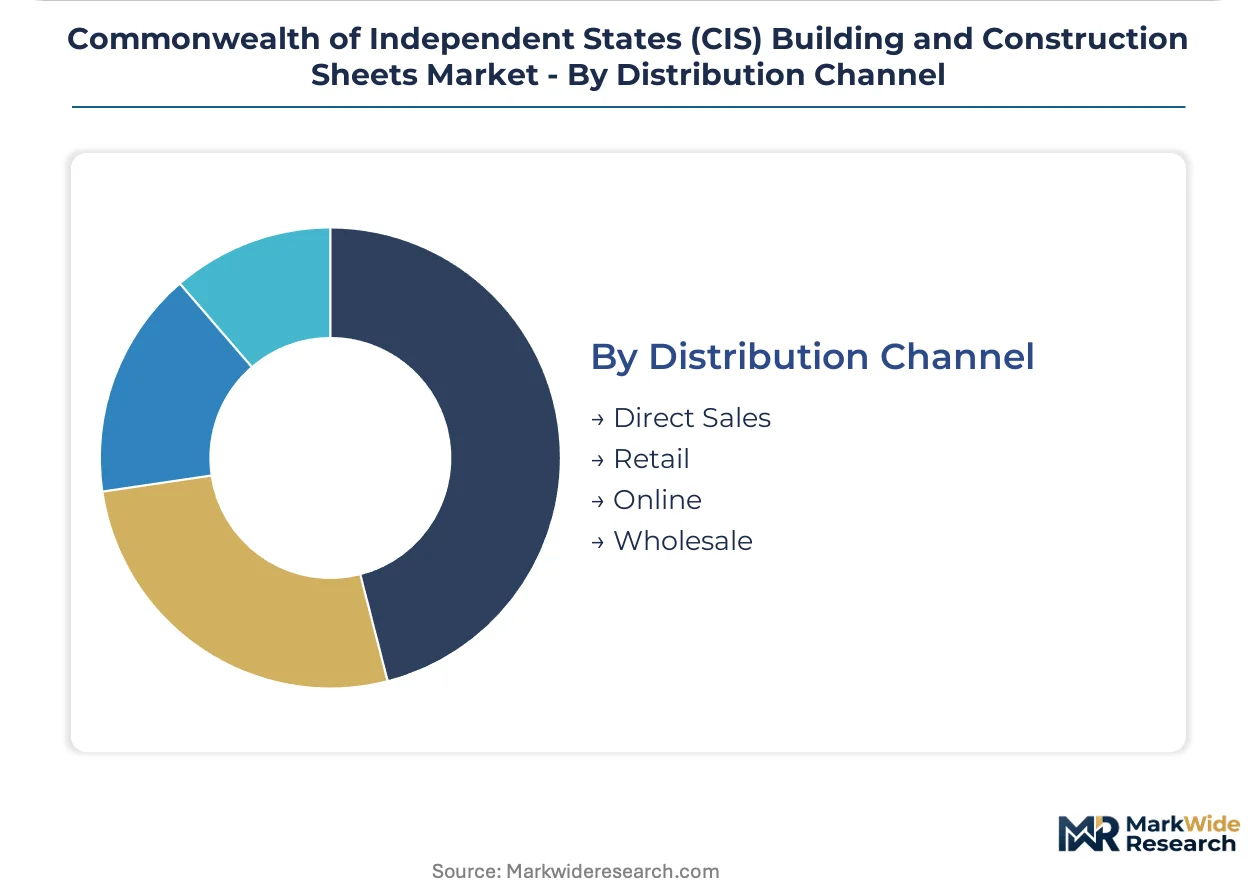
Customer type determines channel leverage, with large developers bypassing intermediaries while smaller contractors depend on fragmented wholesale networks.
- Direct Sales:Volume contractors in St. Petersburg and Moscow negotiate annual frame agreements with engineered wood producers, consolidating structural sheathing, finishing panels, and protective membranes under single-source contracts.
- Retail:Builder merchants and specialized construction outlets serve renovation contractors and small-scale residential developers with standardized sheet dimensions.
- Online:Digital specification workflows through manufacturer portals are virtualizing traditional distributor roles as engineers source certified sheets directly.
- Wholesale:Regional distributors in Russia's Northwest Federal District are losing specification influence as integrated supply contracts capture volume from fragmented reseller networks.
Direct sales anchor the volume base while online channels gain share fastest as BIM-integrated procurement compresses specification cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia exports engineered wood panels to Belarus and Kazakhstan under Eurasian Economic Union tariff preferences, consolidating cross-border supply chains around Moscow production clusters while Rosstandart certification protocols filter which grades qualify for state-funded housing programs.
Russia
Moscow's Central Federal District consumes the bulk of CIS sheet volumes through residential tower projects and Soviet-era housing renovation programs. Rosstandart enforces GOST R 53292 fire-safety standards that disqualify uncertified particleboard from municipal construction tenders. Lipetsk and Magnitogorsk anchor metal sheet production for commercial facade applications.
Belarus
Modular housing factories in Minsk and Brest are specifying OSB wall sheathing systems to compress construction timelines for prefabricated residential units. The Ministry of Architecture and Construction maintains technical codes aligned with EAEU harmonization efforts, enabling seamless import of Russian-certified panels. Gomel Region hosts emerging distribution hubs serving cross-border projects.
Kazakhstan
Agricultural construction across Akmola and Almaty regions is absorbing weather-resistant plastic cladding for livestock housing and greenhouse structures. The Committee for Technical Regulation and Metrology enforces formaldehyde emission protocols referencing EU REACH substance restrictions, pulling MDF manufacturers toward low-resin formulations. Nur-Sultan's commercial development pipeline specifies metal sheets for fire-rated facades.
Uzbekistan
Infrastructure investment in Tashkent and Samarkand is creating demand for composite sheets in bridge decking and tunnel lining applications. The national technical regulation agency is gradually aligning construction material standards with EAEU frameworks to facilitate regional trade. Fergana Valley industrial zones are emerging as assembly points for imported panel systems.
Azerbaijan
Baku's urban renewal initiatives are specifying certified OSB for interior partition systems in high-rise residential conversions. The State Committee for Standardization enforces construction material safety protocols that increasingly reference Russian GOST benchmarks. Sumgayit industrial corridor hosts distributors consolidating shipments from Russian engineered wood producers.
Commonwealth of Independent States (CIS) Building and Construction Sheets Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement tiers, with integrated steel-to-sheets producers dominating metal-based construction panel supply while engineered wood specialists scale for modular housing contracts. The market structures around three archetypes: vertically integrated metallurgical conglomerates, forest-belt plywood specialists, and extrusion-capable plastic sheet fabricators. Competitive moves concentrate on securing annual frame agreements with volume contractors and retrofitting production lines for intumescent coating capabilities.
Among Russia-based producers, NLMK exemplifies the metallurgical-integrated archetype controlling metal sheet supply chains, while Plyterra Group anchors the engineered wood segment through birch plywood specialization. SafPlast Innovative occupies a position within the plastic extrusion tier, representing manufacturers extending capabilities into weather-resistant cladding grades for moisture-exposed applications.
| Leading Market Players |
|---|
| SafPlast Innovative |
| NLMK |
| Sumitomo Corporation |
| Plastmass Group |
| Prominvest |
| Ug Oil Plast |
| Armastek Group |
| Plyterra Group |
| Stymex |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Russia's engineered wood panel sector is compressing margins for commodity-grade producers while concentrating pricing power among manufacturers with Rosstandart fire-safety certification. This utilization asymmetry rewards certified suppliers with state-funded housing program access while forcing uncertified competitors toward spot-market discounting.
Pricing Analysis
Certification-grade pricing gaps separate current-gen fire-retardant OSB from prior-gen untreated panels and next-gen intumescent-coated systems. Three-tier pricing structure across certified-premium, standard-grade, and economy-uncertified levels dominates procurement, with Rosstandart GOST R 53292 compliance and volume scale as primary differentiation drivers. Pricing pressure stems from urea-formaldehyde resin cost volatility tied to natural gas feedstock fluctuations. Residential developers in Moscow's Central Federal District exhibit highest price sensitivity, while infrastructure contractors prioritize certified grades regardless of premium.
Supply Chain Analysis
Export-control restrictions on advanced pressing equipment and resin formulations limit technology transfer into CIS sheet manufacturing, constraining quality upgrades. Supply concentrates in Russia's forest belt republics, Belarus, and Kazakhstan's emerging industrial zones. Birch timber, phenolic resins, and wax binders constitute critical input dependencies. Single-source vulnerability runs through Lipetsk and Magnitogorsk metal sheet clusters. Distribution runs through direct manufacturer portals for volume contractors and fragmented wholesale networks for smaller builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers, regional regulatory divergence, and modular housing procurement consolidation creates niche entry points for specialized players. Prefabricated construction methods are splitting demand between standardized bulk contracts and customized engineered wood systems.
For Market Incumbents: Pre-empt cross-laminated timber substitution by retrofitting OSB lines for intumescent coating capabilities and securing annual frame agreements with Moscow's Central Federal District developers. Backward integration into captive resin production hedges urea-formaldehyde cost volatility. Certification investment in Kazakhstan's REACH-aligned emission protocols opens customs union arbitrage opportunities. For New Entrants and Emerging Players: Pursue agricultural plastic cladding penetration across Kazakhstan's Akmola and Almaty regions, where weather-resistant livestock housing and greenhouse applications remain underserved. Kazakhstan's rural districts offer the most penetrable geography given limited local extrusion capacity. Digital specification workflows through BIM-integrated manufacturer portals provide direct access to engineering-led procurement teams bypassing wholesale intermediaries. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated forest-belt producers with modular housing contract pipelines and Rosstandart certification infrastructure. The five-to-ten year viability window favors assets with EAEU harmonization compliance and cross-border logistics integration. Watch EAEU technical regulation convergence against national carve-outs as the inflection signal for regulatory arbitrage plays.| Strategic Initiative | Industry Significance |
|---|---|
| Intumescent Coating Line Retrofit | Rosstandart GOST R 53292 compliance secures state-funded housing program eligibility for MDF and OSB grades. |
| Backward Integration into Resin Production | Captive urea-formaldehyde supply hedges natural gas feedstock volatility compressing particleboard margins. |
| Direct-to-Contractor Portal Launch | BIM-integrated procurement collapses specification cycles and captures volume from Northwest Federal District distributors. |
| Agricultural Cladding Grade Development | Weather-resistant PVC and polycarbonate extrusions penetrate Kazakhstan's underpenetrated livestock housing sector. |
| EAEU Cross-Border Certification Harmonization | Unified technical standards reduce friction for Russian panel exports into Belarus and Kazakhstan customs union markets. |
Study Parameters
Cross-validation between primary interviews with production directors at engineered wood facilities and secondary analysis of Rosstandart GOST certification databases anchors the qualitative findings. Plant managers at plywood and OSB facilities, procurement leads at Moscow residential developers, distribution channel partners in Russia's Northwest Federal District, and technical R&D directors at resin suppliers constitute the stakeholder base. Secondary sources include EAEU technical regulation harmonization documents, customs union trade flow records, construction material safety protocols from Kazakhstan's Committee for Technical Regulation and Metrology, and SEC filings from publicly traded building materials conglomerates. Bottom-up volume estimates triangulate against top-down construction spending projections.
Calibration against historical certification timelines and production capacity utilization rates informs the analytical framework across the projection horizon. Segmentation dimensions include product type, application, material composition, and distribution channel, with regulatory certification tier as an industry-specific overlay. CAGRs derive from fitted growth curves applied to certified-grade volume trajectories and spot-market commodity-grade trends. Forecast inputs incorporate modular housing adoption rates and EAEU technical regulation convergence assumptions.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, construction lending rates, or EAEU customs union tariff structures would shift the trajectory. Forecasts reflect documented assumptions about certification timeline compression and prefabricated construction penetration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Earthen Plasters Market
Building Materials
Rubbing Bricks Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
South Africa White Cement Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Acoustic Damping Tiles Market
Building Materials
Solar Control Window Film Market
Building Materials
Sanded Grout Market
Building Materials
Shotcrete Market
Building Materials
North America Cement Market
Building Materials
Construction Materials Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Stone Coated Steel Roofing Market
Building Materials
Asia-Pacific Cement Market
Building Materials
India Concealed Cistern Market