
 Saudi Arabia GRC Cladding Market | 2026-2036
Saudi Arabia GRC Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia GRC Cladding Market Analytics
Saudi Green Building Forum standards is recalibrating material specifications across the kingdom's construction procurement chain. PETRACO leverages its manufacturing scale to supply large-scale hospitality developments along the Red Sea coast. Albitar Factory Co. anchors its position through specialized decorative element production for high-end residential towers. ARTIC differentiates via custom-fit facade capabilities tailored to architect-driven commercial projects in Riyadh and Jeddah.
Glassfiber Reinforced Concrete (GRC) cladding combines alkali-resistant glassfiber with cementitious matrices to produce lightweight, high-strength panels typically cast through spray or premix methods, serving primarily as durable architectural envelope systems for buildings requiring complex geometries and fire resistance. Facade Systems command the largest share of architect specifications due to their integration with curtain wall engineering, while Decorative Elements represent the fastest-growing category as heritage-inspired motifs penetrate luxury hospitality and premium residential segments. Precast Panels sustain steady contractor demand through standardized sizing that reduces on-site labor hours.
SFDA material safety protocols and SASO technical regulations for construction products shape GRC cladding compliance pathways, with municipal building codes in Riyadh, Jeddah, and Dammam adding localized fire-performance and wind-load requirements. The Saudi Building Code enforcement mechanisms increasingly tie product certification to project approval timelines. Stakeholders must monitor how evolving green building rating systems and carbon disclosure expectations for embodied materials reshape supplier qualification criteria.
Market Dynamics
Mega-project concentration along the Red Sea coast is compressing procurement cycles and forcing GRC cladding suppliers to scale spray-casting capacity ahead of traditional demand signals. The Saudi Building Code enforcement mechanisms tie product certification directly to municipal approval timelines, creating a compliance bottleneck that reshapes competitive positioning.
Growth Catalysts
- SFDA Material Safety Protocols:Mandated alkali-resistance testing for glassfiber reinforcement is elevating quality thresholds and disqualifying low-grade imports from neighboring GCC states.
- Red Sea Hospitality Pipeline:Luxury resort developments require complex geometric facade systems that favor GRC's moldability over precast concrete alternatives.
- Saudi Green Building Forum Standards:Embodied carbon disclosure requirements for envelope materials are redirecting architect specifications toward locally manufactured panels with verified supply chains.
Market Restraints
- Alkali-Resistant Glassfiber Supply Concentration:Three specialty fiber suppliers control import channels through Jeddah port, exposing fabricators to shipping delay risk.
- White Cement Price Volatility:Aesthetic-grade cladding depends on Saudi White Cement Company pricing, which fluctuates with fuel subsidy adjustments.
- Curtain Wall Substitution:Unitized aluminum systems with composite infill panels capture mid-tier commercial specifications where GRC once dominated.
Strategic Opportunities
- NEOM Urban Envelope Mandates:The linear city's facade performance specifications create demand for fire-rated GRC systems with integrated thermal breaks.
- Heritage Motif Integration:Decorative element contracts for Diriyah Gate and AlUla restoration projects reward suppliers with in-house sculpting capability.
- Direct-to-Contractor Digital Platforms:Procurement portals bypassing traditional distributor markups are capturing volume from mid-size Riyadh developers.
Industry Challenges
- Spray-Casting Technician Scarcity:The specialized skill required for consistent fiber-cement matrix application limits production ramp speed for new entrants.
- SASO Certification Timelines:Factory audit backlogs extend product approval cycles by four to six months, delaying project mobilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia GRC Cladding Market |
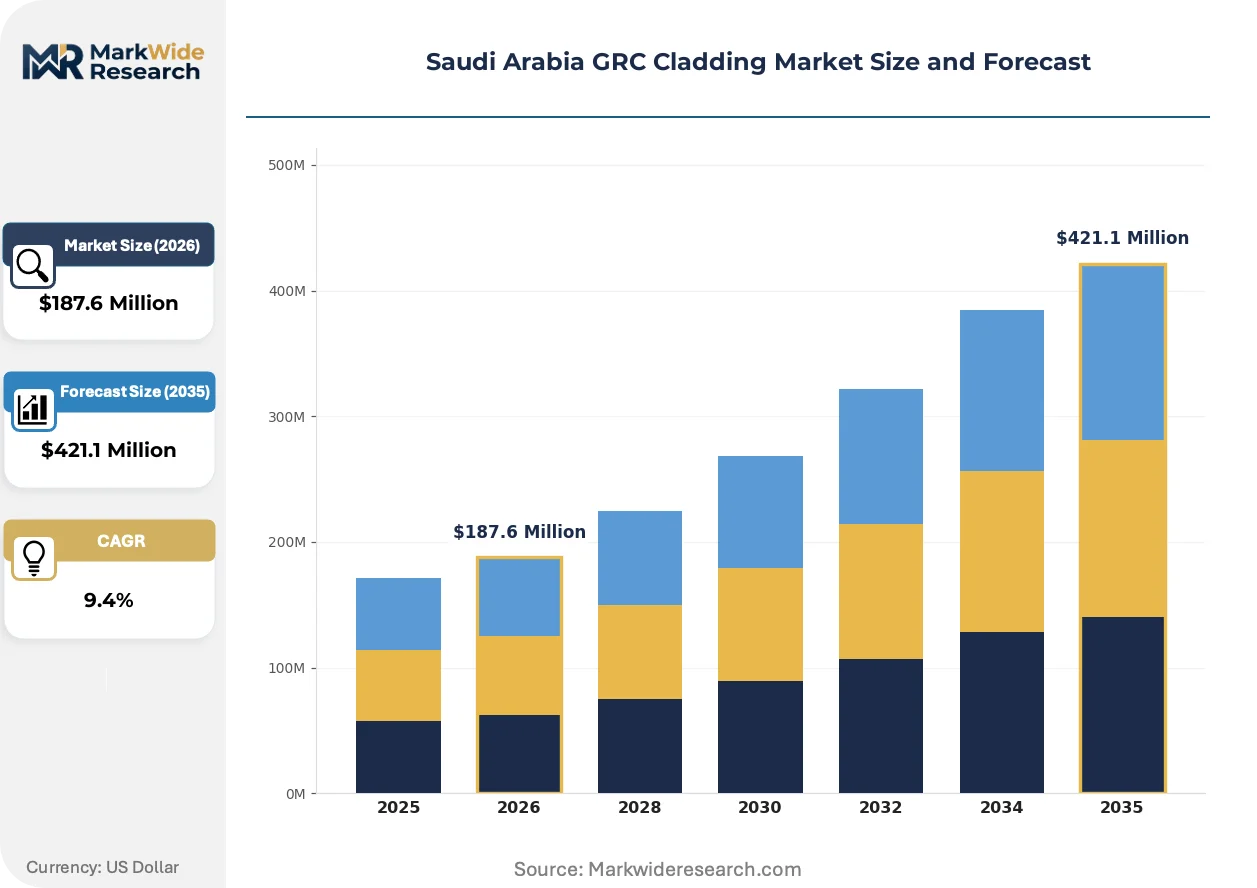
| Market Size in 2026 | $187.6 Million |
| Market Size in 2035 | $421.1 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precast Panels, Decorative Elements, Facade Systems, Support Structures Application: Commercial Buildings, Residential Complexes, Infrastructure Projects, Hospitality Installation Method: Cladding, Overlay, Custom Fit, Modular End User: Contractors, Architects, Property Developers, Government Agencies |
| Companies Covered | Albitar Factory Co., PETRACO, ARTIC, Station Contracting Co. Ltd, GRC Touch, Acementiat Factory, TUNSIF, Arabian Tile Company, DURRAKA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia GRC Cladding Market Evolving Landscape
Digital fabrication workflows and performance-based material specifications are displacing traditional casting methods across Saudi Arabia's high-value envelope contracts. Architects now specify parametrically optimized panel geometries that demand responsive manufacturing infrastructure.
Hybrid spray-premix production lines is modularizing GRC fabrication by separating decorative surface casting from structural backing formation. Red Sea resort developers adopt this dual-process approach to accelerate complex facade delivery without sacrificing compressive strength. The technology is modularizing supplier capabilities, enabling smaller fabricators to bid on geometrically demanding projects previously reserved for integrated producers.
SASO technical regulations for construction products now mandate third-party fire-performance testing for all facade materials in buildings exceeding 75 meters. This enforcement compresses the supplier qualification window and elevates documentation burdens. Riyadh commercial towers face the strictest compliance scrutiny, with municipal building departments rejecting submittals lacking ISO 17025 laboratory accreditation.
Developer procurement teams now bundle envelope specification with lifecycle carbon accounting, requiring suppliers to disclose embodied energy per square meter. This behavioral shift displaces price-per-panel bidding in favor of total-cost-of-ownership evaluation. Jeddah luxury residential towers exhibit the most aggressive adoption, with sustainability consultants embedded in architect selection committees.
Saudi Arabia GRC Cladding Market Segmentation
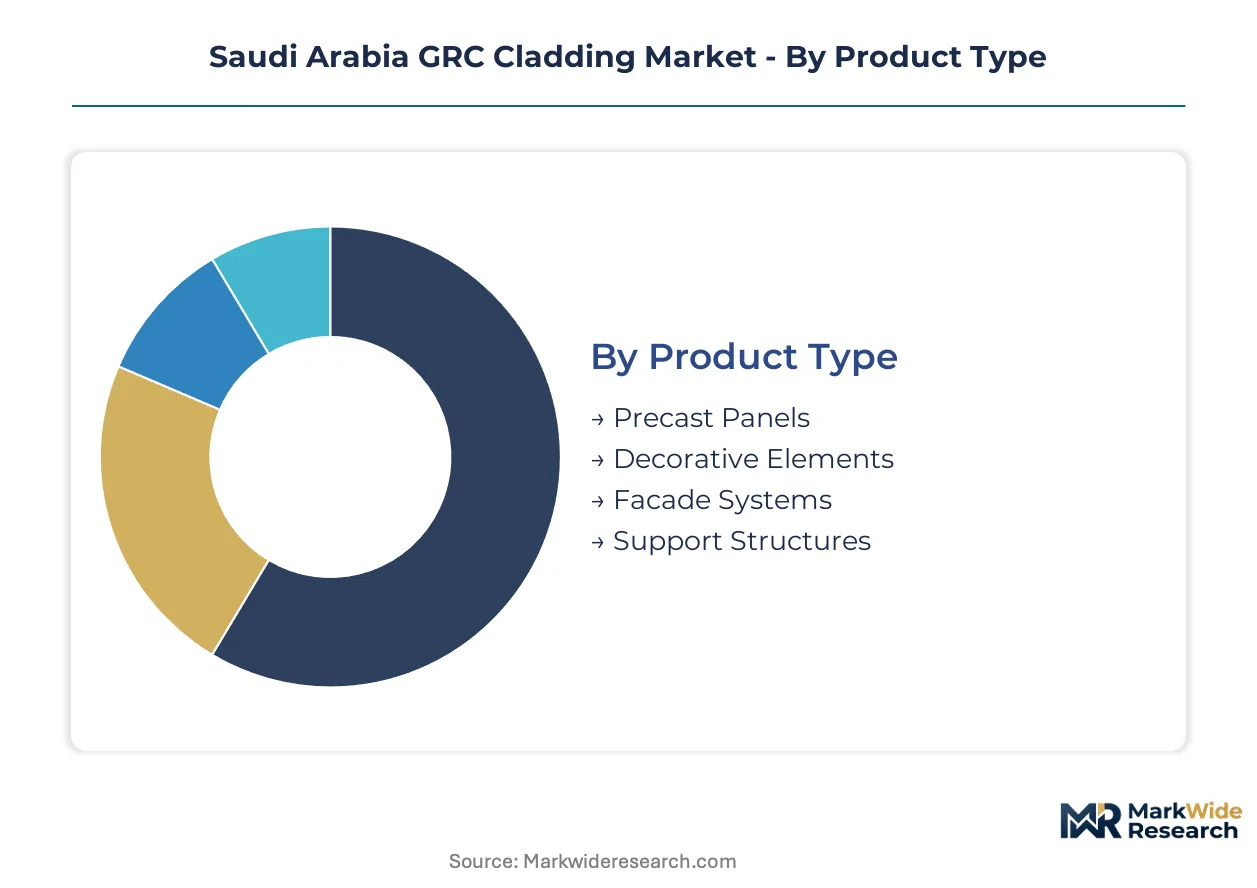
Architect specification power and contractor procurement authority split differently across each dimension of the Saudi GRC cladding market. Understanding these segment boundaries reveals where margin concentrates and where volume flows.
Product Type:
Facade Systems dominate architect specifications and command premium pricing, while Precast Panels drive contractor volume through standardized production.
- Facade Systems:These integrate alkali-resistant glassfiber with cementitious matrices to form lightweight envelope panels engineered for curtain wall attachment. Riyadh commercial towers concentrate demand here, with SASO fire-performance mandates above 75 meters forcing certification upgrades that favor established suppliers.
- Decorative Elements:Heritage-inspired sculptural components serve luxury hospitality and premium residential segments. Red Sea resort developments and Diriyah Gate restoration projects are accelerating uptake of geometrically complex castings that demand in-house mold-making capability.
- Precast Panels:Standardized sizing reduces on-site labor hours for infrastructure contractors. Saudi Building Code enforcement ties these products directly to municipal approval timelines.
- Support Structures:Structural backing formations and anchoring systems complete the envelope assembly. These components follow volume demand from the primary panel categories.
Today's leader: Facade Systems. Tomorrow's challenger: Decorative Elements.
Application:
Hospitality projects along the Red Sea coast are compressing procurement cycles, while commercial towers in Riyadh anchor specification discipline.
- Commercial Buildings:Riyadh's tower pipeline concentrates architect-driven procurement for fire-rated envelope systems. SASO technical regulations and municipal building codes impose the strictest compliance scrutiny here.
- Hospitality:Luxury resort developments require complex geometric facade systems that favor GRC's moldability. NEOM urban envelope mandates create demand for integrated thermal break performance.
- Residential Complexes:Jeddah luxury towers exhibit aggressive adoption of lifecycle carbon accounting for envelope materials. Sustainability consultants now embed in architect selection committees.
- Infrastructure Projects:Government agencies and mega-project developers drive standardized panel demand. SFDA material safety protocols elevate quality thresholds across this segment.
Commercial Buildings retain specification authority. Hospitality expands most quickly.
Installation Method:
Custom Fit commands architect loyalty for signature projects, while Cladding delivers contractor volume through repeatable installation protocols.
- Custom Fit:Parametrically optimized panel geometries demand responsive manufacturing infrastructure. ARTIC and similar suppliers differentiate through digital fabrication workflows tailored to architect-driven commercial projects in Riyadh and Jeddah.
- Cladding:Conventional envelope attachment methods serve mid-tier developments and infrastructure scale. Standardized anchoring reduces field labor risk for contractor procurement teams.
- Overlay:Retrofit applications apply GRC panels over existing substrates. This method serves building renovation and facade upgrade cycles.
- Modular:Factory-complete panel assemblies reduce site coordination complexity. Hybrid spray-premix production lines enable smaller fabricators to bid on geometrically demanding projects.
Custom Fit captures premium margin. Modular gains share fastest through production efficiency.
End User:
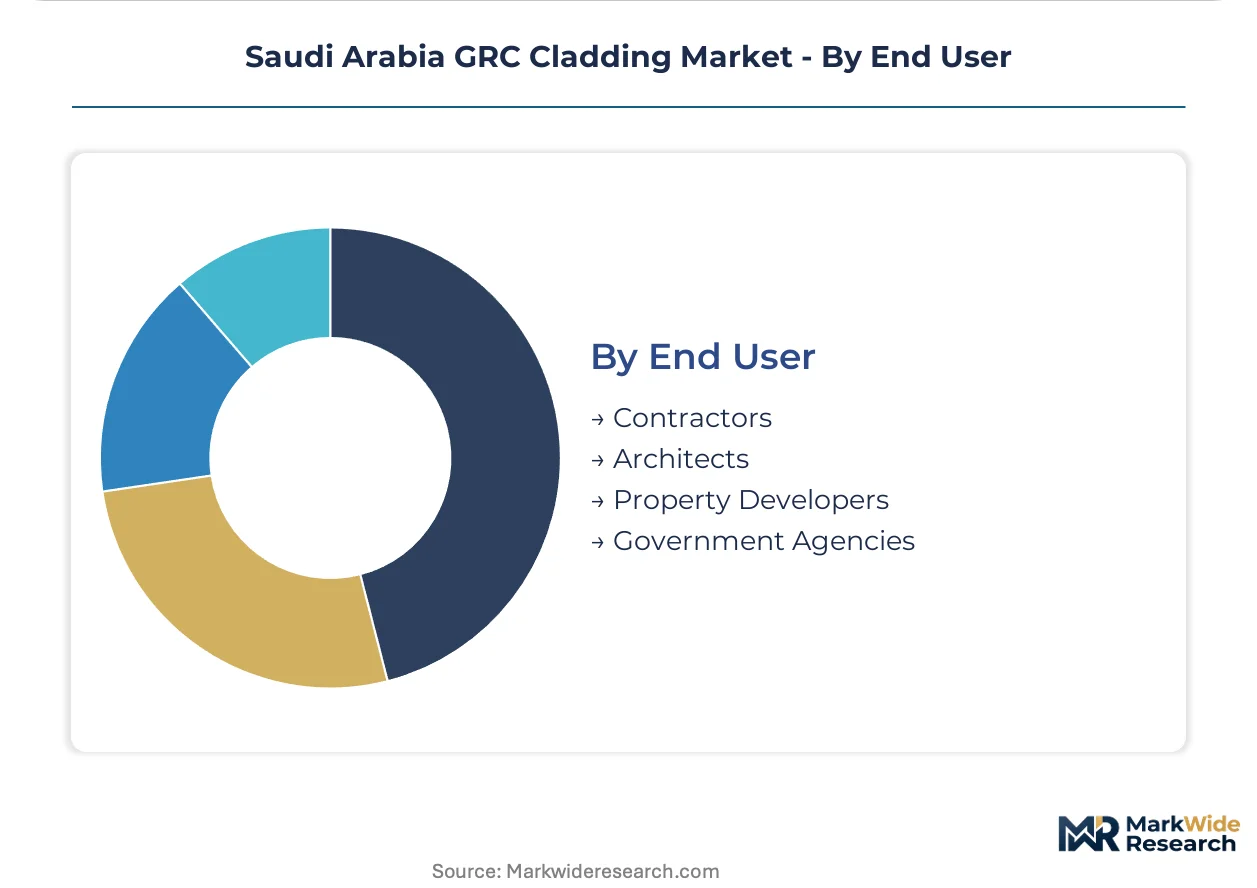
Architects control specification for high-value envelope contracts, while contractors execute procurement for standardized developments.
- Architects:These stakeholders specify parametrically optimized geometries and performance-based material requirements. Direct-to-contractor digital platforms are beginning to fragment their traditional influence over mid-size Riyadh developers.
- Contractors:Procurement teams bundle envelope specification with lifecycle carbon accounting. Spray-casting technician scarcity limits production ramp speed for new entrants serving this segment.
- Property Developers:Mega-project concentration along the Red Sea coast compresses procurement cycles for this group. PETRACO leverages manufacturing scale to supply their large-scale hospitality developments.
- Government Agencies:Public infrastructure and heritage restoration projects impose documentation burdens through SASO certification timelines. AlUla and Diriyah Gate contracts reward suppliers with in-house sculpting capability.
Architects hold specification power. Property Developers drive volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GRC cladding technology migrated from European construction markets into Saudi Arabia during the 1980s petroleum boom, establishing production footholds first in Jeddah's industrial corridor before diffusing inland toward Riyadh and the Eastern Province.
Riyadh
Central Region commercial towers concentrate specification authority for fire-rated facade systems. SASO technical regulations above 75 meters mandate third-party fire-performance testing, compressing supplier qualification windows. The King Abdullah Financial District anchors architect-driven procurement for complex envelope geometries.
Western Region
Jeddah luxury residential towers exhibit aggressive lifecycle carbon accounting for envelope materials. Sustainability consultants embed in architect selection committees, displacing price-per-panel bidding. The city's port infrastructure controls alkali-resistant glassfiber import channels, exposing fabricators to shipping delay concentration.
Eastern Province
Dammam municipal building codes impose localized wind-load requirements on coastal facade installations. Petrochemical sector investment sustains infrastructure-scale precast panel demand through standardized sizing protocols. Government agency procurement drives compliance documentation burdens.
NEOM Northwest
The linear city's urban envelope mandates create demand for fire-rated GRC systems with integrated thermal breaks. Mega-project concentration compresses procurement cycles, forcing suppliers to scale spray-casting capacity ahead of traditional demand signals. Heritage motif integration for AlUla restoration projects rewards in-house sculpting capability.
Red Sea Coast
Luxury resort developments require complex geometric facade systems that favor GRC moldability over precast concrete alternatives. Hospitality developers bundle envelope specification with embodied energy disclosure requirements. Diriyah Gate restoration contracts accelerate uptake of heritage-inspired decorative elements.
Saudi Arabia GRC Cladding Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Saudi Arabia's GRC cladding market, creating a bifurcated structure where integrated manufacturers with captive spray-casting facilities face pressure from specialized facade engineering consultancies. The supplier base concentrates around three strategic archetypes: scale-driven integrated producers serving mega-project hospitality pipelines, decorative specialists capturing heritage restoration contracts, and custom-fit fabricators targeting architect-driven commercial towers. Competitive moves center on SASO certification pre-positioning to capture municipal approval timeline advantages, and hybrid spray-premix production line investments to modularize geometric capability.
Among Saudi-based fabricators, Albitar Factory Co., PETRACO, and ARTIC occupy distinct positioning vectors within this structure. Albitar Factory Co. exemplifies the decorative specialist archetype through its established presence in high-end residential tower supply. PETRACO represents scale-driven integrated production capacity aligned with large-scale hospitality development procurement. ARTIC sits within the custom-fit tier, serving architect-driven commercial projects in Riyadh and Jeddah through responsive manufacturing infrastructure.
| Leading Market Players |
|---|
| Albitar Factory Co. |
| PETRACO |
| ARTIC |
| Station Contracting Co. Ltd |
| GRC Touch |
| Acementiat Factory |
| TUNSIF |
| Arabian Tile Company |
| DURRAKA |
| Others |
Value Network & Pricing Analysis
Red Sea hospitality developers' compressed procurement cycles for complex geometric facades are forcing GRC suppliers to pre-position spray-casting capacity and absorb upfront certification costs, compressing margins on early-mover contracts while creating pricing power for SASO-certified incumbents.
Pricing Analysis
Three-tier pricing structure across premium architect-specified, standard contractor-procured, and economy infrastructure-grade levels dominates the market. Price differentiation hinges on SASO fire-performance certification tier and volume scale, with certified premium panels commanding substantial premiums over uncertified alternatives. Cost compression in the standard tier is intensifying as curtain wall aluminum systems capture mid-tier commercial specifications. Contractors executing government infrastructure projects exhibit the highest price sensitivity, while Riyadh commercial tower architects prioritize performance over unit cost.
Supply Chain Analysis
Direct-to-contractor digital platforms and traditional distributor networks split downstream demand, with platforms capturing volume from mid-size Riyadh developers. Raw material sourcing draws from Saudi White Cement Company for aesthetic-grade binders, Jeddah port-controlled alkali-resistant glassfiber imports, and regional aggregates. Single-source vulnerability concentrates in specialty fiber supply through three import channels. Geographic production clusters anchor in Riyadh's industrial corridor, Jeddah's port-adjacent fabricators, and Dammam's petrochemical-linked facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO technical regulations mandating third-party fire-performance testing for facades above 75 meters compound competitive advantages for pre-certified suppliers, transforming compliance speed into a demand-generating asset.
For Market Incumbents: Acquire captive spray-casting technician training programs to lock in production scalability against emerging modular fabricators. Deepen backward integration into alkali-resistant glassfiber supply through Jeddah port warehousing partnerships to neutralize shipping delay risks from concentrated import channels.
For New Entrants and Emerging Players: Digital fabrication workflows for parametrically optimized panel geometries offer a technology-first wedge into Riyadh commercial tower specifications previously reserved for integrated producers. Target heritage motif sculpting capabilities for Diriyah Gate and AlUla restoration contracts where in-house mold-making differentiates against scale players.
For Investors and Strategic Acquirers: Asymmetric upside sits with custom-fit fabricators possessing responsive manufacturing infrastructure and established architect relationships in Riyadh and Jeddah. Long-term viability favors suppliers bridging digital design capability with hybrid spray-premix production modularity. Monitor NEOM urban envelope mandate enforcement as the critical inflection signal for fire-rated thermal break system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Pre-Positioning | Factory audit completion ahead of competitor submissions compresses municipal approval timelines for Riyadh towers. |
| Hybrid Spray-Premix Production Investment | Modular process separation enables smaller fabricators to bid on geometrically demanding Red Sea resort projects. |
| Heritage Sculpting Capability Development | In-house mold-making for Diriyah Gate and AlUla contracts captures premium decorative element margins. |
| Direct-to-Contractor Platform Launch | Digital procurement portals bypass distributor markups and fragment traditional architect influence over mid-size developers. |
| Alkali-Resistant Fiber Supply Securement | Jeddah port warehousing partnerships neutralize concentrated import channel risks for glassfiber reinforcement. |
Research Methodology
Coverage spans Saudi Arabia's Central, Western, and Eastern regions, with primary inputs from each territory's construction procurement clusters. Primary interviews with facade specification architects, contractor procurement managers, GRC fabrication plant engineers, and municipal building code enforcement officers combined with secondary validation from SASO technical regulation filings, Saudi Building Code amendments, and customs import records for alkali-resistant glassfiber. Bottom-up project pipeline aggregation and top-down construction sector macro indicators underwent triangulation for consistency.
Rate-of-change decomposition across the analysis window modeled product type segmentation by facade systems, decorative elements, precast panels, and support structures; application segmentation across commercial, hospitality, residential, and infrastructure; and installation method differentiation between custom fit, cladding, overlay, and modular approaches. CAGRs derived from project-level procurement timing, certification backlog estimates, and regional construction permit issuance patterns. Forecast inputs incorporated NEOM urban envelope mandate progression and Red Sea hospitality development phase commitments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SFDA material safety protocol amendments and white cement fuel subsidy adjustments. Forecasts reflect documented assumptions regarding SASO audit throughput capacity and spray-casting technician pipeline development. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Steel Sleepers Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Concrete and Cement Market
Building Materials
France Architectural Coatings Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Concrete Admixtures Market
Building Materials
Rapid Strength Concrete Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Fiber Cement Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Composite Decking and Railing Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Roofing and Tile Underlayment Market