
 United States Commercial Construction Market | 2026-2036
United States Commercial Construction Market Size, Share, and Industry Trends Forecast 2026-2036
United States Commercial Construction Market Analytics
Data center construction is realigning the United States commercial construction market as hyperscale cloud operators expand infrastructure across the Sun Belt. Turner Construction Company leverages its institutional scale to dominate mission-critical facility builds. Bechtel Corporation anchors its position through upstream control over complex engineering and procurement cycles. Hensel Phelps specializes in design-build delivery for technology and healthcare clients.
United States commercial construction encompasses the planning, design, and assembly of non-residential structures using concrete, steel, and engineered wood systems with specified load ratings and fire-resistance ratings for occupancy safety. The primary purpose spans enabling commerce, logistics, healthcare delivery, and public administration through purpose-built physical assets. Office and industrial building types capture divergent trajectories as remote work dampens speculative office starts while logistics and manufacturing facilities absorb record capital commitments. Sustainable construction methods gain share against traditional stick-built approaches as energy codes tighten and tenant ESG mandates filter into lease requirements. Modular and precast methods compete on speed-to-occupancy for repetitive building typologies like hotels and distribution centers.
OSHA workplace safety standards, the EPA's Clean Air Act permitting for large developments, and the Inflation Reduction Act's clean building tax incentives collectively reshape project economics and compliance costs across the United States. Local zoning boards and state environmental review processes add jurisdictional friction that extends pre-construction timelines in dense metropolitan areas. Stakeholders must monitor evolving federal energy efficiency benchmarks and their interplay with state-level stretch codes to anticipate where building cost premiums will concentrate and which contractor capabilities will command pricing power.
Market Dynamics
The Inflation Reduction Act's clean building tax incentives are redirecting capital flows toward energy-efficient retrofits and low-carbon manufacturing facilities, compressing project timelines for contractors with certified green construction capabilities.
Growth Catalysts
- Data Center Demand:Hyperscale cloud operators are expanding infrastructure across Texas, Arizona, and Georgia, driving demand for mission-critical facility construction with specialized power and cooling requirements.
- IRA Tax Incentives:The Inflation Reduction Act's clean building deductions and manufacturing facility credits are accelerating capital deployment into energy-efficient commercial assets and industrial retrofits.
- Mass Timber Engineering:Cross-laminated timber and glulam systems are gaining code approval for mid-rise commercial structures, enabling faster erection schedules and carbon-sequestering building envelopes.
Market Restraints
- Electrical Equipment Lead Times:Transformers and switchgear face 52-78 week delivery cycles from concentrated Asian and European foundry capacity, delaying project energization.
- OSHA Compliance Burden:Enhanced workplace safety enforcement and record-keeping requirements are elevating administrative overhead and insurance premiums for general contractors.
- Remote Work Impact:Persistent office vacancy rates above historical norms are suppressing speculative Class-A office starts in gateway metropolitan markets.
Strategic Opportunities
- Battery Manufacturing Facilities:Domestic electric vehicle supply chain investments are creating demand for cleanroom-grade industrial construction with hazardous material containment systems.
- Design-Build Consolidation:Single-source delivery models are capturing share from traditional design-bid-build procurement, rewarding contractors with in-house architectural and engineering capabilities.
- Sun Belt Logistics Corridors:Inland port and distribution hub development along Interstate 35 and Interstate 10 corridors offers volume growth as e-commerce fulfillment networks densify.
Industry Challenges
- Skilled Trades Shortage:Electricians, HVAC technicians, and certified welders are exiting the workforce faster than apprenticeship programs replenish supply, compressing field productivity.
- Permitting Timeline Volatility:Local zoning boards and state environmental review processes are extending pre-construction phases by 8-14 months in dense coastal metropolitan areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Commercial Construction Market |
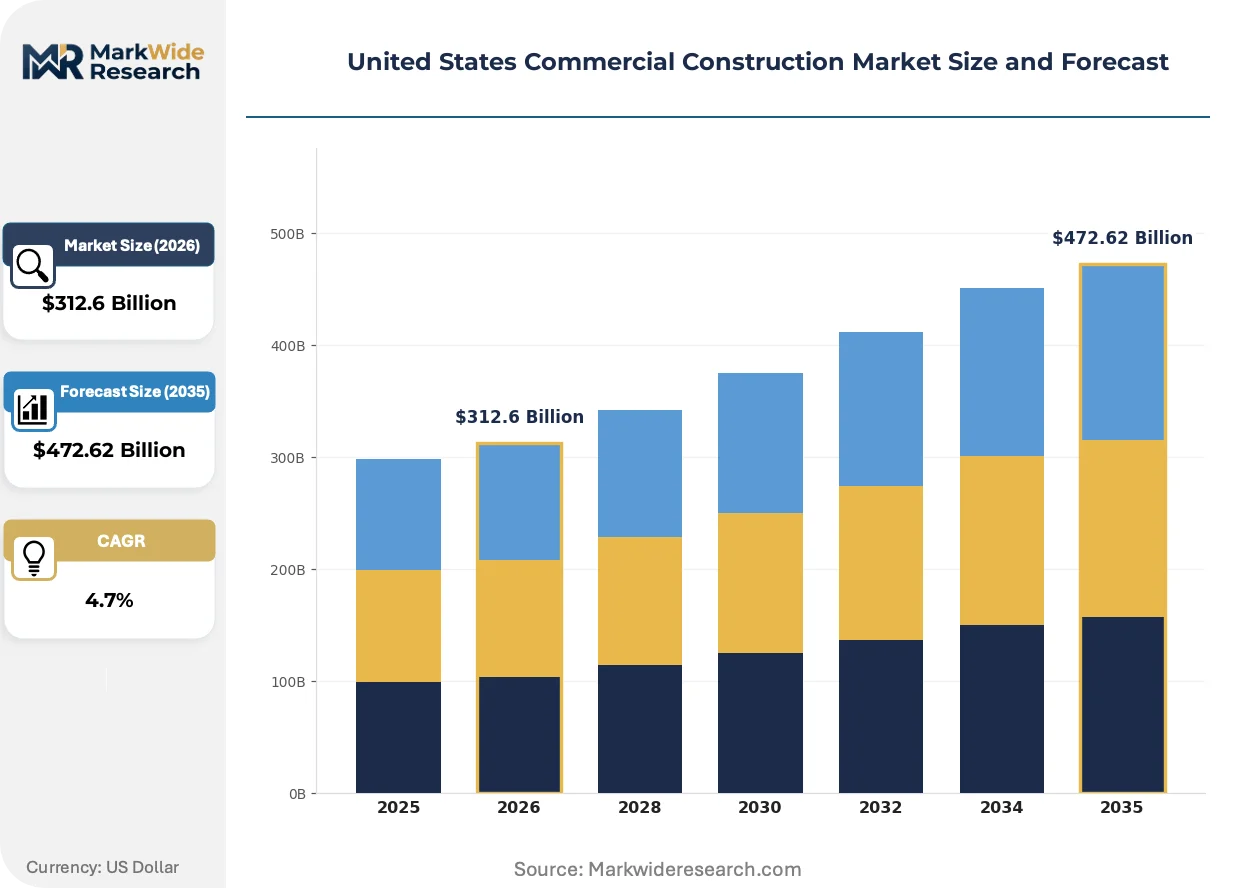
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Office, Retail, Hospitality, Industrial Construction Method: Traditional, Modular, Precast, Sustainable End User Sector: Corporate, Educational, Healthcare, Government Service Type: Design, Project Management, General Contracting, Renovation |
| Companies Covered | DPR Construction, STO Building Group, Turner Construction Company, Brasfield & Gorrie LLC, Fluor Corporation, Bechtel Corporation, MasTec Inc., Hensel Phelps, Kiewit Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Commercial Construction Market Evolving Landscape
Digital fabrication and modular assembly methods are compressing field construction schedules while federal energy mandates are embedding carbon accounting into project specifications.
Cross-laminated timber is expanding into mid-rise commercial and institutional buildings as engineered wood products achieve two-hour fire-resistance ratings under updated International Building Code provisions. Hospitality and education developers are specifying mass timber systems for 6-12 story structures to accelerate enclosure schedules and meet tenant carbon disclosure requirements. This material transition is expanding into markets previously dominated by steel and concrete structural frames.
The EPA's Clean Air Act permitting requirements for large commercial developments are tightening emissions thresholds for construction equipment and material transport logistics. Projects exceeding 25,000 square feet in non-attainment zones now face mandatory low-NOx equipment specifications and dust suppression protocols. Industrial and data center developers in California and Texas metropolitan areas are absorbing compliance premiums to maintain construction schedule certainty.
Owner-operators are consolidating vendor relationships through multi-project alliance contracts that bundle design, construction, and facility management under single-accountability frameworks. Healthcare systems and technology companies are displacing transactional bidding with long-term partnership agreements that emphasize lifecycle cost optimization over first-cost minimization. This procurement evolution is most visible in Texas and Georgia where repeat-client contractors are capturing sequential campus expansion work.
United States Commercial Construction Market Segmentation
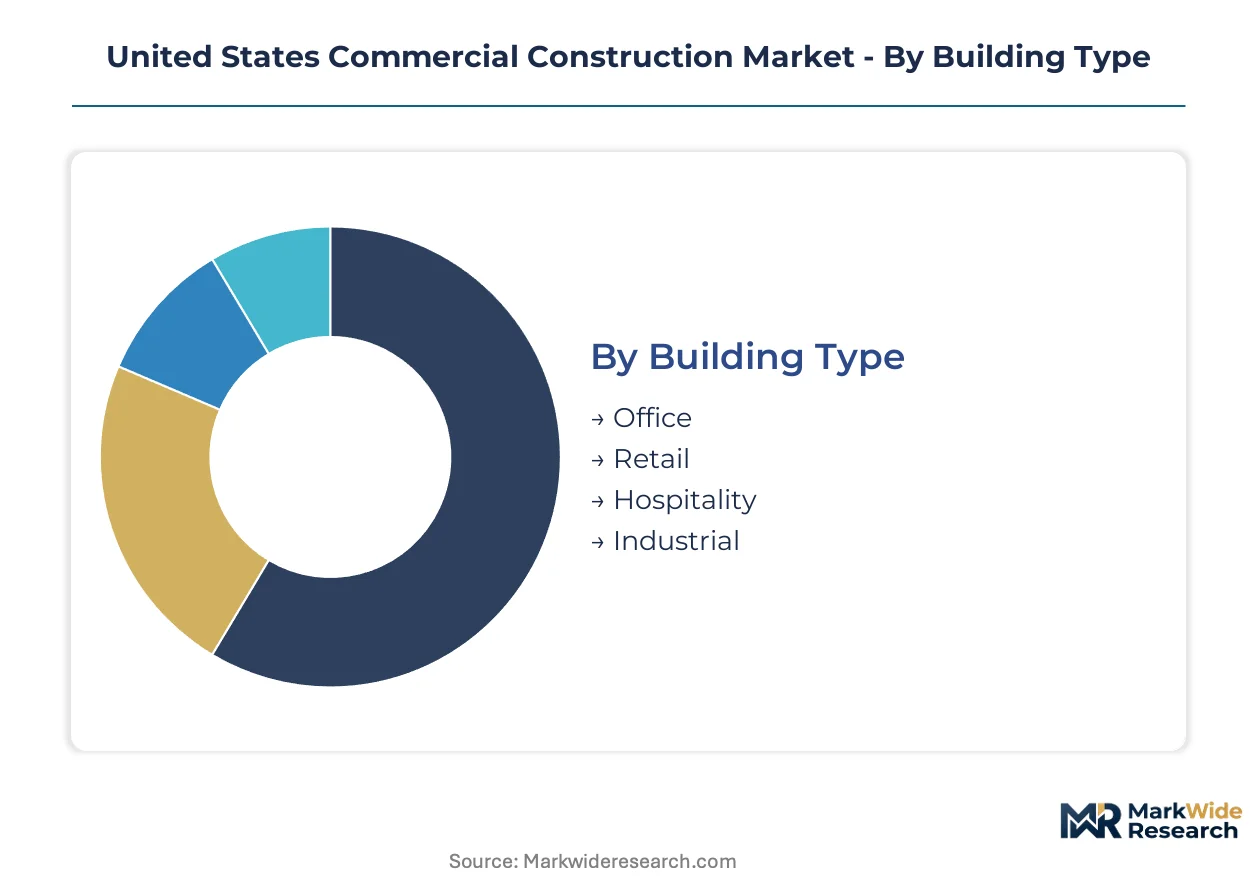
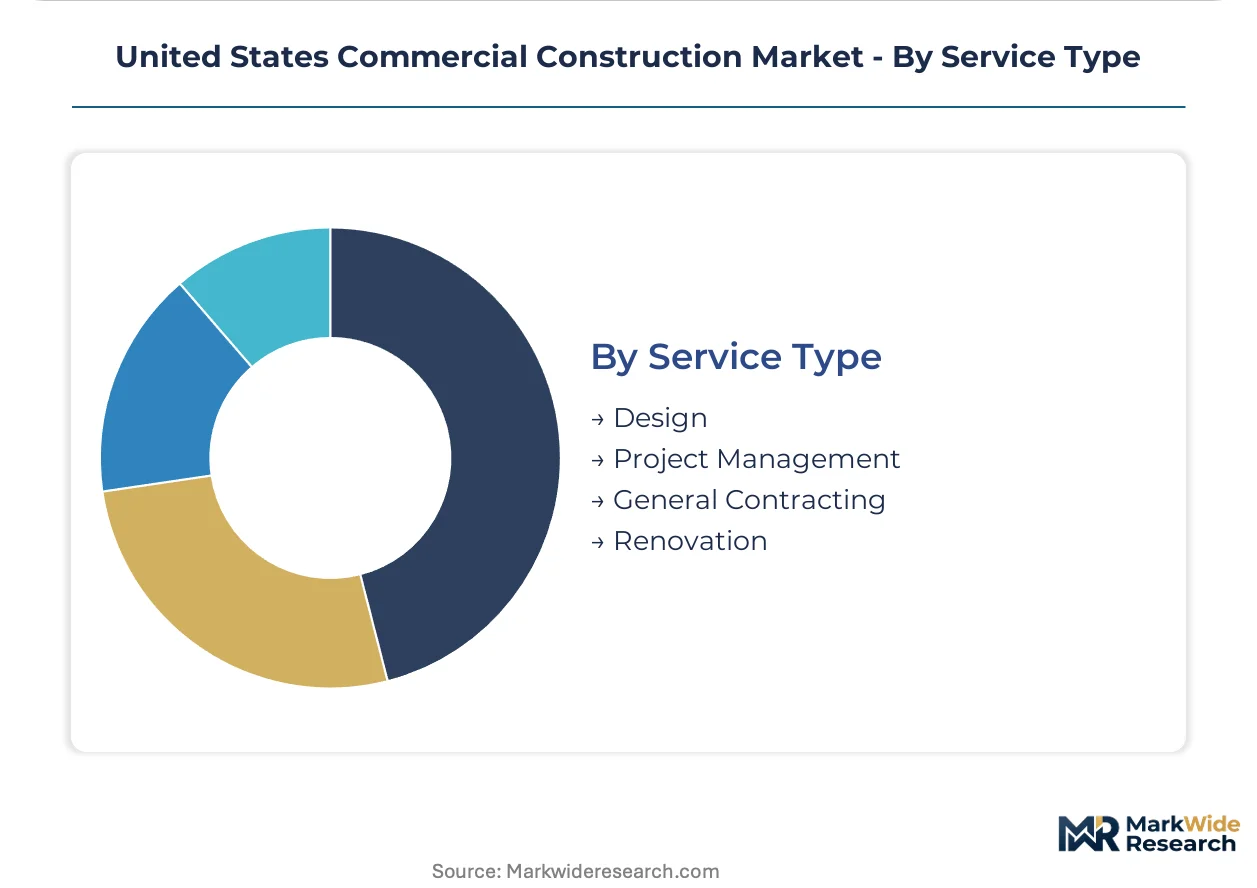
Commercial construction segmentation reveals how capital allocation priorities diverge across building typologies, delivery methods, and client sectors. Contractors must align capability investments with the specific technical and procurement demands of each category to capture pricing power in concentrated growth corridors.
Building Type:
Buyers in this category differentiate by occupancy density, power infrastructure requirements, and tenant credit quality rather than construction cost alone.
- Office:Class-A speculative developments in gateway metros face elevated vacancy headwinds as remote work persists, compressing starts in Manhattan, San Francisco, and Chicago while selective build-to-suit activity continues for life science and technology tenants in Austin and Raleigh-Durham.
- Industrial:Logistics facilities and manufacturing campuses absorb record capital commitments across the Sun Belt, with data center-adjacent warehousing and battery manufacturing plants driving square footage expansion in Phoenix, Dallas-Fort Worth, and Atlanta.
- Retail:Grocery-anchored neighborhood centers and last-mile fulfillment nodes dominate ground-up activity as enclosed mall construction remains dormant.
- Hospitality:Select-service hotel prototypes utilizing modular guestroom construction are recovering in suburban and interstate-adjacent locations.
Volume sits with Industrial; growth tilts toward specialized logistics and clean manufacturing subtypes.
Construction Method:
Cost tier separation determines competitive positioning, with premium methods commanding schedule certainty premiums and economy approaches competing on first-cost minimization.
- Traditional:Stick-built and cast-in-place concrete systems retain dominance in complex, one-off structures where design flexibility outweighs speed-to-market, though labor scarcity and extended electrical equipment lead times are eroding schedule predictability.
- Sustainable:Mass timber cross-laminated timber and glulam systems are gaining International Building Code approval for mid-rise commercial structures, enabling carbon-sequestering envelopes that satisfy tenant ESG mandates and accelerate enclosure in 6-12 story hospitality and education projects.
- Modular:Volumetric prefabrication compresses field schedules for repetitive building typologies including hotels, dormitories, and distribution center offices.
- Precast:Concrete panel systems deliver weather-tight envelopes for parking structures, warehouses, and institutional buildings with reduced on-site labor exposure.
Traditional methods retain volume dominance; sustainable and modular approaches are climbing the fastest as energy codes tighten and skilled trades shortages deepen.
End User Sector:
Procurement sophistication varies sharply, with corporate and healthcare buyers demanding lifecycle cost optimization while government and educational clients navigate extended public funding cycles.
- Corporate:Technology and financial services firms are consolidating vendor relationships through multi-project alliance contracts that bundle design, construction, and facility management under single-accountability frameworks, displacing transactional bidding in Texas and Georgia campus expansions.
- Healthcare:Hospital systems prioritize infection control, redundant mechanical systems, and 24/7 operational continuity, driving demand for design-build delivery with integrated commissioning protocols.
- Government:Federal and state facilities face extended appropriations timelines and prevailing wage requirements under Davis-Bacon Act enforcement.
- Educational:K-12 and university capital programs concentrate in bond-funded districts across Florida, Texas, and North Carolina.
Healthcare and corporate sectors concentrate premium-margin opportunity; government work offers volume stability with compressed margins.
Service Type:
Margin structure and client retention dynamics separate full-service integrated providers from specialized discipline contractors.
- General Contracting:Hard-bid and negotiated construction management at-risk delivery models capture the majority of commercial square footage, with self-perform capabilities in concrete, steel, and MEP trades differentiating tier-one contractors.
- Project Management:Owner-representative services are expanding as institutional developers internalize development expertise and require third-party oversight of complex, multi-prime data center and industrial builds.
- Design:Architectural and engineering disciplines face margin pressure from in-house capability expansion at large contractors and technology-enabled design automation.
- Renovation:Energy-efficient retrofit activity is accelerating under Inflation Reduction Act tax incentives, with HVAC electrification and envelope upgrades dominating commercial building improvement pipelines.
General contracting commands volume leadership; project management and renovation services are expanding most quickly as project complexity and capital allocation to existing stock intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sun Belt absorbs disproportionate construction investment relative to legacy coastal markets, while Midwest manufacturing corridors and Pacific technology hubs sustain specialized demand pockets. Federal infrastructure spending and state-level tax incentives are redistributing project pipelines across sub-regional economies.
Texas
Hyperscale data center campuses and battery manufacturing facilities are consuming industrial land in Dallas-Fort Worth and Austin. The Texas Enterprise Fund awards performance-based grants for capital-intensive projects exceeding $50 million in qualified investment. Houston's energy corridor is pivoting toward carbon capture and hydrogen hub construction as legacy oil headquarters consolidate.
Arizona
Phoenix and Tucson are attracting semiconductor fabrication and supporting supplier construction under the CHIPS and Science Act. Arizona Commerce Authority tax credits reduce state corporate income tax liability for qualifying capital investments. The West Valley logistics corridor along Interstate 10 is densifying with cold storage and e-commerce fulfillment centers.
Georgia
Atlanta's northern suburbs and Savannah port hinterland are absorbing record industrial square footage for electric vehicle supply chain manufacturing. Georgia Department of Economic Development discretionary incentives target clean energy manufacturing facilities with payroll and investment thresholds. The Savannah Harbor deepening project is unlocking bulk cargo terminal construction along the lower Savannah River.
California
Life science buildouts in South San Francisco and San Diego are offsetting subdued speculative office construction. California Energy Commission Title 24 energy code updates mandate all-electric new construction in select jurisdictions by 2026. The Central Valley inland port network is expanding refrigerated warehouse capacity for agricultural export logistics.
Florida
Miami-Dade and Orlando are concentrating hospitality and healthcare construction as population inflows sustain demographic demand. Florida Department of Transportation infrastructure bonding is accelerating interchange and arterial improvements supporting commercial development. The I-4 corridor between Tampa and Orlando is emerging as a distribution hub alternative to saturated Southeast Atlantic ports.
United States Commercial Construction Market Competitive Landscape
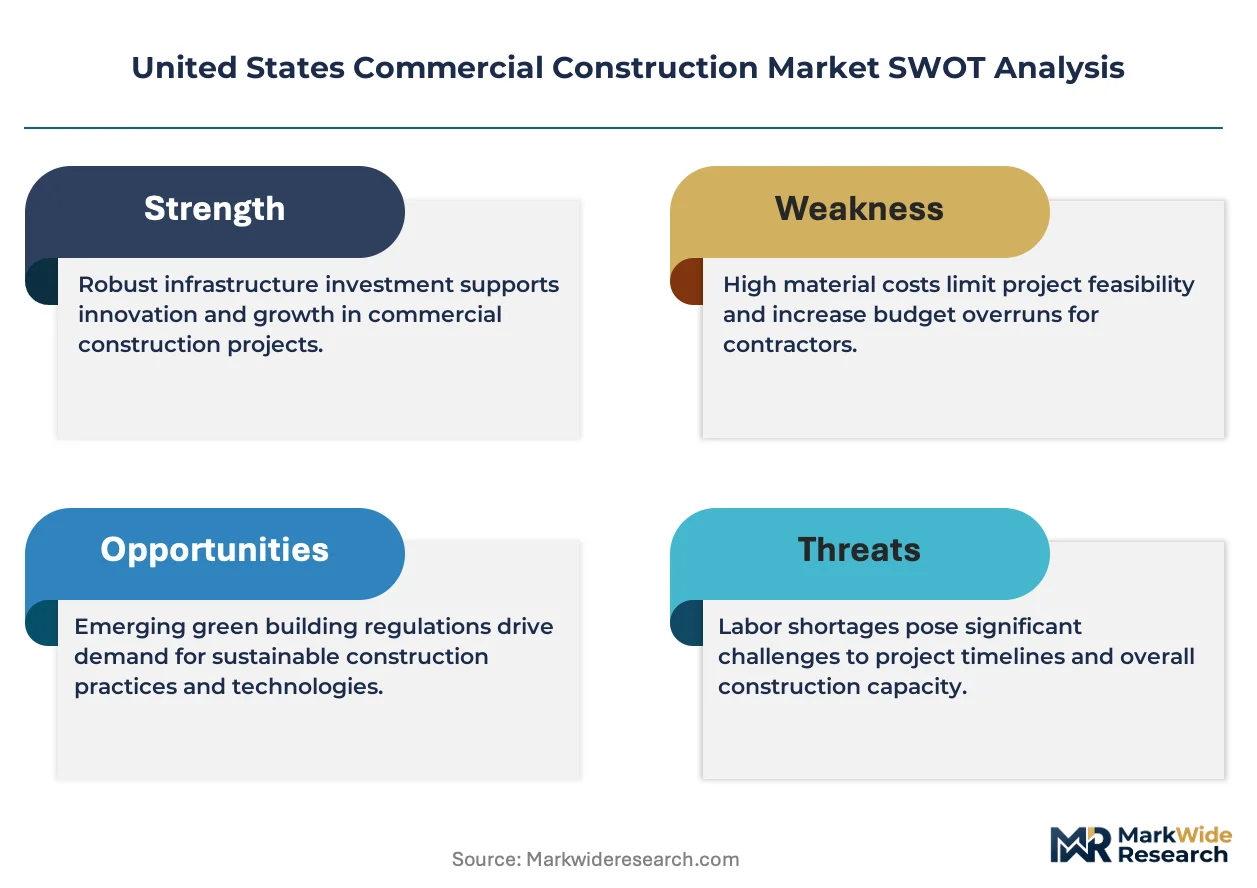
Top-tier vendors anchor mission-critical and complex industrial segments, while mid-tier regional contractors compete on speed-to-market for repetitive building typologies. The vendor base stratifies across three capability tiers: integrated design-build operators with self-perform trades, specialized technology facility contractors, and regional generalists with local entitlement relationships. Consolidation pressure is intensifying as repeat-client alliance contracts favor scale and balance sheet depth over transactional bidding.
Within the integrated tier, Turner Construction Company and Bechtel Corporation exemplify divergent positioning—Turner leveraging institutional scale for data center and healthcare campus delivery, Bechtel anchoring complex engineering-procurement-construction cycles for industrial and infrastructure clients. Hensel Phelps occupies a position between these archetypes with design-build specialization for technology and mission-critical facilities. Regional strength concentrates with DPR Construction and STO Building Group, both representing the California-origin contractor model that has expanded nationally through repeat technology and healthcare relationships.
| Leading Market Players |
|---|
| DPR Construction |
| STO Building Group |
| Turner Construction Company |
| Brasfield & Gorrie LLC |
| Fluor Corporation |
| Bechtel Corporation |
| MasTec Inc. |
| Hensel Phelps |
| Kiewit Corporation |
| Others |
Value Network & Pricing Analysis
Steel and concrete input costs cascade through project pricing tiers as contractors absorb volatile commodity swings and extended electrical equipment procurement cycles. Labor scarcity in certified trades compresses margins on fixed-price contracts while design-build operators capture schedule certainty premiums.
Pricing Analysis
Margin tightening in negotiated construction management reflects skilled trades shortages and 52-78 week transformer lead times. Three-tier pricing structure across premium design-build, standard construction management, and economy hard-bid procurement segments separates schedule-certain delivery from cost-minimized alternatives. Price differentiation rests on LEED certification tier and self-perform capability depth. Cost compression accelerates in speculative industrial as capital deployment concentrates in data center-adjacent warehousing. Government and educational buyers exhibit highest price sensitivity; corporate technology clients prioritize lifecycle cost over first-cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Asian and European foundry capacity for medium-voltage switchgear and power transformers. Supply draws from China, Germany, and South Korea for electrical distribution equipment, with domestic steel mills and regional concrete batch plants anchoring structural material flows. Raw material dependencies center on copper cathode, Portland cement, and engineered lumber products. Tariff exposure on Chinese electrical components elevates landed cost unpredictability. Distribution runs through manufacturer-direct procurement for mission-critical power infrastructure and regional distributor networks for commodity construction materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States commercial construction market occupies a material-transition phase as mass timber engineering displaces conventional steel and concrete structural systems in mid-rise applications.
For Market Incumbents: Acquire specialized electrical infrastructure installation capabilities to capture data center and battery manufacturing facility premiums. Consolidate design-build talent in Texas and Georgia to defend repeat-client relationships against emerging regional specialists. Threat from modular construction entrants and OSHA compliance cost escalation demands backward integration into prefabrication or certified safety programs as defensive positioning. For New Entrants and Emerging Players: Launch via alliance contracting models targeting healthcare system campus expansions in Florida and North Carolina. White-space opportunity concentrates in renovation services for Inflation Reduction Act-funded energy retrofits and mass timber structural engineering for 6-12 story hospitality prototypes. Go-to-market angle emphasizes speed-to-occupancy guarantees against traditional construction schedules. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale design-build contractors with Sun Belt entitlement relationships in Texas and Arizona. Long-term viability over a decade horizon hinges on exposure to data center and clean manufacturing capital deployment trajectories rather than speculative office development. Signal to watch: CHIPS Act and IRA incentive renewal debates as policy inflection indicators for industrial construction pipeline durability.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Timber Capability Investment | Captures carbon-sequestering building envelope demand from hospitality and education developers under tightened energy codes. |
| Electrical Infrastructure Self-Performance | Insulates margin from transformer lead time volatility and positions for mission-critical facility premiums. |
| Alliance Contracting Expansion | Displaces transactional bidding with lifecycle accountability frameworks favored by corporate and healthcare clients. |
| Sun Belt Geographic Concentration | Aligns capacity with data center, battery manufacturing, and logistics corridor investment flows across Texas and Georgia. |
| Green Certification Program | Qualifies contractors for Inflation Reduction Act tax incentive projects and LEED-driven tenant procurement mandates. |
Research Methodology
Multi-period observation of construction starts, permit issuance, and capital expenditure commitments anchored the trend analysis, supplemented by interviews with general contractors, project developers, MEP engineering principals, and facility owner-operators. Secondary validation drew from Census Bureau construction spending reports, Dodge Data & Analytics project tracking, EPA Clean Air Act permit databases, and OSHA enforcement records. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic scenario modeling.
Input-output matrices structured demand forecasting across building type, construction method, end user sector, and service type dimensions over the projection horizon. CAGRs derived from regression analysis against fixed investment, employment, and interest rate variables. Industry-specific inputs included hyperscaler data center capex disclosures, CHIPS Act facility announcement tracking, and Inflation Reduction Act tax credit utilization patterns.
The model assumes a particular technology adoption path; alternative pathways for mass timber engineering penetration or modular construction cost parity would alter the outlook. Forecasts embed assumptions regarding federal incentive continuity, skilled trades workforce replenishment, and electrical equipment supply normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
India Commercial Construction Market
Building Construction
India Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
Egypt Construction Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Scandinavia Construction Market
Building Construction
Japan Construction Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
GCC Cement Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
GCC Construction Market
Building Construction
Guatemala Construction Market
Building Construction
Poland Construction Market
Building Construction
France Prefab Homes Market
Building Construction
US Offsite Construction Market