
 Commercial Aircraft Disassembly Dismantling and Recycling Market | 2026-2036
Commercial Aircraft Disassembly Dismantling and Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Disassembly Dismantling and Recycling Market Intelligence
The southwestern United States is fragmenting as legacy teardown yards in Arizona compete with emerging capacity in New Mexico and Texas. TARMAC Aerosave leverages its French and Spanish facilities to dominate European end-of-life aircraft intake. GA Telesis LLC anchors its competitive position through vertical integration from disassembly into certified parts distribution. CAVU Aerospace specializes in narrow-body teardown programs and competes aggressively on turnaround speed.
Commercial aircraft disassembly, dismantling and recycling encompasses the systematic deconstruction of retired airframes to recover serviceable components, segregate hazardous materials, and reclaim metallic and composite feedstocks through processes including plasma cutting and robotic extraction. The primary purpose centers on converting end-of-life aviation assets into reusable parts and raw materials while ensuring environmental compliance through regulated hazardous waste disposal. Engine overhaul and parts refurbishment command the deepest margin pools due to OEM traceability requirements and airworthiness certification value. Component salvage represents the highest-volume service category as airlines prioritize engine and landing gear recovery from parked fleets. Material recovery in aluminum and titanium alloys is accelerating fastest as smelters develop aviation-grade recycling streams to bypass virgin metal premiums.
The FAA governs airworthiness documentation for recycled components through its parts certification framework, while the EPA enforces hazardous waste disposal protocols affecting solvent and coating handling at US dismantling sites. The EU's REACH regulation and F-Gas Directive constrain material processing methods and refrigerant recovery obligations across European teardown facilities. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple jurisdictions reshape liability allocation between lessors, airlines, and dismantlers.
Market Dynamics
Wide-body retirement waves are concentrating teardown demand at desert storage sites, while REACH and F-Gas compliance costs are filtering smaller European dismantlers from the competitive set.
Growth Catalysts
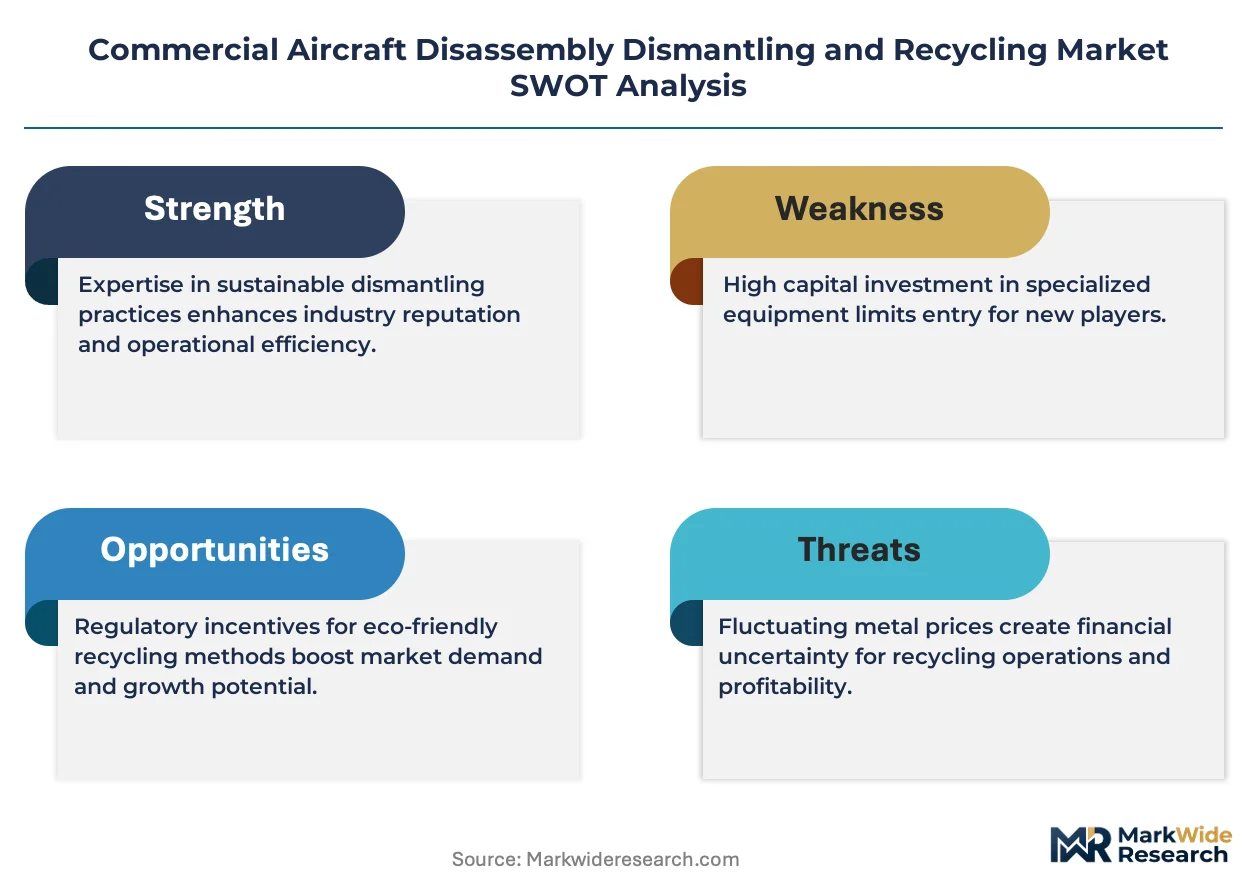
- EU material traceability mandates:The EU Aircraft Dismantling and Recycling Association's protocols are forcing facility upgrades that favor accredited operators with capital reserves.
- Aluminum-titanium alloy recovery:Aviation-grade smelters in Germany and France are developing closed-loop streams that bypass virgin metal premiums for aerospace feedstock.
- Arizona-California dismantling clusters:Proximity to desert boneyards at Mojave and Pinal Airpark reduces transport costs for airframe intake.
Market Restraints
- Specialized labor scarcity:Certified airframe technicians command wage premiums that compress margins at independent dismantling yards.
- Hazardous waste handling costs:EPA solvent and coating disposal protocols add fixed compliance burdens that scale poorly for low-volume operators.
- OEM traceability gatekeeping:Engine and landing gear documentation requirements limit parts resale to certified refurbishment networks.
Strategic Opportunities
- Composite carbon fiber reclamation:Pyrolysis and solvolysis methods are maturing to recover fibers from retired Boeing 787 and Airbus A350 structures.
- Indian subcontinent MRO integration:Hyderabad and Bangalore maintenance clusters are adding teardown capacity to capture adjacent parts refurbishment revenue.
- Extended producer responsibility frameworks:Emerging liability allocation rules in France and Germany are positioning lessors to pre-fund end-of-life processing.
Industry Challenges
- Parts provenance documentation:FAA Form 337 and EASA release certificates require paper trails that many aging fleets lack, blocking resale.
- Robotic dismantling capex:Automated plasma cutting and extraction systems demand upfront investment that stretches payback periods beyond five years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Disassembly Dismantling and Recycling Market |
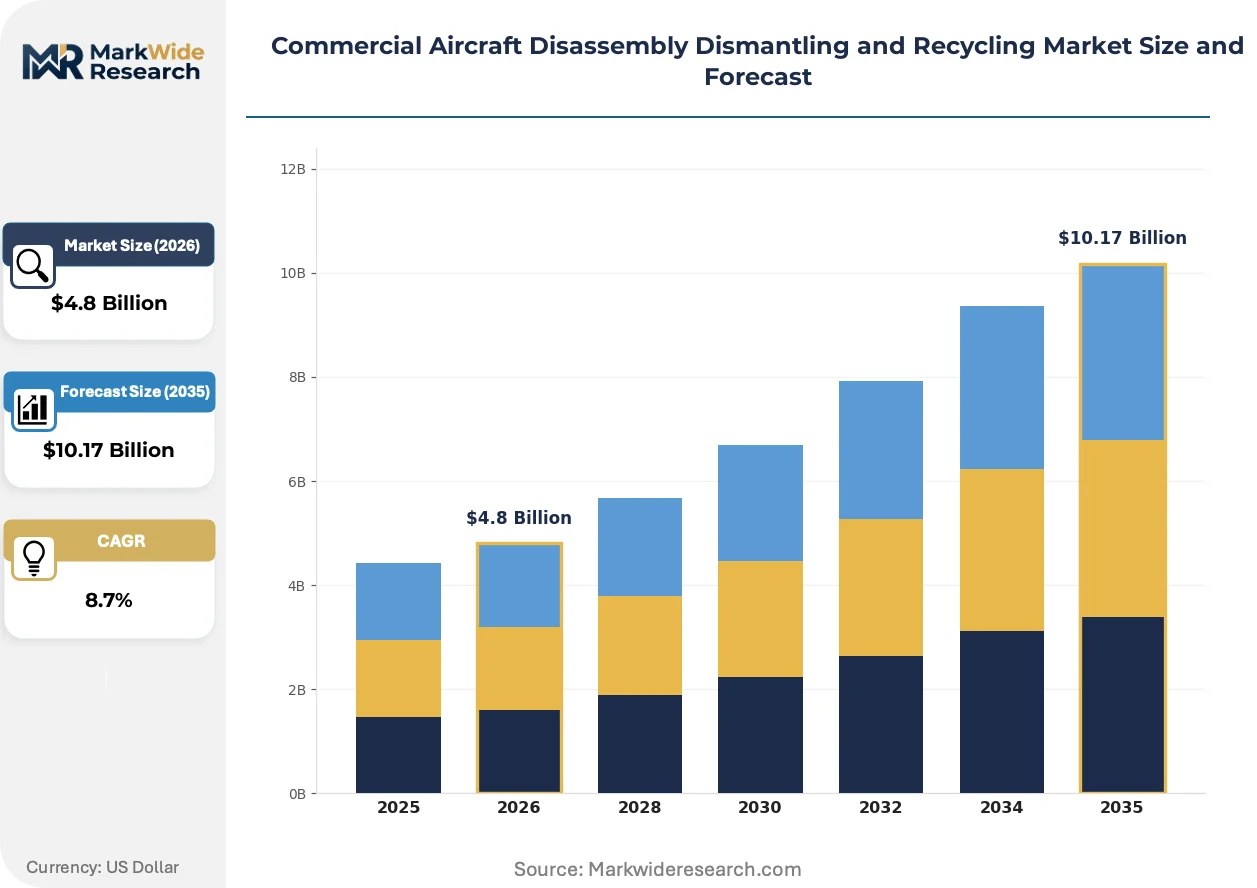
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Component Salvage, Engine Overhaul, Material Recovery, Parts Refurbishment, Hazardous Waste Disposal End User: Airlines, MRO Providers, OEMs, Recycling Facilities, Leasing Companies Disassembly Technique: Manual Dismantling, Automated Disassembly, Robotic Extraction, On-site Deconstruction, Plasma Cutting Recycled Material Type: Aluminum, Titanium Alloys, Composites, Steel, Copper, Plastics |
| Companies Covered | TARMAC Aerosave, Air Salvage International Ltd, CAVU Aerospace, Aircraft End-of-Life Solutions (AELS) BV, GA Telesis LLC, Eirtrade Aviation, Vallair, Aerocycle, Ecube, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Disassembly Dismantling and Recycling Market Strategic Shifts & Innovations
Digital material passports and automated sorting systems are compressing teardown cycle times while regulatory pressure on refrigerant and composite waste is reshaping facility design standards.
Robotic plasma cutting systems are collapsing manual labor requirements in airframe sectioning. Tier-one dismantlers in Spain and the United States are deploying articulated arms with machine-vision guidance to extract titanium structural elements. The technology is collapsing turnaround timelines from ninety days to under forty-five for narrow-body programs.
REACH Annex XVII restrictions on chromium and cadmium coatings are mandating substitute surface treatments for recovered components. European teardown facilities must now segregate legacy hexavalent chromium parts before smelting. The regulation is compressing margins at Dutch and German yards that lack dedicated hazardous material lines.
Airlines are unbundling end-of-life asset management from traditional lessor agreements. Carriers now contract directly with dismantlers for guaranteed buyback values on retired engines and auxiliary power units. This behavior is most visible among US legacy carriers with aging A320ceo and 737-800 fleets parked at desert storage sites.
Commercial Aircraft Disassembly Dismantling and Recycling Market Segmentation
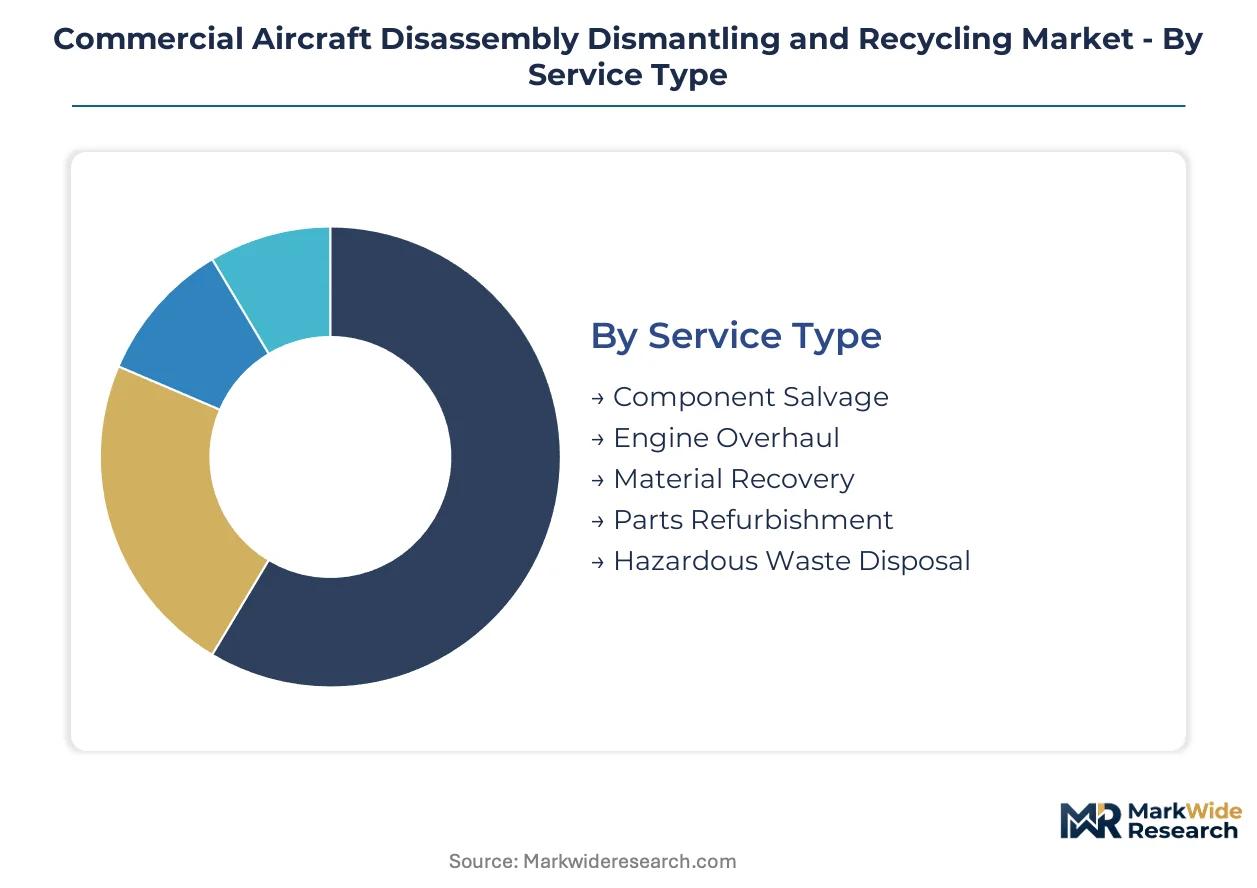
Segmentation in aircraft teardown services reveals stark divergences in capital intensity, cycle times, and margin profiles. Understanding these structural differences separates high-return operators from commodity players competing on volume alone.
Service Type:
Component salvage and engine overhaul compress turnaround windows to under sixty days for narrow-body programs, while material recovery and hazardous waste disposal stretch across ninety to one hundred twenty days due to regulatory documentation burdens.
- Component Salvage:Recovery of avionics, landing gear, and flight control surfaces demands FAA Form 337 traceability for each serial-numbered unit. Airlines at Arizona desert boneyards prioritize this service to monetize parked A320ceo and 737-800 fleets before lease returns trigger penalties.
- Engine Overhaul:Turbofan teardown and module refurbishment command premium pricing tied to OEM airworthiness release certificates. German and French aviation-grade smelters feed closed-loop aluminum-titanium streams that bypass virgin metal premiums for aerospace feedstock recovery.
- Material Recovery:Metallic and composite feedstock reclamation through plasma cutting and mechanical shredding.
- Parts Refurbishment:Component reconditioning to serviceable status for secondary market distribution.
- Hazardous Waste Disposal:EPA-regulated solvent, coating, and refrigerant handling with fixed compliance burdens.
Component salvage dominates installed base. Material recovery is where expansion concentrates.
End User:
Airlines and leasing companies drive teardown contracting through direct asset ownership, while MRO providers and OEMs capture margin through refurbishment networks and traceability gatekeeping.
- Airlines:Legacy carriers with aging wide-body fleets unbundle end-of-life management from lessor agreements to secure guaranteed buyback values on engines and APUs. US carriers at Mojave and Pinal Airpark sites now contract directly with dismantlers.
- MRO Providers:Maintenance clusters in Hyderabad and Bangalore add teardown capacity to capture adjacent parts refurbishment revenue from narrow-body programs.
- OEMs:Original equipment manufacturers control certification pathways for recovered components.
- Recycling Facilities:Smelters and material processors handling aviation-grade alloy streams.
- Leasing Companies:Lessors pre-funding end-of-life processing under emerging extended producer responsibility frameworks in France and Germany.
Airlines dominate installed base. MRO providers are where expansion concentrates.
Disassembly Technique:
Capital requirements stratify sharply: manual dismantling employs certified airframe technicians at wage premiums, while robotic extraction and automated systems demand five-year payback horizons on plasma cutting and machine-vision installations.
- Manual Dismantling:Labor-intensive airframe sectioning by certified technicians preserves component integrity for high-value avionics and landing gear recovery.
- Automated Disassembly:Programmable machinery for repetitive structural cutting tasks.
- Robotic Extraction:Articulated arms with machine-vision guidance collapse turnaround timelines from ninety days to under forty-five for narrow-body programs at tier-one facilities in Spain and the United States.
- On-site Deconstruction:Mobile teardown operations at desert storage locations.
- Plasma Cutting:Thermal sectioning for titanium structural elements and alloy recovery.
Manual dismantling dominates installed base. Robotic extraction is where expansion concentrates.
Recycled Material Type:
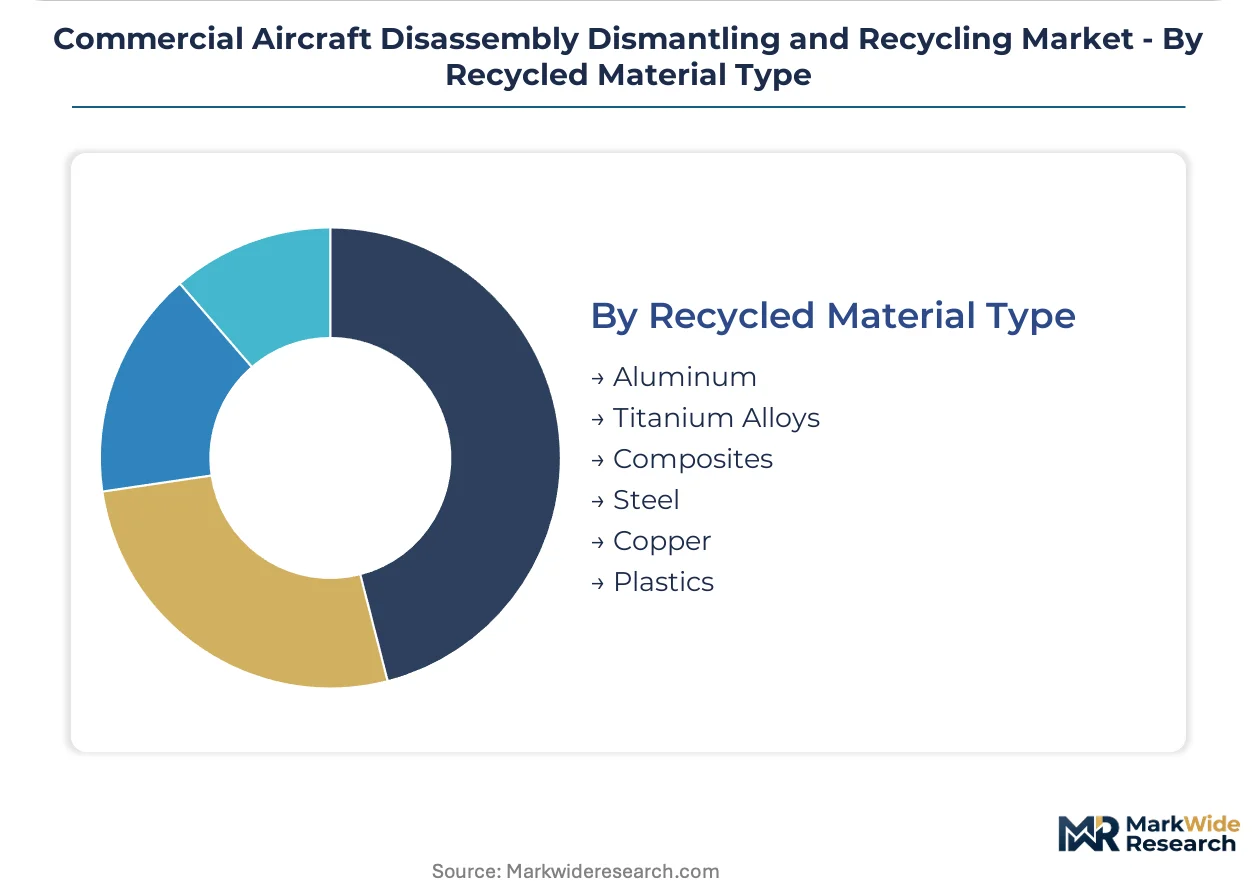
Aluminum and titanium alloys flow fastest into aviation-grade smelter networks, while composite carbon fiber reclamation through pyrolysis and solvolysis methods remains technically immature for Boeing 787 and Airbus A350 structures.
- Aluminum:Airframe skin and structural elements comprise the highest-volume metallic recovery stream, with German and French smelters developing closed-loop processing to bypass virgin metal premiums.
- Titanium Alloys:Engine components and landing gear structures command premium pricing in secondary aerospace feedstock markets.
- Composites:Carbon fiber reclamation from retired wide-body structures through emerging thermal and chemical methods.
- Steel:Landing gear and fastener recovery for industrial remelting.
- Copper:Electrical system wiring and conductor reclamation.
- Plastics:Interior panel and insulation material recovery.
Aluminum dominates installed base. Composites are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mojave Air and Space Port anchors the United States' teardown infrastructure through its desert storage capacity and adjacent dismantling yards. Pinal Airpark in Arizona feeds dismantling clusters with retired narrow-body fleets. European facilities leverage rail and barge networks for airframe transport from temporary storage.
United States
Arizona and California desert boneyards concentrate retiring A320ceo and 737-800 fleets awaiting teardown. FAA parts certification frameworks govern airworthiness documentation for recovered components. Mojave and Pinal Airpark sites feed dismantling clusters where GA Telesis and CAVU Aerospace operate adjacent facilities.
France
TARMAC Aerosave dominates European end-of-life aircraft intake through its Tarbes facility near the Pyrenees. REACH Annex XVII restrictions on chromium and cadmium coatings mandate substitute surface treatments for recovered parts. French aviation-grade smelters in the Haute-Garonne region develop closed-loop aluminum-titanium streams.
Germany
Extended producer responsibility frameworks are positioning German lessors to pre-fund end-of-life processing obligations. ECHA enforcement of REACH protocols filters smaller dismantlers lacking dedicated hazardous material lines. Hamburg and Frankfurt maintenance clusters integrate teardown capacity for adjacent parts refurbishment.
Spain
TARMAC Aerosave's Teruel facility leverages arid climate conditions for airframe storage and robotic dismantling deployment. F-Gas Directive compliance costs constrain refrigerant recovery operations at Iberian teardown sites. Teruel's emerging capacity competes with French facilities for Mediterranean basin retirements.
India
Hyderabad and Bangalore MRO clusters add teardown capacity to capture parts refurbishment revenue from narrow-body programs. The country's national aviation regulator aligns with EASA standards for component traceability documentation. Karnataka and Telangana maintenance hubs attract lessor contracts for regional fleet retirements.
Commercial Aircraft Disassembly Dismantling and Recycling Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in narrower service bands. The vendor base stratifies between accredited European operators with capital reserves and desert-storage-adjacent US yards competing on turnaround speed. Three archetypes dominate: vertically integrated parts distributors, specialized narrow-body teardown contractors, and smelter-linked material recovery operators. Consolidation pressures favor M&A activity among Arizona and California clusters, while European players pursue capacity expansion to meet REACH compliance thresholds.
Within the European accredited tier, TARMAC Aerosave exemplifies multi-facility platform scale across France and Spain. Among US-based dismantlers, CAVU Aerospace occupies a position in narrow-body specialization, while GA Telesis LLC anchors the vertical integration archetype linking disassembly to certified parts distribution. Air Salvage International Ltd represents the UK-based independent operator model serving lessor direct contracts.
| Leading Market Players |
|---|
| TARMAC Aerosave |
| Air Salvage International Ltd |
| CAVU Aerospace |
| Aircraft End-of-Life Solutions (AELS) BV |
| GA Telesis LLC |
| Eirtrade Aviation |
| Vallair |
| Aerocycle |
| Ecube |
| Others |
Cost & Logistics Intelligence
Overcapacity at Arizona desert boneyards is compressing turnaround pricing for narrow-body teardown programs while simultaneously pushing dismantlers toward robotic extraction investments that reshape supplier cost structures and margin recovery timelines.
Pricing Analysis
EU REACH Annex XVII dictates the pricing tier structure across European teardown facilities, separating accredited operators with dedicated hazardous material lines from commodity yards facing margin compression. Pricing stratifies across premium, standard, and economy tiers based on airworthiness documentation completeness and OEM certification pathways. Cost compression in standard-tier dismantling is intensifying because REACH compliance investments filter smaller operators from the competitive set. Leasing companies demonstrate highest price sensitivity due to pre-funded end-of-life processing obligations, while airlines with aging wide-body fleets prioritize premium-tier guaranteed buyback contracts.
Supply Chain Analysis
Retired airframe feedstock concentrates in the United States, France, and Spain where desert storage and arid climate facilities anchor intake capacity. The supply chain draws from aluminum-titanium alloy streams, composite carbon fiber structures, and certified component inventories. Single-source vulnerability runs through aviation-grade smelter networks in Germany and France that bypass virgin metal premiums. Distribution feeds through tier-one dismantler platforms linking disassembly to parts refurbishment networks and secondary aerospace feedstock markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial aircraft teardown functions as a service-attach opportunity where parts refurbishment and material recovery revenue layers expand faster than base disassembly contracting. Component salvage margins deepen through airworthiness certification value capture.
For Market Incumbents: Build regulatory accreditation moats through REACH Annex XVII and FAA parts certification framework investments that filter smaller competitors. Consolidate adjacent capacity in Arizona and California desert clusters to capture transport cost advantages from Mojave and Pinal Airpark storage sites. Anchor backward integration into aviation-grade smelter partnerships to secure closed-loop aluminum-titanium feedstock pricing.
For New Entrants and Emerging Players: Pursue composite carbon fiber reclamation white space where pyrolysis and solvolysis methods for Boeing 787 and Airbus A350 structures remain technically immature. Target Indian subcontinent MRO integration at Hyderabad and Bangalore maintenance clusters where teardown capacity additions capture adjacent parts refurbishment revenue. Lead with narrow-body turnaround speed guarantees to penetrate airline direct contracting channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic extraction and automated plasma cutting installations with five-year payback horizons. Long-term viability centers on platform-scale operators with multi-facility accreditation spanning REACH and FAA jurisdictions. Acquisition targets should demonstrate smelter-linked material recovery contracts and lessor pre-funding arrangements under extended producer responsibility frameworks. Monitor EU material traceability mandate enforcement as inflection signal for competitive filtration velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Extraction Deployment | Machine-vision guided plasma cutting collapses narrow-body turnaround from ninety days to under forty-five at tier-one facilities. |
| REACH Compliance Investment | Dedicated hazardous material lines at European facilities filter competition and anchor premium-tier pricing power. |
| Smelter Partnership Integration | Closed-loop aluminum-titanium streams with German and French aviation-grade smelters bypass virgin metal premium exposure. |
| Desert Storage Proximity Expansion | Arizona and California cluster consolidation captures transport cost advantages from Mojave and Pinal Airpark intake. |
| Composite Reclamation R&D | Pyrolysis and solvolysis maturation for Boeing 787 and Airbus A350 carbon fiber recovery opens structurally underpenetrated material category. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline fleet managers, lessor asset directors, MRO procurement leads, and dismantling facility operations heads. Secondary validation drew from FAA airworthiness directives, EASA certification databases, EU Aircraft Dismantling and Recycling Association protocols, and customs trade data on aviation-grade alloy flows. Bottom-up segment sizing across service types and disassembly techniques was triangulated against top-down macroeconomic drivers including fleet retirement forecasts and regulatory implementation timelines.
Calibration against historical teardown volumes and documented facility capacity utilization anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, disassembly technique, recycled material category, and end-user archetype. CAGRs were derived from regression analysis of fleet age profiles, regulatory phase-in schedules, and smelter capacity expansion announcements. Industry-specific forecast inputs incorporated wide-body retirement wave timing and REACH Annex XVII enforcement intensity.
Sensitivities concentrate around EU extended producer responsibility framework adoption velocity and composite carbon fiber reclamation technology maturation. Forecasts reflect documented assumptions on labor availability for certified airframe technicians and hazardous waste disposal cost trajectories. Cross-checking against IATA fleet retirement projections and ECHA enforcement activity reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Washing Systems Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Engine Hoists Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Middle-East Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market