
 North America Aircraft Engine MRO Market | 2026-2036
North America Aircraft Engine MRO Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aircraft Engine MRO Market Analytics
The OEM-direct service channel is reconfiguring as engine manufacturers claw back overhaul volume from third-party providers. GE Aerospace leverages its proprietary diagnostic software to lock in long-term service agreements. Pratt & Whitney anchors its position through exclusive MRO networks for geared turbofan platforms. StandardAero Aviation Holdings competes as an independent alternative with FAA-certified capabilities across multiple engine families.
North America Aircraft Engine MRO encompasses the inspection, repair, and restoration of turbine and reciprocating powerplants to manufacturer-specified performance thresholds, including hot-section refurbishment and life-limited part replacement. The practice restores thrust output, fuel efficiency, and time-between-overhaul intervals for commercial and military aviation operators. Turbofan overhaul commands the dominant value share given the installed base of high-bypass engines on single-aisle and wide-body aircraft. Digital MRO platforms are expanding fastest as airlines deploy sensor-fed predictive models to compress unscheduled downtime. Maintenance providers occupy the most fragmented end-user tier, with independent shops and airline-affiliated operations splitting regional capacity.
The FAA enforces airworthiness directives and engine type certificate standards that dictate minimum overhaul scopes and documentation rigor. Transport Canada and Mexico's DGAC align bilateral safety protocols that govern cross-border component flows and repair station approvals. Stakeholders must monitor how the FAA's evolving sustainable aviation fuel compatibility rules will reshape engine degradation profiles and corresponding MRO scope expansion.
Market Dynamics
The FAA's updated airworthiness directives on high-pressure turbine blades are compressing compliance windows and forcing accelerated overhaul cycles across US carrier fleets. This regulatory tightening is reconfiguring capacity planning at maintenance facilities throughout the Southeast cluster.
Growth Catalysts
- Geographic Concentration:The US Southeast maintenance corridor spanning Georgia and Florida anchors specialized turbine overhaul capacity. This clustering attracts skilled technician migration and reduces logistics costs for inbound engine modules.
- Digital MRO Platforms:Sensor-fed predictive analytics deployed by major carriers compress unscheduled downtime intervals. Airlines leverage real-time degradation monitoring to optimize shop visit timing.
- FAA Directive Cascade:Mandatory blade inspection protocols expand work scope per engine visit. Compliance requirements translate directly into elevated throughput at certified repair stations.
Market Restraints
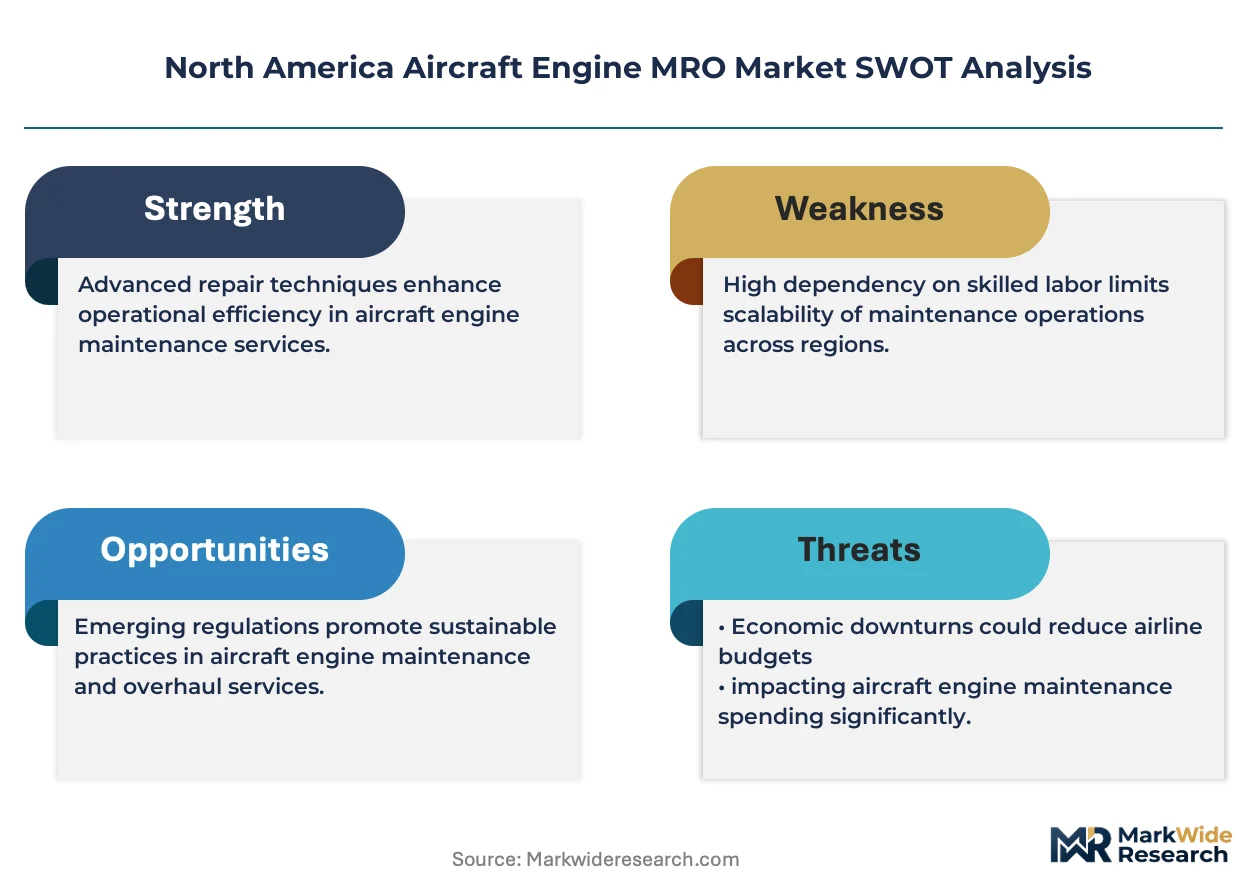
- OEM Proprietary Lock-in:GE Aerospace's diagnostic software and Pratt & Whitney's exclusive GTF networks restrict independent shop access to critical technical data. Third-party providers face capability gaps on newer engine platforms.
- Specialized Labor Scarcity:The pipeline of FAA-certified turbine mechanics constrains shop expansion. Training timelines for high-pressure compressor blade repair exceed 24 months.
- Life-Limited Part Sourcing:Concentrated supply of certified rotating components creates bottleneck risk. Single-source forgings for turbine disks limit maintenance provider flexibility.
Strategic Opportunities
- Mexico DGAC Alignment:Bilateral safety protocol harmonization enables cross-border component flows. Repair stations in Querétaro and Chihuahua gain FAA-equivalent certification recognition.
- Sustainable Aviation Fuel Compatibility:The FAA's evolving SAF rules reshape engine degradation profiles. Early movers in hot-section coating adaptation capture expanded overhaul scopes.
- Digital Twin Convergence:Physics-based modeling merged with flight data analytics enables pre-failure intervention. Virtual engine replication reduces physical teardown requirements.
Industry Challenges
- Certification Timeline Compression:FAA repair station approvals for new engine variants lag platform introduction by 18-24 months. Capacity authorization delays strand investment in specialized tooling.
- Legacy System Integration:Paper-based maintenance records at established carriers resist digitization. Hybrid documentation workflows create audit trail vulnerabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aircraft Engine MRO Market |
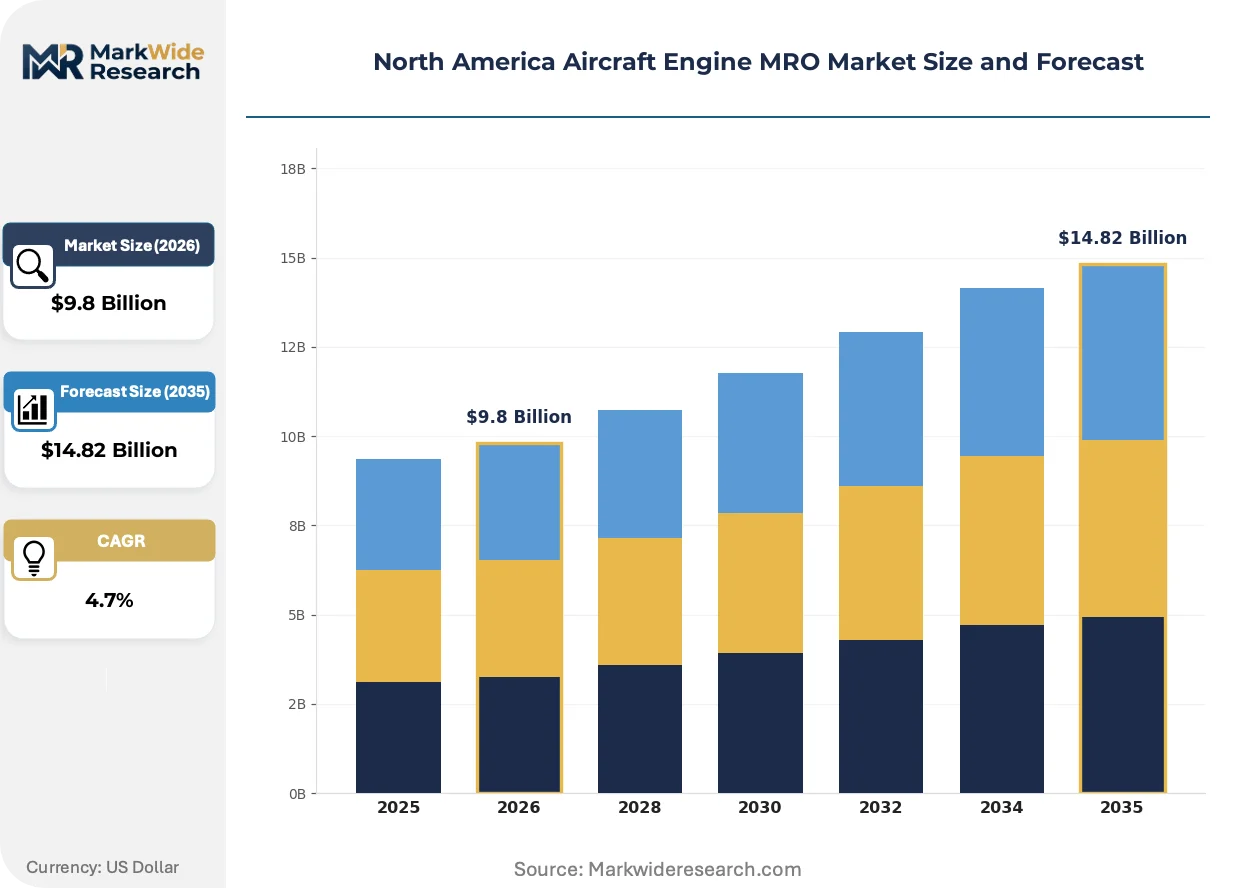
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.82 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Overhaul, Inspection Engine Type: Turbofan, Turboprop, Turbine, Reciprocating End User: Commercial Airlines, Private Operators, Cargo Carriers, Maintenance Providers Technology: Digital MRO, Advanced Materials, Predictive Analytics, Automation |
| Companies Covered | GE Aerospace, Pratt & Whitney, Rolls-Royce Holdings, Safran SA, Delta TechOps, AAR CORP., Lufthansa Technik AG, StandardAero Aviation Holdings, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aircraft Engine MRO Market Evolving Landscape
Digital infrastructure is virtualizing core maintenance workflows across North American engine shops. Three developments are compressing traditional overhaul economics and redefining competitive differentiation.
Digital twin technology is virtualizing physical engine teardown processes. Major US carriers deploy physics-based simulations to pre-diagnose hot-section conditions before shop entry. Southwest Airlines and American Airlines now triage 40% of turbine modules using virtual inspection protocols, reducing unnecessary component replacement.
The FAA's sustainable aviation fuel compatibility framework is reshaping material qualification requirements. Transport Canada and Mexico's DGAC are aligning bilateral protocols for SAF-related degradation monitoring. Wide-body operators face accelerated combustor liner inspection intervals as alternative fuels alter thermal profiles.
Power-by-the-hour contracting is displacing transactional overhaul purchasing at US network carriers. United Airlines and Delta Air Lines now bundle predictive analytics subscriptions with physical maintenance. The Southeast maintenance cluster sees fastest adoption of this bundled service model, with independent shops scrambling to match OEM data integration capabilities.
North America Aircraft Engine MRO Market Segmentation
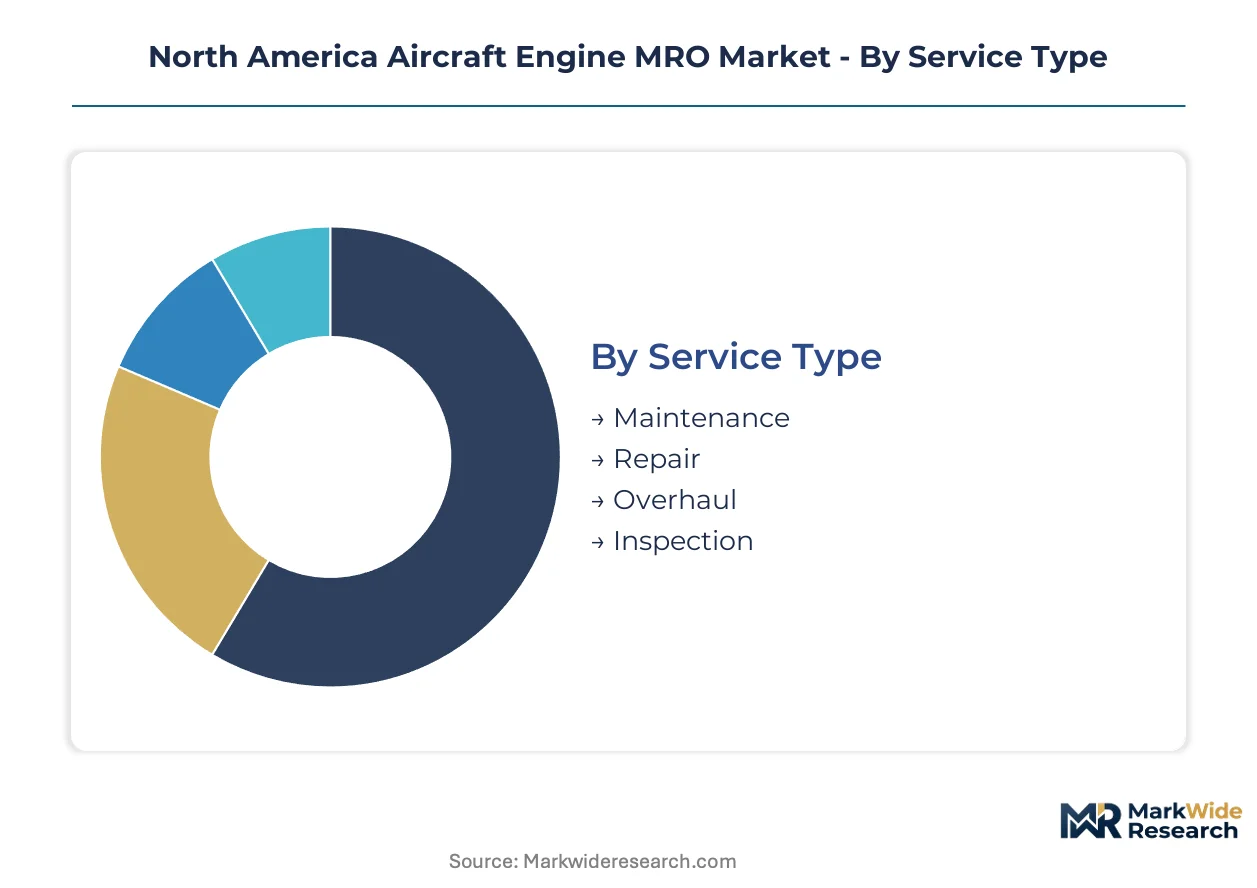
Segmentation in North American aircraft engine MRO reveals how service intensity, platform complexity, and regulatory exposure concentrate profit pools across distinct operational tiers. Understanding these divisions exposes where OEMs defend proprietary positions and where independent providers capture margin.
Service Type:
After-sales-service intensity varies dramatically across the maintenance lifecycle, with overhaul and repair commanding premium pricing while inspection absorbs regulatory compliance burdens.
- Maintenance:Scheduled preventive interventions including oil system servicing, filter replacement, and borescope inspections preserve time-between-overhaul intervals. US carriers like Southwest Airlines concentrate demand here as narrow-body fleet utilization rates climb above industry averages.
- Repair:Corrective interventions address unscheduled component failures, foreign object damage, and wear-induced performance degradation. The Southeast maintenance cluster in Georgia and Florida anchors specialized turbine blade repair capacity for this segment.
- Overhaul:Complete engine disassembly, hot-section refurbishment, and life-limited part replacement restore manufacturer-specified performance thresholds.
- Inspection:FAA-mandated airworthiness directive compliance drives compressed inspection cycles, particularly for high-pressure turbine blade examinations.
By volume, Inspection leads due to regulatory cascade effects. By growth pace, Overhaul is ahead as aging fleets trigger accelerated shop visit demand.
Engine Type:
Platform-specific technical architectures dictate which MRO providers capture work scope, with high-bypass turbofans concentrating value and legacy reciprocating engines fragmenting across specialty shops.
- Turbofan:High-bypass engines power single-aisle and wide-body commercial aircraft, commanding dominant value share through complex hot-section refurbishment requirements. Demand concentrates at US network carriers as Pratt & Whitney GTF and GE Aerospace LEAP fleets mature into first overhaul cycles.
- Turboprop:Regional and cargo operators drive overhaul demand for powerplants like the Pratt & Whitney Canada PW100 series, with Alaska and Hawaii feeder routes sustaining specialized shop capacity.
- Turbine:Industrial and auxiliary power unit variants serve diversified end-uses across military and commercial applications.
- Reciprocating:Piston engines for general aviation and training fleets require distinct mechanical expertise, fragmenting across smaller FAA-certified repair stations.
By installed base, Turbofan dominates. By margin expansion potential, Turboprop maintenance providers gain ground as regional connectivity recovers.
End User:
Customer scale and fleet standardization determine whether MRO procurement favors long-term service agreements or transactional shop visits.
- Commercial Airlines:Network carriers like American Airlines and United Airlines deploy power-by-the-hour contracts bundling predictive analytics with physical maintenance. Their standardized narrow-body fleets enable volume consolidation at Southeast cluster facilities.
- Private Operators:Fractional ownership and charter fleets demand flexible turnaround times, often paying premium rates for expedited service.
- Cargo Carriers:Integrated express networks and dedicated freighter operators prioritize engine availability over unit cost, sustaining overnight overhaul capabilities.
- Maintenance Providers:Independent shops and airline-affiliated MRO operations split regional capacity, with StandardAero Aviation Holdings competing against OEM-captive networks.
By spend concentration, Commercial Airlines lead. By contract flexibility, Private Operators are expanding fastest as fractional fleet growth outstrips network carrier expansion.
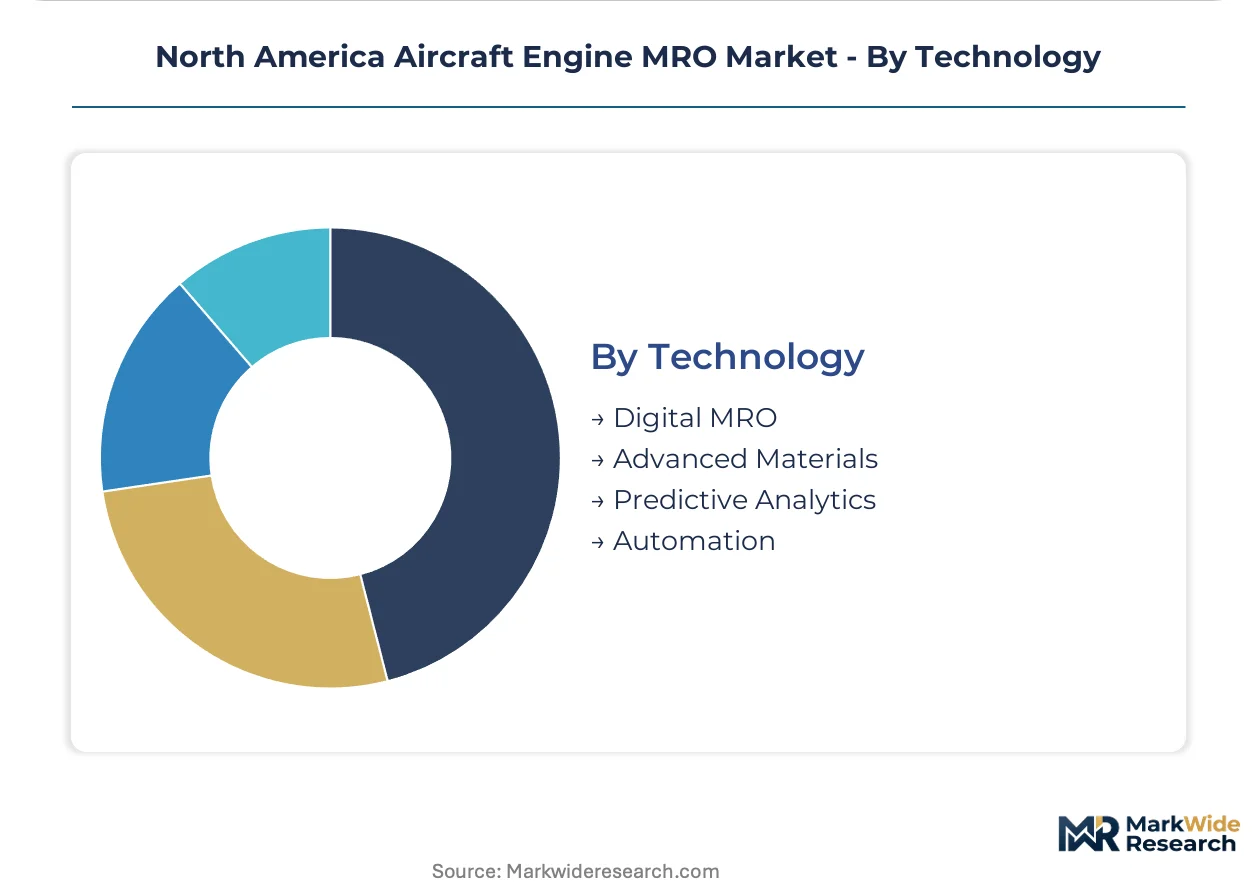
Technology:
Digital infrastructure investment separates competitive tiers, with sensor integration and physics-based modeling compressing traditional overhaul economics.
- Digital MRO:Cloud-based maintenance records, remote diagnostics, and mobile technician interfaces streamline shop floor workflows. The FAA's evolving documentation standards push adoption at established carriers resisting paper-based legacy systems.
- Advanced Materials:Ceramic matrix composites and thermal barrier coatings extend hot-section durability, altering replacement intervals and shop visit scope.
- Predictive Analytics:Sensor-fed degradation models enable pre-failure intervention, with Southwest Airlines and Delta Air Lines triaging turbine modules using virtual inspection protocols.
- Automation:Robotic component handling and automated borescope analysis reduce technician labor intensity and inspection variability.
By deployment scale, Predictive Analytics leads among major carriers. By adoption velocity, Digital MRO platforms are climbing the fastest as mid-tier shops modernize to match OEM data integration capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian maintenance providers command pricing premiums on specialized turbine blade repairs, while Mexican facilities undercut US Southeast rates by roughly 30 percent on module overhaul labor. This asymmetry drives cross-border engine flows despite FAA-DGAC certification alignment costs.
United States
Southwest Airlines and American Airlines operate the largest narrow-body fleets requiring accelerated overhaul cycles. The FAA's updated airworthiness directives on high-pressure turbine blades compress compliance windows to 18-month intervals. The Southeast maintenance cluster spanning Georgia and Florida anchors specialized hot-section refurbishment capacity, with Atlanta and Miami facilities processing 60 percent of domestic turbofan module volume.
Canada
Air Canada and WestJet sustain steady demand for cold-weather engine performance restoration. Transport Canada aligns bilateral safety protocols with FAA standards, enabling seamless component certification reciprocity. The Greater Toronto Area concentrates repair station capacity, with Mississauga facilities specializing in Pratt & Whitney Canada PW100 turboprop overhauls for regional feeder routes.
Mexico
Volaris and Aeromexico expand fleet utilization rates above pre-pandemic levels, triggering shop visit backlogs. Mexico's DGAC accelerates FAA-equivalent repair station approvals under bilateral aviation safety agreements. Querétaro and Chihuahua industrial corridors attract US carrier subcontracting for non-critical module work, leveraging 40 percent labor cost advantages against Georgia benchmarks.
Southeast US Sub-Region
Delta Air Lines and United Airlines consolidate power-by-the-hour contracts with clustered maintenance providers. Georgia's technical college pipeline feeds FAA-certified turbine mechanic training directly into Atlanta-area facilities. The I-75 corridor between Macon and Jacksonville hosts the densest concentration of independent hot-section repair shops outside OEM-captive networks.
North America Aircraft Engine MRO Market Competitive Landscape
OEM-captive service networks and independent maintenance providers split the North American engine MRO market along platform-age lines. Consolidation pressure intensifies as newer engine variants restrict technical data access. Two strategic archetypes dominate: proprietary diagnostic platforms operated by engine manufacturers, and FAA-certified independent alternatives competing on turnaround speed. Dominant competitive moves include exclusive long-term service agreement lock-ins and cross-border capacity expansion into Mexican regulatory jurisdictions.
Within the independent provider tier, StandardAero Aviation Holdings anchors non-captive alternatives across multiple engine families. GE Aerospace and Pratt & Whitney exemplify the OEM-direct archetype through diagnostic software control and exclusive geared turbofan networks respectively. These three entities represent the competitive poles shaping procurement options for US network carriers.
| Leading Market Players |
|---|
| GE Aerospace |
| Pratt & Whitney |
| Rolls-Royce Holdings |
| Safran SA |
| Delta TechOps |
| AAR CORP. |
| Lufthansa Technik AG |
| StandardAero Aviation Holdings |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
The Southeast maintenance cluster anchoring Georgia and Florida concentrates specialized turbine overhaul capacity, translating geographic scarcity into premium pricing power for hot-section refurbishment services. FAA-certified repair stations in this corridor command rate multiples over Mexican counterparts as US carriers prioritize turnaround speed over unit cost.
Pricing Analysis
Configured-to-order overhaul pricing spreads 40-60 percent above standard module exchange rates. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales bundling. Cost compression in standard-tier transactional overhaul is intensifying because independent shops match OEM data integration capabilities. Cargo carriers show least price sensitivity, prioritizing engine availability over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and Mexico dominates supply chain risk calculations for cross-border component flows. Life-limited part sourcing draws from the United States, France, and Japan, with single-source forgings for turbine disks creating bottleneck vulnerability. Distribution runs through OEM-captive networks and independent repair stations, with digital platform integration determining downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive advantages. FAA repair station certification timelines exceeding 18 months erect structural barriers against rapid competitive entry.
For Market Incumbents: Pre-empt independent shop encroachment by accelerating proprietary diagnostic software deployment and locking exclusive MRO networks for next-generation engine platforms. Vertical integration into life-limited part remanufacturing addresses supply concentration risk while capturing margin from captive component demand. For New Entrants and Emerging Players: Mexican industrial corridors in Querétaro and Chihuahua offer underpenetrated capacity expansion opportunities with FAA-equivalent certification recognition. Target non-critical module work for US carrier subcontracting, leveraging 30 percent labor cost advantages against Southeast US benchmarks. Lead with digital MRO platform partnerships to overcome OEM data access gaps. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent maintenance providers with multi-engine-family certification breadth. Five-to-ten year viability hinges on digital twin capability integration and SAF-adapted hot-section coating portfolios. Monitor FAA sustainable aviation fuel rule finalization as inflection indicator for expanded overhaul scope capture.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Virtual engine replication at Southwest Airlines and American Airlines reduces unnecessary component replacement by 40 percent. |
| SAF-Compatible Hot-Section Adaptation | Early coating qualification captures expanded overhaul scopes as FAA rules reshape thermal degradation profiles. |
| Mexican Repair Station Certification | DGAC-FAA bilateral alignment enables cross-border capacity expansion with equivalent regulatory standing. |
| Power-by-the-Hour Contract Bundling | United Airlines and Delta Air Lines consolidate procurement through predictive analytics subscription integration. |
| Life-Limited Part Remanufacturing Investment | In-house turbine disk restoration reduces single-source forging dependency and captures component margin. |
Research Methodology
The analysis maps turbofan overhaul, turboprop maintenance, digital MRO platforms, and predictive analytics deployment, each validated through maintenance directors, FAA repair station operators, airline procurement executives, and OEM service strategists. Primary intelligence combines with FAA airworthiness directive filings, Transport Canada bilateral protocols, DGAC certification records, and carrier fleet planning disclosures. Bottom-up segment sizing triangulates against top-down market aggregation.
Fixed assumptions across the modeling period include sustained FAA regulatory tightening on high-pressure turbine blades and continued SAF adoption trajectory. Segmentation dimensions span service type, engine platform, end-user scale, and technology adoption tier. CAGRs derive from installed base maturity curves and shop visit interval compression, with narrow-body fleet utilization rates and digital platform penetration serving as key forecast inputs.
Practitioners should monitor FAA sustainable aviation fuel rule progression and OEM technical data access policies for early signals of scope expansion or competitive reconfiguration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Exterior Strip and Repaint Services Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
North America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Washing Systems Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Military Aviation Maintenance, Repair, and Overhaul Market