
 Global Aircraft Engine MRO Market | 2026-2036
Global Aircraft Engine MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Engine MRO Market Analysis
Power-by-the-hour leasing and asset-light fleet management is rewriting competitive access in aircraft engine MRO, allowing airlines to outsource overhaul obligations without capital deployment. GE Aviation leverages its OEM data advantage to capture long-term service agreements. Rolls-Royce anchors its position through TotalCare contracts that bundle maintenance with predictive analytics. Lufthansa Technik competes as an independent provider with broad multi-OEM capability.
Aircraft engine MRO encompasses the inspection, repair, overhaul, and restoration of gas turbine and reciprocating powerplants to certified airworthiness standards, requiring precision machining of high-pressure compressor blades and thermal barrier coating refurbishment to restore thrust-specific fuel consumption parameters. The primary purpose is extending engine life cycles while ensuring regulatory compliance for continuous flight operations. Turbofan engine MRO commands the dominant value pool given narrowbody and widebody fleet penetration, while offsite depot overhaul generates the fastest growth as operators seek to minimize aircraft downtime. Commercial airlines represent the most concentrated end-user segment, though military operators sustain higher-margin specialized work.
The FAA, EASA, and CAAC each enforce distinct airworthiness directive schedules that dictate overhaul intervals and parts traceability requirements across their respective jurisdictions. EPA emissions standards and ICAO Carbon Offsetting and Reduction Scheme for International Aviation targets are progressively embedding environmental compliance into engine restoration scope. Stakeholders must monitor how sustainable aviation fuel compatibility requirements reshape component wear patterns and overhaul specifications.
Market Dynamics
Power-by-the-hour contracts are restructuring capital deployment across commercial aviation, transferring overhaul risk from balance sheets to OEMs and specialized MRO providers while compressing traditional spot-repair markets.
Growth Catalysts
- FAA Airworthiness Directives:Mandated turbine blade inspection intervals are expanding scheduled maintenance volume for legacy narrowbody fleets operating under Part 121 certificates.
- Sustainable Aviation Fuel Compatibility:Thermal barrier coating refurbishment cycles are lengthening as SAF blend ratios alter combustion chamber wear patterns in high-bypass turbofans.
- Military Depot Modernization:United States Air Force engine overhaul backlogs are creating sustained demand for third-party depot capacity and specialized component repair.
Market Restraints
- Specialized Alloy Supply Concentration:Single-source dependence for nickel-based superalloy castings in turbine disk production creates input vulnerability for independent repair stations.
- Parts Traceability Requirements:EASA Part 145 documentation standards impose compliance costs that disproportionately burden smaller MRO facilities without integrated ERP systems.
- Core Engine Availability:OEM-controlled lease pools limit access to overhaul-ready powerplants for non-affiliated service providers.
Strategic Opportunities
- India Fleet Expansion:Low-cost carrier growth and bilateral traffic rights are building latent demand for engine overhaul capacity near Mumbai and Delhi maintenance clusters.
- Predictive Maintenance Convergence:Digital twin integration with borescope inspection data is collapsing unscheduled removal rates for widebody operators.
- EU Emissions Trading System:Carbon border adjustments on aviation are incentivizing engine performance restoration over premature replacement.
Industry Challenges
- Certified Technician Scarcity:FAA Airframe and Powerplant license holders with turbine-specific ratings are aging out faster than training pipeline replacement.
- Legacy Fleet Documentation:Paper-based maintenance records for pre-1990 engines resist digitization, delaying blockchain traceability adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Engine MRO Market |
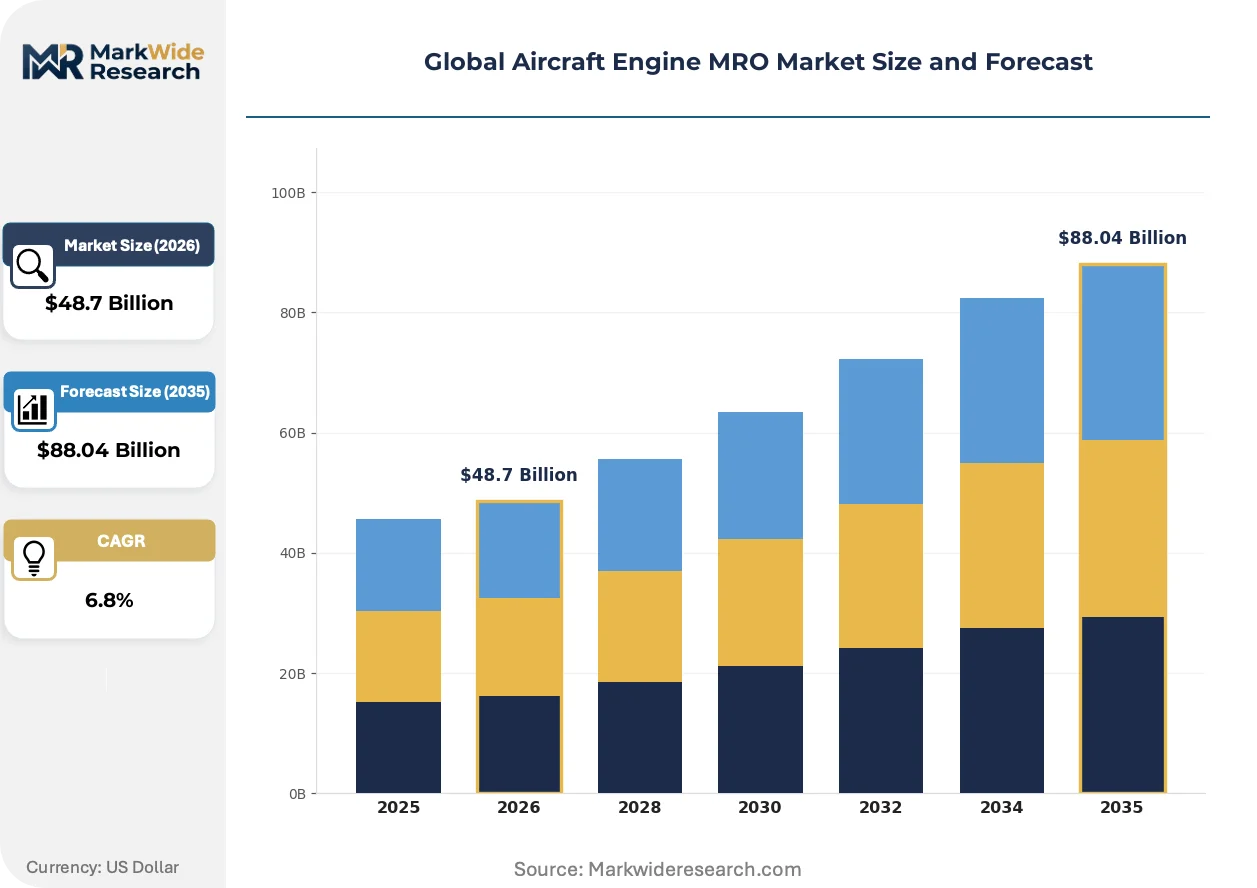
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engine Overhaul, Maintenance, Repair, Inspection Deployment Model: Onsite, Offsite, Mobile, Remote Engine Type: Turbofan, Turbojet, Turboprop, Reciprocating End User: Commercial Airlines, Cargo Carriers, Military Operators, Private Operators |
| Companies Covered | GE Aviation, Rolls-Royce, Pratt & Whitney, Lufthansa Technik, Safran Aircraft Engines, MTU Aero Engines, Delta TechOps, Air France Industries KLM Engineering & Maintenance, ST Engineering Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Engine MRO Market Emerging Trajectories
Digital thread architectures are threading through every overhaul stage, from incoming engine inspection to parts reclamation, compressing turnaround times and recalibrating labor-to-technology ratios.
Additive repair for high-pressure compressor airfoils is collapsing traditional weld-rebuild and blend-limit methodologies. Airlines with concentrated narrowbody fleets are adopting cold spray metallization for on-wing restoration. The technology is collapsing scrap rates for blade tip restoration while extending time-on-wing between shop visits.
ICAO Carbon Offsetting and Reduction Scheme for International Aviation targets are embedding emissions compliance into engine restoration specifications. Overhaul scope now explicitly addresses thrust-specific fuel consumption recovery thresholds. Widebody operators serving trans-Pacific routes are prioritizing performance restoration over minimum airworthiness compliance.
Asset-light fleet management is displacing captive overhaul infrastructure among network carriers. Low-cost carriers are unbundling engine maintenance from airframe contracts, creating spot-market liquidity for independent MRO slots. This pattern concentrates in Southeast Asia where rapid fleet growth outstocks established service relationships.
Global Aircraft Engine MRO Market Segmentation
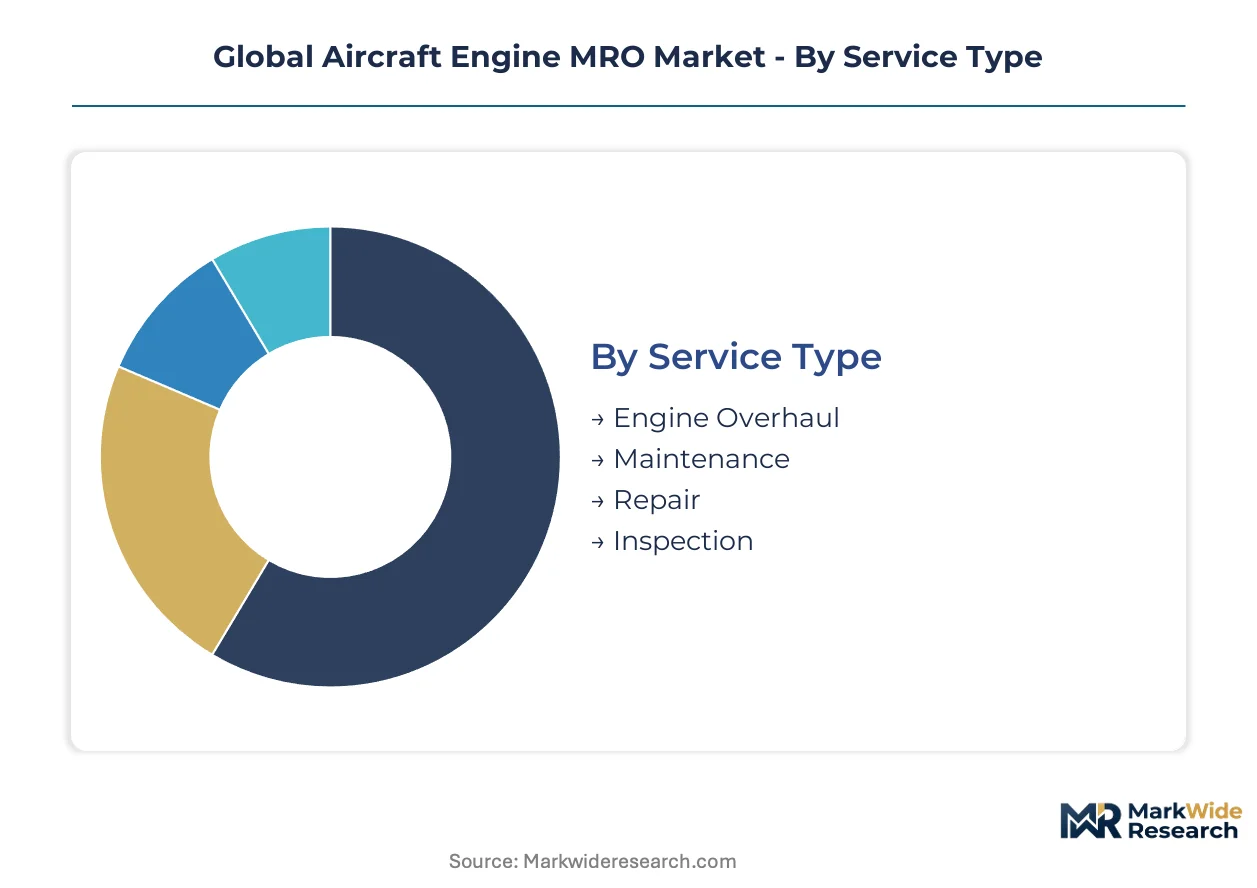
Service intensity varies dramatically across aircraft engine MRO segments, with overhaul complexity and regulatory burden creating distinct margin profiles. Understanding these structural differences enables precise capacity planning and partnership targeting for both OEM-affiliated and independent providers.
Service Type:
After-sales-service intensity peaks in full engine overhauls, where labor hours and specialized tooling requirements far exceed routine line maintenance.
- Engine Overhaul:Complete disassembly, inspection, and reassembly of gas turbine powerplants to restore thrust-specific fuel consumption parameters and certified airworthiness. Demand concentrates in the United States, where legacy narrowbody fleets under Part 121 certificates generate sustained volume from FAA-mandated turbine blade inspection intervals.
- Maintenance:Scheduled preventive interventions including oil system servicing, filter replacement, and borescope inspections to sustain time-on-wing performance. Operators in India are expanding maintenance contracts fastest as low-cost carrier fleet growth outstrips captive overhaul infrastructure.
- Repair:Component-level restoration of damaged airfoils, combustion chambers, and bearing housings without full engine disassembly. Cold spray metallization adoption is accelerating blade tip restoration throughput.
- Inspection:Regulatory compliance verification through non-destructive testing and dimensional measurement against manufacturer specifications. Digital twin integration is compressing unscheduled removal rates for widebody operators.
Engine Overhaul holds the largest share; momentum sits with Maintenance as fleet managers unbundle services from bundled power-by-the-hour agreements.
Deployment Model:
Cost tier differentiation separates capital-intensive depot infrastructure from flexible mobile solutions serving remote operators.
- Onsite:Fixed-base overhaul facilities with dedicated test cells and precision machining centers for complete engine restoration. The United States Air Force sustains demand through depot modernization backlogs requiring third-party capacity augmentation.
- Offsite:Centralized depot operations where engines ship for turnaround, minimizing aircraft downtime through spare engine pooling. Southeast Asian low-cost carriers are driving fastest expansion as rapid fleet growth outstocks established service relationships.
- Mobile:Transportable borescope and cold spray units performing on-wing restoration at airline hubs. Deployment concentrates near Mumbai and Delhi maintenance clusters serving India's expanding narrowbody fleet.
- Remote:Telemetry-driven diagnostics and augmented-reality guided technician support reducing unnecessary engine removals. Predictive analytics integration is collapsing unscheduled maintenance events for trans-Pacific widebody routes.
Offsite deployment captures the dominant value pool; Mobile solutions are climbing the fastest as operators prioritize aircraft availability over shop-visit minimization.
Engine Type:
Application-specific thermal and mechanical stress patterns dictate distinct overhaul intervals and component replacement rates across powerplant architectures.
- Turbofan:High-bypass engines powering narrowbody and widebody commercial aircraft, requiring thermal barrier coating refurbishment and high-pressure compressor blade restoration. SAF blend ratio increases are altering combustion chamber wear patterns and extending coating cycles.
- Turbojet:Pure jet propulsion systems in military fighter and trainer aircraft sustaining higher-margin specialized work with stringent documentation requirements. United States military aviation activity anchors the largest national procurement base.
- Turboprop:Gas turbine-driven propeller engines serving regional aviation and cargo feeder networks with lower thrust demands but frequent thermal cycling. Indian regional connectivity schemes are building latent demand for turboprop overhaul capacity.
- Reciprocating:Piston-engine powerplants in general aviation and training fleets with simpler maintenance profiles but aging technician certification pipelines. FAA Airframe and Powerplant license scarcity constrains service expansion.
Turbofan commands the dominant value pool; Turboprop is gaining share fastest as regional fleet renewal accelerates in emerging aviation markets.
End User:
Customer type determines contract structure, with commercial airlines favoring long-term service agreements while military operators sustain premium pricing for security-cleared work.
- Commercial Airlines:Network and low-cost carriers outsourcing overhaul obligations through power-by-the-hour contracts and spot-market procurement. Asset-light fleet management is displacing captive infrastructure among legacy carriers.
- Cargo Carriers:Express freight and dedicated freighter operators prioritizing engine performance restoration to minimize fuel burn on high-utilization routes. EU Emissions Trading System carbon border adjustments are incentivizing restoration over replacement.
- Military Operators:Air force and naval aviation units requiring security-cleared facilities and specialized component traceability. United States engine overhaul backlogs are creating sustained demand for third-party depot capacity.
- Private Operators:Corporate and business aviation fleets with dispersed geographic footprints and preference for mobile maintenance solutions. Blockchain traceability adoption faces delays from pre-1990 paper record legacy.
Commercial Airlines hold the largest share; Cargo Carriers are expanding most quickly as e-commerce-driven freighter conversions accelerate engine shop visit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Legacy narrowbody fleet density concentrates buyer demand in the United States, while low-cost carrier expansion in India and Southeast Asia builds overhaul procurement in emerging aviation corridors. Military aviation activity and regulatory compliance mandates shape procurement patterns across distinct national markets.
United States
FAA Part 121 certificate holders operating aging narrowbody fleets generate sustained engine overhaul volume from mandated turbine blade inspection intervals. The FAA's continued tightening of airworthiness directives elevates compliance-driven maintenance requirements. Oklahoma City and San Antonio depot clusters absorb United States Air Force engine overhaul backlogs through third-party capacity augmentation.
United Kingdom
Rolls-Royce TotalCare contract structures anchor long-term service agreement penetration among British Airways and Virgin Atlantic widebody operators. EASA Part 145 documentation standards impose traceability requirements that favor integrated ERP-capable facilities. Derby and Bristol maintenance clusters specialize in high-bypass turbofan performance restoration for trans-Atlantic routes.
Germany
Lufthansa Technik's independent multi-OEM capability captures unbundled maintenance demand from asset-light European network carriers. EU Emissions Trading System carbon border adjustments incentivize engine performance restoration over premature replacement. Hamburg and Frankfurt overhaul centers process thermal barrier coating refurbishment for SAF-altered combustion chamber wear patterns.
India
Low-cost carrier fleet growth outstrips captive overhaul infrastructure, building latent demand for engine maintenance contracts near Mumbai and Delhi. IndiGo and SpiceJet unbundle engine services from airframe agreements, creating spot-market liquidity for independent MRO slots. Maintenance clusters in Maharashtra and Haryana deploy mobile cold spray units for on-wing blade tip restoration.
Singapore
ST Engineering Aerospace anchors Southeast Asian overhaul capacity serving rapid fleet growth across Indonesia, Vietnam, and Thailand. Changi-based facilities leverage geographic positioning for trans-shipment of engines between European and Asia-Pacific operators. The city-state's maintenance cluster specializes in offsite depot turnaround minimizing aircraft downtime through spare engine pooling.
Global Aircraft Engine MRO Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where OEM-affiliated service providers hold data-advantaged positions in long-term contracts. The market consolidates around three strategic archetypes: original equipment manufacturers bundling maintenance with predictive analytics, independent multi-OEM specialists competing on flexibility, and airline-captive operations serving internal fleet requirements. Dominant competitive moves include strategic partnerships expanding geographic reach and technology licensing agreements transferring additive repair capabilities.
Within the OEM-anchored tier, GE Aviation exemplifies channel control through power-by-the-hour leasing structures that transfer overhaul risk from airline balance sheets. Rolls-Royce occupies a parallel position in the premium-contract segment through integrated TotalCare offerings. Lufthansa Technik represents the independent specialist archetype, competing without manufacturer affiliation through broad multi-OEM technical capability and Hamburg-based depot infrastructure.
| Leading Market Players |
|---|
| GE Aviation |
| Rolls-Royce |
| Pratt & Whitney |
| Lufthansa Technik |
| Safran Aircraft Engines |
| MTU Aero Engines |
| Delta TechOps |
| Air France Industries KLM Engineering & Maintenance |
| ST Engineering Aerospace |
| Others |
Supply Flow & Price Mechanics
Single-source dependence for nickel-based superalloy castings in the United States and United Kingdom concentrates upstream margin capture among specialty foundries, forcing independent MRO providers to absorb input volatility or cede pricing power to OEM-affiliated service networks with captive alloy supply.
Pricing Analysis
Certification level creates the primary spread, with FAA Part 145 and EASA Part 145 credentials commanding premium rates over uncertified repair stations. Three-tier pricing structure separates OEM-authorized facilities from independent specialists and non-affiliated job shops. Cost compression in the independent tier is intensifying because parts traceability documentation burdens disproportionately burden smaller facilities. Low-cost carriers in India and Southeast Asia exhibit highest price sensitivity, while military operators sustain lowest sensitivity due to security-cleared work requirements.
Supply Chain Analysis
Export control regimes under ITAR and EAR restrictions limit cross-border flows of turbine disk alloys and precision machining equipment. Manufacturing concentrates in the United States, Germany, and Japan for high-pressure compressor components. The supply chain draws from nickel-based superalloys, thermal barrier coatings, and precision bearings. Single-source vulnerability in turbine disk castings creates structural risk. Distribution runs through OEM-controlled lease pools and independent depot networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power-by-the-hour contract structures are transforming aircraft engine MRO into a platform economy where data interoperability between OEM analytics systems and airline fleet management platforms determines competitive access.
For Market Incumbents: Insulate long-term service agreement margins by deepening predictive analytics integration and securing exclusive alloy supply contracts. Cold spray metallization specialists threaten component-level repair margins. Backward integration into thermal barrier coating refurbishment capabilities preserves pricing power. For New Entrants and Emerging Players: India's maintenance clusters near Mumbai and Delhi represent underpenetrated white space where rapid low-cost carrier fleet growth outstocks established service relationships. Mobile on-wing restoration units bypass capital-intensive depot infrastructure. Partner with regional lessors for spare engine pooling access. For Investors and Strategic Acquirers: Capital is best deployed toward independent MRO specialists with multi-OEM capability and integrated ERP systems compliant with EASA Part 145 documentation standards. Long-term viability hinges on digital twin integration and additive repair technology licensing. Watch for FAA airworthiness directive acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Predictive analytics collapse unscheduled removal rates for widebody operators. |
| Additive Repair Technology Licensing | Cold spray metallization transfers extend blade tip restoration throughput. |
| Multi-OEM Certification Investment | Broad technical capability captures unbundled maintenance from asset-light carriers. |
| Alloy Supply Agreement | Long-term superalloy contracts insulate against single-source foundry concentration. |
| Mobile Service Deployment | Transportable borescope units penetrate India's narrowbody fleet expansion corridors. |
Methodological Framework
Cross-validation between primary interviews with MRO operations directors, FAA certification specialists, airline fleet procurement managers, and turbine component engineers anchors the qualitative findings. Secondary validation draws from FAA airworthiness directive filings, EASA Part 145 certification databases, ICAO emissions compliance records, and customs trade data for superalloy imports. Bottom-up capacity modeling triangulates against top-down fleet projection methodologies.
Calibration against historical shop visit rates and engine removal patterns shapes the analytical framework across the projection horizon. Segmentation dimensions include service type, deployment model, engine architecture, and end-user contract structure. CAGRs derive from fleet growth projections, regulatory mandate acceleration curves, and technology adoption S-cycles. Forecast inputs incorporate SAF blend ratio impacts on thermal barrier coating cycles and military depot modernization backlogs.
Practitioners should monitor FAA airworthiness directive tightening schedules and sustainable aviation fuel mandate acceleration for early signals. Forecasts reflect assumptions about technician certification pipeline recovery and alloy supply chain stability. Material shifts in export control regime enforcement or OEM lease pool access restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
North America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Narrowbody Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market