
 Aviation Asset Management Market | 2026-2036
Aviation Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Asset Management Market Analysis
Subscription-based engine health monitoring is rebalancing how lessors price power-by-the-hour contracts and residual value guarantees. AerCap Holdings N.V. leverages its scale across widebody and narrowbody portfolios to sustain pricing power in volatile lease rate environments. SMBC Aviation Capital anchors its competitive position through concentrated exposure to next-generation narrowbody assets with superior fuel efficiency profiles. BOC Aviation competes aggressively on delivery slots secured through direct OEM relationships across Chinese and international carrier networks.
Aviation asset management encompasses the technical and financial stewardship of aircraft, engines, and rotable components throughout acquisition, operation, and disposition phases, requiring adherence to airworthiness directives, maintenance program intervals, and component traceability standards per ATA chapters. Its primary commercial purpose is to maximize utilization efficiency and residual value recovery while ensuring continuous regulatory compliance across multiple jurisdictions. Lease financing structures dominate capital deployment as airlines prioritize balance sheet flexibility over direct ownership burdens, while spare parts trading has emerged as a high-margin segment where component scarcity and OEM aftermarket pricing create arbitrage opportunities for specialized traders. Maintenance, repair, and overhaul services represent the most operationally intensive layer, with labor rates and turnaround times determining lessor preference for third-party versus captive MRO providers.
The FAA's Airworthiness Directives and the EASA Part-M continuing airworthiness framework impose mandatory inspection cycles that directly dictate asset downtime scheduling and revenue loss calculations for lessors and operators. Ireland's aviation regulatory authority aligns with EU safety standards while offering specialized leasing company oversight that has made Dublin the dominant jurisdiction for aircraft special purpose vehicle incorporation and enforceable security interest perfection. Stakeholders must monitor how emerging sustainable aviation fuel mandates and carbon border adjustments will recalibrate asset depreciation curves and engine retrofit investment thresholds across regional regulatory regimes.
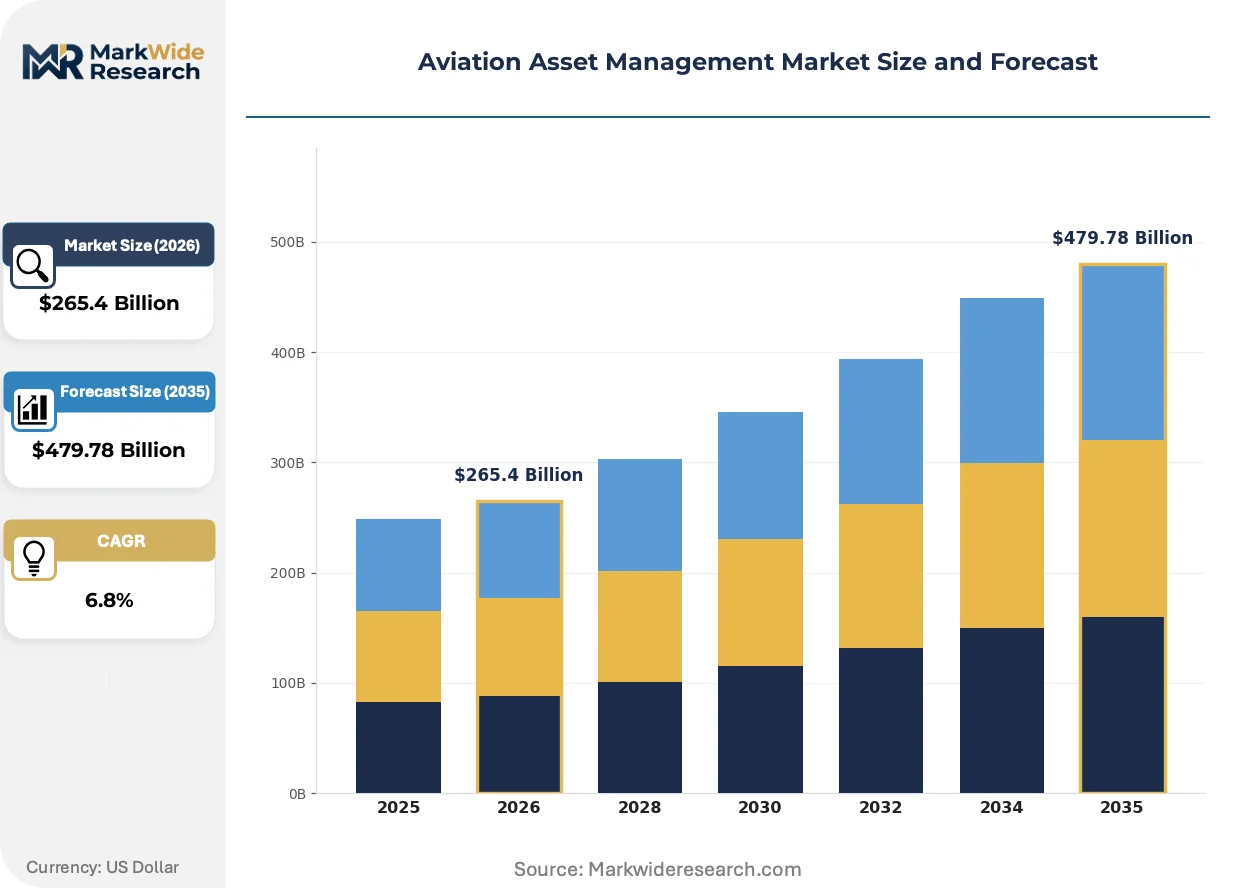
Market Dynamics
Subscription-based engine health monitoring is rebalancing lessor pricing power and compressing traditional power-by-the-hour contract structures. The FAA's updated aging aircraft inspection protocols are reshaping maintenance scheduling and asset valuation methodologies across lessor portfolios.
Growth Catalysts
- Leased Fleet Expansion:Low-cost carriers in Southeast Asia are prioritizing operating lease structures over direct ownership to preserve balance sheet flexibility and accelerate fleet renewal cycles.
- EU Green Deal SAF Mandates:Sustainable aviation fuel requirements are forcing asset managers to recalibrate engine retrofit investment thresholds and residual value depreciation curves.
- Dublin Leasing Cluster Concentration:Ireland's specialized legal frameworks for aircraft special purpose vehicles and enforceable security interest perfection are drawing capital deployment toward Irish-domiciled lessors.
Market Restraints
- OEM Aftermarket Pricing Power:Component scarcity and proprietary parts certification create arbitrage constraints for independent spare parts traders and MRO providers.
- Regulatory Inspection Burden:The FAA's Airworthiness Directives and EASA Part-M continuing airworthiness frameworks impose mandatory downtime cycles that directly reduce asset utilization rates.
- Technical Labor Rate Inflation:Specialized aviation maintenance technician shortages in North America and Western Europe are compressing third-party MRO margin structures.
Strategic Opportunities
- India Fleet Modernization:The country's PLI scheme for aviation manufacturing and expanding domestic carrier networks are creating demand for next-generation narrowbody lease structures.
- Digital Twin Convergence:Predictive maintenance algorithms fused with blockchain component traceability are enabling real-time residual value adjustments and automated lease rate resets.
- Carbon Border Adjustment Arbitrage:EU carbon border mechanisms on aviation emissions are positioning SAF-compliant aircraft assets at premium lease rate tiers versus legacy fuel-dependent portfolios.
Industry Challenges
- ATA Chapter Compliance Complexity:Component traceability standards across multiple jurisdictions require specialized documentation systems that strain legacy asset management platforms.
- Widebody Residual Value Compression:Long-haul route recovery uncertainty and accelerated retirements of four-engine aircraft categories are forcing write-downs on aging twin-aisle portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Asset Management Market |
| Market Size in 2026 | $265.4 Billion |
| Market Size in 2035 | $479.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Asset Type: Aircraft, Engines, Spare Parts, Components Investment Strategy: Lease Financing, Ownership, Joint Ventures, Residual Value Service Type: Maintenance, Repair, Overhaul, Consulting Client Type: Airlines, Lessors, Freight Operators, OEMs |
| Companies Covered | AerCap Holdings N.V., Air Lease Corporation, SMBC Aviation Capital, BOC Aviation, Avolon, BBAM Aircraft Leasing and Management, GA Telesis, Aviation Asset Management, Acumen Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Asset Management Market Emerging Trajectories
Digital infrastructure is penetrating every layer of aviation asset stewardship, from acquisition due diligence through disposition forecasting. Three distinct vectors are compressing traditional operating models and creating new value capture mechanisms.
Predictive analytics platforms are integrating sensor-derived engine performance data with lease contract trigger clauses to automate maintenance reserve calculations. Lessors adopting these systems are shifting from calendar-based inspections to condition-driven scheduling, reducing unplanned downtime by restructuring power-by-the-hour agreements around real-time health scores rather than flight hour accumulations.
EASA's expanding Part-M continuing airworthiness framework is tightening documentation requirements for component life-limited parts and repair station approvals. Lessors with mixed-registry portfolios must now maintain dual compliance systems, driving consolidation toward specialized asset managers with regulatory technology investments spanning FAA, EASA, and CAAC jurisdictions.
Airline procurement departments are unbundling maintenance, repair, and overhaul services from integrated lease packages to capture labor rate arbitrage between captive and third-party providers. This disintermediation is most visible among Southeast Asian low-cost carriers, where direct MRO contracting is displacing lessor-arranged maintenance structures and compressing the traditional value-add layer of full-service operating leases.
Aviation Asset Management Market Segmentation
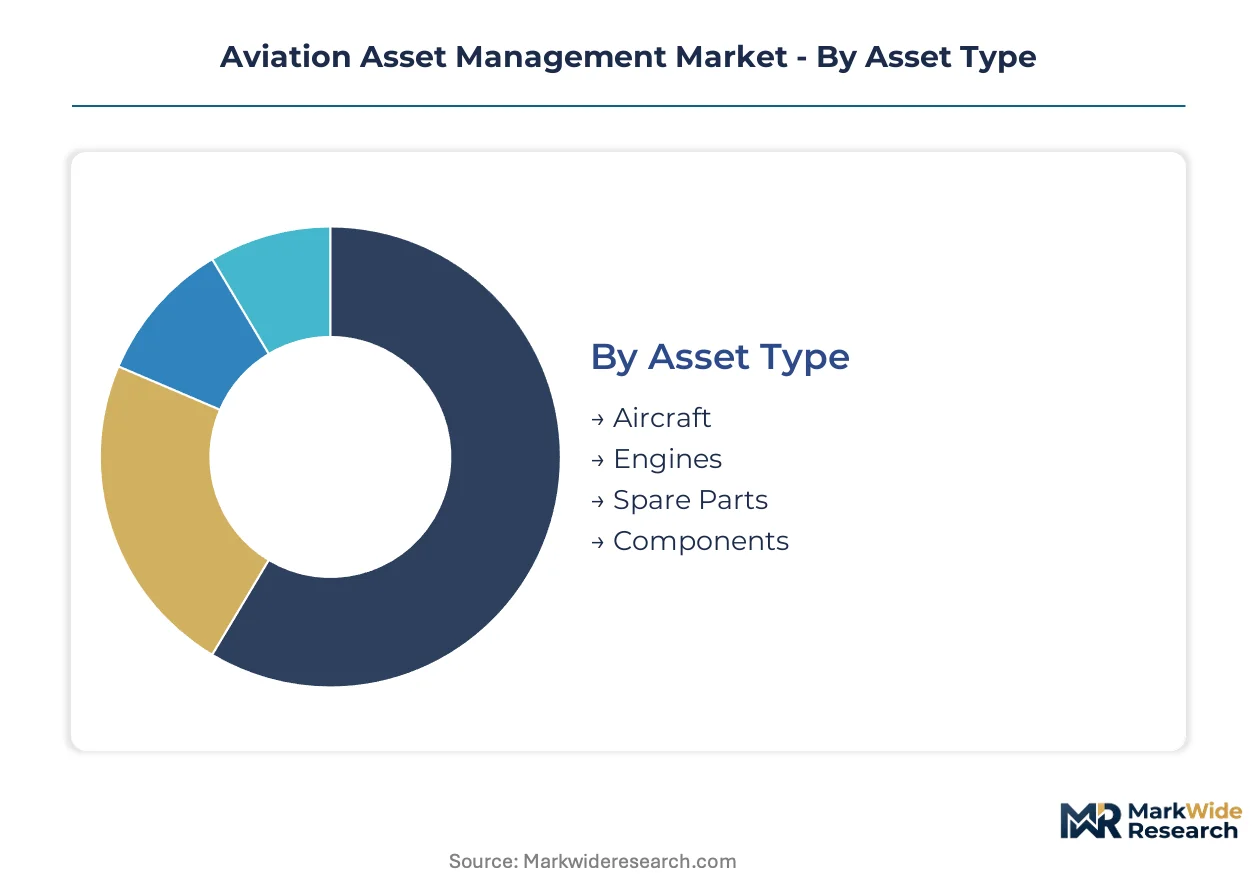
Segmentation in aviation asset management reveals how capital deployment, technical specialization, and client relationships stratify across distinct value pools. Understanding these divisions exposes where pricing power concentrates and where operational complexity erodes margins.
Asset Type:
Technical specifications and certification complexity differentiate capital intensity and residual value predictability across physical asset categories.
- Aircraft:Complete airframe platforms require continuous airworthiness directive compliance and heavy maintenance interval management. Demand concentrates among Irish-domiciled lessors structuring sale-leaseback transactions for Southeast Asian low-cost carriers seeking balance sheet flexibility.
- Engines:Powerplants generate recurring revenue through power-by-the-hour contracts and life-limited parts management. Lessors in Dublin leverage subscription-based health monitoring to reprice residual value guarantees and compress traditional PBH structures.
- Spare Parts:Component trading exploits arbitrage between OEM aftermarket pricing and independent certification pathways.
- Components:Rotable assemblies demand ATA chapter traceability systems spanning multiple regulatory jurisdictions.
Mature deployment sits with Aircraft. Newer deployment is concentrated in Engines.
Investment Strategy:
Capital structure preferences reflect risk tolerance and regulatory treatment across ownership models.
- Lease Financing:Operating leases dominate airline fleet planning by transferring residual value risk to lessor balance sheets. Dublin's specialized legal frameworks for enforceable security interest perfection attract capital deployment toward Irish special purpose vehicles serving global carrier networks.
- Ownership:Direct acquisition preserves full residual value capture but burdens balance sheets with depreciation obligations. Full-service carriers in India retain ownership for national flag operations while spinning narrowbody assets into lease structures.
- Joint Ventures:Risk-sharing partnerships between lessors and MRO providers integrate maintenance capacity with asset portfolios.
- Residual Value:Specialized funds trade anticipated end-of-lease valuations as standalone financial instruments.
Lease Financing commands institutional capital flows. Joint Ventures are expanding most quickly.
Service Type:
Operational intensity and labor rate arbitrage shape competitive positioning across technical service delivery.
- Maintenance:Scheduled inspection cycles mandated by FAA Airworthiness Directives and EASA Part-M frameworks dictate asset downtime and revenue loss calculations. Southeast Asian low-cost carriers disintermediate lessor-arranged maintenance to capture labor rate arbitrage through direct MRO contracting.
- Repair:Unscheduled component restoration requires specialized station approvals and dual compliance systems for mixed-registry portfolios.
- Overhaul:Heavy maintenance events compress asset utilization and trigger lease rate adjustment clauses.
- Consulting:Technical advisory services optimize fleet planning and end-of-life disposition strategies.
Maintenance absorbs the largest labor allocation. Consulting shows the steepest margin expansion trajectory.
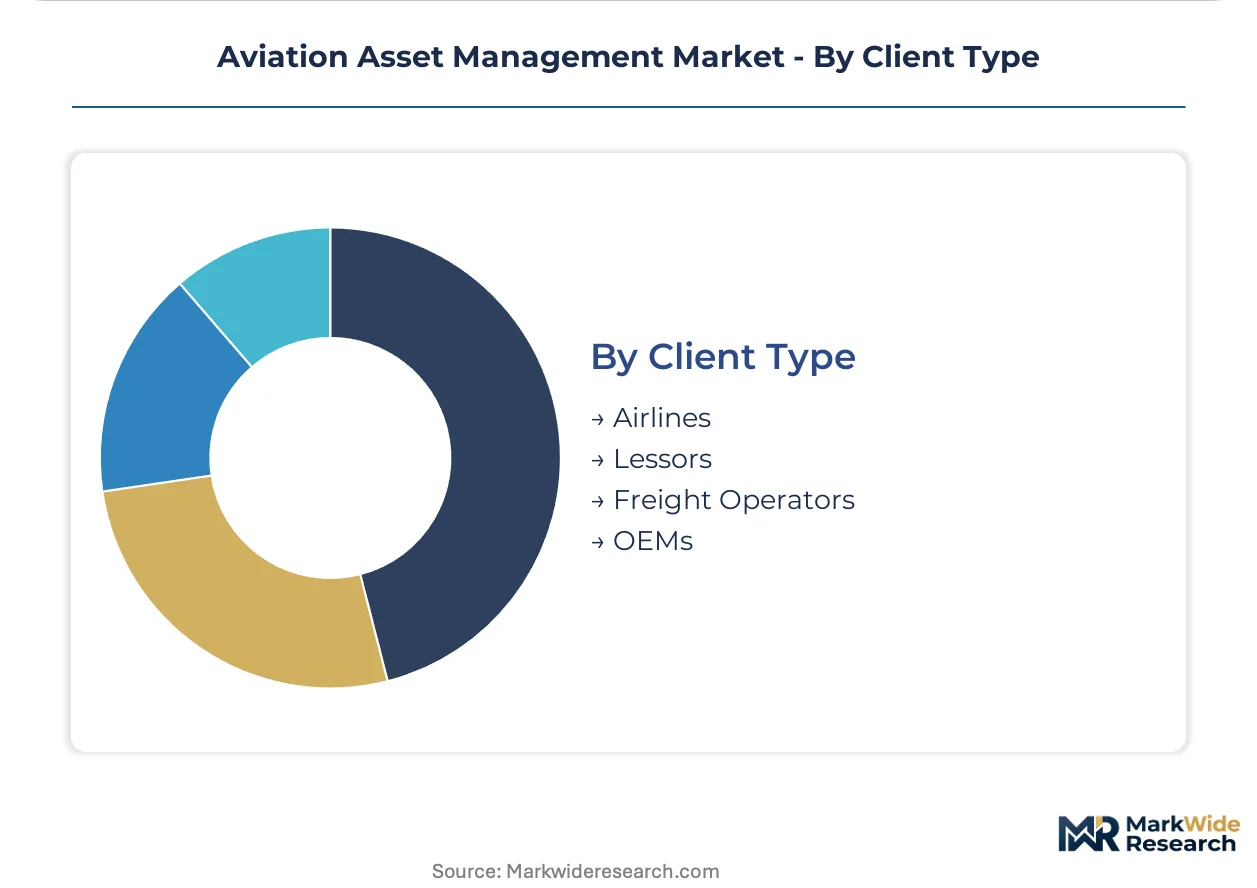
Client Type:
Procurement sophistication and regulatory exposure differentiate service requirements across stakeholder categories.
- Airlines:Operating carriers prioritize lease rate competitiveness and maintenance reserve structures over direct ownership. India's expanding domestic networks under PLI scheme incentives drive next-generation narrowbody lease demand.
- Lessors:Asset owners manage portfolio diversification across widebody and narrowbody exposures while monitoring carbon border adjustment impacts on legacy fuel-dependent valuations.
- Freight Operators:Cargo carriers seek converted freighter assets with modified maintenance intervals.
- OEMs:Manufacturers retain residual exposure through direct financing subsidiaries and parts aftermarket control.
Lessors anchor transaction volume. Freight Operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment concentrates in Ireland while operational demand radiates from Southeast Asian carrier networks. Production gravity in Dublin's legal and financial infrastructure contrasts with consumption intensity across Indonesia, Vietnam, and the Philippines. Lessors domiciled in Ireland structure sale-leaseback vehicles for airlines seeking balance sheet flexibility.
Ireland
Dublin's aircraft leasing cluster hosts special purpose vehicle incorporation for global lessor headquarters. The Irish Aviation Authority aligns with EASA Part-M continuing airworthiness standards while offering specialized oversight frameworks. Shannon and Dublin legal districts enforce security interest perfection mechanisms that attract institutional capital toward Irish-domiciled asset structures.
United States
The FAA's updated aging aircraft inspection protocols are reshaping maintenance scheduling for lessor portfolios with US-registered assets. Federal Airworthiness Directives mandate downtime cycles that compress utilization rates for legacy narrowbody fleets. Miami and Los Angeles MRO clusters absorb technical labor demand from Latin American carrier networks seeking FAA-certified repair station approvals.
Indonesia
Lion Air Group and Garuda Indonesia subsidiaries are expanding leased fleet portfolios under operating lease structures. The country's national aviation regulator enforces continuing airworthiness requirements aligned with ICAO standards. Jakarta's Soekarno-Hatta corridor concentrates maintenance demand from low-cost carriers prioritizing balance sheet flexibility over direct ownership.
Vietnam
VietJet Air and Bamboo Airways are accelerating narrowbody lease renewals to capture next-generation fuel efficiency gains. The Civil Aviation Authority of Vietnam implements inspection protocols harmonized with EASA technical guidance. Ho Chi Minh City's Tan Son Nhat maintenance zone is developing third-party MRO capacity to disintermediate lessor-arranged service structures.
India
IndiGo and Akasa Air are driving next-generation narrowbody lease demand under the government's PLI scheme for aviation manufacturing. The Directorate General of Civil Aviation enforces airworthiness directives with increasing convergence toward FAA and EASA standards. Delhi-NCR and Mumbai maintenance clusters are absorbing technical labor demand from expanding domestic carrier networks.
Aviation Asset Management Market Vendor Landscape
Top-tier vendors anchor widebody and narrowbody portfolio scale, while mid-tier specialists compete on regional market penetration and technical service bundling. The vendor base stratifies across three tiers: global lessors with multi-billion dollar asset portfolios, regional specialists with concentrated geographic exposure, and technical service providers integrating MRO capacity with asset management platforms. Strategic archetypes include scale-driven portfolio diversifiers, efficiency-focused narrowbody concentrators, and OEM-aligned delivery slot secured. Dominant competitive moves encompass direct manufacturer relationship cultivation for delivery priority and predictive maintenance technology integration to reprice residual value guarantees.
Within the scale-driven tier, AerCap Holdings N.V. and Air Lease Corporation exemplify portfolio breadth across aircraft and engine categories. SMBC Aviation Capital represents the narrowbody efficiency concentrator archetype with next-generation asset exposure. These entities occupy positions where subscription-based health monitoring and Dublin-domiciled legal structures create defensive moats against lease rate volatility.
| Leading Market Players |
|---|
| AerCap Holdings N.V. |
| Air Lease Corporation |
| SMBC Aviation Capital |
| BOC Aviation |
| Avolon |
| BBAM Aircraft Leasing and Management |
| GA Telesis |
| Aviation Asset Management |
| Acumen Aviation |
| Others |
Supply Flow & Price Mechanics
Airline procurement departments unbundling maintenance services from integrated lease packages force lessors to restructure contract economics and compress bundled pricing premiums. This disintermediation pressure cascades through supplier networks as third-party MRO providers capture labor rate arbitrage previously retained by full-service lessors.
Pricing Analysis
Margin tightening in power-by-the-hour contracts reflects subscription-based engine health monitoring displacing traditional flight-hour accumulations. Pricing stratifies across premium predictive maintenance tiers, standard calendar-based structures, and economy spot-repair arrangements differentiated by sensor integration depth and OEM certification lineage. Cost-down pressure on standard tiers accelerates because Southeast Asian low-cost carriers prioritize direct MRO contracting over lessor-arranged bundles. Freight operators exhibit lowest price sensitivity given converted freighter scarcity and modified maintenance interval premiums.
Supply Chain Analysis
Refurbishment flows for life-limited engine parts and rotable component exchanges anchor reverse logistics networks across Ireland, Singapore, and the United States. OEM aftermarket channels draw from proprietary parts certification, specialized repair station approvals, and ATA chapter traceability documentation spanning FAA, EASA, and CAAC jurisdictions. Single-source vulnerability concentrates in OEM-controlled proprietary component families with restricted independent certification pathways. Distribution runs through Dublin-domiciled lessor special purpose vehicles serving global carrier networks with enforceable security interest perfection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
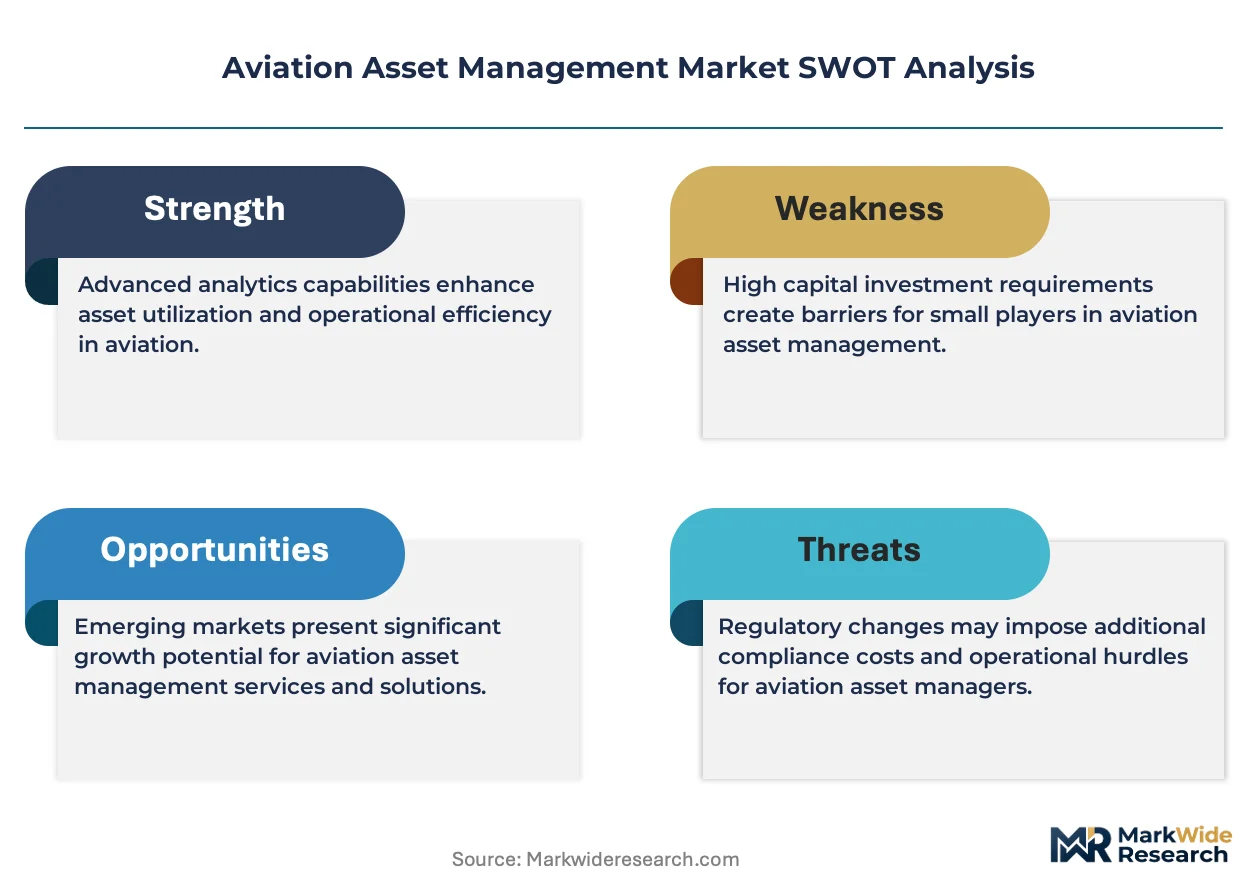
Aviation asset management sits in a technology-transition phase as predictive maintenance algorithms replace calendar-based inspection protocols and automate residual value adjustments.
For Market Incumbents: Extend predictive analytics integration across mixed-registry portfolios to defend pricing power against unbundling pressures from Southeast Asian low-cost carriers. Deepen backward integration into captive MRO capacity in India and Vietnam to capture labor rate arbitrage and retain full-service lease premiums. Vertical integration into blockchain component traceability systems addresses EASA Part-M documentation tightening. For New Entrants and Emerging Players: Digital twin convergence for narrowbody fleets offers a technology-first wedge into the India fleet modernization wave under PLI scheme incentives. White-space targets include independent spare parts trading arbitrage against OEM aftermarket pricing and third-party MRO capacity in Ho Chi Minh City's emerging maintenance zone. A direct contracting model with VietJet Air and Bamboo Airways bypasses incumbent lessor-arranged service structures. For Investors and Strategic Acquirers: The window for entry favors specialized asset managers with regulatory technology investments spanning FAA, EASA, and CAAC jurisdictions. Long-term viability hinges on carbon border adjustment positioning as SAF-compliant portfolios command premium lease rate tiers over legacy fuel-dependent assets. Monitor EU Green Deal mandate implementation velocity as the inflection signal for engine retrofit investment thresholds and residual value depreciation curve recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Sensor-derived health scores automate power-by-the-hour repricing and reduce unplanned downtime for Dublin-domiciled lessors. |
| SAF-Compliant Asset Portfolio Acquisition | Carbon border adjustment positioning secures premium lease rate tiers as EU Green Deal mandates tighten. |
| India MRO Capacity Joint Venture | PLI scheme incentives and expanding IndiGo narrowbody demand create captive maintenance arbitrage capture. |
| Blockchain Traceability System Integration | EASA Part-M documentation requirements and ATA chapter compliance complexity favor specialized regulatory technology investments. |
| Freighter Conversion Asset Positioning | Long-haul route recovery uncertainty and accelerated four-engine retirements compress twin-aisle residual values while converted freighter scarcity persists. |
Methodological Framework
Document review covered FAA Airworthiness Directives, EASA Part-M continuing airworthiness frameworks, and ICAO standards documentation, complemented by interviews with aircraft leasing portfolio managers, MRO procurement directors, airline fleet planning executives, and aviation regulatory compliance officers. Secondary validation drew from lessor SEC 10-K filings, OEM aftermarket pricing disclosures, and Irish Aviation Authority regulatory guidance. Bottom-up fleet deployment models triangulated against top-down capital flow analysis across the analysis window.
Market size outputs trace to segment-level deployment tracking across asset type, investment strategy, and service type dimensions, with geographic allocation calibrated to Dublin leasing cluster concentration and Southeast Asian carrier network expansion. CAGRs derive from lease rate trajectory modeling and residual value depreciation curve analysis incorporating sustainable aviation fuel mandate impacts. Forecast inputs include engine retrofit investment thresholds and power-by-the-hour contract restructuring velocity.
Several conditions sit outside the modeled scope, including sudden regulatory harmonization failures between FAA and EASA jurisdictions, and unanticipated OEM aftermarket pricing collusion enforcement. Forecasts reflect documented assumptions regarding ICAO standards convergence and continuing airworthiness directive implementation timelines. Practitioners should monitor EU carbon border adjustment mechanism rollout pace and SAF production scale-up velocity for early signals of asset valuation recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Narrowbody Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
North America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market