
 MRO Software Market | 2026-2036
MRO Software Market Size, Share, and Industry Trends Forecast 2026-2036
MRO Software Market Analysis
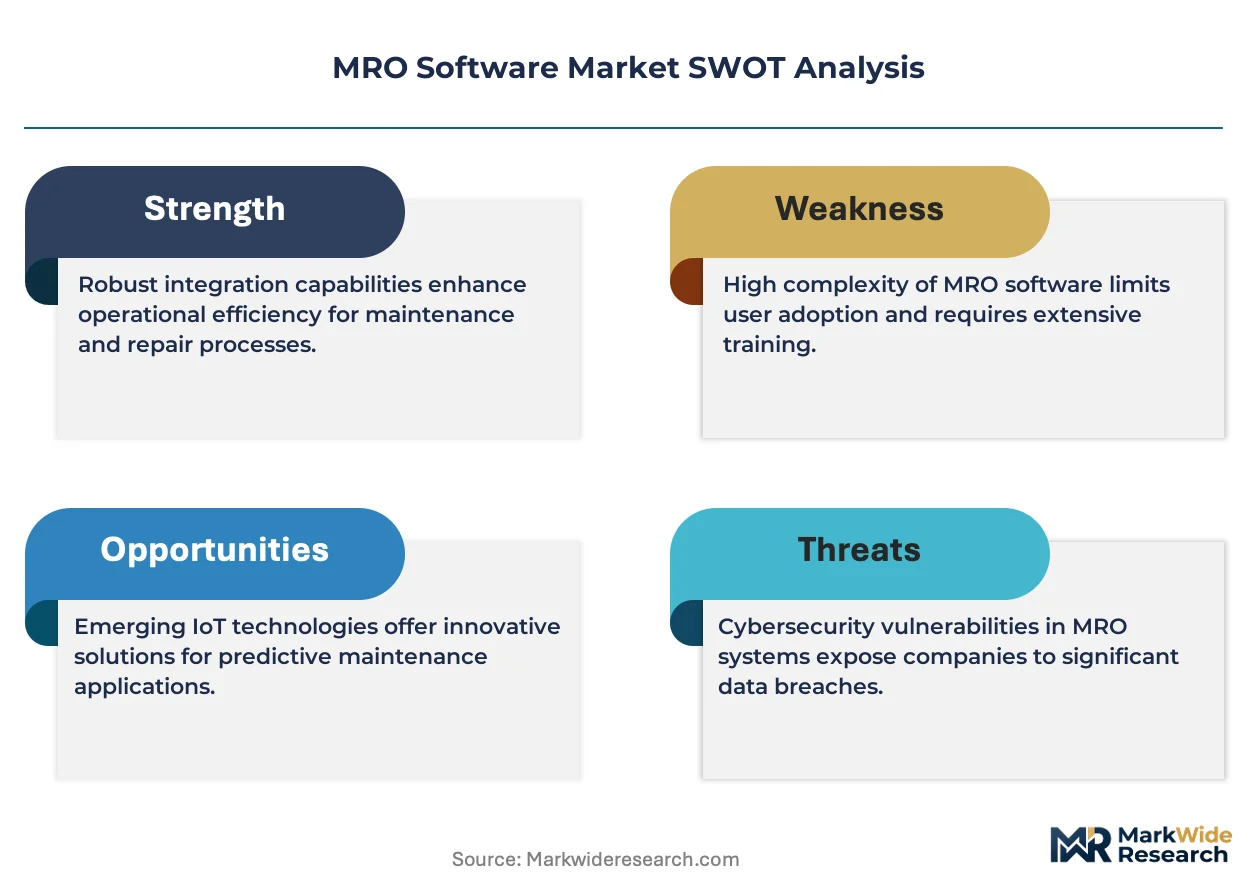
North American MRO capacity is fragmenting as legacy aviation hubs compete with emerging software clusters. IBM leverages deep enterprise integration to anchor defense and commercial aviation contracts. SAP SE sustains dominance in European manufacturing verticals through embedded ERP-MRO modules. Oracle Corporation differentiates via database-native analytics for fleet reliability engineering.
MRO software encompasses computerized maintenance management systems, predictive analytics engines, and spare parts inventory optimizers that orchestrate asset upkeep across physical infrastructure. These platforms integrate IoT sensor streams, work order automation, and compliance documentation to minimize unplanned downtime in capital-intensive operations. Cloud-based solutions are capturing the fastest expansion as aerospace operators abandon on-premises data centers for elastic compute. On-premises solutions retain margin concentration in defense and nuclear energy segments where air-gapped security protocols override cloud economics. Hybrid deployments are emerging as the structural compromise for energy utilities balancing legacy SCADA integration with modern analytics.
FAA airworthiness directives and EASA Part-M maintenance regulations are mandating digital audit trails for component traceability, forcing legacy paper-based operators toward certified software platforms. OSHA process safety management standards and EPA leak detection rules in US refineries are embedding MRO analytics into environmental compliance workflows. Stakeholders must weigh sovereign data residency requirements against multi-tenant cloud economies as defense and critical infrastructure buyers harden procurement criteria.
Market Dynamics
Cloud migration is compressing deployment cycles for MRO platforms as aerospace operators abandon capital-intensive data center infrastructure. FAA airworthiness directives now mandate digital audit trails, forcing legacy paper-based maintenance operations toward certified software architectures.
Growth Catalysts
- IoT sensor convergence:Industrial OEMs in Germany embed predictive analytics into legacy asset fleets. Real-time vibration monitoring reduces unplanned turbine downtime in energy utilities.
- FAA digital mandate:Component traceability requirements under airworthiness directives compel North American aviation operators to replace manual documentation systems with automated compliance platforms.
- Spare parts optimization:Machine learning algorithms now forecast inventory needs across distributed maintenance networks. Capital-intensive operators capture working capital efficiency through demand-sensing procurement.
Market Restraints
- Air-gapped security protocols:Defense and nuclear energy segments block cloud connectivity, constraining SaaS penetration. On-premises deployments carry higher total cost of ownership.
- Legacy SCADA integration friction:Energy utilities face technical debt from proprietary protocols incompatible with modern API architectures. Hybrid deployment complexity extends implementation timelines.
- Sovereign data residency mandates:Critical infrastructure procurement criteria in defense verticals fragment vendor addressable markets. Multi-tenant cloud economics clash with national security requirements.
Strategic Opportunities
- Small fleet aviation:Regional carriers and cargo operators in Southeast Asia remain underpenetrated by predictive maintenance platforms. Cloud-native solutions bypass capital barriers for mid-tier operators.
- EU Green Deal alignment:Embedded carbon tracking modules in MRO software capture maintenance-related emissions data. Industrial facilities use this documentation for CSRD compliance reporting.
- Digital twin convergence:Physics-based simulation layers merge with operational sensor streams. Asset-intensive industries simulate failure modes before physical intervention.
Industry Challenges
- Reliability engineering talent scarcity:Fleet analytics roles require hybrid competencies in data science and domain-specific maintenance protocols. Compensation inflation compresses vendor margins.
- Multi-system integration complexity:Enterprise ERP-MRO module synchronization demands specialized implementation partners. Project overruns erode customer lifetime value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRO Software Market |
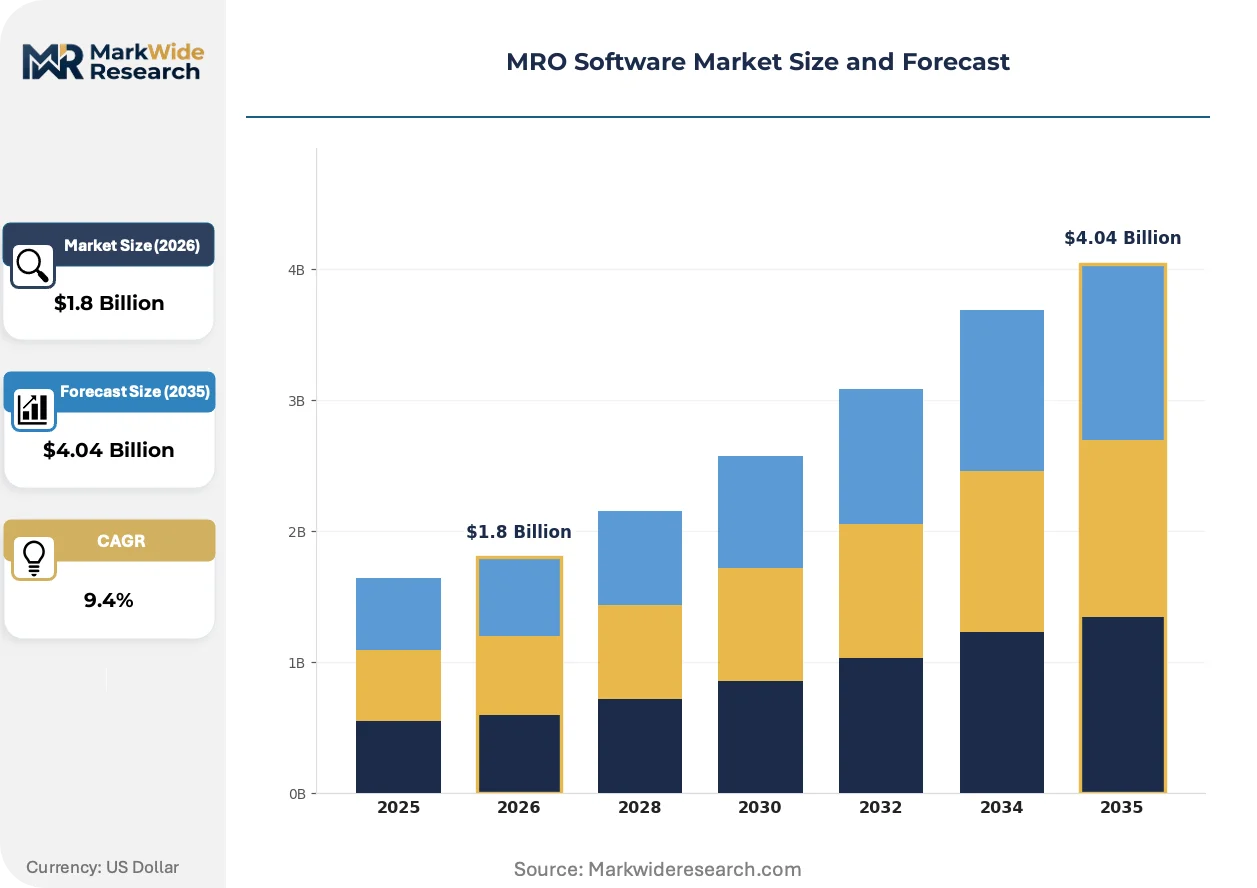
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premises Solutions, Hybrid Solutions, Mobile Applications End User: Aerospace, Manufacturing, Transportation, Energy Deployment: Public Cloud, Private Cloud, On-premise, Hybrid Cloud Service Type: Consulting Services, Support Services, Training Services, Maintenance Services |
| Companies Covered | IBM, SAP SE, HCL Technologies Limited, Oracle Corporation, IFS AB, Ramco Systems Limited, Infor, Trax, Swiss AviationSoftware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRO Software Market Emerging Trajectories
Generative AI is penetrating maintenance documentation workflows, automating regulatory report generation that previously consumed specialist labor hours. Edge computing architectures simultaneously reduce latency for time-critical failure detection.
Agentic AI systems now autonomously triage work order prioritization based on operational risk scoring. Commercial aviation maintenance control centers deploy these tools for overnight fleet turnaround decisions. Human-in-the-loop validation requirements is rendering obsolete fully manual dispatch protocols.
EASA Part-M maintenance regulations now enforce electronic record-keeping for component life-cycle traceability. European MRO providers must reconstruct decades of paper archives into structured databases. Smaller independent repair stations face compliance cost barriers that favor consolidated software platform adoption.
Subscription pricing models displace perpetual license structures across mid-market industrial buyers. Energy utilities and manufacturing operators prefer operational expenditure treatment for maintenance software. North American procurement teams now evaluate total cost of ownership over five-year horizons rather than upfront capital outlay.
MRO Software Market Segmentation
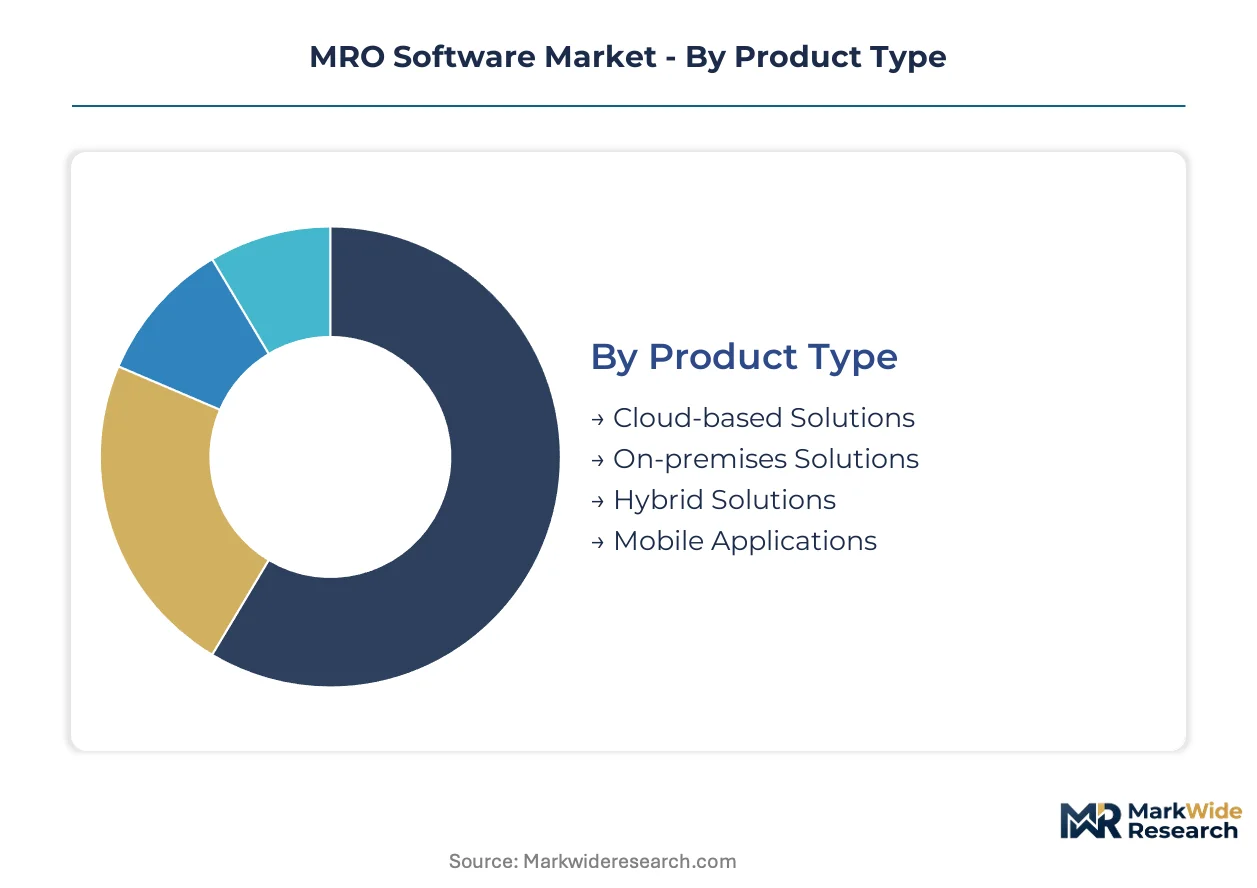
Segmentation in MRO software reveals how after-sales service intensity varies dramatically by deployment architecture and customer operational maturity. Vendors must align pricing models and implementation depth with each segment's technical debt profile and compliance burden.
Product Type:
After-sales service intensity peaks where legacy infrastructure demands continuous integration support and compliance validation.
- Cloud-based Solutions:Multi-tenant architectures with elastic compute provisioning serve aerospace operators abandoning capital-intensive data centers. German industrial OEMs modernizing legacy fleets drive concentration here, though FAA airworthiness directive compliance requires vendor-side certification overhead.
- On-premises Solutions:Air-gapped installations with localized data sovereignty controls dominate defense and nuclear energy procurement. Higher total cost of ownership reflects specialized security protocols and dedicated support staffing that SaaS economics cannot match.
- Hybrid Solutions:Split architectures bridge legacy SCADA integration with modern analytics layers.
- Mobile Applications:Field technician interfaces with offline synchronization capabilities for distributed maintenance networks.
Cloud-based solutions hold the largest share; momentum sits with hybrid deployments.
End User:
Customer operational maturity dictates whether vendors sell standardized modules or embedded enterprise integration.
- Aerospace:Fleet reliability engineering platforms with predictive analytics engines and component traceability documentation. FAA digital audit trail mandates in the United States and EASA Part-M regulations in Europe compel replacement of manual systems, concentrating demand among North American and German operators.
- Manufacturing:ERP-MRO module synchronization with embedded production line maintenance scheduling.
- Transportation:Vehicle fleet lifecycle management with route-integrated maintenance windows.
- Energy:Turbine and grid asset monitoring with environmental compliance workflows.
Aerospace commands premium pricing; manufacturing shows steepest expansion trajectory as industrial digitization accelerates.
Deployment:
Infrastructure location determines regulatory exposure and vendor margin structure.
- Public Cloud:Shared-tenant environments with consumption-based pricing attract mid-market industrial buyers seeking operational expenditure treatment.
- Private Cloud:Dedicated single-tenant instances with sovereign data residency controls serve critical infrastructure buyers in defense verticals.
- On-premise:Fully localized hardware stacks with perpetual licensing retain concentration where air-gapped security overrides connectivity economics.
- Hybrid Cloud:Workload portability between edge and centralized compute supports energy utility SCADA modernization.
Public cloud captures volume leadership; private cloud is gaining share fastest among regulated buyers.
Service Type:
Revenue recurrence depends on how deeply vendors embed in customer operational workflows.
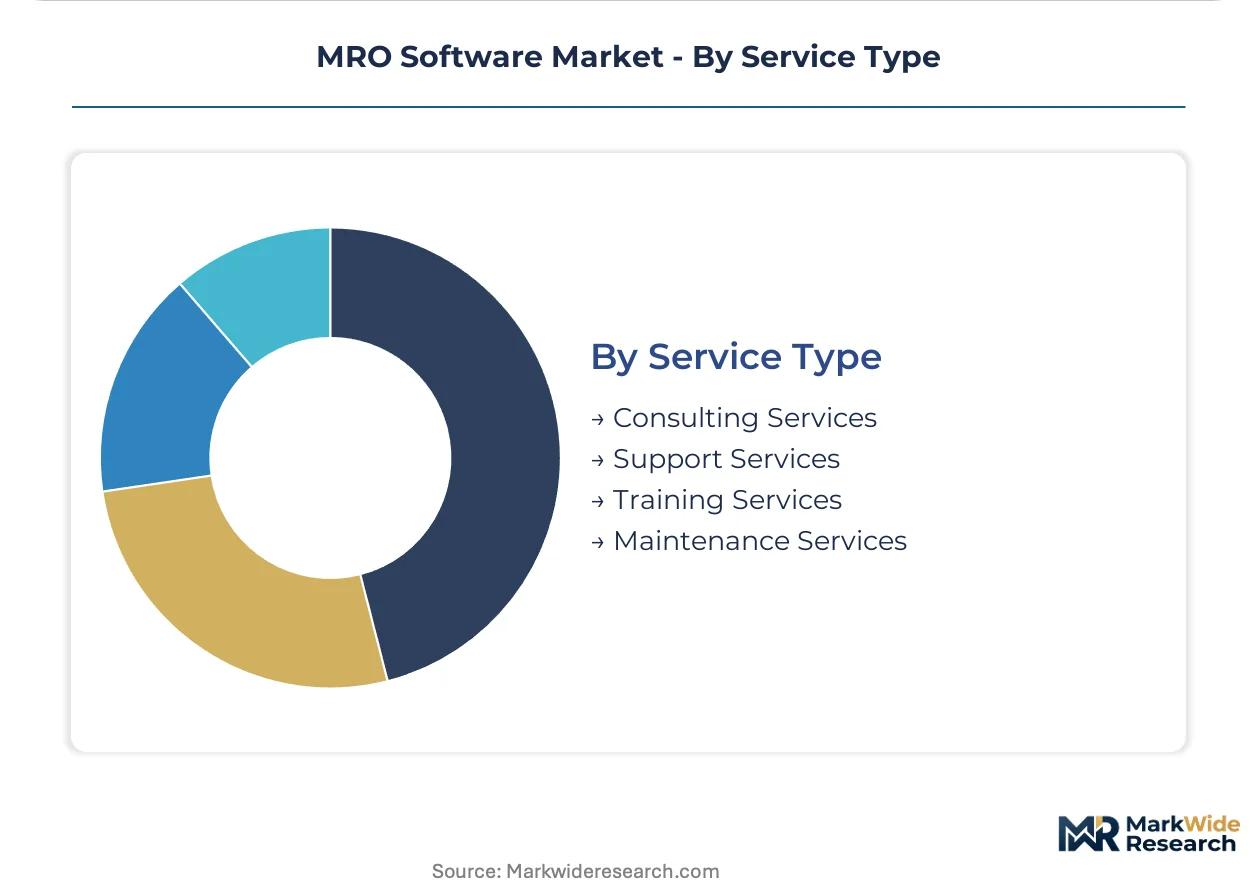
- Consulting Services:Business process reengineering and legacy system migration planning for paper-based operators transitioning to certified digital platforms.
- Support Services:Tiered technical assistance with guaranteed response times for 24/7 maintenance control centers.
- Training Services:Certification programs addressing reliability engineering talent scarcity through hybrid data science and domain protocol curricula.
- Maintenance Services:Platform updates and regulatory patch management ensuring continuous compliance with evolving FAA and EASA mandates.
Support services generate the most recurring revenue; consulting services show strongest growth as legacy digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform integrators cluster where aviation density and industrial OEM concentration overlap. Germany, the United States, Japan, the United Kingdom, and India each present distinct procurement patterns shaped by regulatory mandates and legacy infrastructure maturity.
United States
FAA airworthiness directives mandate digital audit trails for component traceability across commercial and defense fleets. OSHA process safety management standards embed MRO analytics into refinery environmental compliance workflows. Seattle and Wichita anchor aerospace software clusters where predictive maintenance platforms serve Boeing's supplier network and emerging urban air mobility operators.
Germany
Industrial OEMs modernizing legacy asset fleets drive cloud-based platform concentration. EU Green Deal alignment pressures facilities to document maintenance-related emissions for CSRD reporting. Munich and Stuttgart house automotive and industrial machinery software development centers where ERP-MRO module synchronization dominates procurement decisions.
Japan
METI industrial digitization programs subsidize predictive analytics adoption among small and medium manufacturers. JIS standards for maintenance data interoperability reduce integration friction for legacy equipment. Nagoya's aerospace corridor and Osaka's machinery belt concentrate vendor implementation partnerships for hybrid deployment architectures.
United Kingdom
EASA Part-M maintenance regulations enforce electronic record-keeping for component life-cycle traceability. CAA safety management system requirements parallel FAA mandates for digital documentation. London's financial-technology nexus and Bristol's aerospace engineering cluster split demand between SaaS procurement platforms and specialized aviation software.
India
PLI scheme incentives for aircraft component manufacturing expand MRO software demand among tier-one suppliers. DGFT export promotion programs accelerate software services outsourcing from aviation technology centers. Bangalore and Hyderabad host development operations for global platform vendors serving regional carrier digitization initiatives.
MRO Software Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in predictive analytics and mobile field interfaces. The vendor structure concentrates around three to five full-stack providers with embedded ERP integration capabilities, while dozens of niche operators fragment across vertical-specific compliance modules. Two strategic archetypes dominate: enterprise software conglomerates leveraging existing customer relationships, and pure-play aviation specialists with certified regulatory workflows. Competitive moves center on cloud migration service bundling and strategic partnerships with industrial OEMs for embedded deployment.
Within the enterprise platform tier, IBM and SAP SE represent archetypal approaches to defense and manufacturing verticals respectively. Oracle Corporation occupies a position emphasizing database-native analytics for fleet reliability engineering. Swiss AviationSoftware exemplifies the specialized aviation pure-play model with concentrated regulatory certification depth.
| Leading Market Players |
|---|
| IBM |
| SAP SE |
| HCL Technologies Limited |
| Oracle Corporation |
| IFS AB |
| Ramco Systems Limited |
| Infor |
| Trax |
| Swiss AviationSoftware |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure concentration in the United States and Germany anchors margin capture for SaaS-native MRO vendors, while on-premises security specialists extract premiums from defense buyers unwilling to accept multi-tenancy economics. Subscription pricing models now dominate mid-market procurement, displacing perpetual licenses as energy utilities and manufacturing operators shift capital expenditure to operational treatment.
Pricing Analysis
FAA airworthiness directives and EASA Part-M regulations dictate the pricing tier structure by mandating certified compliance modules that separate audit-ready platforms from uncertified alternatives. Three-tier pricing stratifies across premium certified suites, standard cloud-native offerings, and economy field-mobile tools. Price differentiation hinges on certification depth and vertical integration with ERP systems. Pricing pressure stems from open-source analytics commoditizing basic predictive maintenance features. Regional carriers in Southeast Asia exhibit highest price sensitivity; defense contractors demonstrate lowest.
Supply Chain Analysis
Contract manufacturing for MRO software concentrates among specialized aviation technology integrators in Switzerland, Germany, and the United States with regulatory certification depth. Core dependencies include cloud compute capacity from hyperscalers, IoT sensor hardware from industrial automation suppliers, and compliance documentation templates from aviation regulatory consultants. Single-source vulnerability concentrates in certified regulatory workflow engines where FAA and EASA accreditation creates switching barriers. Distribution runs through direct enterprise sales for large fleet operators and channel partners serving mid-tier industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as aerospace fleet operators consolidate vendor relationships and demand bundled cloud-migration services, fragmenting addressable markets for point-solution specialists.
For Market Incumbents: Insulate certified regulatory workflows from SaaS commoditization by deepening FAA and EASA accreditation moats. Vertical integration into edge computing hardware for air-gapped defense deployments captures margins unavailable to pure-software competitors. Threat substitution from generative AI documentation tools demands preemptive embedding of autonomous maintenance triage capabilities. For New Entrants and Emerging Players: Establish a beachhead in Southeast Asian regional aviation where predictive maintenance penetration remains underdeveloped and capital barriers favor cloud-native solutions. Target cargo operators and urban air mobility fleets with modular subscription pricing that bypasses enterprise procurement cycles. Go-to-market leverage rests on partnerships with industrial OEMs embedding analytics into new equipment sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures as multi-tenant economics improve. Long-term viability favors platforms with embedded ERP integration capabilities and regulatory certification depth rather than point-solution analytics vendors. Acquisition target archetype: specialized aviation compliance modules with FAA/EASA accreditation. Signal to watch: defense procurement shifts toward hybrid cloud architectures relaxing air-gapped mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-MRO module synchronization captures manufacturing verticals in Germany and Japan. |
| Regulatory Certification Investment | FAA and EASA accreditation creates switching costs for commercial aviation fleet contracts. |
| Strategic Partnership with Industrial OEMs | Embedded deployment in new equipment sales bypasses lengthy enterprise procurement cycles. |
| Geographic Expansion | Southeast Asian regional carriers offer white-space demand for cloud-native predictive maintenance. |
| Acquisition of Specialist Firm | Compliance documentation modules with airworthiness directive expertise fill portfolio gaps. |
Methodological Framework
Initial hypotheses were tested against primary input from maintenance control center directors, aviation regulatory compliance officers, IT procurement leads at industrial OEMs, and enterprise software integration specialists, then refined through secondary validation. Primary research drew from FAA airworthiness directive filings, EASA Part-M compliance databases, hyperscaler cloud infrastructure disclosures, and industrial digitization program documentation from METI and EU Green Deal reporting. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Demand-supply balance framing anchored the forecast framework, modeling deployment architecture, end-user vertical, organization size, integration complexity, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from elasticity-weighted adoption curves calibrated to compliance mandate timelines and cloud migration velocity. Industry-specific inputs included fleet expansion trajectories from aviation manufacturing data and SCADA modernization investment cycles from utility regulatory filings.
Stress conditions across cloud infrastructure cost inflation, defense procurement security protocol shifts, and reliability engineering talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts embed assumptions about regulatory mandate enforcement continuity and hyperscaler pricing stability. Quarterly review of FAA airworthiness directive issuance velocity and EASA Part-M compliance deadline adherence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Middle-East Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Airplane Pushback Tug Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market