
 Aircraft Recycling Market | 2026-2036
Aircraft Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Recycling Market Analysis
The EU Green Deal is expanding compliance obligations for aircraft end-of-life processing across European Union member states. CAVU Aerospace leverages its dismantling infrastructure to capture high-value aluminum and titanium streams from retired commercial fleets. GA Telesis LLC sustains a global parts recovery network that connects disassembly yards with aftermarket buyers across multiple continents. Air Salvage International Ltd anchors its operations in the United Kingdom, specializing in complete teardown and material segregation for narrow-body and wide-body platforms.
Aircraft recycling encompasses the systematic dismantling, material recovery, and component reclamation of retired commercial, military, and cargo aircraft, typically involving the extraction of aerospace-grade aluminum alloys, titanium structures, and heat-resistant steel alloys through flame-cutting, mechanical shredding, and chemical separation processes. The primary purpose is to return certified airworthy components to the aviation aftermarket while channeling structural metals back into industrial smelting streams. Aluminum dominates material type recovery volumes due to its prevalence in older fuselage construction, though composites represents the fastest-expanding recovery challenge as carbon-fiber-reinforced polymer content rises in newer generation aircraft. Dismantling and parts recovery generate the deepest margin pools within process type segmentation, driven by OEM traceability requirements and MRO demand for cost-effective replacement units.
The European Union Aviation Safety Agency works alongside REACH and the EU Green Deal to mandate documented chain-of-custody for hazardous materials including hydraulic fluids, fire suppressants, and composite resins during aircraft disassembly. The EPA in the United States enforces parallel requirements under RCRA for proper handling of chromium compounds and depleted beryllium assemblies encountered in older airframes. Stakeholders must monitor evolving certification standards for reclaimed avionics and landing gear components as regulators on both sides of the Atlantic tighten documentation requirements for circular economy participation.
Market Dynamics
Fleet renewal cycles are compressing as next-generation narrow-body platforms replace aging aluminum-intensive airframes, concentrating dismantling demand in specialized facilities with certified hazardous-material handling capabilities.
Growth Catalysts
- EU F-Gas Regulation:Mandates documented recovery of fluorinated greenhouse gases from fire suppression systems and air conditioning units during aircraft teardown, creating compliance-driven service demand across member states.
- Aerospace-grade titanium recovery:Heat-resistant alloys from engine nacelles and landing gear assemblies command premium smelter prices, incentivizing investment in precision flame-cutting and non-destructive testing infrastructure.
- France:TARMAC Aerosave and the Tarbes-Lourdes-Pyrénées dismantling cluster have established Europe's densest concentration of certified storage, disassembly, and parts-tagging capacity.
Market Restraints
- Specialized labor scarcity:Certified aircraft dismantlers with airframe-specific expertise and hazardous-material handling credentials face recruitment bottlenecks in aviation hubs.
- Composite resin disposal costs:Carbon-fiber-reinforced polymers from newer-generation fuselages require thermal decomposition or chemical solvolysis, lacking established industrial-scale processing pathways.
- REACH documentation burden:European chemical registration requirements impose traceability costs on reclaimed hydraulic fluids and sealants that exceed recovery value for smaller operators.
Strategic Opportunities
- India:Expanding MRO infrastructure at Hyderabad and Bengaluru creates demand for localized component reclamation and aluminum alloy reprocessing to feed domestic aerospace forging supply chains.
- Avionics remanufacturing:Circular economy mandates under the EU Green Deal position certified refurbished flight control computers and navigation systems as cost-competitive alternatives to new OEM units.
- Blockchain-traceable parts tagging:Immutable chain-of-custody records for reclaimed landing gear and auxiliary power units address insurer and regulator documentation requirements.
Industry Challenges
- Airworthiness certification timelines:FAA and EASA validation of reclaimed structural components requires extensive non-destructive testing protocols that extend inventory holding periods.
- Legacy airframe documentation gaps:Incomplete maintenance records for aircraft manufactured before digital logging standards complicate traceability requirements for re-entry into aftermarket channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Recycling Market |
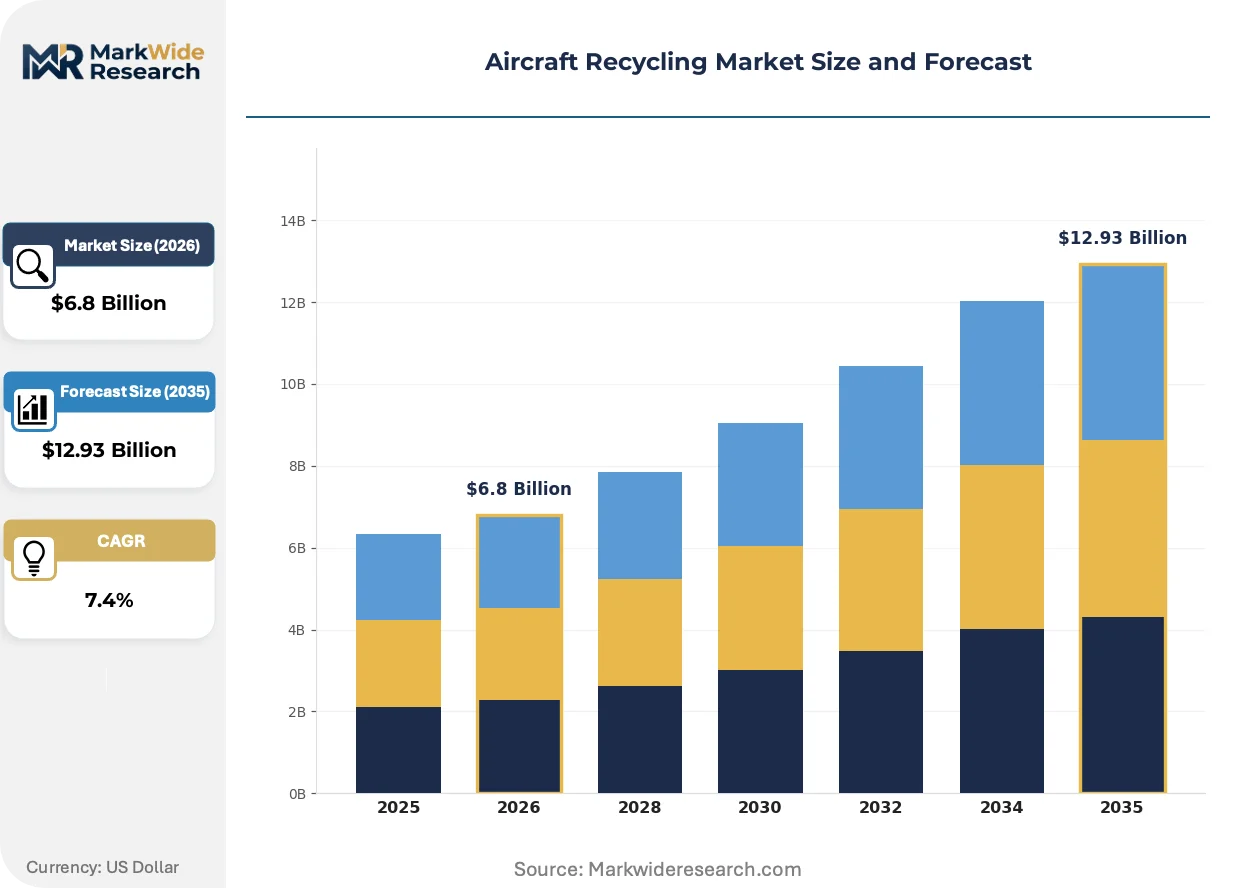
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Titanium, Composites Process Type: Demilitarization, Dismantling, Parts Recovery, Waste Management End User: OEMs, MROs, Airlines, Brokers Component: Fuselage, Wings, Landing Gear, Avionics |
| Companies Covered | Aviation International Recycling LLC, CAVU Aerospace, Aircraft Solutions USA, GA Telesis LLC, Air Salvage International Ltd, TARMAC Aerosave, Vallair Solutions, Ecube Solutions Ltd, AELS (Aircraft End-of-Life Solutions), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Recycling Market Emerging Trajectories
Digital dismantling workflows and automated material identification systems are compressing teardown timelines while improving alloy segregation purity, reshaping facility economics and competitive positioning.
Robotic water-jet cutting systems for aluminum fuselage sectioning are consolidating dismantling throughput in high-volume European facilities. Specialized yards in France and Germany deploy six-axis robotic arms with abrasive slurry injection to separate stringer-frame assemblies without thermal damage to surrounding titanium fittings. This automation compresses narrow-body teardown from twelve weeks to under seven, enabling fixed-cost absorption across more airframes annually.
The EPA's RCRA hazardous waste manifesting requirements for chromium compounds and depleted beryllium assemblies are tightening documentation standards for US-based dismantling operations. Facilities must now maintain cradle-to-grave tracking for cadmium-plated fasteners and legacy fire-suppressant reservoirs, elevating compliance costs for independent operators without integrated environmental services capabilities. Smaller yards in Arizona and California are consolidating into regional networks to share certified waste handling infrastructure.
Airline procurement departments are unbundling teardown contracts from original equipment manufacturer buyback agreements, creating direct relationships with specialized dismantlers. Carriers now negotiate separate agreements for airframe disassembly, component certification, and metal scrap aggregation, compressing intermediary margins previously captured by OEM asset management divisions. This disintermediation is most visible among European low-cost carriers with centralized fleet planning functions in Ireland and the United Kingdom.
Aircraft Recycling Market Segmentation
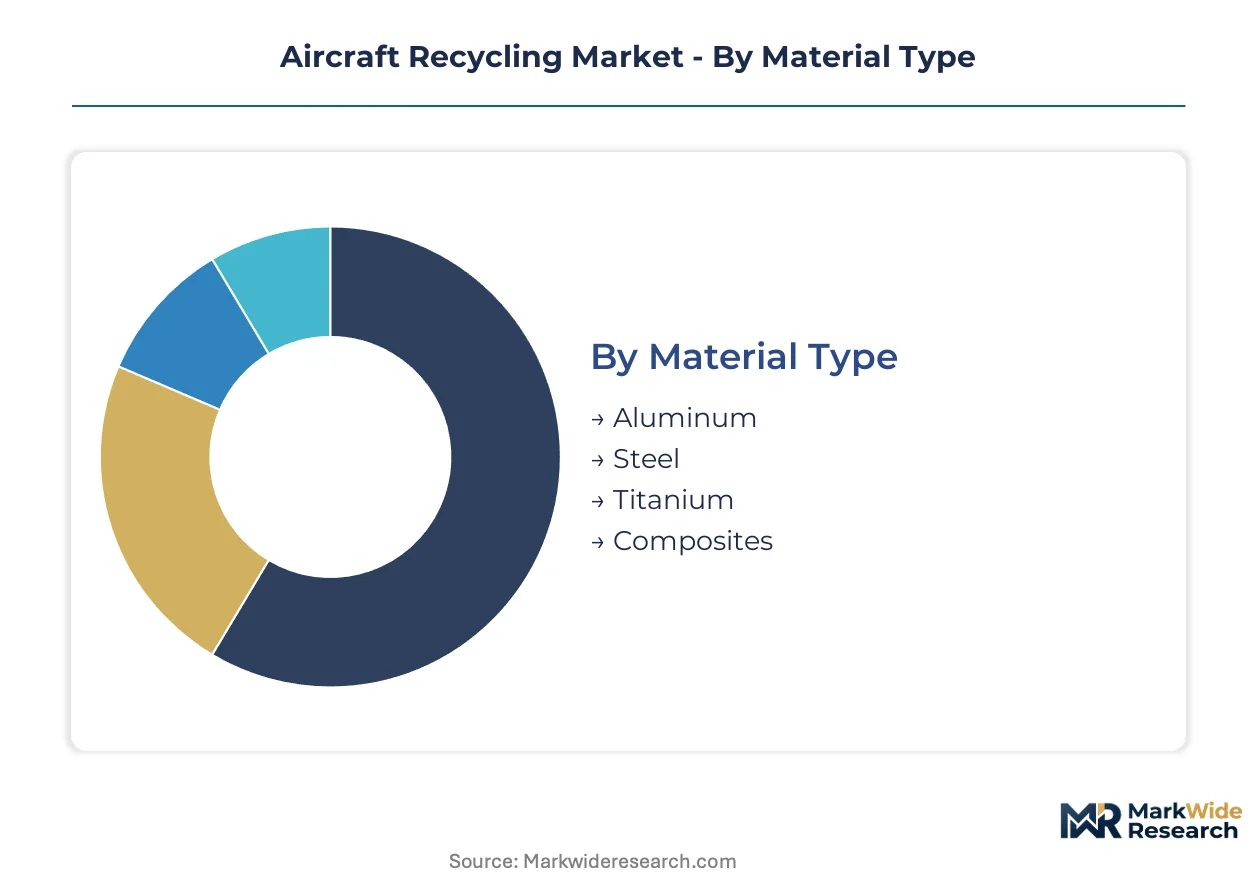
Segmentation in aircraft recycling reveals how fleet renewal cycles concentrate value capture across distinct material streams, processing capabilities, and customer relationships. Each dimension exposes different margin pools and compliance burdens as operators navigate tightening environmental mandates and evolving airworthiness documentation standards.
Material Type:
Fleet renewal compressing replacement timelines is redistributing recovery economics across metallic and non-metallic waste streams from retired airframes.
- Aluminum:Aerospace-grade aluminum alloys constitute the dominant recovery volume from older fuselage construction, with smelter-ready purity requirements driving investment in mechanical shredding and eddy-current separation infrastructure. Demand concentrates in French dismantling clusters where TARMAC Aerosave feeds specialized aluminum reprocessing into domestic aerospace forging supply chains.
- Titanium:Heat-resistant alloys from engine nacelles and landing gear assemblies command premium pricing due to aerospace-specific metallurgical specifications and limited secondary supply sources. Recovery in Germany and France targets precision flame-cutting to preserve alloy integrity for direct remelting rather than downcycling.
- Steel:High-strength steel alloys from landing gear and structural fittings require specialized handling for chromium and nickel content traceability under REACH documentation protocols.
- Composites:Carbon-fiber-reinforced polymers from newer-generation fuselages present unresolved processing challenges, with thermal decomposition and chemical solvolysis pathways still scaling toward industrial viability.
Volume placements concentrate in aluminum; the faster expansion belongs to composites as next-generation aircraft penetrate retirement queues.
Process Type:
Customer procurement unbundling teardown contracts from OEM buyback agreements is fragmenting service demand across discrete processing stages with diverging margin profiles.
- Dismantling:Systematic airframe disassembly with certified hazardous-material handling generates the deepest margin pools, requiring EPA RCRA compliance for chromium compounds and EU F-Gas Regulation adherence for fluorinated greenhouse gas recovery. Facilities in the United Kingdom and France capture value through robotic water-jet cutting systems that compress narrow-body teardown timelines.
- Parts Recovery:Component reclamation with OEM traceability documentation connects disassembly yards with MRO demand for cost-effective replacement units, governed by EASA and FAA airworthiness certification timelines that extend inventory holding periods.
- Demilitarization:Military aircraft processing involves classified material destruction protocols and defense-specific chain-of-custody requirements that limit facility participation.
- Waste Management:Residual stream handling for hydraulic fluids, sealants, and composite resins imposes REACH documentation burdens that exceed recovery value for smaller independent operators.
Margin capture peaks in dismantling and parts recovery; regulatory compliance costs are climbing fastest in waste management as documentation requirements tighten.
End User:
Procurement centralization among fleet operators is reshaping contractual relationships and pricing power across the dismantling value chain.
- Airlines:Direct teardown contract negotiation with specialized dismantlers compresses intermediary margins previously captured by OEM asset management divisions, particularly visible among European low-cost carriers with centralized fleet planning functions.
- MROs:Maintenance, repair, and overhaul operators drive demand for certified reclaimed components with documented traceability, sourcing from dismantling networks with established parts-tagging and blockchain-traceable custody systems.
- OEMs:Original equipment manufacturers retain residual buyback agreements for newer-generation aircraft but face disintermediation pressure as carriers unbundle service packages.
- Brokers:Intermediary traders in reclaimed avionics and landing gear components navigate tightening insurer and regulator documentation requirements for circular economy participation.
Contract volume aggregates with airlines; documentation sophistication requirements are advancing most rapidly for MROs as certification standards tighten.
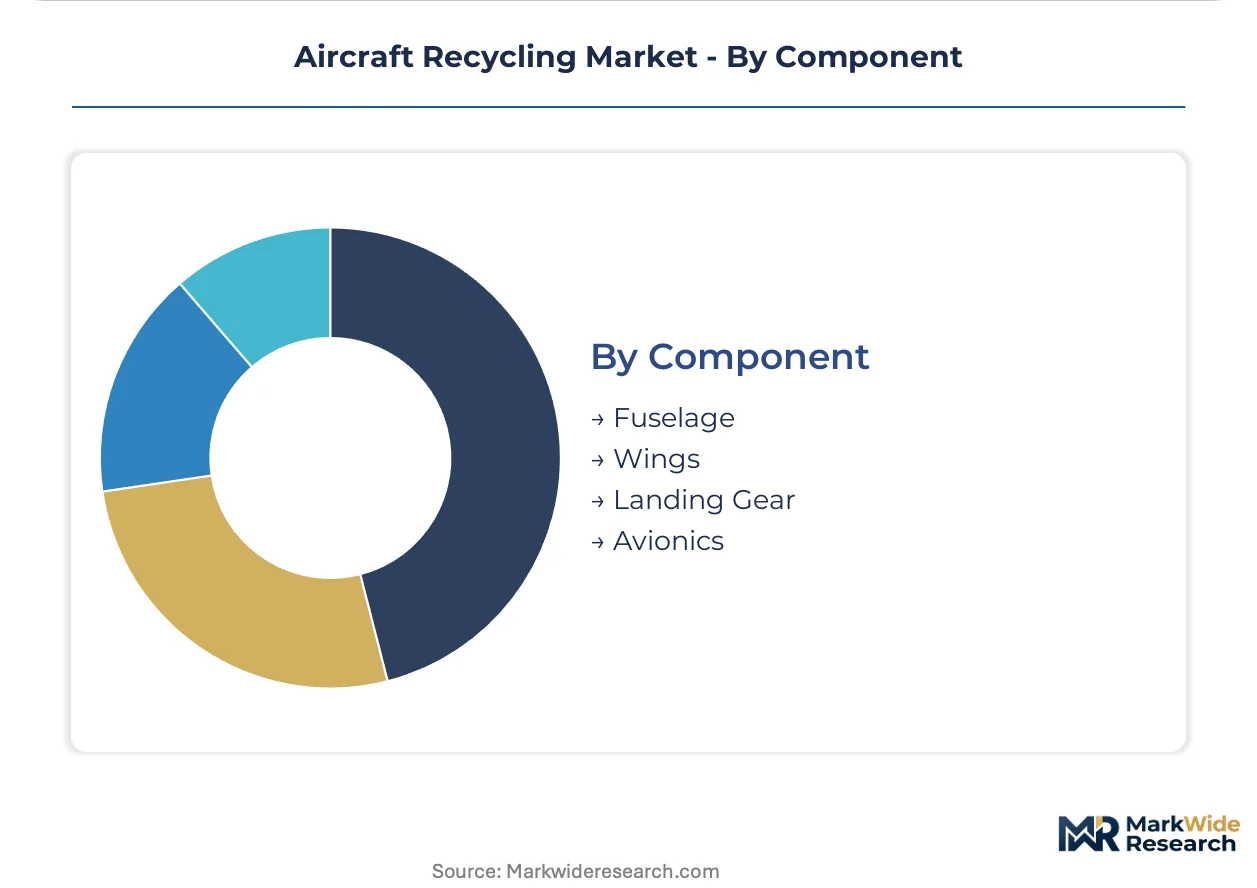
Component:
Physical distribution of recoverable value across airframe systems determines facility specialization and capital equipment deployment.
- Landing Gear:High-value assemblies with extensive titanium and heat-resistant steel content command premium dismantling attention, with non-destructive testing infrastructure required for re-entry into aftermarket channels.
- Avionics:Flight control computers and navigation systems face evolving certification standards for remanufacturing under EU Green Deal circular economy mandates, positioning refurbished units as cost-competitive alternatives.
- Fuselage:Primary structural sections dominate aluminum recovery volumes but require efficient sectioning workflows to achieve smelter-ready purity specifications.
- Wings:Composite-intensive structures from newer aircraft designs present emerging recovery challenges as carbon-fiber-reinforced polymer content rises.
Value recovery concentrates in landing gear; regulatory attention is intensifying fastest around avionics as airworthiness documentation requirements evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tarbes-Lourdes-Pyrénées in southwestern France hosts Europe's densest concentration of certified aircraft dismantling capacity, with TARMAC Aerosave anchoring a technical cluster that processes narrow-body and wide-body retirements from carriers across the continent.
France
Fleet renewal acceleration by Air France-KLM and low-cost carriers drives dismantling demand toward the Tarbes-Lourdes-Pyrénées cluster. The EU F-Gas Regulation mandates documented fluorinated gas recovery during teardown, elevating compliance requirements for facilities. TARMAC Aerosave operates integrated storage, disassembly, and parts-tagging infrastructure that feeds specialized aluminum reprocessing into domestic aerospace forging supply chains.
United States
Major carriers including Delta and American Airlines are unbundling teardown contracts from OEM buyback agreements, creating direct procurement relationships with dismantlers. The EPA enforces RCRA hazardous waste manifesting for chromium compounds and depleted beryllium assemblies encountered in older airframes. Arizona and California host consolidating regional networks where smaller yards share certified waste handling infrastructure to absorb elevated compliance costs.
Germany
Lufthansa Technik's MRO operations generate sustained demand for certified reclaimed components with full traceability documentation. REACH chemical registration requirements impose traceability costs on reclaimed hydraulic fluids and sealants that challenge smaller operators. Precision flame-cutting facilities in Hamburg and Frankfurt target titanium recovery from engine nacelles and landing gear assemblies for direct remelting rather than downcycling.
United Kingdom
British Airways and easyJet centralized fleet planning functions are reshaping contractual relationships with dismantling service providers. Air Salvage International Ltd anchors operations specializing in complete teardown and material segregation for both narrow-body and wide-body platforms. The Cotswolds region maintains dismantling yards with established parts-tagging infrastructure connecting to European MRO demand.
India
Expanding MRO infrastructure at Hyderabad and Bengaluru creates localized demand for component reclamation and aluminum alloy reprocessing. The country's national aviation regulator tightens documentation standards for circular economy participation by reclaimed parts entering domestic aftermarket channels. Specialized dismantling partnerships are forming around Bengaluru's aerospace manufacturing corridor to feed forging supply chains serving both commercial and defense programs.
Aircraft Recycling Market Vendor Landscape
The competitive structure tilts toward integrated dismantling specialists with certified hazardous-material handling capabilities and established OEM traceability documentation systems. Player concentration clusters around facilities with EPA RCRA compliance in North America and EU F-Gas Regulation adherence in Europe, creating geographic moats for incumbents. Two archetypes dominate: full-service dismantlers with robotic water-jet cutting automation, and component recovery specialists with non-destructive testing infrastructure for airworthiness certification. Competitive moves center on M&A consolidation of regional yard networks and backward integration into aluminum reprocessing to capture smelter premium pricing.
Among European integrated dismantlers, TARMAC Aerosave and Air Salvage International Ltd exemplify the full-service archetype with established storage-to-disassembly workflows. CAVU Aerospace occupies a position representing North American dismantling infrastructure leveraged for high-value aluminum and titanium stream recovery. GA Telesis LLC sits within the component recovery tier, sustaining global parts recovery networks that connect disassembly yards with aftermarket buyers across multiple continents.
| Leading Market Players |
|---|
| Aviation International Recycling LLC |
| CAVU Aerospace |
| Aircraft Solutions USA |
| GA Telesis LLC |
| Air Salvage International Ltd |
| TARMAC Aerosave |
| Vallair Solutions |
| Ecube Solutions Ltd |
| AELS (Aircraft End-of-Life Solutions) |
| Others |
Supply Flow & Price Mechanics
Airline procurement centralization among European low-cost carriers with fleet planning functions in Ireland and the United Kingdom drives value-based teardown contracts tied to certified component recovery yields and documented material segregation purity.
Pricing Analysis
Outcome-based pricing tied to certified airworthiness documentation and smelter-ready aluminum purity anchors contract structures in this market. Price differentiation separates full-service dismantlers with robotic water-jet automation from component recovery specialists with non-destructive testing infrastructure. Cost compression in waste management streams is intensifying because REACH documentation burdens for hydraulic fluids and sealants exceed recovery value for smaller independent operators. MRO procurement teams demonstrate highest price sensitivity due to compressed replacement part budgets, while OEM asset management divisions retain leverage for newer-generation aircraft buyback agreements.
Supply Chain Analysis
Dual-sourcing requirements from EASA and FAA for certified reclaimed landing gear and avionics components mandate multi-facility qualification across dismantling networks. Supply concentrates in France, the United Kingdom, and Germany, where TARMAC Aerosave, Air Salvage International Ltd, and Lufthansa Technik operations feed specialized aluminum and titanium streams into aerospace forging supply chains. Raw material recovery draws from aerospace-grade aluminum alloys, heat-resistant titanium structures, and chromium-nickel steel assemblies. Single-source vulnerability persists for precision flame-cutting infrastructure capable of preserving alloy integrity. Distribution runs through direct airline procurement relationships and MRO component sourcing networks with blockchain-traceable custody systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
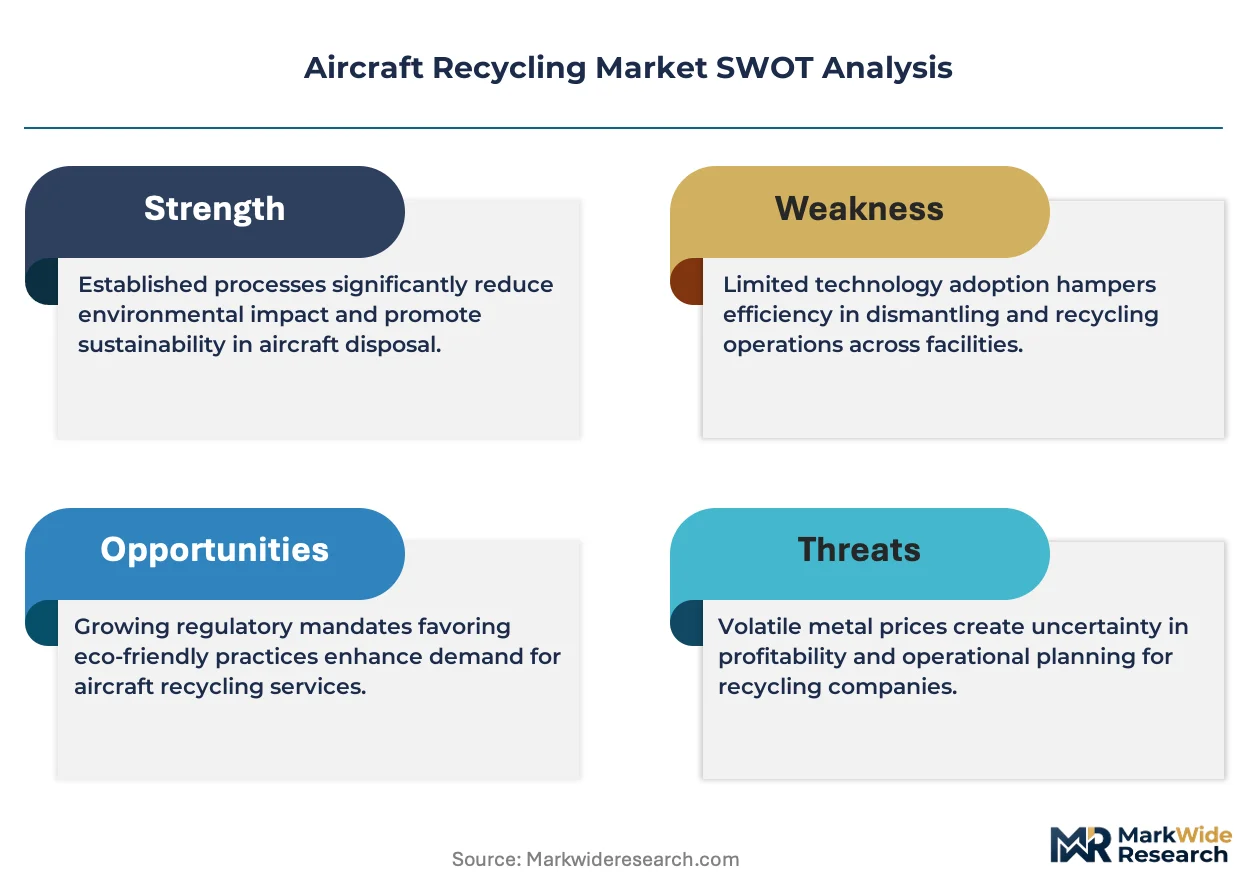
Backward integration into aluminum reprocessing and upstream control over certified waste handling infrastructure defines the competitive race in aircraft recycling, as facilities capture smelter premium pricing and absorb elevated EPA RCRA compliance costs.
For Market Incumbents: Anchor market position through M&A consolidation of regional yard networks in Arizona and California where smaller operators lack integrated environmental services capabilities. Invest in robotic water-jet cutting automation to compress narrow-body teardown timelines from twelve weeks to under seven, absorbing fixed costs across more airframes annually. Defend against disintermediation pressure from airline procurement unbundling by deepening OEM traceability documentation systems for reclaimed avionics and landing gear components. For New Entrants and Emerging Players: MRO procurement departments at Lufthansa Technik and expanding Indian operations at Hyderabad represent the most penetrable channel partner entry points for certified component reclamation with full traceability documentation. Target India's Bengaluru aerospace manufacturing corridor for localized dismantling partnerships feeding domestic forging supply chains. Pursue go-to-market positioning around blockchain-traceable parts tagging addressing insurer documentation requirements for circular economy participation. For Investors and Strategic Acquirers: The window for entry favors integrated dismantling specialists with EPA RCRA compliance and EU F-Gas Regulation adherence creating geographic moats. Long-term viability centers on facilities with certified hazardous-material handling capabilities and established robotic automation infrastructure. Watch for inflection signals in airline fleet renewal acceleration rates and next-generation composite-intensive aircraft penetration into retirement queues.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Reprocessing | Captures smelter premium pricing from aerospace-grade alloy streams in French and German forging supply chains. |
| Robotic Water-Jet Cutting Deployment | Compresses narrow-body teardown timelines at TARMAC Aerosave and Air Salvage International Ltd facilities. |
| Blockchain-Traceable Parts Tagging | Addresses EASA and FAA airworthiness documentation requirements for reclaimed landing gear and auxiliary power units. |
| Regional Yard Network Consolidation | Shares certified EPA RCRA waste handling infrastructure among Arizona and California dismantling operations. |
| EU F-Gas Regulation Compliance Investment | Creates compliance-driven service demand for fluorinated greenhouse gas recovery during aircraft teardown across member states. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this aircraft recycling market analysis. Primary interviews with aircraft dismantling facility managers, airline fleet planning directors, MRO procurement leads, and aerospace forging supply chain coordinators combined with EASA airworthiness directives, EPA RCRA enforcement records, EU F-Gas Regulation implementation guidance, and REACH chemical registration databases. Bottom-up facility capacity modeling and top-down fleet retirement projections triangulated volume estimates.
Granularity-level modeling operated at the intersection of material type, process type, and end-user segmentation across the projection horizon. Aluminum, titanium, steel, and composite material streams were modeled separately with distinct recovery economics. Dismantling, parts recovery, demilitarization, and waste management process types carried diverging margin profiles and compliance cost burdens. CAGRs derived from fleet renewal cycle compression rates and next-generation aircraft penetration into retirement queues, with aerospace-grade titanium recovery premiums and composite resin disposal cost escalations as industry-specific forecast inputs.
Caveats apply where regulatory enforcement intensity shifts or breakthrough composite processing technologies could materially shift the outlook. Forecasts reflect assumptions around documented chain-of-custody standardization and airworthiness certification timeline stability. Deviation in EU Green Deal circular economy mandate implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
Global Degaussing System Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Aerospace and Defense MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market