
 Aircraft Washing Systems Market | 2026-2036
Aircraft Washing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Washing Systems Market Outlook
North American manufacturing capacity for automated wash platforms is fragmenting as regional fabricators enter the supply chain. Kärcher leverages its pressure-system heritage to dominate European export channels for mobile wash units. Nordic Dino AB sustains engineering-intensive production of robotic wash frames purpose-built for narrow-body profiles. InterClean Equipment competes through water-recapture integration that appeals to airports facing discharge restrictions.
Aircraft washing systems encompass mobile and fixed infrastructure that applies pressurized water, chemical foaming agents, or filtered recycled fluids to exterior airframe surfaces at pressures typically ranging from 500 to 3,000 PSI to remove hydrocarbon deposits, insect accumulation, and atmospheric particulates that degrade aerodynamic efficiency. Automatic wash systems command the largest installed base among product types due to throughput advantages at high-frequency airline hubs, while waterless washing technology represents the fastest-expanding segment as drought-prone airports restrict potable water access for non-critical ground operations. Pressure washing retains structural dominance across technology categories though soft washing gains share for composite-intensive next-generation airframes requiring reduced mechanical stress.
The FAA enforces airworthiness directives linking surface contamination to corrosion susceptibility, compelling scheduled wash intervals for Part 121 carriers. EPA discharge standards for aircraft deicing and wash effluent push operators toward closed-loop reclamation systems that filter and reuse process water. EASA's continuing airworthiness regulation alignment with corrosion control programs reinforces comparable compliance burdens across European operators. Stakeholders must evaluate capital deployment timing between conventional water-based infrastructure and emerging waterless chemistries as regulatory water-use restrictions tighten at major hub airports.
Market Dynamics
Water scarcity mandates at major hub airports are forcing operators to choose between capital-intensive reclamation infrastructure and unproven waterless chemistries, reshaping procurement timelines and vendor selection criteria across the installed base.
Growth Catalysts
- FAA Corrosion Prevention Protocols:Mandatory scheduled wash intervals for Part 121 carriers sustain baseline demand for automated washing platforms at US airline maintenance facilities.
- Composite Airframe Proliferation:Boeing 787 and Airbus A350 fleets require soft-wash chemistries that reduce mechanical stress on carbon fiber surfaces, expanding addressable equipment specifications.
- California Water Restrictions:Drought-driven discharge limits at Los Angeles and San Francisco hubs accelerate closed-loop reclamation system deployment among ground handlers.
Market Restraints
- Stainless Steel Input Volatility:Pressure vessel and frame fabrication costs fluctuate with nickel alloy pricing, compressing margins for platform manufacturers.
- German Component Concentration:High-pressure pump assemblies rely on a narrow supplier base in Baden-Württemberg, creating single-source vulnerability.
- Waterless Chemistry Efficacy Gap:Current solvent formulations fail to match aqueous systems on insect protein removal, limiting adoption for tropical route operators.
Strategic Opportunities
- Indian MRO Expansion:Bangalore and Hyderabad maintenance clusters lack automated wash capacity, creating first-mover positioning for reclamation-integrated platform suppliers.
- EU Green Deal Alignment:CSRD reporting requirements pressure European flag carriers to document water-use reductions, favoring vendors with certified environmental product declarations.
- Drone-Assisted Pre-Wash Inspection:Convergence of UAV imaging and AI surface assessment enables targeted cleaning protocols that cut chemical consumption by application zone.
Industry Challenges
- Pressure System Certification Delays:ASME Boiler and Pressure Vessel Code compliance timelines for custom wash platform designs extend 14-18 months, slowing fleet rollout schedules.
- Legacy Hangar Retrofit Complexity:Existing maintenance bays require structural reinforcement and drainage reconfiguration to accommodate automated wash robotics, inflating project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Washing Systems Market |
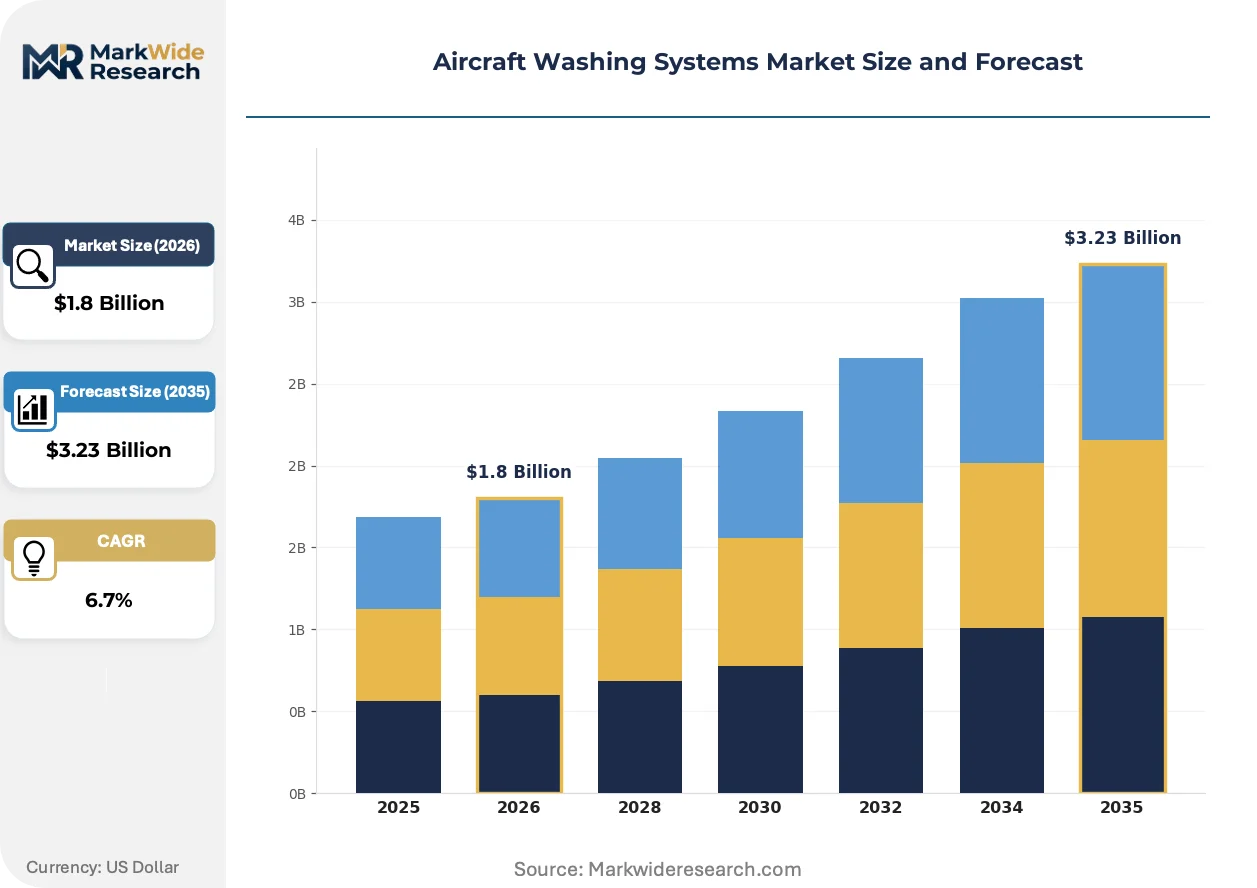
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Wash Systems, Manual Wash Systems, Foam Wash Systems, Eco-friendly Wash Solutions End User: Commercial Airlines, Private Operators, MRO Service Providers, Military Operators Technology: Pressure Washing, Soft Washing, Chemical Washing, Waterless Washing Service Type: On-site Cleaning, Off-site Cleaning, Maintenance Contracts, Consulting Services |
| Companies Covered | Nordic Dino AB, Kärcher, InterClean Equipment, Nordic Aerowash Equipment, Stoelting Cleaning Equipment, Cleaning Technologies Inc., Riveer, JRI Industries, Jensen Fabricating Engineers Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Washing Systems Market Strategic Shifts
Equipment architecture is converging around modular designs that permit rapid reconfiguration between narrow-body and wide-body profiles without full line shutdowns.
Electrostatic foaming application technology is hybridizing aqueous and chemical delivery into single-pass operations. Lufthansa Technik and Air France Industries are retrofitting existing wash lines with these systems to cut cycle times at high-throughput hubs. The technology is hybridizing competitive positioning between fixed automated platforms and mobile units by enabling portable electrostatic rigs that match stationary system efficiency.
EPA effluent guidelines for aircraft wash operations are tightening allowable hydrocarbon discharge limits from 15 ppm to 5 ppm at federally permitted facilities. This forces operators to upgrade filtration stages or face consent decree exposure. Wash reclaim system vendors serving Atlanta and Dallas-Fort Worth hubs report 40% quote volume increases as compliance deadlines approach.
Airline procurement teams are unbundling wash service contracts from integrated ground handling agreements, creating direct vendor relationships previously intermediated by multinational handlers. This channel shift concentrates buying power with technical specification teams at American, Delta, and United headquarters. The pattern is most pronounced in US legacy carrier networks where cost transparency mandates now require line-item service separation.
Aircraft Washing Systems Market Segmentation
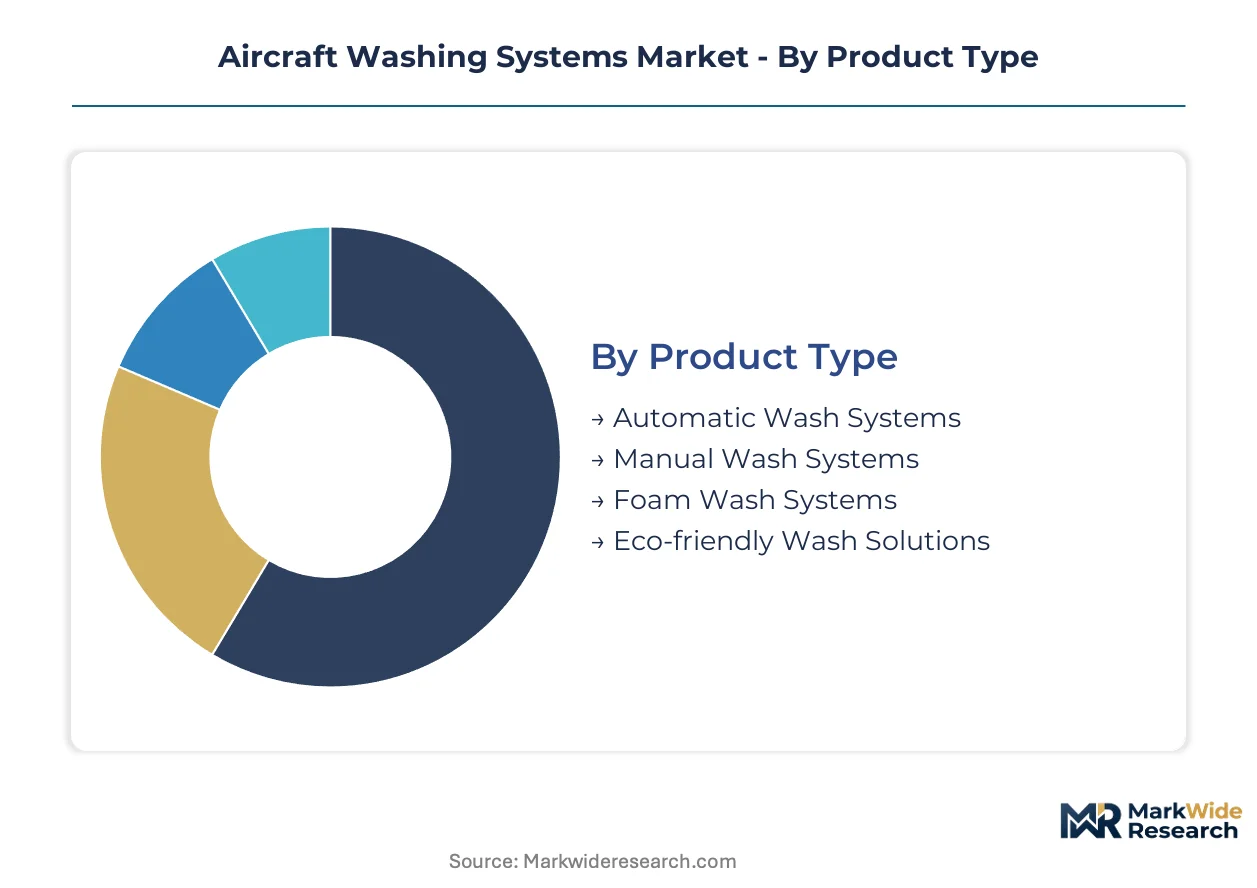
Equipment configuration and service delivery models in aircraft washing systems diverge sharply across operator scale, regulatory exposure, and fleet composition. Procurement patterns cluster around throughput requirements at major hubs versus flexibility needs at secondary airports and military installations.
Product Type:
Cost tier separates capital-intensive fixed infrastructure from deployable units suited to variable demand patterns.
- Automatic Wash Systems:Robotic gantry platforms integrate high-pressure manifolds, chemical dosing modules, and water reclamation circuits in permanent hangar installations. Demand concentrates at Atlanta, Dallas-Fort Worth, and Chicago O'Hare where American, Delta, and United operate scheduled wash programs under FAA corrosion prevention mandates.
- Manual Wash Systems:Mobile pressure rigs and scaffolding assemblies permit operator-directed cleaning of control surfaces, landing gear bays, and empennage sections inaccessible to automated coverage. Private operators and regional carriers at secondary airports favor these units for acquisition cost flexibility.
- Foam Wash Systems:Low-pressure chemical application rigs reduce water consumption through cling-time extension of surfactant formulations.
- Eco-friendly Wash Solutions:Biodegradable surfactant packages and closed-loop filtration skids address EPA discharge limits at California and Texas hubs.
Automatic Wash Systems holds installed capacity. Eco-friendly Wash Solutions is rotating up the share rankings.
End User:
Application context drives specification divergence between scheduled fleet maintenance and ad-hoc cleaning requirements.
- Commercial Airlines:Part 121 carriers operate the largest installed base of automated wash platforms, integrating cleaning cycles into overnight maintenance windows at hub facilities. Lufthansa Technik and Air France Industries specify electrostatic foaming retrofits to compress turnaround times.
- MRO Service Providers:Third-party maintenance clusters in Bangalore and Hyderabad lack automated wash capacity, creating first-mover positioning for reclamation-integrated platform suppliers serving Indian airline outsourcing contracts.
- Private Operators:Fractional ownership fleets and business aviation terminals favor mobile units for hangar-sharing flexibility.
- Military Operators:Defense airfields require contamination protocols for chemical, biological, and radiological threat mitigation beyond commercial specifications.
Commercial Airlines dominates procurement volume. MRO Service Providers is climbing the fastest as outsourcing expands.
Technology:
Volume throughput and airframe material compatibility determine technology selection across operator portfolios.
- Pressure Washing:High-velocity water jets at 500-3,000 PSI remain the dominant installed technology for hydrocarbon deposit and insect protein removal on aluminum-skinned legacy fleets. German pump assemblies from Baden-Württemberg suppliers concentrate critical component supply.
- Waterless Washing:Solvent-based chemistries and microfiber application systems expand most quickly at drought-prone airports facing potable water restrictions, though efficacy gaps persist on tropical route insect accumulation.
- Soft Washing:Reduced-pressure aqueous systems protect carbon fiber surfaces on Boeing 787 and Airbus A350 composite airframes from mechanical stress damage.
- Chemical Washing:Acidic and alkaline formulations target specific contaminant types including runway rubber deposits and exhaust soot streaking.
Pressure Washing retains structural dominance. Waterless Washing is gaining share fastest on water scarcity mandates.
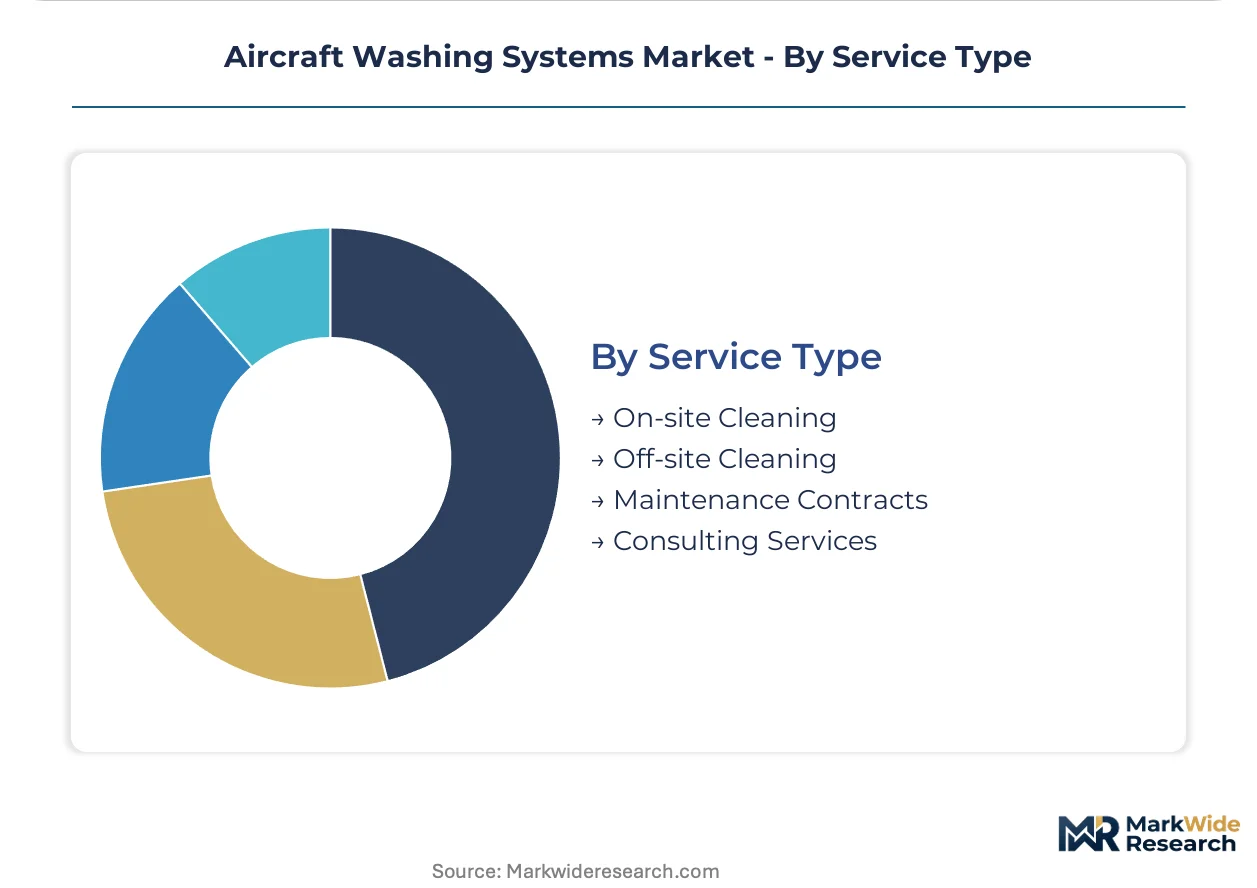
Service Type:
Customer type and contract structure reshape vendor relationships across direct procurement and outsourced arrangements.
- Maintenance Contracts:Long-term service agreements bundle scheduled wash intervals with corrosion inspection documentation, aligning with FAA airworthiness directive compliance requirements. US legacy carriers are unbundling these contracts from integrated ground handling agreements to concentrate technical specification authority at headquarters procurement teams.
- On-site Cleaning:Deployable crews with mobile equipment serve operators lacking permanent wash infrastructure, particularly at seasonal tourist destinations and remote military forward operating locations.
- Off-site Cleaning:Ferry flights to dedicated wash facilities accommodate operators at airports with discharge restrictions or inadequate drainage infrastructure.
- Consulting Services:Water-use audits and reclamation system design support compliance with tightening EPA effluent guidelines.
Maintenance Contracts anchors recurring revenue. On-site Cleaning is rotating up the share rankings on fleet dispersion patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global aircraft washing systems market traces its commercial backbone to hub airport infrastructure density. Dallas-Fort Worth International's centralized maintenance campus underwrites North American demand concentration. Frankfurt Airport's integrated MRO zone anchors European procurement patterns.
United States
American, Delta, and United operate scheduled wash programs at Atlanta, Chicago O'Hare, and Dallas-Fort Worth under FAA corrosion prevention mandates. EPA discharge standards tightening to 5 ppm hydrocarbon limits force reclamation system upgrades at federally permitted facilities. Los Angeles and San Francisco hubs accelerate closed-loop deployment as California drought restrictions intensify water-use scrutiny.
Germany
Lufthansa Technik specifies electrostatic foaming retrofits to compress turnaround times at Frankfurt and Munich maintenance centers. EASA continuing airworthiness regulation alignment with corrosion control programs reinforces compliance burdens across European operators. Baden-Württemberg hosts concentrated high-pressure pump assembly fabrication, creating single-source vulnerability for critical components.
India
Bangalore and Hyderabad maintenance clusters lack automated wash capacity, creating first-mover positioning for reclamation-integrated platform suppliers serving airline outsourcing contracts. DGFT import procedures for pressure vessel equipment extend procurement timelines for foreign vendors. The country's national aviation regulator mandates corrosion control documentation for Part 145 maintenance organizations.
France
Air France Industries retrofits existing wash lines with hybrid aqueous-chemical delivery systems at Paris-Charles de Gaulle. EU Green Deal CSRD reporting requirements pressure flag carriers to document water-use reductions, favoring vendors with certified environmental product declarations. The Occitanie region hosts emerging MRO capacity serving Mediterranean route operators.
United Arab Emirates
Dubai International's 24-hour hub operations demand high-throughput automated platforms for Emirates' wide-body fleet. MOHAP environmental standards for industrial discharge shape procurement specifications for ground handlers. Abu Dhabi's Etihad Engineering cluster invests in soft-wash infrastructure for composite-intensive next-generation airframes.
Aircraft Washing Systems Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in pressure vessel and pump assembly fabrication. The vendor base organizes around three functional layers: full-system integrators delivering turnkey gantry installations, regional fabricators supplying mobile pressure rigs, and component OEMs controlling critical high-pressure technology. Consolidation pressure concentrates at the system tier where project scale demands turnkey accountability. Strategic moves center on water-recapture technology licensing and backward integration into filtration component manufacturing.
Among European heritage manufacturers, Kärcher leverages pressure-system expertise across mobile wash unit export channels. Nordic Dino AB occupies a position within the engineering-intensive robotic wash frame segment purpose-built for narrow-body profiles. InterClean Equipment exemplifies the reclamation-integrated platform archetype, appealing to airports facing discharge restrictions. These three anchors represent divergent competitive vectors: heritage pressure technology, airframe-specific robotics, and environmental compliance integration.
| Leading Market Players |
|---|
| Nordic Dino AB |
| Kärcher |
| InterClean Equipment |
| Nordic Aerowash Equipment |
| Stoelting Cleaning Equipment |
| Cleaning Technologies Inc. |
| Riveer |
| JRI Industries |
| Jensen Fabricating Engineers Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in North American gantry fabrication is compressing project margins and forcing tier-two suppliers toward aggressive quoting on reclamation-integrated platforms. This utilization imbalance grants procurement teams at major US carriers substantial leverage in multi-year maintenance contract negotiations.
Pricing Analysis
Volume-discount tiering structures separate enterprise fleet contracts from single-unit mobile rig sales. Pricing stratifies across premium certification-grade systems, standard ASME-compliant platforms, and economy-tier manual assemblies. Cost compression in the economy tier is intensifying because regional fabricators in Texas and Ohio are absorbing stainless steel volatility to defend backlog positions. MRO service providers exhibit the highest price sensitivity due to thin outsourcing margins, while Emirates and Lufthansa Technik prioritize throughput over unit cost.
Supply Chain Analysis
Upstream feedstock for pressure vessel fabrication draws from German pump assembly clusters in Baden-Württemberg, Chinese stainless steel coil suppliers, and domestic North American frame fabricators. Critical component dependencies include nickel-alloy pressure vessels, ceramic-plunger pump assemblies, and membrane filtration skids. Single-source vulnerability in German high-pressure technology creates procurement risk for platform integrators lacking dual-qualified suppliers. Distribution runs through direct OEM sales to airline procurement teams and regional distributor networks serving secondary airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as American, Delta, and United unbundle wash contracts from ground handling agreements, shifting specification authority to centralized technical teams and fragmenting incumbent vendor relationships.
For Market Incumbents: Build regulatory compliance moats through ASME certification acceleration and EPA discharge documentation services. Incumbent platform integrators should secure dual sourcing for Baden-Württemberg pump assemblies to mitigate single-source exposure. Backward integration into membrane filtration manufacturing captures margin from reclamation system upgrades driven by California water restrictions. For New Entrants and Emerging Players: Establish a beachhead in Bangalore and Hyderabad MRO clusters where automated wash capacity is underdeveloped and Indian airline outsourcing contracts are expanding. New entrants should target waterless chemistry validation partnerships with drought-prone California hubs as a go-to-market angle, leveraging efficacy gaps in tropical route insect removal as a near-term limitation to acknowledge. For Investors and Strategic Acquirers: Capital is best deployed toward reclamation-integrated platform specialists with certified environmental product declarations aligned to EU Green Deal CSRD reporting requirements. Acquisition targets should demonstrate installed base expansion potential at federally permitted facilities facing EPA discharge deadline pressure. The signal to watch is quote volume acceleration at Atlanta and Dallas-Fort Worth hubs as compliance deadlines approach.| Strategic Initiative | Industry Significance |
|---|---|
| Water Recapture Technology Licensing | EPA discharge limits at California hubs force reclamation system upgrades across installed base. |
| Electrostatic Foaming Retrofit Programs | Lufthansa Technik and Air France Industries deploy hybrid systems to compress turnaround times. |
| Modular Platform Architecture Development | Rapid reconfiguration between narrow-body and wide-body profiles reduces line shutdown frequency. |
| Drone-Assisted Pre-Wash Inspection Integration | UAV imaging with AI surface assessment enables targeted cleaning protocols cutting chemical consumption. |
| Baden-Württemberg Supplier Diversification | Dual qualification for high-pressure pump assemblies mitigates concentration risk in German component base. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directives, EPA effluent guideline dockets, and EASA continuing airworthiness regulations. Primary interviews incorporated fleet maintenance directors at Part 121 carriers, procurement leads at major ground handlers, technical specification engineers at MRO clusters, and reclamation system vendors serving federally permitted facilities. Secondary sources included ASME Boiler and Pressure Vessel Code documentation, state-level water restriction filings, and customs records for pressure vessel equipment imports. Bottom-up equipment shipment tracking and top-down fleet maintenance spend analysis provided cross-validation.
Forecast inputs considered airframe delivery schedules across Boeing 787 and Airbus A350 composite fleets, regulatory compliance deadline clustering at major hub airports, and water scarcity mandate expansion patterns. Segmentation modeling spanned product configuration, end-user archetype, technology category, and service delivery structure across the projection horizon. CAGRs were derived from installed base replacement cycles and new capacity deployment at emerging MRO clusters. Industry-specific inputs included FAA corrosion prevention protocol enforcement intensity and EPA hydrocarbon discharge limit phase-in schedules.
Macroeconomic conditions sit as an overlay; deviation in nickel alloy pricing, airline capital expenditure cycles, or drought severity patterns would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology efficacy convergence timelines. Cross-checking against airline fleet modernization announcements and state-level water restriction legislative calendars is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Aerospace and Defense MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Exterior Strip and Repaint Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market